
 Isocitrate Dehydrogenase (IDH) Inhibitors Market | 2026-2036
Isocitrate Dehydrogenase (IDH) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Isocitrate Dehydrogenase (IDH) Inhibitors Market Foresight
Small molecule chemistry is shifting toward mutant-selective binding profiles that improve therapeutic indices over earlier pan-inhibitor platforms. Agios Pharmaceuticals leverages deep enzymology expertise to sustain leadership in targeted metabolism oncology. Bayer anchors European development capacity through integrated discovery networks. Daiichi Sankyo differentiates its pipeline with differentiated brain-penetrant formulations for glioma indications.
Isocitrate dehydrogenase inhibitors are small molecule or biologic agents that block mutated IDH1 or IDH2 enzymes, thereby preventing the accumulation of the oncometabolite D-2-hydroxyglutarate and restoring normal cellular differentiation programs. These therapeutics primarily serve oncology applications where IDH mutations drive leukemogenesis or solid tumor progression. Small molecule inhibitors dominate current revenue pools due to established oral bioavailability and manufacturing scalability, while combination therapies represent the fastest-expanding segment as clinicians seek to overcome resistance mechanisms. Monoclonal antibodies occupy a narrower but higher-margin niche in settings requiring prolonged target engagement.
The FDA maintains stringent chemistry, manufacturing, and controls standards for targeted oncology agents, while the EMA's centralized procedure governs European market authorization for hematology therapeutics. REACH compliance shapes raw material sourcing for active pharmaceutical ingredient synthesis, particularly for fluorinated intermediates. Stakeholders must monitor evolving biomarker-defined patient segmentation and corresponding payer evidence requirements to secure favorable reimbursement positioning.
Market Dynamics
Mutant-selective binding chemistry is compressing development timelines as developers engineer inhibitors with narrower target profiles, forcing pan-inhibitor platforms toward obsolescence in competitive protocols.
Growth Catalysts
- Biomarker-Driven Segmentation:Companion diagnostic integration into FDA's oncology drug approval pathway accelerates patient identification and therapeutic matching in hematology clinics.
- REACH Compliance Infrastructure:ECHA's centralized chemical safety framework streamlines fluorinated intermediate sourcing for active pharmaceutical ingredient synthesis across European manufacturing networks.
- Combination Therapy Expansion:Clinicians in academic medical centers are layering IDH inhibitors with hypomethylating agents to overcome acquired resistance mechanisms in acute myeloid leukemia protocols.
Market Restraints
- Fluorinated Intermediate Concentration:Active pharmaceutical ingredient synthesis depends on specialized fluorination capacity concentrated in Chinese and Indian contract manufacturing organizations.
- Reimbursement Evidence Thresholds:Payer organizations demand progression-free survival data exceeding twelve months before granting favorable formulary positioning for novel inhibitors.
- Brain Penetration Limitations:First-generation small molecules face blood-brain barrier exclusion that restricts addressable glioma patient populations.
Strategic Opportunities
- Central Nervous System Formulations:Developers engineering enhanced brain-penetrant chemistries can access glioblastoma multiforme indications where current standards fail.
- Myelodysplastic Syndrome Expansion:EMA's centralized procedure for hematology therapeutics creates a streamlined path into secondary malignancy applications beyond acute leukemia.
- Real-World Evidence Networks:Flatiron Health and similar oncology data platforms enable post-approval efficacy tracking that satisfies Medicare's evidence development requirements.
Industry Challenges
- Enzymology Talent Scarcity:Deep expertise in cancer metabolism biochemistry remains concentrated among a handful of academic laboratories and specialized biotechnology firms.
- Manufacturing Scale-Up Complexity:Chiral synthesis requirements for mutant-selective inhibitors demand specialized continuous flow chemistry infrastructure that few contract manufacturers possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isocitrate Dehydrogenase (IDH) Inhibitors Market |
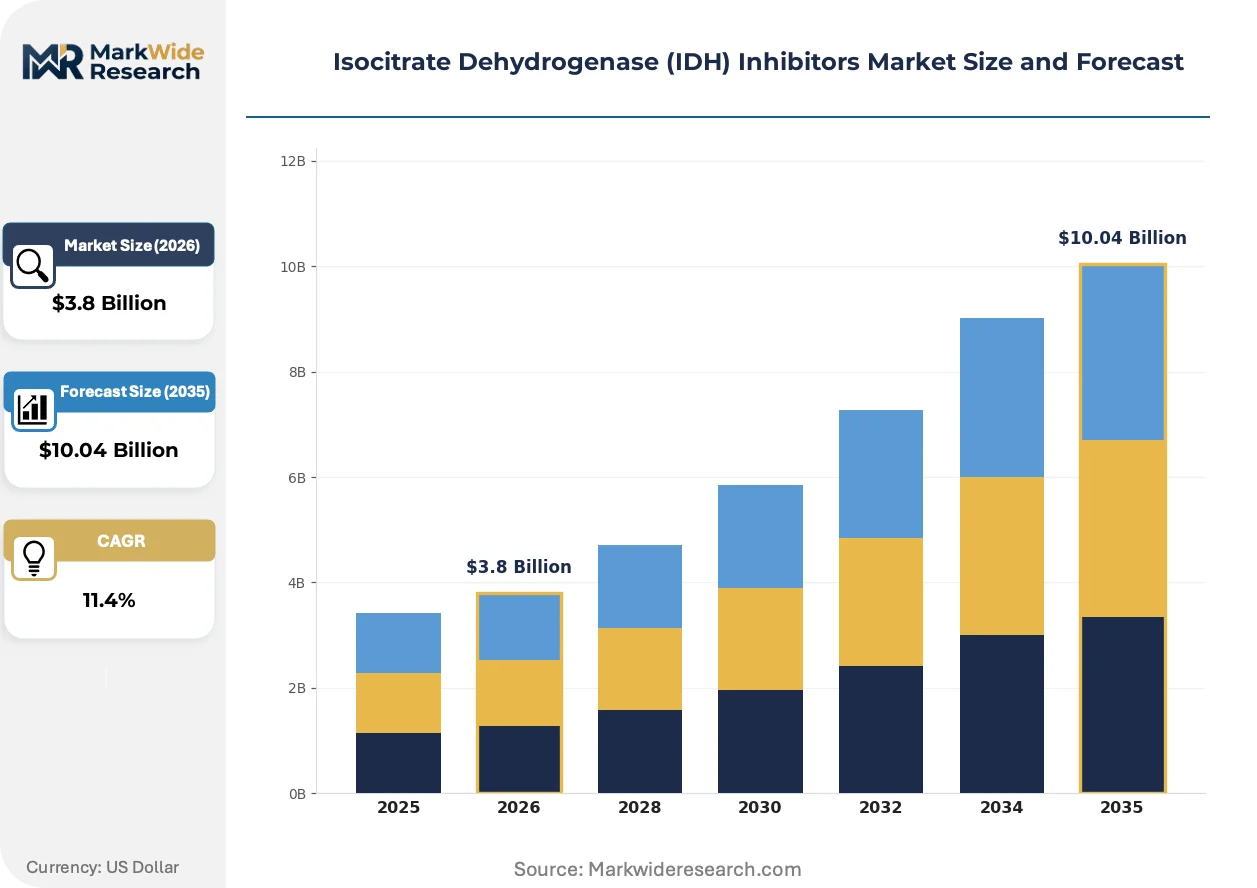
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule Inhibitors, Monoclonal Antibodies, Combination Therapies, Novel Compounds Application: Oncology, Hematology, Neurology, Rare Diseases End User: Pharmaceutical Companies, Research Institutions, Hospitals, Contract Research Organizations Distribution Channel: Direct Sales, Online Sales, Wholesalers, Specialty Pharmacies |
| Companies Covered | Agios Pharmaceuticals, Bayer, Daiichi Sankyo, Pfizer, Celgene, Servier, Sun Pharmaceutical Industries, Philogen, Aslan Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isocitrate Dehydrogenase (IDH) Inhibitors Market Shifts & Advancements
Allosteric inhibitor design is displacing orthosteric approaches across the development pipeline, compressing off-target liabilities while expanding addressable mutation spectra.
Next-generation allosteric binding platforms is rewriting therapeutic index calculations by achieving complete mutant enzyme inhibition at plasma concentrations below those triggering wild-type suppression. Hematology clinics at Memorial Sloan Kettering and MD Anderson are adopting these candidates in first-line protocols ahead of regulatory conversion. The technology is rewriting competitive positioning by rewarding developers with structural biology capabilities over traditional medicinal chemistry shops.
EMA's centralized procedure for orphan oncology drugs is compressing market access timelines for hematology indications across EU member states. The regulation eliminates national divergence in approval standards that previously fragmented commercialization strategy. Developers targeting acute myeloid leukemia are restructuring European clinical trial designs to capture this procedural efficiency.
Academic medical centers are consolidating procurement authority for targeted oncology agents into centralized pharmacy and therapeutics committees. Community oncology practices and smaller hospital systems are losing direct purchasing autonomy as formularies narrow to evidence-backed protocols. The concentration is most visible in United States markets where Medicare's oncology care model accelerates site-of-care consolidation.
Isocitrate Dehydrogenase (IDH) Inhibitors Market Segmentation
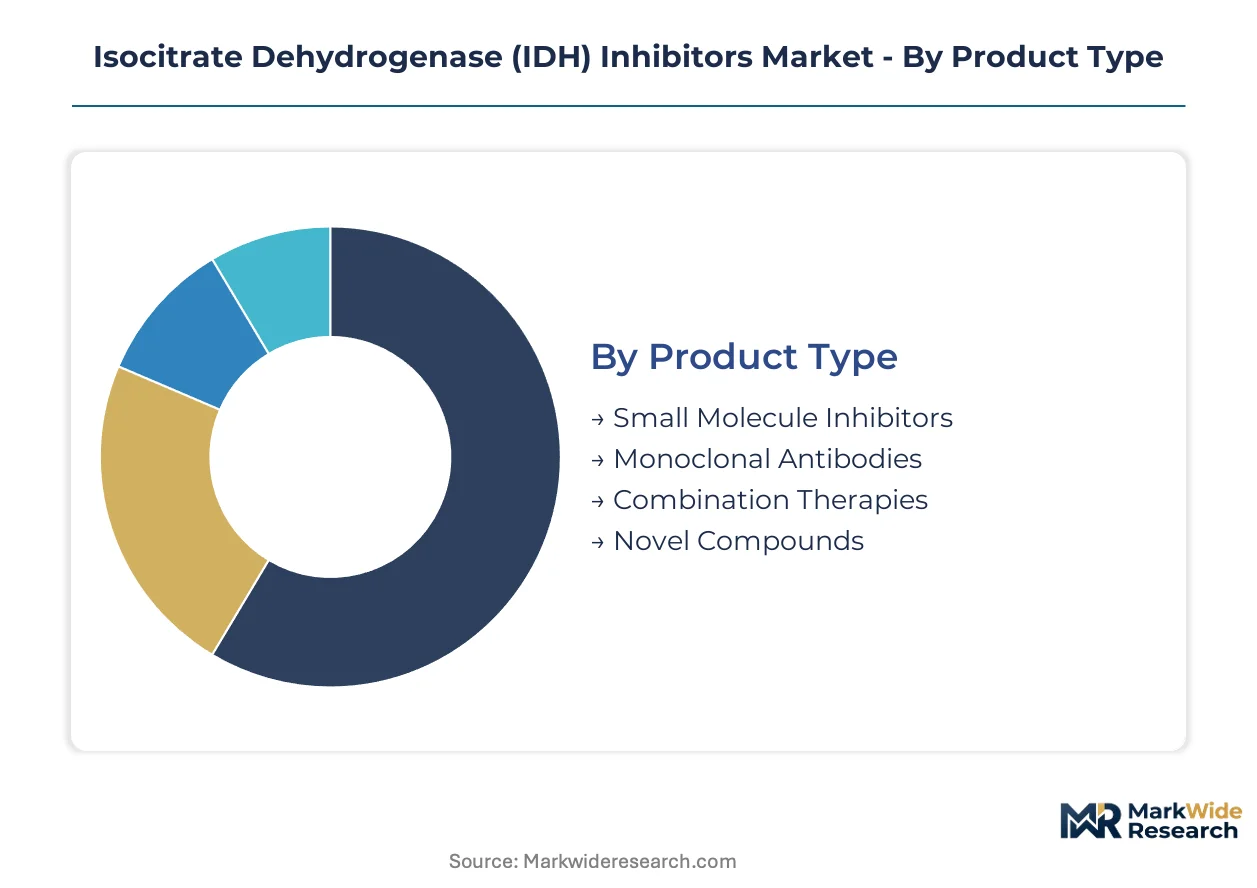
IDH inhibitor segmentation reveals how therapeutic delivery modes, clinical settings, and procurement pathways fragment commercial opportunity. Developers must align formulation strategies with the distinct technical and regulatory requirements of each segment to capture value across the treatment continuum.
Product Type:
Small molecule platforms dominate standalone therapeutic use, while monoclonal antibodies and combination regimens embed into broader oncology protocols with distinct integration requirements.
- Small Molecule Inhibitors:Oral bioavailability and established manufacturing scalability position these agents as first-line standards in acute myeloid leukemia. Memorial Sloan Kettering and MD Anderson prioritize mutant-selective small molecules for frontline protocols. Volume placements concentrate in hematology clinics with companion diagnostic infrastructure.
- Combination Therapies:Layering IDH inhibitors with hypomethylating agents addresses acquired resistance mechanisms in relapsed settings. Academic medical centers drive adoption as clinicians seek durable remissions beyond monotherapy limits. The faster expansion belongs to this segment as resistance patterns emerge in treated populations.
- Monoclonal Antibodies:Prolonged target engagement suits settings requiring sustained enzymatic suppression.
- Novel Compounds:Brain-penetrant formulations target glioblastoma multiforme indications.
Small molecules anchor current revenue pools; combination protocols are climbing the fastest as resistance management becomes standard of care.
Application:
Oncology and hematology segments absorb the bulk of clinical investment, while neurology and rare disease applications remain underdeveloped due to formulation and trial design barriers.
- Oncology:Solid tumor applications beyond glioma remain exploratory as mutant-selective binding profiles prove efficacy in defined genetic subsets.
- Hematology:Acute myeloid leukemia protocols at major academic centers generate the deepest clinical experience and regulatory precedent. FDA's oncology drug approval pathway accelerates biomarker-driven patient matching here. Volume placements concentrate in hematology.
- Neurology:Blood-brain barrier penetration limits addressable glioma populations for first-generation agents.
- Rare Diseases:Cholangiocarcinoma and other IDH-mutant rare malignancies offer orphan drug incentives.
Hematology commands the deepest clinical infrastructure; neurology represents the steepest expansion trajectory pending brain-penetrant formulation advances.
End User:
Procurement authority concentrates in institutional buyers with integrated pharmacy and therapeutics committees, fragmenting access for smaller independent operators.
- Pharmaceutical Companies:In-house development programs and partnered asset acquisitions drive preclinical and early clinical investment.
- Research Institutions:Academic laboratories with deep cancer metabolism enzymology expertise supply foundational intellectual property.
- Hospitals:Centralized pharmacy and therapeutics committees at academic medical centers control formulary placement and purchasing volume. Medicare's oncology care model accelerates this consolidation. Volume placements concentrate in hospital systems.
- Contract Research Organizations:Specialized hematology trial execution supports FDA and EMA submission packages.
Hospital procurement consolidation reshapes access patterns; research institutions are gaining share fastest as enzymology talent scarcity intensifies.
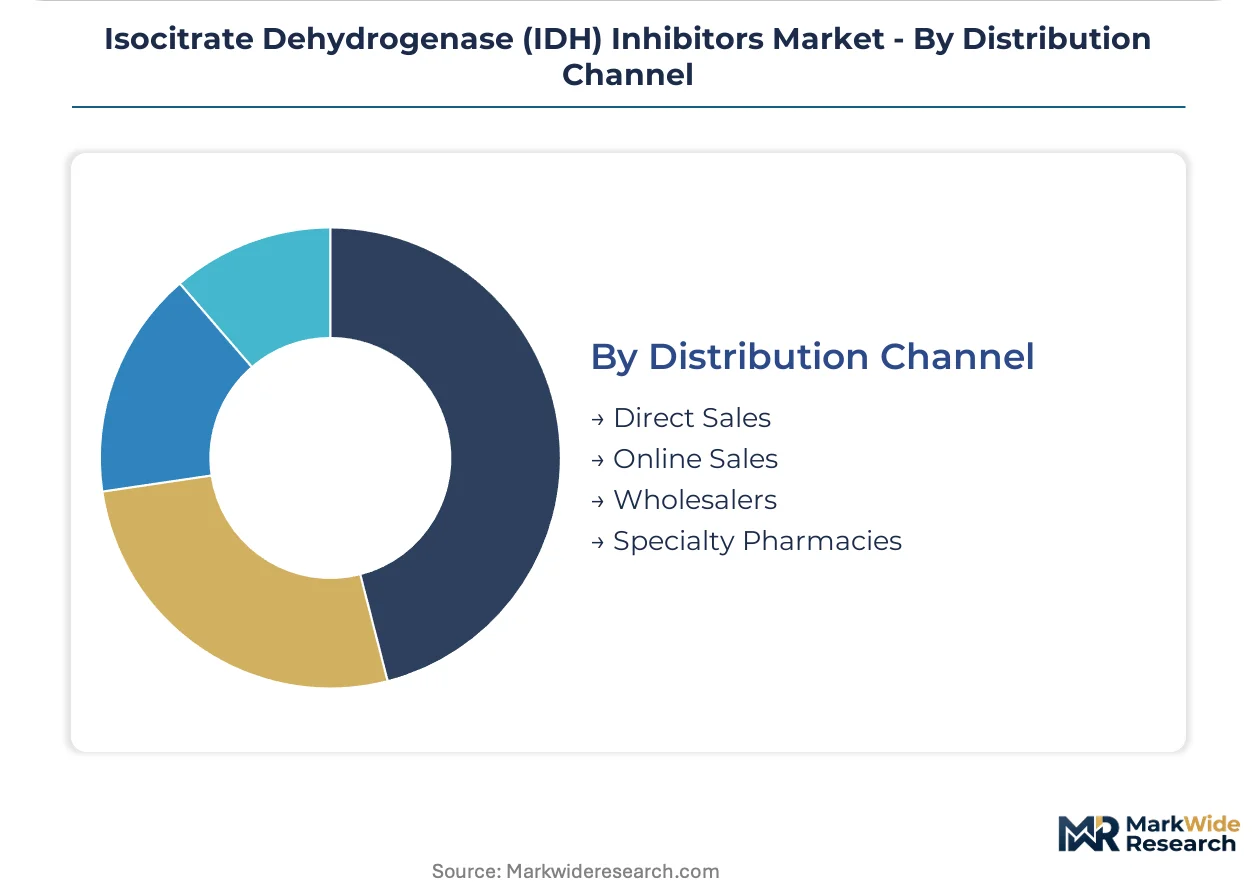
Distribution Channel:
Specialized handling requirements and patient access programs favor controlled distribution models over commodity wholesale.
- Direct Sales:Manufacturer field forces engage consolidated hospital pharmacy committees with clinical and economic evidence packages.
- Specialty Pharmacies:Patient support services and adherence monitoring address oral oncology agent compliance challenges. Hub services manage prior authorization and reimbursement navigation. Volume placements concentrate in specialty pharmacies.
- Wholesalers:Limited role given cold chain and controlled substance considerations for investigational agents.
- Online Sales:Emerging for expanded access programs and compassionate use settings.
Specialty pharmacies anchor commercial distribution; direct sales channels are expanding most quickly as site-of-care consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where academic medical centers at Memorial Sloan Kettering and MD Anderson drive early therapeutic integration. Germany and Japan anchor European and Asian development capacity through integrated discovery networks. China and India expand manufacturing infrastructure for active pharmaceutical ingredient synthesis.
United States
Academic medical centers and hematology clinics generate the deepest clinical experience with IDH inhibitor protocols. FDA's oncology drug approval pathway accelerates biomarker-driven patient matching and regulatory conversion. The Boston-Cambridge corridor and Houston's Texas Medical Center concentrate enzymology talent and early-phase trial execution.
Germany
Integrated pharmaceutical manufacturing networks support European supply security for fluorinated intermediates. EMA's centralized procedure streamlines market authorization across EU member states. The Rhine-Main and Bavarian clusters host specialized contract manufacturing organizations with chiral synthesis capabilities.
Japan
PMDA's expedited review pathways for orphan oncology drugs compress development timelines for hematology indications. Pharmaceutical companies leverage deep medicinal chemistry expertise to advance mutant-selective binding platforms. The Kanto region around Tokyo anchors clinical trial infrastructure and regulatory submission capacity.
China
Contract manufacturing organizations concentrate fluorination capacity for active pharmaceutical ingredient synthesis. NMPA's reform of oncology drug approval procedures aligns with international standards. The Yangtze River Delta and Pearl River Delta clusters expand specialized chemical production for export markets.
India
Pharmaceutical manufacturers develop cost-efficient synthesis routes for generic and novel inhibitor candidates. CDSCO's streamlined approval pathways for oncology therapeutics accelerate market entry. The Mumbai-Pune corridor and Hyderabad host contract research organizations supporting global clinical trial execution.
Isocitrate Dehydrogenase (IDH) Inhibitors Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek to combine enzymology expertise with commercial infrastructure. The vendor base organizes around three tiers: established oncology pharmaceutical companies with integrated metabolism platforms, mid-cap biotechnology firms with specialized structural biology capabilities, and emerging regional players with manufacturing scale advantages. Two competitive moves define positioning: portfolio diversification into combination therapy regimens, and geographic expansion through licensing arrangements that access EMA and FDA approval pathways.
Within the established pharmaceutical tier, Agios Pharmaceuticals and Bayer occupy positions anchored by deep cancer metabolism expertise and integrated European development networks respectively. Daiichi Sankyo exemplifies the mid-cap biotechnology archetype through differentiated formulation capabilities. These three companies represent distinct strategic postures: enzymology-led discovery, continental manufacturing scale, and targeted indication expansion.
| Leading Market Players |
|---|
| Agios Pharmaceuticals |
| Bayer |
| Daiichi Sankyo |
| Pfizer |
| Celgene |
| Servier |
| Sun Pharmaceutical Industries |
| Philogen |
| Aslan Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Continuous flow chemistry adoption for chiral synthesis of mutant-selective inhibitors is compressing unit production costs while concentrating manufacturing capacity among specialized contract manufacturers in Germany and India. This technological shift simultaneously reduces per-batch variability and elevates entry barriers for developers lacking capital-intensive flow reactor infrastructure, reshaping how procurement committees at academic medical centers negotiate supply agreements.
Pricing Analysis
Volume placements in hematology clinics anchor the lower-margin tier, while brain-penetrant formulations for glioma indications capture premium positioning. Price differentiation hinges on mutant-selectivity certification and companion diagnostic bundling. Pricing pressure stems from payer demands for progression-free survival data exceeding twelve months. Community oncology practices exhibit highest price sensitivity; academic medical centers with centralized pharmacy committees demonstrate lowest sensitivity due to evidence-based procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with fluorinated intermediate production concentrated in Chinese and Indian contract manufacturing organizations. Active pharmaceutical ingredient synthesis draws from specialized fluorination capacity in the Yangtze River Delta and Hyderabad clusters. Raw material dependencies include fluorinated aromatics, chiral auxiliaries, and palladium catalysts. Tariff exposure on imported intermediates poses structural risk. Distribution runs through specialty pharmacy hubs with cold chain handling for oral oncology agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance infrastructure and FDA chemistry manufacturing controls erect formidable cost-of-compliance barriers that protect incumbent positions while filtering out undercapitalized entrants unable to sustain regulatory quality systems.
For Market Incumbents: To counter enzymology talent scarcity eroding R&D productivity, Agios Pharmaceuticals and Bayer should deepen captive supply of fluorinated intermediates through backward integration into German Rhineland manufacturing clusters. Simultaneously, incumbents must lock exclusive access to Memorial Sloan Kettering and MD Anderson clinical data networks to accelerate real-world evidence generation for Medicare reimbursement negotiations.
For New Entrants and Emerging Players: Digital therapeutics platforms offer a de-risked entry vector into IDH-mutant patient management software, bypassing capital-intensive small molecule manufacturing. White-space targets include myelodysplastic syndrome protocols underserved by current glioma-focused pipelines and community oncology practices excluded from academic medical center formularies. A direct-to-clinician telemedicine model can circumvent consolidated hospital procurement committees.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap biotechnology firms possessing structural biology capabilities and brain-penetrant formulation expertise given EMA's centralized procedure compressing European market access timelines. Long-term viability frames around five-to-ten year windows for combination therapy regimens displacing monotherapy standards. Acquisition targets should demonstrate mutant-selective binding platforms with complete enzyme inhibition at sub-wild-type suppression concentrations. The signal to watch is FDA breakthrough therapy designation velocity for central nervous system indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Memorial Sloan Kettering's first-line protocol adoption accelerates regulatory conversion timelines for mutant-selective candidates. |
| Regulatory Approval Pathway | EMA's centralized procedure for orphan oncology drugs eliminates national divergence across EU member states. |
| Manufacturing Scale-Up | Continuous flow chemistry investment in Bavarian clusters secures chiral synthesis capacity for next-generation inhibitors. |
| Pipeline Diversification | Layering IDH inhibitors with hypomethylating agents addresses acquired resistance in relapsed acute myeloid leukemia. |
| Licensing Agreement | Flatiron Health data partnerships enable post-approval efficacy tracking satisfying Medicare evidence requirements. |
Research Methodology
Multi-period observation of FDA oncology drug approval velocity, EMA centralized procedure completion rates, and hematology clinic formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives at Agios Pharmaceuticals and Daiichi Sankyo, regulatory affairs leads navigating REACH compliance, formulary directors at academic medical centers, and payer access specialists at Medicare Advantage plans. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation cross-checked volume estimates.
Input-output matrices mapped mutant-selective inhibitor penetration across treatment lines, dosage forms, oral versus intravenous administration routes, and patient population segments defined by IDH1 versus IDH2 mutation status. CAGRs were derived from regression analysis of historical approval-to-adoption intervals and projected biomarker testing expansion. Forecast inputs incorporated companion diagnostic infrastructure buildout rates and hypomethylating agent combination protocol adoption curves across the analysis window.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world progression-free survival data from community oncology practices introduce uncertainty bands around reimbursement scenario outcomes. Forecasts reflect assumptions regarding biomarker-driven patient segmentation stability and fluorinated intermediate supply security. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Global Tick-Borne Encephalitis Inactivated Vaccine Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market