
 Global Oncology/Cancer Drugs Market | 2026-2036
Global Oncology/Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology/Cancer Drugs Market Foresight
Project finance structures and royalty-backed lending for late-stage clinical assets is reshaping which biopharma developers can sustain independent pipelines through commercialization. F. Hoffmann-La Roche Ltd leverages its diagnostic-drug pairing model to anchor premium positioning in companion-tested therapies. Merck & Co., Inc. dominates the PD-1 checkpoint inhibitor class through manufacturing scale and label expansion across tumor types. Bristol-Myers Squibb Company sustains competitive breadth with dual immunotherapy combinations and cell therapy manufacturing investments.
Oncology drugs comprise targeted therapeutic agents, cytotoxic compounds, and biologics engineered to interrupt malignant cell proliferation, with monoclonal antibodies requiring mammalian cell culture production in single-use bioreactors at titers exceeding five grams per liter. Their primary purpose is to extend progression-free survival and overall survival in patients with solid tumors and hematologic malignancies. Immunotherapy agents command the fastest expansion as checkpoint inhibitors and CAR-T cell therapies displace chemotherapy in earlier treatment lines across lung cancer and lymphoma. Monoclonal antibodies retain the largest revenue pool due to established biosimilar competition eroding originator pricing, while tyrosine kinase inhibitors concentrate margin in resistant-mutation subpopulations with smaller addressable populations.
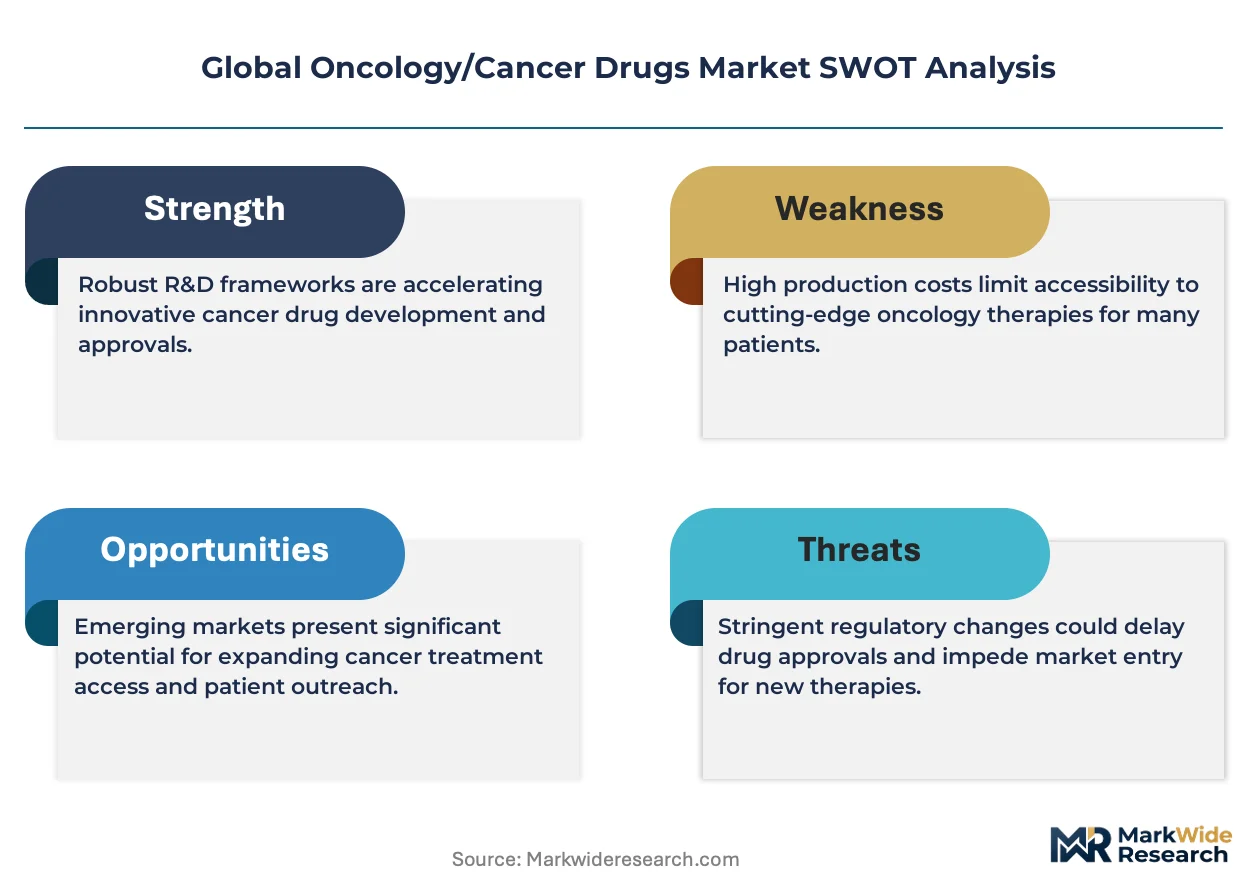
The FDA's accelerated approval framework and the EMA's conditional marketing authorization pathway create parallel but divergent evidentiary standards that shape trial design and launch sequencing. REACH and the EU MDR impose escalating purity and traceability requirements on biologic manufacturing supply chains, favoring producers with captive fill-finish capacity. China's NMPA reform of oncology drug review timelines has compressed local approval gaps versus Western markets. Stakeholders must monitor how real-world evidence mandates from multiple regulators redefine post-market commitment burdens and pricing negotiation leverage.
Market Dynamics
The FDA's accelerated approval pathway compresses clinical development timelines from years to months, forcing competitors to match speed-to-market or cede first-mover advantage in breakthrough therapy designations.
Growth Catalysts
- Biomarker-driven patient stratification:Companion diagnostics now mandate parallel development with oncology drugs, expanding addressable populations through precision targeting.
- China's NMPA oncology review reforms:Compressed approval timelines have eliminated historical lag versus Western markets, accelerating multinational launch sequencing.
- Hospital infusion capacity expansion:US-based health systems are adding dedicated oncology suites to accommodate rising patient volumes for intravenous biologics.
Market Restraints
- Single-source mammalian cell culture supply:Bioreactor capacity concentrates among contract manufacturers in Switzerland and Singapore, creating bottleneck risk for monoclonal antibody production.
- REACH biologic traceability mandates:EU regulatory escalation imposes purity documentation burdens that favor producers with captive fill-finish facilities.
- CAR-T autologous manufacturing complexity:Patient-specific cell processing requires distributed production networks that resist scale economies.
Strategic Opportunities
- Subcutaneous formulation conversion:IV-to-SC delivery shifts for checkpoint inhibitors open home administration channels and reduce hospital dependency.
- India's CDSCO fast-track oncology pathway:Localized clinical trial requirements and abbreviated review create earlier access for biosimilar entrants.
- Real-world evidence post-market commitments:FDA mandates for confirmatory trials create data infrastructure partnerships between developers and specialty pharmacy networks.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:GMP-compliant cleanroom operators and vector production specialists command premium compensation in Boston and Basel clusters.
- Legacy EHR integration with precision dosing platforms:Hospital IT systems require costly customization to support biomarker-result-driven treatment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology/Cancer Drugs Market |
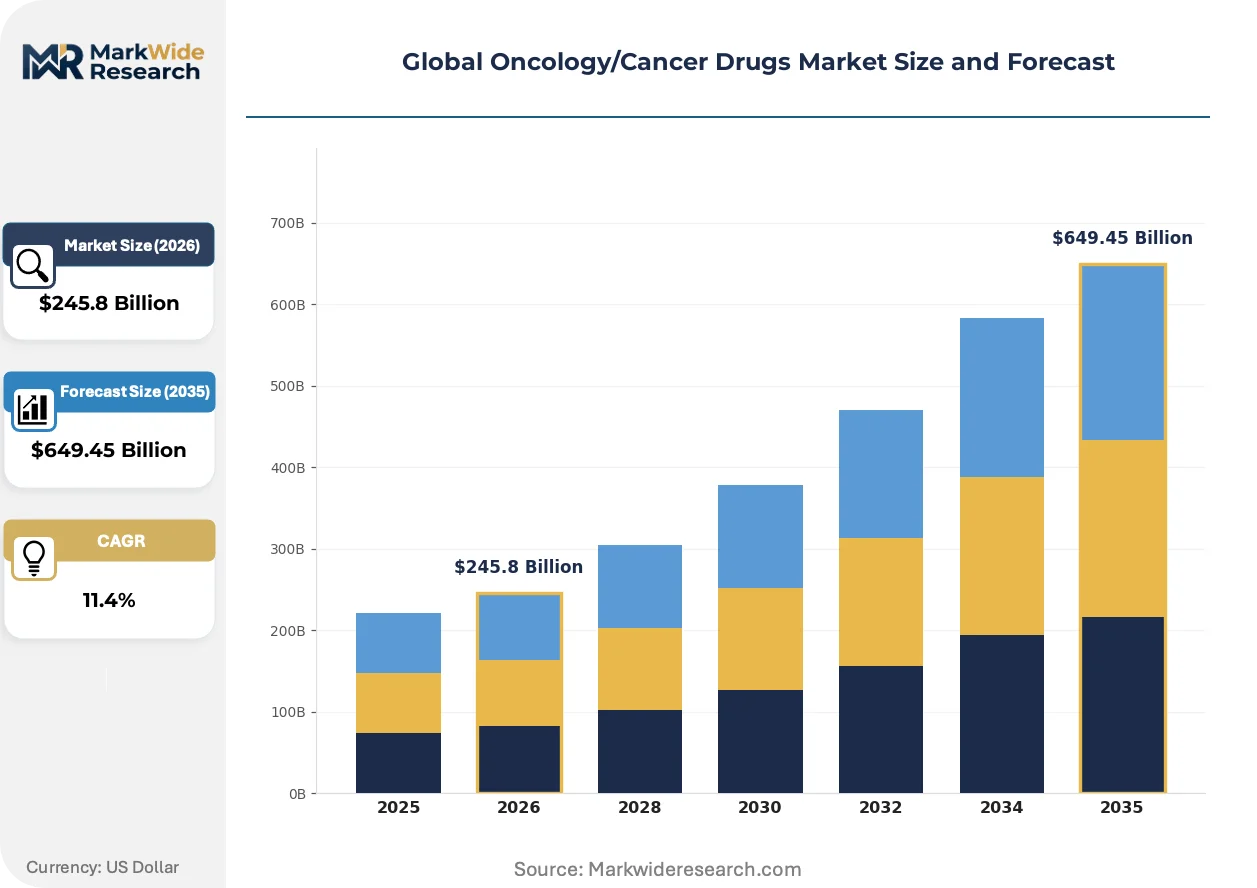
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $649.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Tyrosine Kinase Inhibitors, Immunotherapy Agents, Chemotherapy Drugs, Hormonal Therapies Therapy Area: Lung Cancer, Breast Cancer, Colorectal Cancer, Leukemia, Lymphoma, Melanoma End User: Oncology Clinics, Specialized Cancer Centers, Research Institutions, Pharmaceutical Manufacturers Administration Route: Intravenous, Oral, Subcutaneous, Topical, Intramuscular |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Novartis AG, Bristol-Myers Squibb Company, Pfizer Inc., AstraZeneca, Johnson & Johnson, Eli Lilly and Company, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology/Cancer Drugs Market Shifts & Advancements
Artificial intelligence is compressing target identification timelines while biosimilar competition erodes originator pricing power across established monoclonal antibody franchises.
Antibody-drug conjugates are collapsing the boundary between targeted therapy and cytotoxic potency by delivering payloads directly to tumor-associated antigens. Oncology clinics in the United States are adopting ADCs for earlier treatment lines in breast and lung malignancies. This modality is collapsing the historical sequencing of chemotherapy followed by targeted agents into simultaneous delivery.
EMA's conditional marketing authorization pathway creates divergent evidentiary standards from FDA accelerated approval, forcing sponsors to design parallel trial architectures. European regulators demand earlier survival data while accepting smaller initial cohorts. Sponsors are responding with adaptive trial designs that satisfy both jurisdictions through shared control arms.
Specialty pharmacy networks are consolidating procurement leverage through exclusive distribution agreements for oral oncology agents. Payers are mandating white-bag distribution that bypasses hospital markup for high-cost tyrosine kinase inhibitors. This channel shift is most pronounced in Medicare Part D plans, where mail-order fulfillment now dominates maintenance therapy dispensing.
Global Oncology/Cancer Drugs Market Segmentation
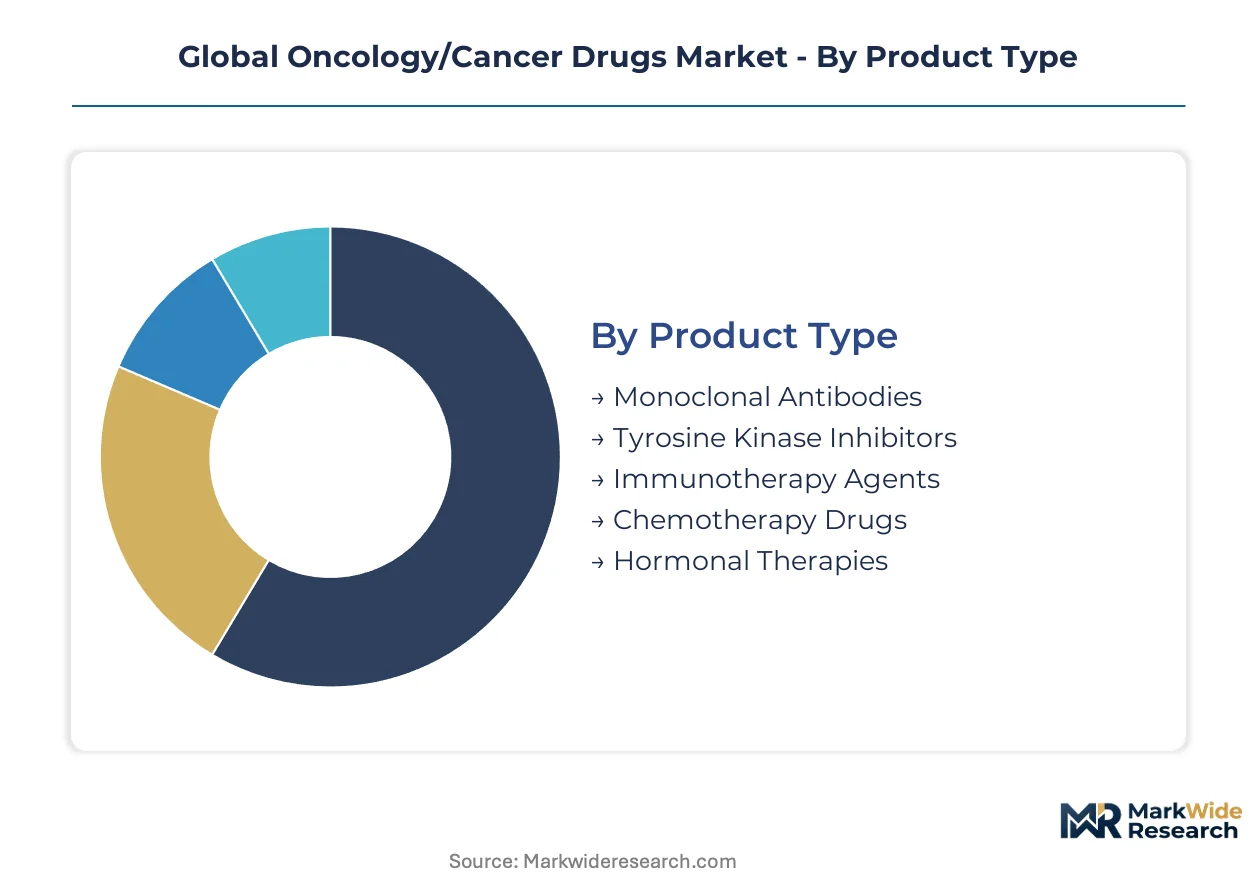
Oncology drug segmentation reveals how treatment modality, disease biology, and care delivery infrastructure intersect to determine commercial priority. Each dimension carries distinct regulatory, reimbursement, and manufacturing implications that reshape competitive investment.
Product Type:
Use-case spectrum spans curative intent in early-stage solid tumors through palliative management of metastatic disease, with each modality commanding different development timelines and pricing architectures.
- Monoclonal Antibodies:Engineered immunoglobulins targeting tumor-associated antigens require mammalian cell culture production at titers exceeding five grams per liter. Demand concentrates in United States hospital infusion centers where Medicare reimbursement anchors premium positioning, though biosimilar erosion compresses originator pricing power.
- Immunotherapy Agents:Checkpoint inhibitors and CAR-T cell therapies reprogram host immune surveillance against malignant cells. United States specialty pharmacy networks and oncology clinics drive fastest uptake as PD-1 inhibitors displace chemotherapy in earlier lung cancer treatment lines.
- Tyrosine Kinase Inhibitors:Small-molecule ATP-competitive inhibitors target oncogenic kinase mutations in resistant subpopulations.
- Chemotherapy Drugs:Cytotoxic alkylating agents and antimetabolites retain foundational role in combination regimens despite toxicity limitations.
- Hormonal Therapies:Androgen and estrogen pathway modulators address hormone-dependent malignancies with established generic substitution.
The dominant share belongs to Monoclonal Antibodies, while Immunotherapy Agents is closing the gap fastest.
Therapy Area:
Cost tier stratification separates high-volume prevalent indications from orphan-designated rare malignancies with concentrated pricing power.
- Lung Cancer:Non-small cell and small cell histologies represent the largest addressable population for checkpoint inhibitor penetration. United States Medicare Part B reimbursement for pembrolizumab and nivolumab combinations anchors revenue concentration, with biomarker-driven patient stratification expanding eligible cohorts.
- Breast Cancer:HER2-directed therapies and CDK4/6 inhibitors command sustained investment as antibody-drug conjugates collapse historical chemotherapy-sequencing boundaries. United States oncology clinics adopt ADCs for earlier lines, reshaping progression-free survival benchmarks.
- Colorectal Cancer:MSI-high subpopulation unlocks immunotherapy eligibility despite overall modest checkpoint inhibitor response rates.
- Leukemia:B-cell malignancies drive CAR-T manufacturing scale as autologous cell processing networks mature.
- Lymphoma:Diffuse large B-cell and follicular histologies anchor CD19-directed cell therapy approvals.
- Melanoma:CTLA-4 and PD-1 combination approvals established immunotherapy efficacy proof-of-concept.
Lung Cancer captures the largest revenue pool, though Breast Cancer is expanding most quickly through ADC adoption.
End User:
Customer type determines channel economics, with institutional purchasing power varying across integrated delivery networks and independent specialty practices.
- Oncology Clinics:Hospital-based infusion centers and community practices administer intravenous biologics under buy-and-bill reimbursement. United States health systems are adding dedicated oncology suites to accommodate rising patient volumes, concentrating demand for monoclonal antibody infusions.
- Specialized Cancer Centers:NCI-designated comprehensive cancer centers anchor clinical trial enrollment and early access to breakthrough therapies. United States academic medical centers drive real-world evidence generation for FDA confirmatory trial mandates.
- Research Institutions:Preclinical and translational research organizations support target identification and biomarker discovery partnerships.
- Pharmaceutical Manufacturers:Captive production facilities and contract manufacturing organizations supply active pharmaceutical ingredients and finished dosage forms.
Oncology Clinics command the dominant patient volume share, while Specialized Cancer Centers are gaining procurement leverage fastest through exclusive distribution negotiations.
Administration Route:
Supply concentration favors parenteral formulations with captive fill-finish capacity, while oral agents channel through consolidated specialty pharmacy networks.
- Intravenous:Large-volume biologic infusions require cold-chain distribution and hospital-based administration infrastructure. Singapore and Switzerland contract manufacturers concentrate bioreactor capacity for monoclonal antibody production.
- Oral:Tyrosine kinase inhibitors and hormone therapies enable home administration with pharmacy benefit manager oversight. United States Medicare Part D plans mandate mail-order fulfillment for maintenance therapy, bypassing hospital markup.
- Subcutaneous:IV-to-SC formulation conversion for checkpoint inhibitors reduces infusion chair time and expands administration settings.
- Topical:Limited application to superficial skin malignancies and radiation dermatitis management.
- Intramuscular:Hormonal depot formulations support extended-release androgen suppression protocols.
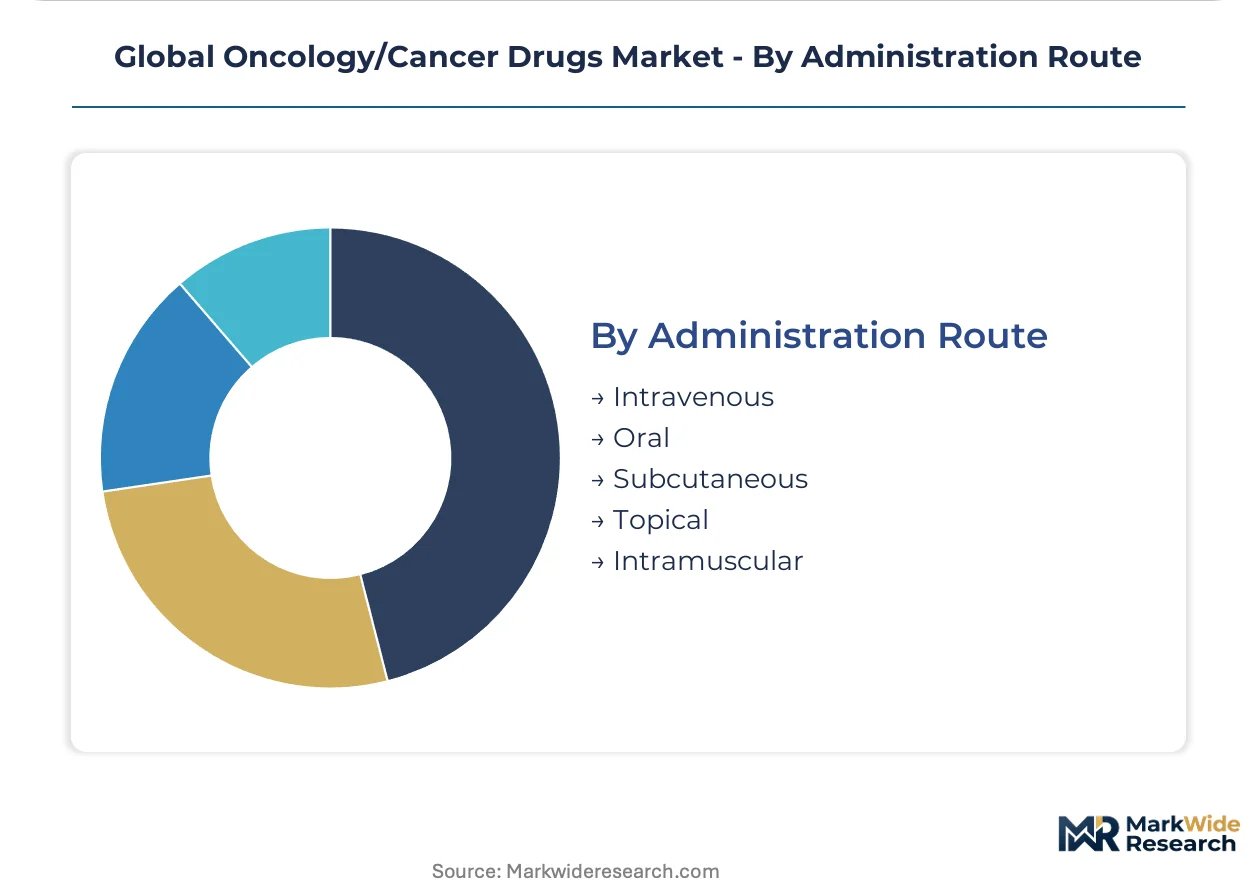
Intravenous retains the dominant revenue position, though Subcutaneous is climbing the fastest as formulation conversion programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology drug trade flows reveal a pronounced import dependency in emerging markets offset by concentrated biopharmaceutical export capacity in Switzerland, the United States, and Singapore. Manufacturing gravity clusters around mammalian cell culture facilities and fill-finish operations that anchor regional supply security.
United States
Medicare Part B reimbursement frameworks anchor hospital buy-and-bill economics for intravenous biologics, while FDA accelerated approval pathways compress commercialization timelines for breakthrough therapies. The IRA's drug pricing negotiation provisions reshape revenue forecasting for oncology assets reaching Medicare eligibility. Greater Boston and San Francisco Bay Area clusters concentrate CAR-T manufacturing and vector production capabilities.
Germany
EMA centralized marketing authorization procedures position Germany as the commercial launch gateway for European oncology markets, with statutory health insurance funds driving price-volume negotiations. REACH biologic traceability mandates impose documentation burdens that favor producers with captive fill-finish capacity. The Rhine-Main and Munich metropolitan regions host contract manufacturing organizations serving monoclonal antibody supply chains.
China
NMPA oncology review reforms have compressed approval timelines to near-parity with FDA cycles, enabling simultaneous multinational launch sequencing for innovative assets. National reimbursement drug list negotiations determine market access velocity for domestic and imported therapies. Shanghai and Suzhou industrial parks concentrate bioreactor capacity and biosimilar development operations.
Switzerland
Swissmedic regulatory alignment with EMA procedures enables seamless European market entry, while bilateral trade agreements preserve pharmaceutical export advantages. The country's dual role as manufacturing hub and headquarters location concentrates decision-making for global oncology portfolios. Basel and Zürich clusters integrate diagnostic-drug pairing capabilities and mammalian cell culture production at industrial scale.
India
CDSCO fast-track oncology pathways and localized clinical trial requirements accelerate biosimilar registration timelines for domestic and export markets. Production-linked incentive schemes for active pharmaceutical ingredients reduce import dependency for oncology drug intermediates. Hyderabad and Ahmedabad manufacturing corridors expand monoclonal antibody biosimilar capacity and contract research operations.
Global Oncology/Cancer Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with manufacturing scale or biomarker technology. The oncology drug market structures around three archetypes: diversified pharmaceutical conglomerates with diagnostic-drug pairing capabilities, immunotherapy-focused developers with checkpoint inhibitor portfolios, and targeted therapy specialists with kinase inhibitor franchises. Competitive moves concentrate on bioreactor capacity expansion and subcutaneous formulation conversions that reduce hospital infusion dependency.
Among Swiss-based integrated healthcare conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diagnostic-therapeutic pairing model that anchors companion-tested therapy positioning. Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions within the immunotherapy tier, representing divergent strategies in checkpoint inhibitor commercialization and cell therapy manufacturing investment. These three entities illustrate how scale, pairing capabilities, and modality focus differentiate competitive positioning within the same therapeutic class.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| AstraZeneca |
| Johnson & Johnson |
| Eli Lilly and Company |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
The Singapore-Basel air freight corridor governs cold-chain distribution economics for monoclonal antibodies, with per-kilogram transport costs cascading into hospital buy-and-bill markups that separate originator biologics from biosimilar entrants across United States and European markets.
Pricing Analysis
Hospital-based oncology clinics anchor value-based pricing structures that stratify across breakthrough therapy designation, companion diagnostic pairing, and line of therapy positioning. Price differentiation hinges on biomarker-driven patient selection and captive fill-finish manufacturing scale, with Medicare Part B reimbursement compressing margins for non-differentiated entrants. Cost pressure intensifies as biosimilar competition erodes originator pricing power in mature monoclonal antibody franchises. Community oncology practices exhibit highest price sensitivity due to buy-and-bill working capital constraints, while NCI-designated centers command premium positioning through trial access leverage.
Supply Chain Analysis
Export control restrictions on mammalian cell culture technology limit bioreactor capacity expansion in emerging markets, concentrating production among Swiss and Singaporean contract manufacturers. Active pharmaceutical ingredient supply draws from Chinese and Indian fermentation facilities, with fill-finish operations tethered to Basel and Boston clusters. Single-source dependency on Swiss bioreactor engineering creates vulnerability to equipment delivery delays. Distribution runs through specialty pharmacy networks for oral agents and hospital-based wholesalers for intravenous biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology drug development fragments across modality-specific niches as biomarker-driven stratification collapses blockbuster economics into addressable subpopulations, creating entry points for targeted therapy specialists.
For Market Incumbents: Pre-empt biosimilar erosion by accelerating subcutaneous formulation conversions that reduce hospital infusion dependency and extend patent-protected positioning. Consolidate manufacturing scale through captive bioreactor capacity additions in Singapore to offset contract manufacturing concentration risk. Prioritize companion diagnostic integration to defend premium pricing against undifferentiated immunotherapy competition.
For New Entrants and Emerging Players: Establish a beachhead in antibody-drug conjugate development for solid tumor indications where payload-linker chemistry differentiation commands pricing power. Target India's CDSCO fast-track pathway for biosimilar registration to capture earlier market access before originator patent cliffs. Deploy real-world evidence partnerships with United States specialty pharmacy networks as primary go-to-market infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated developers with diagnostic-therapeutic pairing capabilities over single-asset biotechs facing confirmatory trial risk. Long-term viability concentrates in entities with validated CAR-T manufacturing networks and vector production scale. Watch FDA accelerated approval withdrawal rates as signal for regulatory risk recalibration across immunotherapy portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | FDA parallel review pathways compress approval timelines for biomarker-selected therapies. |
| Subcutaneous Formulation Conversion | IV-to-SC delivery shifts reduce hospital markup dependency and expand home administration channels. |
| Captive Fill-Finish Capacity Expansion | REACH traceability mandates favor producers with in-house aseptic manufacturing infrastructure. |
| Real-World Evidence Infrastructure | Medicare data partnerships satisfy FDA confirmatory trial mandates for accelerated approvals. |
| Biosimilar Portfolio Buildout | CDSCO fast-track pathways in India enable earlier market entry before United States patent expiries. |
Research Methodology
The analysis maps monoclonal antibody, immunotherapy, and targeted therapy sub-sectors, each validated through regulatory affairs leads at EMA and FDA, hospital formulary directors, payer access specialists, and contract manufacturing executives. Primary interviews with biopharma development executives and specialty pharmacy procurement managers combined with secondary validation against FDA accelerated approval filings, EMA centralized procedure submissions, ClinicalTrials.gov enrollment data, and Medicare Part B claims databases. Bottom-up patient population modeling and top-down revenue triangulation anchored segmentation-specific growth trajectories.
Assumptions held regulatory pathway timelines and reimbursement frameworks constant across the projection horizon, while treatment line positioning and biosimilar entry timing varied by segment. The analytical framework modeled administration route, therapy area, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from patient volume epidemiology, pricing elasticity by payer type, and manufacturing capacity expansion schedules. Forecast inputs incorporated biomarker prevalence rates and hospital infusion capacity constraints.
Sensitivities concentrate around FDA confirmatory trial failure rates, IRA drug pricing negotiation implementation, and bioreactor capacity bottlenecks. Forecasts reflect documented assumptions on biomarker-driven patient stratification adoption curves. Material shifts in accelerated approval withdrawal patterns or Medicare reimbursement rate changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
1-Step RT-PCR Kits Market