
 Global Anti-Infective Drugs Market | 2026-2036
Global Anti-Infective Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Infective Drugs Market Foresight
The EU Green Deal is rebalancing manufacturing priorities across European pharmaceutical supply chains, with anti-infective producers facing stricter environmental discharge limits and carbon accounting under the CSRD framework. Pfizer Inc. leverages its integrated fermentation network to sustain cost-competitive cephalosporin output. Merck & Co., Inc. anchors its anti-infective portfolio on hospital-administered carbapenems. Gilead Sciences Inc. differentiates through its antiviral specialization in HIV and hepatitis C therapies.
Anti-infective drugs comprise chemically synthesized or biologically derived agents that inhibit pathogen replication or directly destroy infectious microorganisms, with formulations typically specified by minimum inhibitory concentration thresholds, bioavailability percentages, and stability under cold-chain conditions. These therapeutics serve to treat or prevent bacterial, viral, fungal, and parasitic infections across acute care, chronic disease management, and prophylactic settings. Antibiotics retain the largest revenue share within product type segmentation, though antivirals are expanding fastest as RNA-targeting platforms mature. Hospital pharmacies dominate distribution channel value capture due to formulary control and infusion-administered therapies, while online pharmacies are gaining share in post-acute oral regimens.
FDA, EMA, and WHO standards govern clinical trial endpoints, manufacturing quality, and antimicrobial resistance surveillance, with each body tightening evidence requirements for novel mechanisms and restricting legacy antibiotic approvals. The WHO Essential Medicines List shapes national procurement priorities and access programs across low- and middle-income markets. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization criteria as this gap determines portfolio sequencing and launch geography decisions.
Market Dynamics
Antimicrobial resistance surveillance is compressing development timelines and forcing portfolio rebalancing across anti-infective pipelines, with regulators now conditioning approvals on resistance stewardship commitments.
Growth Catalysts
- US Hospital Stewardship Mandates:CMS reimbursement rules now tie infection control metrics to formulary access, accelerating demand for narrow-spectrum agents with resistance-sparing profiles.
- India's National Health Mission Procurement:Government tenders for anti-TB and HIV regimens are scaling domestic formulation capacity through price-volume agreements with local manufacturers.
- RNA-Targeted Platform Maturation:Next-generation antiviral design tools are shortening lead optimization cycles for hepatitis C and emerging pathogen programs.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China dominates cephalosporin and penicillin intermediate supply, creating single-source vulnerability for European and North American formulators.
- EU Green Deal Discharge Limits:ECHA's pharmaceutical effluent standards are raising capital requirements for fermentation-based antibiotic production by mandating closed-loop water systems.
- Generic Substitution Pressure:Off-patent carbapenems and fluoroquinolones face rapid commoditization in hospital group purchasing, eroding branded pricing power.
Strategic Opportunities
- Sub-Saharan Africa Access Programs:WHO prequalification pathways for HIV and malaria combination therapies create first-mover advantage in procurement pools serving 40-plus national programs.
- Online Pharmacy Post-Acute Channels:Direct-to-patient oral antibiotic fulfillment is capturing chronic prophylaxis prescriptions previously routed through hospital discharge pharmacies.
- CSRD Carbon Accounting Integration:Early adopters of supply chain emissions transparency are securing preferential formulary positioning with EU hospital systems under green procurement directives.
Industry Challenges
- Specialized Fermentation Talent Scarcity:Industrial microbiology expertise for large-scale antibiotic production is concentrating at legacy manufacturing sites, constraining geographic expansion.
- Legacy Quality System Integration:MDR-compliant documentation requirements are forcing retrofits of decades-old batch record systems at European production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Infective Drugs Market |
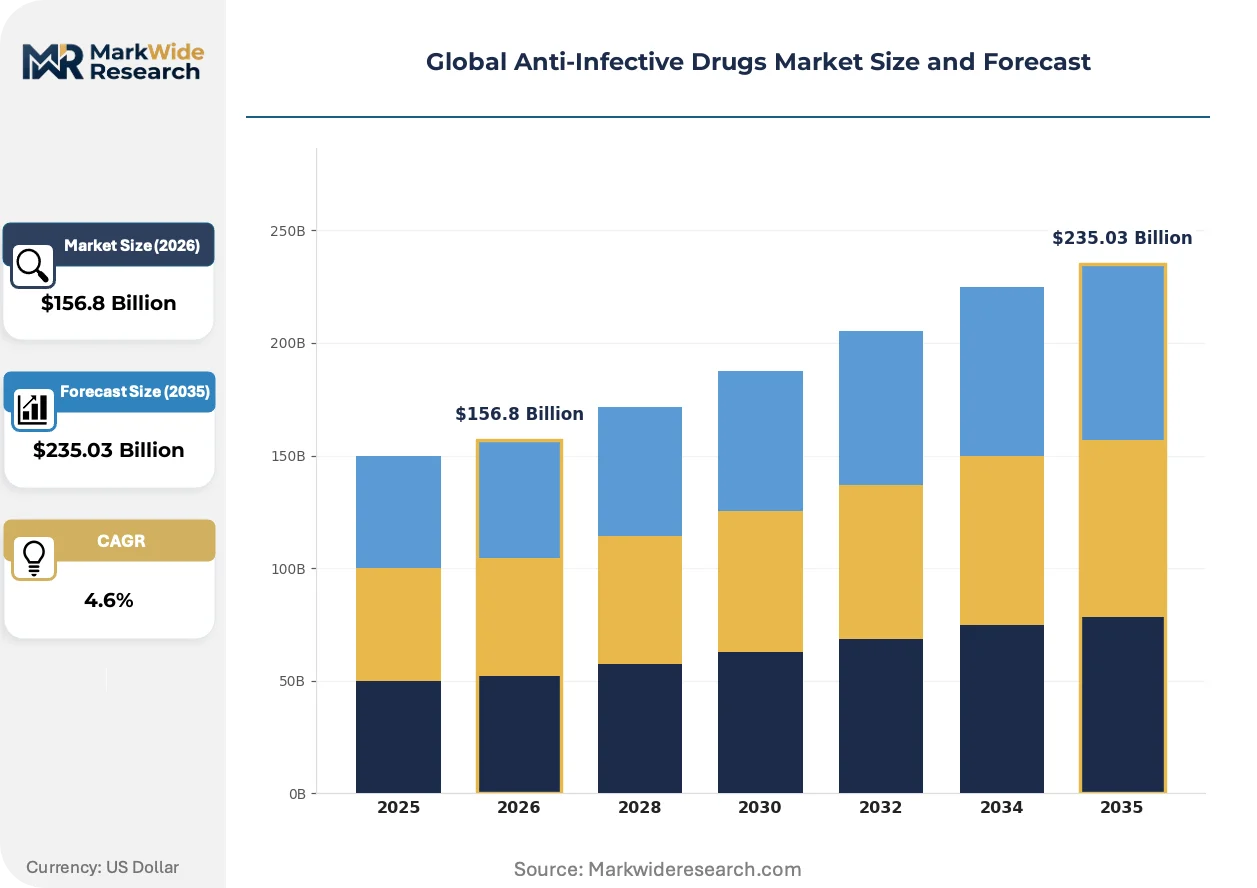
| Market Size in 2026 | $156.8 Billion |
| Market Size in 2035 | $235.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Antifungals, Antiparasitics, Immunomodulators Therapy Area: Respiratory Infections, Sexually Transmitted Infections, Urinary Tract Infections, Skin & Soft Tissue Infections, Gastrointestinal Infections End User: Pharmacies, Clinics, Diagnostic Labs, Home Healthcare, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Direct Sales |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Novartis AG, Gilead Sciences Inc., GlaxoSmithKline plc, Sanofi, AbbVie Inc., Johnson & Johnson Services Inc., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Infective Drugs Market Shifts & Advancements
Machine learning is penetrating anti-infective discovery pipelines, compressing target identification cycles and reshaping how sponsors prioritize resistance-resistant chemical scaffolds.
Artificial intelligence-driven molecular design platforms are automating the screening of bacteriophage-derived lysins and antimicrobial peptides against priority pathogens. Mid-sized biotech sponsors are integrating these tools into early-phase programs within 18-month adoption windows. The technology is automating the elimination of compounds with predicted resistance liability before costly synthesis, redirecting R&D spend toward mechanism-novel candidates.
EMA's conditional marketing authorization framework is tightening evidentiary standards for novel antibiotic classes, requiring sponsors to pre-commit resistance surveillance protocols as a condition of approval. This policy shift is extending regulatory timelines for Gram-negative programs by 12-18 months. Hospital-administered therapies in Southern Europe are experiencing delayed launches as sponsors restructure Phase IV commitment packages.
Hospital procurement consortia are consolidating formulary decision-making across multi-state networks in the United States, replacing individual pharmacy and therapeutics committees with centralized value-assessment boards. This concentration is compressing supplier negotiation windows and privileging vendors with integrated resistance data packages. The Midwest and Southeast regions display the most advanced consolidation, with three buying groups controlling access to 40 percent of acute-care beds.
Global Anti-Infective Drugs Market Segmentation
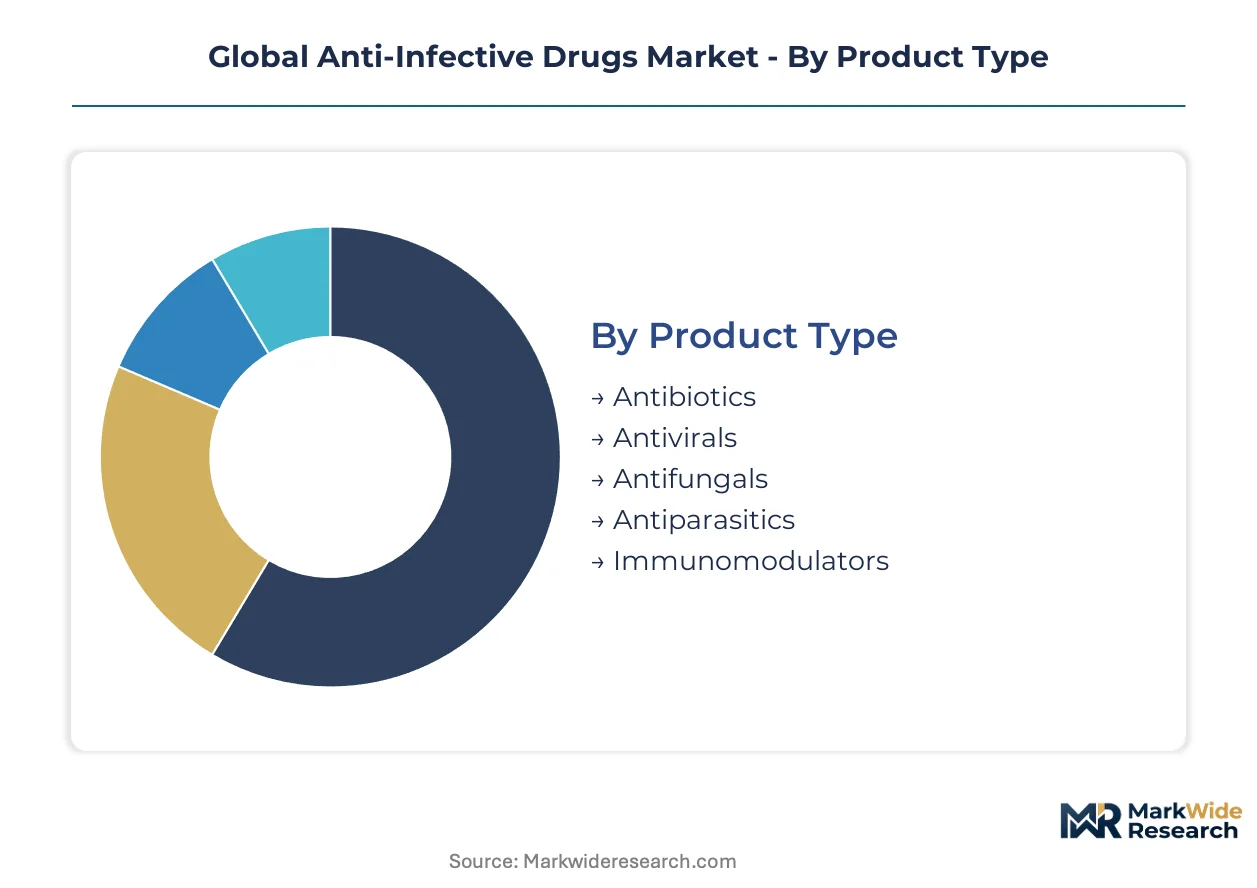
Anti-infective drugs require precise segmentation to match formulation characteristics with administration settings and resistance profiles. Each dimension reveals distinct procurement patterns, regulatory pathways, and margin structures that determine competitive positioning.
Product Type:
Standalone therapeutics dominate revenue capture, while combination regimens and adjuvant platforms embed within broader treatment protocols.
- Antibiotics:Beta-lactams, macrolides, and fluoroquinolones constitute the foundational antibacterial arsenal, with cephalosporin fermentation output concentrated at legacy manufacturing sites in India and China. CMS stewardship mandates in US hospital systems are accelerating demand for narrow-spectrum agents that spare resistance development.
- Antivirals:Nucleoside analogs and protease inhibitors target HIV, hepatitis C, and emerging RNA pathogens, with RNA-targeted platform maturation shortening lead optimization cycles. Gilead Sciences anchors this segment through its hepatitis C and HIV specialization.
- Antifungals:Azoles and echinocandins address invasive candidiasis and aspergillosis in immunocompromised populations.
- Antiparasitics:Antimalarial combinations and anthelmintic regimens serve WHO prequalification pathways across sub-Saharan Africa.
- Immunomodulators:Adjunctive agents that enhance host response to refractory infections.
Antibiotics lead volumes today; antivirals are gaining share fastest.
Therapy Area:
Acute indications drive episodic prescribing patterns, while chronic infectious disease management embeds within longitudinal care pathways.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis generate high-volume outpatient prescribing, with seasonal influenza co-infections amplifying antiviral demand in temperate climates. Stewardship programs are narrowing empiric coverage in US hospitals.
- Sexually Transmitted Infections:Gonococcal and chlamydial infections require dual-therapy coverage amid rising resistance to legacy agents. India's National Health Mission procurement is scaling domestic formulation capacity for HIV co-treatment regimens.
- Urinary Tract Infections:Uncomplicated cystitis drives retail pharmacy volume, while complicated pyelonephritis routes through hospital infusion.
- Skin & Soft Tissue Infections:Diabetic foot infections and surgical site prophylaxis anchor hospital antibiotic consumption.
- Gastrointestinal Infections:Clostridioides difficile and traveler's diarrhea indications favor targeted oral therapies.
Respiratory infections anchor prescription volumes; sexually transmitted infections show the steepest expansion trajectory amid resistance surveillance intensification.
End User:
Institutional settings capture complex infusion therapies, while decentralized channels expand for oral maintenance regimens.
- Pharmacies:Retail and hospital dispensaries control formulary access, with hospital pharmacies dominating value capture through infusion-administered carbapenems and antivirals.
- Clinics:Outpatient infusion centers and infectious disease practices manage parenteral antibiotic completion.
- Diagnostic Labs:Reference laboratories inform resistance-guided therapy selection through rapid susceptibility testing.
- Home Healthcare:Post-acute oral antibiotic fulfillment is capturing chronic prophylaxis prescriptions previously routed through hospital discharge.
- Research Institutes:Academic medical centers conduct antimicrobial resistance surveillance and novel mechanism validation.
Hospital pharmacies command the largest value share; home healthcare is expanding most quickly through direct-to-patient fulfillment models.
Distribution Channel:
Direct procurement relationships dominate high-value hospital contracts, while intermediaries serve fragmented retail and institutional demand.
- Hospital Pharmacies:Integrated formulary control and group purchasing organization consolidation across Midwest and Southeast US networks compress supplier negotiation windows.
- Retail Pharmacies:Community dispensaries handle oral antibiotic and antiviral maintenance prescriptions.
- Online Pharmacies:Direct-to-patient platforms are gaining share in post-acute oral regimens and chronic prophylaxis.
- Wholesale Distributors:Regional warehouses maintain cold-chain integrity for temperature-sensitive biologics.
- Direct Sales:Manufacturer-to-institution contracts serve large hospital systems with integrated resistance data packages.
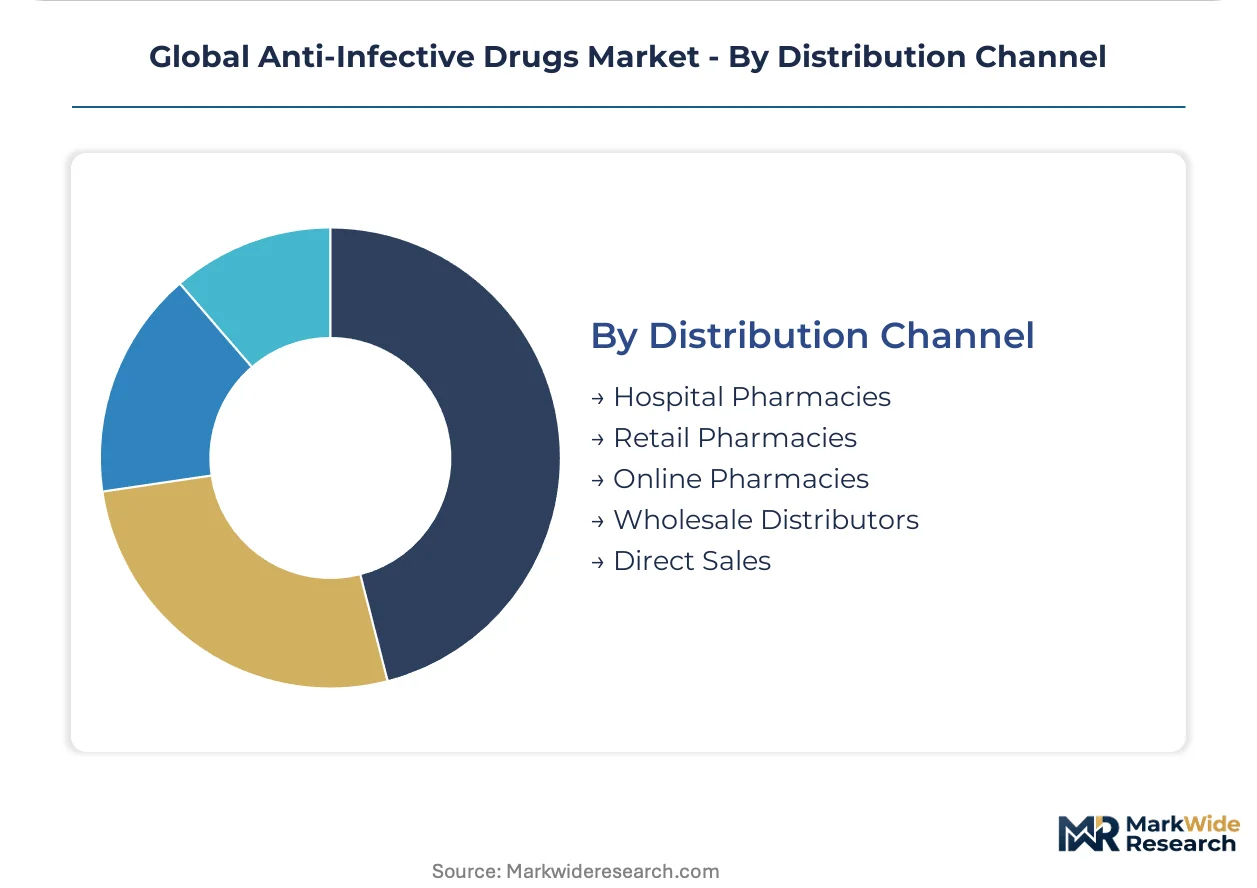
Hospital pharmacies retain dominant value capture; online pharmacies are climbing the fastest as post-acute prescribing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial microbiology talent clusters anchor pharmaceutical fermentation output across three continents, with cephalosporin and penicillin intermediate production concentrated at legacy manufacturing sites in Asia and Europe.
United States
CMS stewardship mandates tie infection control metrics to hospital formulary access, accelerating procurement of narrow-spectrum agents. FDA accelerated approval pathways condition novel antibiotic launches on resistance surveillance commitments. The Research Triangle Park corridor in North Carolina hosts antimicrobial resistance surveillance coordination and clinical trial operations.
India
Government tenders for anti-TB and HIV regimens scale domestic formulation capacity through price-volume agreements with local manufacturers. CDSCO streamlined approval pathways support export-oriented production under WHO prequalification standards. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient synthesis and generic formulation packaging for African and Southeast Asian markets.
Germany
EMA conditional marketing authorization frameworks extend regulatory timelines for Gram-negative programs by requiring pre-committed resistance protocols. EU Green Deal discharge limits under ECHA pharmaceutical effluent standards mandate closed-loop water systems at fermentation facilities. The Rhine-Main industrial cluster around Frankfurt maintains legacy antibiotic production infrastructure with integrated quality system retrofits for MDR compliance.
China
Domestic cephalosporin and penicillin intermediate supply dominates global raw material flows for European and North American formulators. NMPA manufacturing quality inspections align with WHO prequalification standards for export-oriented production. The Shandong and Jiangsu province clusters concentrate fermentation capacity with state-supported capacity expansion for domestic health security stockpiles.
Brazil
ANVISA regulatory harmonization with FDA and EMA standards facilitates technology transfer partnerships for local antiviral production. Government procurement through the Unified Health System scales access programs for HIV combination therapies. The São Paulo state pharmaceutical corridor hosts formulation packaging and distribution logistics serving Mercosur markets.
Global Anti-Infective Drugs Market Competitive Landscape
Capital-heavy producers with integrated fermentation networks compete with asset-light designers of RNA-targeted antiviral platforms. The market structures around three tiers: multinational conglomerates with hospital-administered portfolios, mid-cap specialists in narrow-spectrum antibiotics, and generic formulators serving national procurement programs. Dominant competitive moves include M&A to secure resistance-sparing chemical scaffolds and capacity expansion into India and China to capture government tender volumes.
Within the integrated manufacturing tier, Pfizer Inc. and Merck & Co., Inc. occupy positions anchored on fermentation-derived cephalosporin and carbapenem output respectively. Gilead Sciences Inc. exemplifies the asset-light antiviral specialist model focused on nucleoside analog design. These three entities represent contrasting strategic archetypes: captive supply chain control versus outsourced synthesis partnerships versus platform technology licensing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Gilead Sciences Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| AbbVie Inc. |
| Johnson & Johnson Services Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Fermentation-to-synthesis technology transitions in cephalosporin production are compressing unit economics while redistributing manufacturing gravity toward India and China, simultaneously eroding legacy European cost premiums and amplifying price competition in hospital procurement tenders across North America and Western Europe.
Pricing Analysis
Three-tier pricing structure across originator brands, authorized generics, and commodity API suppliers governs hospital formulary negotiations and retail pharmacy procurement. Price differentiation hinges on FDA bioequivalence certification status and resistance surveillance data packages bundled with supply contracts. Cost compression in the commodity tier is intensifying because Indian and Chinese manufacturers are scaling fermentation capacity under government-backed production incentives. Hospital group purchasing organizations display the highest price sensitivity, while specialty infectious disease clinics accept premiums for narrow-spectrum agents with validated resistance-sparing profiles.
Supply Chain Analysis
Dual-sourcing requirements mandated by EU MDR and US FDA quality agreements are forcing formulators to qualify secondary API suppliers beyond their primary China-based relationships. Active pharmaceutical ingredient production draws from Shandong and Jiangsu provinces in China, the Hyderabad-Visakhapatnam corridor in India, and legacy fermentation sites in Germany and Italy. Supply chain risk centers on single-source vulnerability for penicillin and cephalosporin intermediates, where three Chinese state-affiliated producers control upstream fermentation output. Distribution runs through regional wholesale distributors maintaining cold-chain integrity for temperature-sensitive biologics, with direct manufacturer-to-hospital contracts capturing high-value carbapenem and antiviral infusions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Anti-Infective Drugs Market functions as a stable compounder anchored by irreplaceable hospital demand for last-resist antibiotics and chronic antiviral maintenance regimens that resist substitution.
For Market Incumbents: Anticipate generic substitution pressure in carbapenem and fluoroquinolone categories by accelerating backward integration into fermentation capacity in India and securing WHO prequalification status for sub-Saharan Africa tenders. Resistance surveillance data infrastructure represents the priority defensive lever for sustaining formulary positioning against emerging narrow-spectrum competitors.
For New Entrants and Emerging Players: Enter via online pharmacy direct-to-patient channels for post-acute oral antibiotic fulfillment, where hospital discharge pharmacy relationships remain underdeveloped. Sub-Saharan Africa access programs for HIV and malaria combination therapies offer the most penetrable procurement entry point, with WHO prequalification serving as the critical go-to-market credential.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap narrow-spectrum antibiotic developers with Phase III Gram-negative programs and pre-committed resistance surveillance protocols. Long-term viability across the analysis window favors asset-light antiviral platform specialists over capital-heavy fermentation operators exposed to EU Green Deal discharge compliance costs. The signal to watch is EMA conditional marketing authorization timeline extensions for novel antibiotic classes, which would compress exit multiples for development-stage assets.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks procurement access across 40-plus national HIV and malaria programs in sub-Saharan Africa. |
| Resistance Surveillance Data Integration | Secures preferential formulary positioning with US hospital systems under CMS stewardship mandates. |
| Fermentation Capacity Expansion | Captures price-volume agreements with India's National Health Mission for anti-TB and HIV regimens. |
| Online Pharmacy Channel Development | Captures chronic prophylaxis prescriptions shifting from hospital discharge pharmacies. |
| CSRD Carbon Accounting Adoption | Qualifies for green procurement directives with EU hospital systems under EU Green Deal frameworks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure tracking were cross-referenced to anchor volume estimates.
Segment-weighting approaches distributed revenue projections across product type, therapy area, and distribution channel dimensions, with regional regulatory clusters and administration route modifiers applied throughout the projection horizon. CAGRs were derived from patent expiry schedules, biosimilar entry assumptions, and government tender volume trajectories, with antimicrobial resistance surveillance intensity and stewardship program adoption serving as demand-side modifiers.
Inputs from clinical trial registries and procurement databases were available through the study window; gaps in real-time hospital formulary shift data introduce uncertainty bands around near-term market share assumptions. Deviation in EMA conditional marketing authorization evidentiary requirements or CMS stewardship mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market