
 Plasma Protease C1-Inhibitor Market | 2026-2036
Plasma Protease C1-Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Protease C1-Inhibitor Market Analytics
Buyer concentration among hospital systems and specialty infusion centers is hardening, with integrated delivery networks consolidating C1-inhibitor procurement decisions. CSL Behring leverages its plasma collection infrastructure across multiple continents to sustain raw material security. Takeda Pharmaceutical Company anchors the recombinant segment through specialized manufacturing capabilities. Pharming Group N.V. competes with niche positioning in ultra-rare complement disorders.
Plasma protease C1-inhibitor is a serine protease inhibitor glycoprotein, approximately 105 kDa in molecular weight, synthesized in the liver and circulating at plasma concentrations near 0.25 g/L, where it regulates the classical complement pathway, contact activation system, and fibrinolytic cascade. Its primary therapeutic purpose centers on preventing or aborting acute swelling attacks in hereditary angioedema patients with C1-INH deficiency or dysfunction. Concentrates dominate current revenue pools due to established reimbursement and long clinical track records, while subcutaneous delivery modes represent the fastest-growing structural shift as patients migrate from hospital-based intravenous administration toward homecare self-injection protocols. Lyophilized products retain margin strength in emerging markets where cold chain infrastructure remains fragmented.
FDA orphan drug exclusivity provisions and EMA's orphan medicinal product designation framework shape development incentives, accelerating trial timelines and extending market protection for novel C1-inhibitor formulations. The EU's F-Gas Regulation and corresponding EPA mandates on hydrofluorocarbon propellants in medical aerosols are forcing device redesigns for some delivery platforms. Stakeholders must monitor evolving biosimilar pathways and subcutaneous formulation interchangeability standards as these will determine competitive switching dynamics and payer contracting leverage in the decade ahead.
Market Dynamics
Subcutaneous delivery migration is compressing hospital-based infusion revenues and redistributing value toward device-enabled homecare platforms, forcing manufacturers to reconfigure commercial infrastructure around patient self-administration rather than institutional procurement.
Growth Catalysts
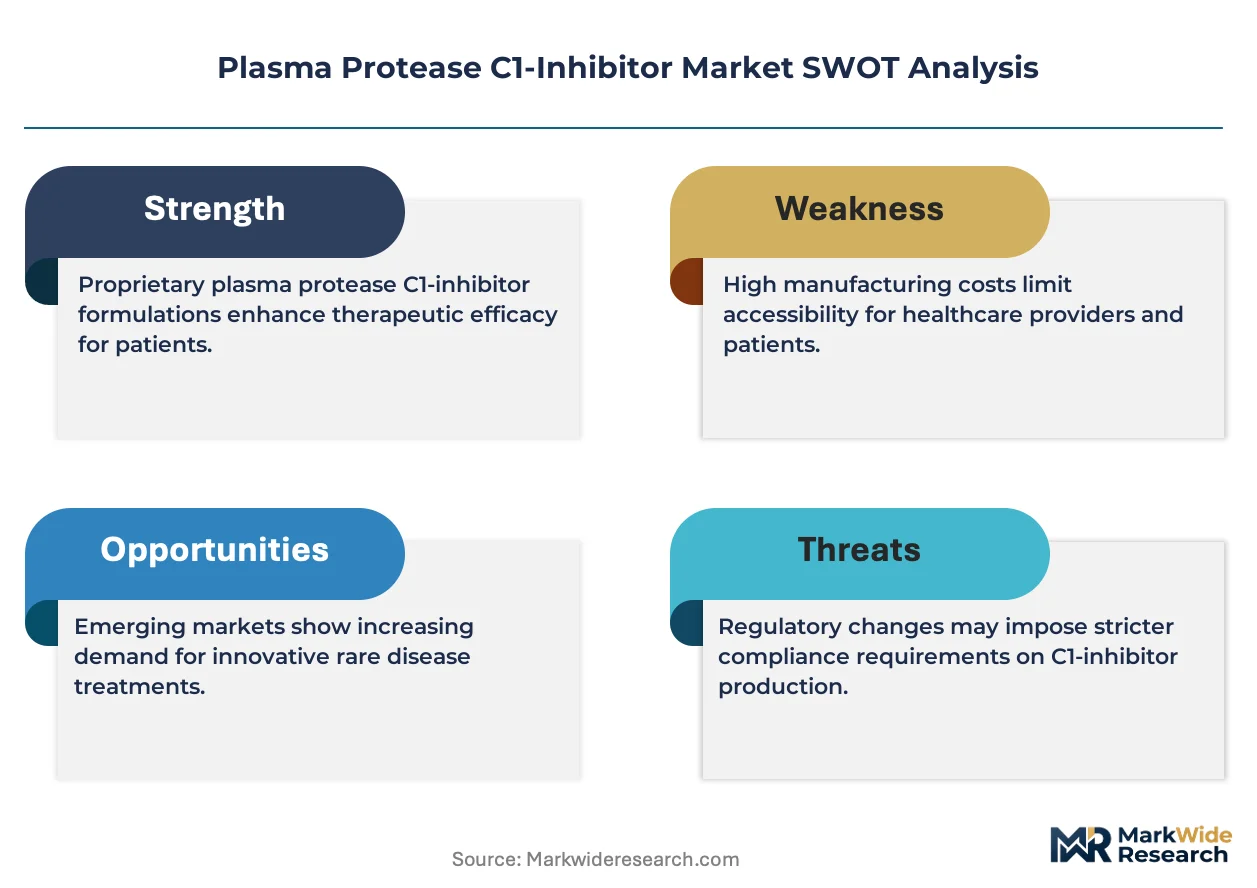
- EMA Orphan Medicinal Product designation:Accelerated clinical trial protocols and extended market exclusivity provisions incentivize development of novel C1-inhibitor formulations across European markets.
- Specialist immunology centers:Concentrated patient access points in the United States, Germany, and Japan streamline diagnosis-to-treatment pathways and anchor reimbursement negotiations.
- Lyophilized formulations:Reduced cold chain dependency expands addressable markets in regions with fragmented logistics infrastructure.
Market Restraints
- Plasma collection concentration:Dependence on fractionation infrastructure across limited geographies creates raw material security vulnerabilities during supply disruptions.
- F-Gas Regulation compliance costs:EU mandates on hydrofluorocarbon propellants force device redesign expenditures for aerosolized delivery platforms.
- Recombinant protein manufacturing complexity:Specialized bioreactor requirements and glycosylation control limit production scale-up velocity.
Strategic Opportunities
- Homecare self-injection protocols:Patient migration from intravenous hospital administration creates channel expansion potential for device-integrated combination products.
- Biosimilar pathway clarity:Emerging FDA and EMA interchangeability standards will determine competitive switching dynamics and payer contracting leverage.
- Ultra-rare complement disorders:Niche positioning in atypical hemolytic uremic syndrome and related conditions opens premium pricing segments.
Industry Challenges
- Biologics manufacturing talent scarcity:Specialized expertise in plasma fractionation and recombinant protein purification commands premium compensation and limits operational expansion.
- Legacy intravenous infrastructure stranded costs:Hospital infusion center investments face utilization compression as patients transition to subcutaneous home administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Protease C1-Inhibitor Market |
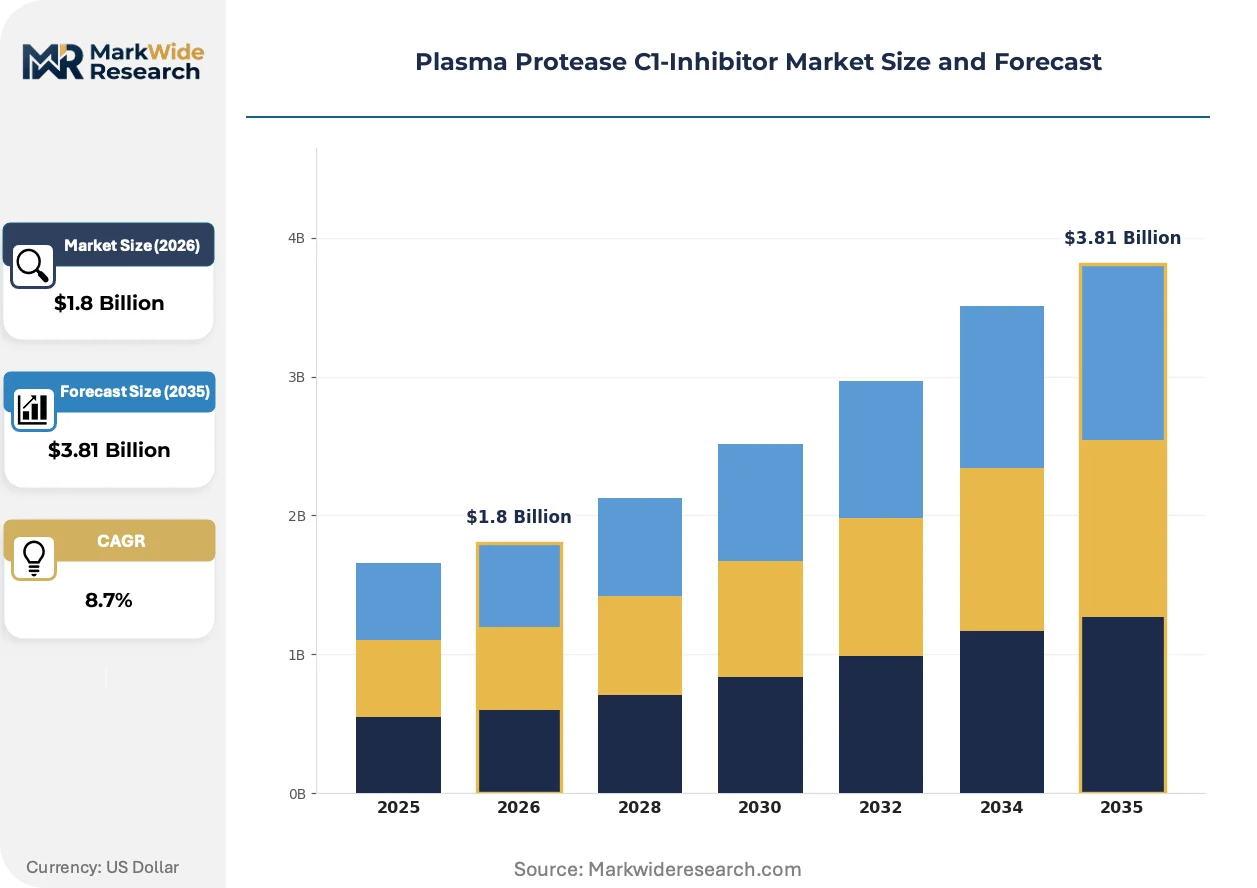
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
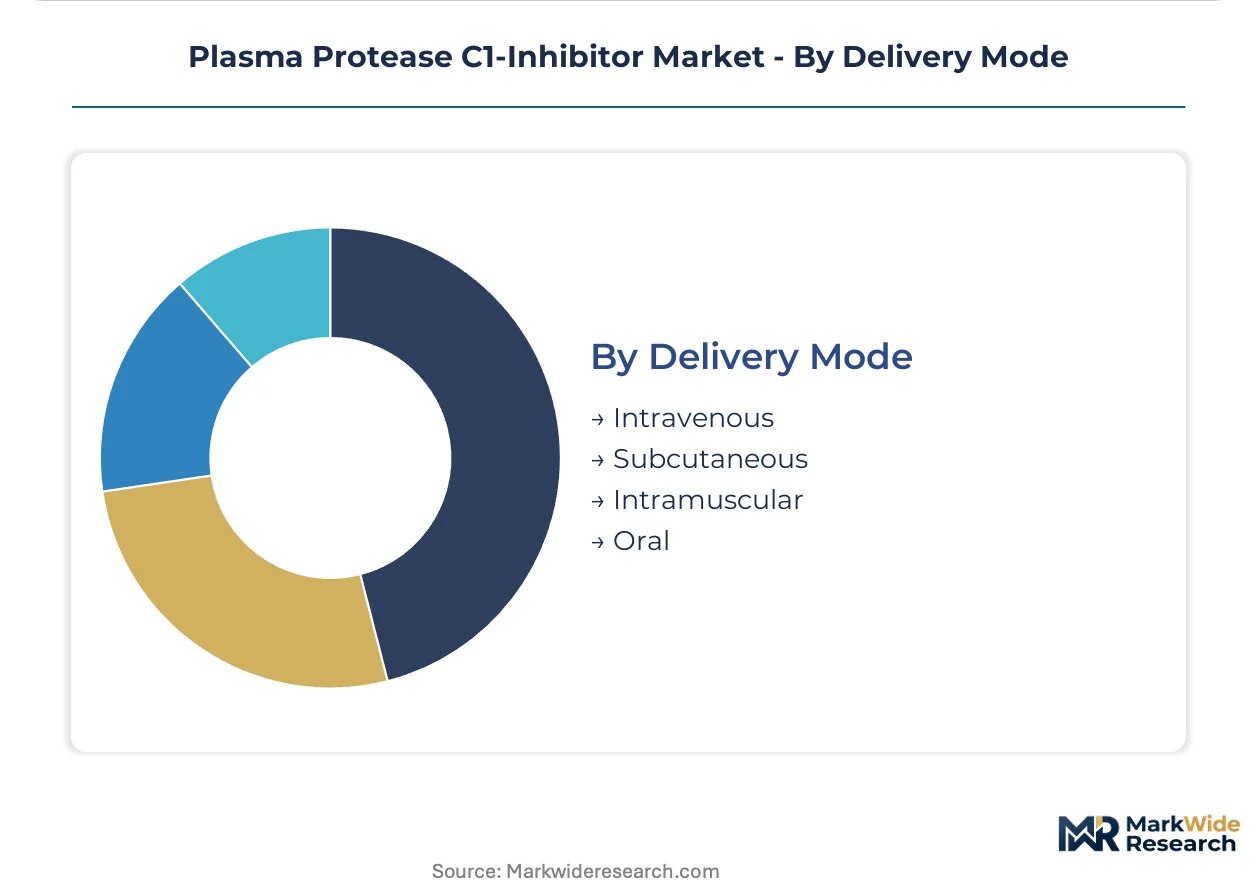
| Segmentation | Product Type: Concentrates, Injectable Solutions, Lyophilized Products, Frozen Products Application: Hereditary Angioedema, Acquired Angioedema, Trauma Management, Surgical Procedures End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company, Pharming Group N.V., KalVista Pharmaceuticals, BioCryst Pharmaceuticals, Sanquin, Grifols, Octapharma, ADMA Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Protease C1-Inhibitor Market Evolving Landscape
Formulation science and delivery mechanism convergence are redistributing competitive advantage from plasma sourcing scale toward patient-centered administration convenience and cold chain resilience.
Subcutaneous C1-inhibitor concentrates are absorbing market share previously held by intravenous formulations as patient preference for home-based self-administration hardens. Specialist immunology centers in the United States and Germany report accelerating enrollment in patient training programs for prefilled syringe and autoinjector platforms. This modality shift is compressing hospital infusion revenue streams while expanding addressable patient populations through reduced treatment burden.
REACH and EU F-Gas Regulation mandates on fluorinated greenhouse gases are compelling device manufacturers to reformulate propellant systems for metered-dose inhalation platforms. Industrial consequence includes extended development timelines and validation requirements for combination product submissions. Manufacturers with advanced device portfolios are reallocating R&D expenditure toward propellant-free or alternative gas systems to maintain European market access.
Integrated delivery networks are consolidating C1-inhibitor procurement decisions under centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. Specialty infusion centers face margin compression as hospital systems negotiate exclusive distribution agreements directly with manufacturers. This concentration is most visible in United States metropolitan markets where vertically integrated health systems anchor regional patient access.
Plasma Protease C1-Inhibitor Market Segmentation
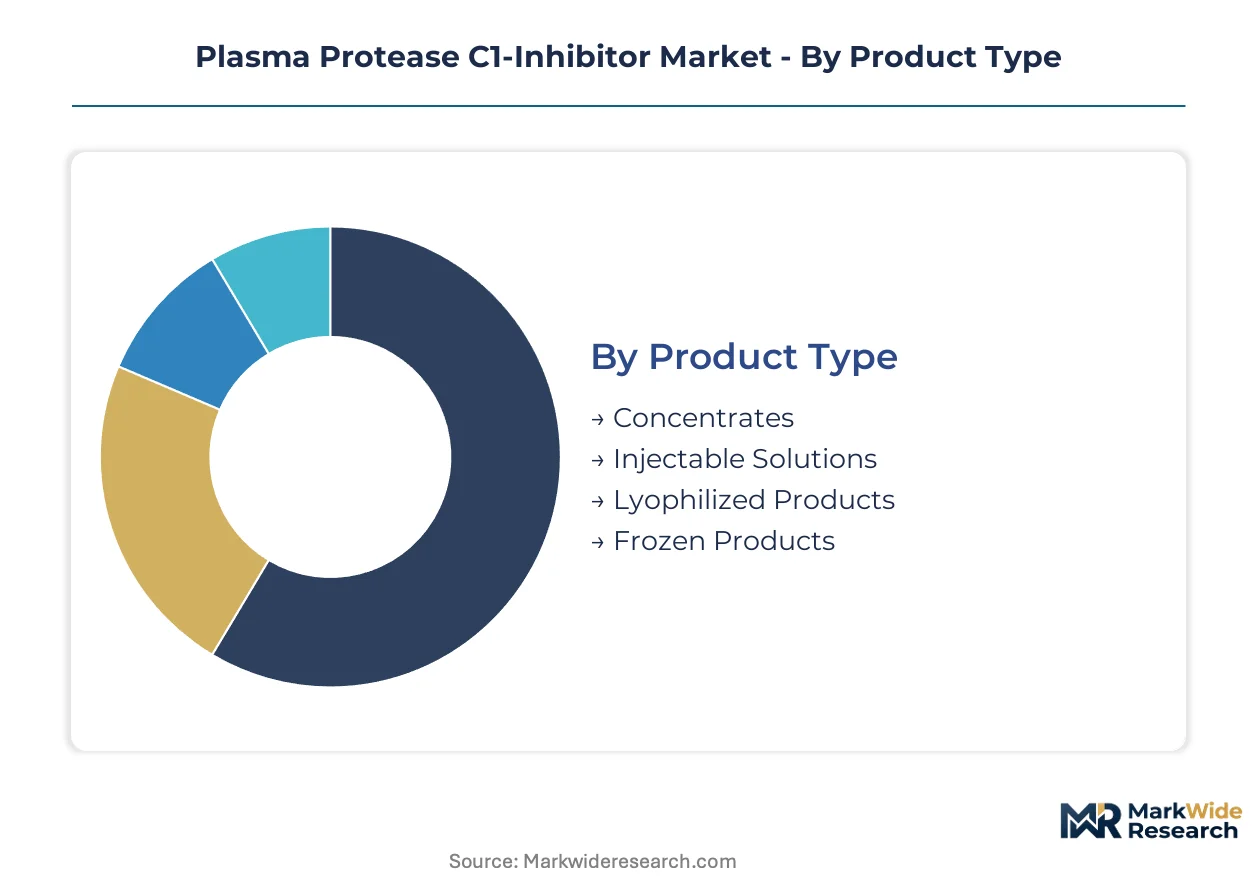
Segmentation in the Plasma Protease C1-Inhibitor Market reveals how regulatory pathways, patient administration preferences, and supply chain infrastructure reshape competitive positioning across product formats and delivery channels. Each dimension carries distinct certification burdens and margin structures that determine manufacturer resource allocation.
Product Type:
FDA BLA and EMA MAA pathways impose divergent stability validation requirements across these four formats, with lyophilized and frozen products facing distinct cold chain documentation standards.
- Concentrates:Plasma-derived or recombinant protein formulations at high purity levels, stabilized for extended shelf life. Hospital procurement in the United States and Germany concentrates demand here, driven by established reimbursement codes and long clinical track records in hereditary angioedema prophylaxis.
- Lyophilized Products:Freeze-dried formulations enabling ambient temperature storage after reconstitution. Emerging markets across India and Brazil absorb volume growth as fragmented logistics infrastructure limits frozen distribution reach.
- Injectable Solutions:Ready-to-use liquid formulations requiring continuous cold chain maintenance.
- Frozen Products:Ultra-low temperature storage formats preserving native protein conformation.
Concentrates sit at the top of the volume ranking, with lyophilized products climbing the fastest.
Application:
Orphan drug exclusivity provisions and diagnosis code specificity create tiered addressable market economics across these four clinical indications.
- Hereditary Angioedema:Genetic C1-INH deficiency driving prophylactic and acute treatment protocols. Specialist immunology centers in the United States, Germany, and Japan anchor patient identification and therapy initiation, with subcutaneous self-administration expanding the treatable population.
- Acquired Angioedema:Autoantibody-mediated C1-INH dysfunction associated with lymphoproliferative disorders. Oncology and immunology co-management in tertiary hospitals drives concentrated demand, constrained by lower diagnosis rates and complex payer navigation.
- Trauma Management:Off-label complement modulation in massive transfusion scenarios.
- Surgical Procedures:Perioperative prophylaxis in high-risk angioedema patients.
Hereditary angioedema generates dominant revenue share, while acquired angioedema applications are expanding most quickly through improved diagnostic antibody testing.
End User:
Channel economics and patient training infrastructure determine margin capture and commercial model requirements across these four access points.
- Homecare:Self-administration platforms with nursing support and remote monitoring. Patient migration from hospital infusion centers in the United States and Western Europe accelerates enrollment, driven by preference for reduced treatment burden and flexible scheduling.
- Hospitals:Institutional procurement through centralized pharmacy and therapeutics committees. Integrated delivery networks in United States metropolitan markets consolidate purchasing power, displacing individual physician autonomy with exclusive distribution agreements.
- Specialty Clinics:Immunology and allergy-focused outpatient facilities.
- Research Institutions:Academic medical centers conducting clinical trials and mechanistic studies.
Hospital channels retain the largest volume position, with homecare gaining share fastest through device-integrated combination product launches.
Delivery Mode:
Administration route selection shapes device regulatory pathways, patient training requirements, and reimbursement coding complexity.
- Subcutaneous:Prefilled syringe and autoinjector platforms enabling self-injection without vascular access. Patient training programs at specialist centers in Germany and the United States report accelerating enrollment, compressing hospital infusion revenues while expanding addressable populations.
- Intravenous:Hospital-based infusion requiring vascular access and monitoring infrastructure. Legacy investments in infusion centers face utilization pressure as patients transition to home-based alternatives.
- Intramuscular:Alternative parenteral route for specific clinical scenarios.
- Oral:Experimental and non-standard administration approaches.
Intravenous delivery holds established volume leadership, with subcutaneous administration posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns in the United States diverge sharply from Germany's integrated insurance-physician networks, yet both anchor comparable patient volumes for C1-inhibitor therapies. Specialist immunology centers in these markets drive diagnosis-to-treatment velocity while reimbursement frameworks determine access breadth.
United States
FDA orphan drug exclusivity provisions accelerate trial timelines for novel formulations. Integrated delivery networks in metropolitan markets consolidate procurement under centralized pharmacy committees, displacing individual physician autonomy. Boston and New York specialist clusters anchor patient identification for hereditary angioedema protocols.
Germany
EMA orphan medicinal product designation streamlines approval pathways for plasma-derived and recombinant products. The country's statutory health insurance system negotiates centralized reimbursement rates with manufacturers. Munich and Hamburg immunology centers report accelerating enrollment in subcutaneous self-injection training programs.
Japan
PMDA accelerated approval pathways for rare disease therapies compress development timelines for C1-inhibitor candidates. The Ministry of Health, Labour and Welfare maintains orphan drug premium pricing provisions. Tokyo and Osaka specialist hospitals concentrate patient access for hereditary angioedema diagnosis.
United Kingdom
NICE technology appraisals determine NHS funding eligibility for C1-inhibitor prophylaxis versus acute treatment protocols. The UK Rare Diseases Framework prioritizes diagnostic pathway shortening for hereditary angioedema. London and Manchester tertiary centers coordinate national patient registries and outcomes monitoring.
Switzerland
Swissmedic streamlined review processes for orphan biologics align with EMA standards while maintaining independent national authorization. The country's compulsory health insurance system covers C1-inhibitor therapies with cost-sharing limits. Basel and Zurich university hospitals anchor clinical research participation for novel formulation trials.
Plasma Protease C1-Inhibitor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across plasma fractionation and recombinant manufacturing vectors. The market structure tilts toward consolidation among entities controlling plasma collection infrastructure or specialized bioreactor capabilities. Three archetypes dominate: integrated plasma collectors with fractionation depth, recombinant protein specialists with glycosylation expertise, and niche ultra-rare disease players with orphan drug positioning. Capacity expansion in subcutaneous delivery platforms and strategic partnerships for device integration represent the dominant competitive moves reshaping commercial infrastructure.
Within the plasma-derived tier, CSL Behring and Grifols exemplify integrated collectors with multi-continent fractionation networks. Takeda Pharmaceutical Company anchors the recombinant segment through specialized manufacturing capabilities. Pharming Group N.V. occupies a position among niche specialists targeting ultra-rare complement disorders beyond hereditary angioedema.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company |
| Pharming Group N.V. |
| KalVista Pharmaceuticals |
| BioCryst Pharmaceuticals |
| Sanquin |
| Grifols |
| Octapharma |
| ADMA Biologics |
| Others |
Value Network & Pricing Analysis
Plasma collection costs cascade through fractionation economics into three-tier pricing structure across premium, standard, and economy levels, with raw material security premiums widening spreads between plasma-derived concentrates and recombinant alternatives.
Pricing Analysis
Capacity additions in recombinant manufacturing are reshaping price floors for C1-inhibitor therapies as specialized bioreactor scale-up introduces competitive tension. Three-tier pricing structure across premium, standard, and economy levels separates orphan-designated formulations from biosimilar-ready products from regional lyophilized alternatives. Price differentiation hinges on FDA/EMA exclusivity status and cold chain infrastructure requirements. Pricing pressure stems from integrated delivery network consolidation in United States metropolitan markets, with hospital procurement committees extracting volume discounts that squeeze mid-tier suppliers.
Supply Chain Analysis
Direct-to-hospital channels handle institutional procurement for intravenous formulations, while specialty pharmacy distribution runs through device-integrated combination products for homecare self-injection. Plasma fractionation concentrates in the United States, Germany, and Australia, where CSL Behring and Grifols maintain captive collection infrastructure. Production draws from human plasma donations, recombinant cell lines, and glycosylation control reagents. Single-source vulnerability in plasma collection regions creates exposure during donor recruitment disruptions or regulatory inspection holds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Plasma Protease C1-Inhibitor Market represents a late-cycle quality story as patient migration toward subcutaneous home administration elevates convenience specifications above pure efficacy metrics.
For Market Incumbents: Lock in plasma collection network exclusivity through long-term donor center contracts and backward integration into regional fractionation capacity. Defend against recombinant substitution by accelerating subcutaneous formulation lifecycle management and securing device-integrated combination product approvals ahead of biosimilar entry. For New Entrants and Emerging Players: Launch via specialty pharmacy channels targeting acquired angioedema diagnosis gaps where diagnostic antibody testing expansion outpaces established therapy penetration. White-space exists in lyophilized formulations for Indian and Brazilian markets where cold chain fragmentation limits incumbent reach. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma fractionation expertise concentrates among aging technical workforces and limited bioreactor engineering talent pools. Viability over the coming decade favors targets with dual plasma-derived and recombinant manufacturing capabilities plus established European orphan drug positioning. Monitor FDA interchangeability guidance publication as inflection signal for competitive switching dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Delivery Platform Development | Device-integrated combination products capture patient preference shift toward home administration. |
| Plasma Collection Network Expansion | Multi-continent donor center density secures raw material continuity against regional supply shocks. |
| Orphan Drug Exclusivity Defense | EMA and FDA designation maintenance extends market protection against biosimilar erosion. |
| Lyophilized Formulation Investment | Ambient-stable products unlock addressable markets in cold chain-constrained geographies. |
| Specialty Clinic Partnership Program | Immunology center alliances accelerate diagnosis-to-treatment velocity and anchor reimbursement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plasma fractionation executives, regulatory affairs specialists, hospital pharmacy directors, and specialty infusion center administrators against secondary validation through FDA BLA filings, EMA MAA submissions, ClinicalTrials.gov records, and hospital procurement database extracts. Bottom-up patient population estimates and top-down revenue triangulation anchored segment-level outputs.
Segment-weighting across product type, application, end user, and delivery mode dimensions structured the analytical framework over the projection horizon. CAGRs derived from patient cohort expansion models, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated orphan drug exclusivity expiration schedules and subcutaneous formulation adoption velocity by geography.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biosimilar approval acceleration or plasma collection disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market