
 Polyclonal Antibodies Market | 2026-2036
Polyclonal Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Polyclonal Antibodies Market Analytics
ISO 13485 certification for in vitro diagnostic reagents is reorganizing competitive access across the polyclonal antibodies supply base, favoring manufacturers with documented quality management systems. Thermo Fisher Scientific Inc. leverages its vertically integrated serum sourcing and purification infrastructure to sustain cost advantages at scale. Abcam plc differentiates through recombinant validation overlays on traditional polyclonal catalogs, occupying a premium position in research antibody channels.
Polyclonal antibodies consist of heterogeneous immunoglobulin populations derived from multiple B-cell clones, typically raised in host animals such as rabbits, goats, or sheep, with specificity determined by the antigen immunization protocol and serum collection timing. These reagents serve as binding tools in diagnostic assays, therapeutic antivenoms, and research detection systems where epitope breadth and robust signal amplification outweigh batch-to-batch consistency requirements. Research antibodies command the largest volume position within product type segmentation, though therapeutic antibodies carry substantially higher per-unit value and margin concentration. Diagnostic antibodies face accelerating demand from contract research organizations running large-scale biomarker validation studies, while conjugated antibodies represent a fast-growing format as multiplexing protocols expand in immunohistochemistry workflows.
FDA oversight of antibody-based diagnostic components, coupled with EMA's In Vitro Diagnostic Regulation transition requirements, shapes product registration pathways and manufacturing documentation burdens across major supply destinations. ISO 17025 accreditation for analytical testing and WHO prequalification standards for diagnostic materials further constrain which producers can serve regulated clinical segments. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on antibody performance characterization metrics, as harmonization will determine which suppliers retain multi-jurisdictional market access without duplicative validation investments.
Market Dynamics
ISO 13485 certification requirements for in vitro diagnostic reagents are compressing supplier access and forcing documented quality management systems across the polyclonal antibodies supply base. This regulatory tightening favors manufacturers with captive serum sourcing and validated purification infrastructure.
Growth Catalysts
- NIH Funding Cycles:Sustained federal research budgets in the United States drive consistent procurement volumes from academic institutes running proteomics workflows.
- EMA In Vitro Diagnostic Regulation:The transition to IVDR standards across European member states is accelerating demand for prequalified antibody materials in clinical diagnostic segments.
- Multiplexing Protocols:Expansion of immunohistochemistry workflows requiring conjugated antibody formats is pulling volume through contract research organizations.
Market Restraints
- Serum Input Volatility:Fluctuations in host animal serum availability and pricing constrain margin predictability for rabbit-derived polyclonal production.
- Batch Consistency Limitations:Intrinsic heterogeneity of multi-clone immunoglobulin populations restricts adoption in therapeutic applications requiring reproducible dosing.
- Regulatory Documentation Burden:WHO prequalification standards for diagnostic materials impose validation timelines that exclude smaller producers from clinical segments.
Strategic Opportunities
- Recombinant Validation Overlays:Hybrid catalogs combining traditional polyclonal sera with recombinant monoclonal confirmation layers command premium positioning in research channels.
- Antivenom Therapeutics:Polyclonal hyperimmune sera for snakebite and envenomation treatment represent underpenetrated therapeutic applications with high per-unit value concentration.
- ISO 17025 Accreditation:Analytical testing laboratories with accredited antibody characterization capabilities capture biomarker validation contracts from pharmaceutical sponsors.
Industry Challenges
- Cross-Reactivity Characterization:Epitope mapping and off-target binding assessment require specialized mass spectrometry expertise that concentrates in a limited supplier pool.
- Host Animal Welfare Compliance:USDA and equivalent agricultural oversight bodies impose facility inspection cycles that extend production timelines for serum-dependent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyclonal Antibodies Market |
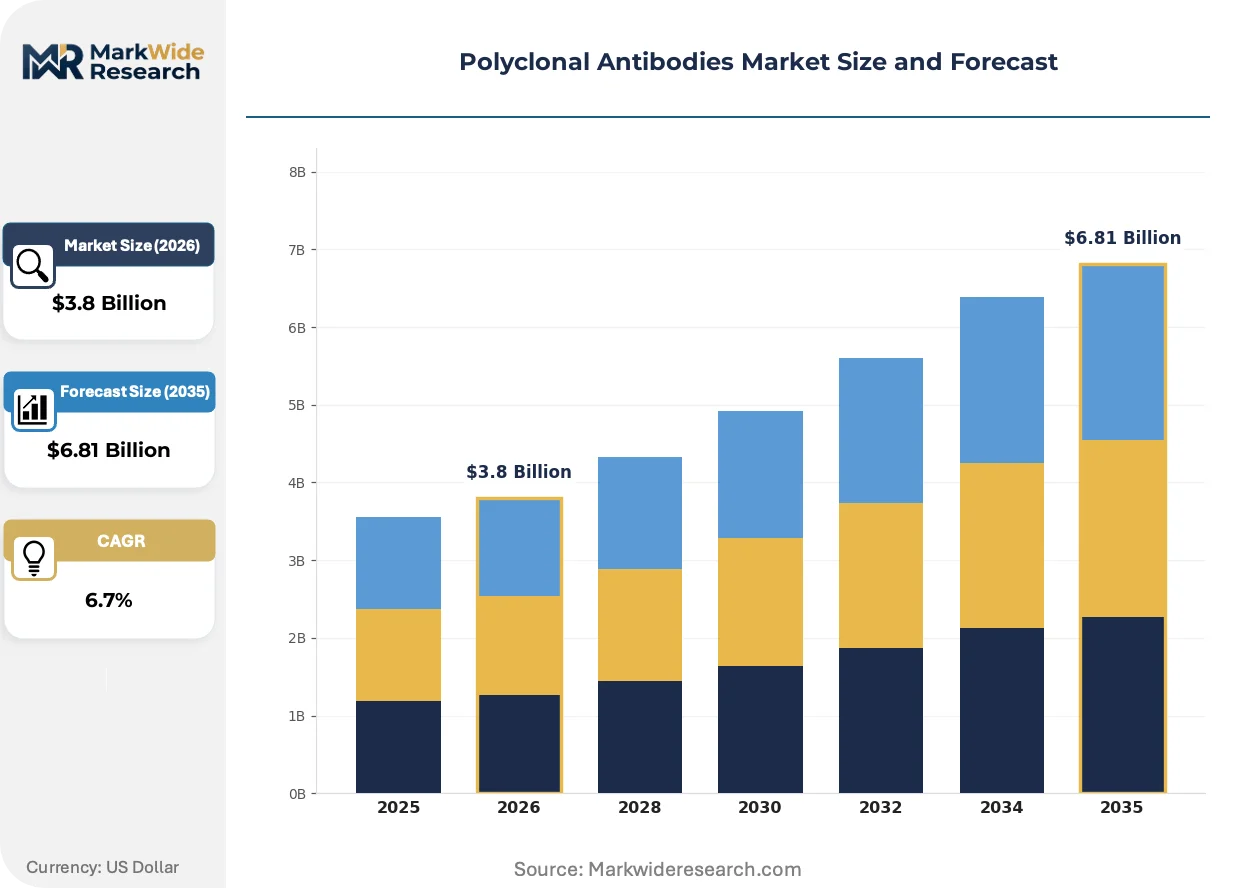
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Antibodies, Diagnostic Antibodies, Therapeutic Antibodies, Conjugated Antibodies End User: Academic Research Institutes, Hospitals, Pharmaceutical Companies, Contract Research Organizations Technology: Hybridoma Technology, Phage Display, Recombinant Technology, Immunization Technology Application: Diagnostics, Therapeutics, Research, Immunohistochemistry |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Abcam plc, Bio-Rad Laboratories Inc., F. Hoffmann-La Roche Ltd, GenScript Biotech Corporation, Cell Signaling Technology Inc., BioLegend Inc., ProteoGenix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyclonal Antibodies Market Evolving Landscape
Recombinant antibody technologies are fragmenting traditional polyclonal market positions while regulatory harmonization pressures reshape validation requirements across diagnostic supply chains. These forces are compressing the viable supplier base toward integrated quality-certified producers.
Affinity maturation platforms are decomposing the historical trade-off between polyclonal breadth and monoclonal specificity. Synthetic immunization protocols using DNA-based antigen delivery enable rabbit hosts to generate narrower but higher-affinity serum populations. Biopharma assay development groups are adopting these semi-synthetic polyclonals for biomarker panels requiring reduced cross-reactivity. The technology is decomposing the premium pricing power of traditional high-titer polyclonal catalogs.
FDA guidance on antibody-based diagnostic validation is tightening analytical performance benchmarks for suppliers seeking 510(k) clearance. The agency's evolving expectations for lot-to-lot consistency documentation are extending validation timelines for new antibody submissions. Diagnostic kit manufacturers serving the United States market are responding by consolidating supplier relationships toward ISO 13485-certified producers with established master file submissions.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in academic research channels. University systems and multi-site institutes are centralizing antibody sourcing through negotiated framework agreements with preferred distributors. This concentration is most visible in the United States, where NIH-funded consortia leverage collective purchasing power to extract volume discounts on research-grade reagents.
Polyclonal Antibodies Market Segmentation
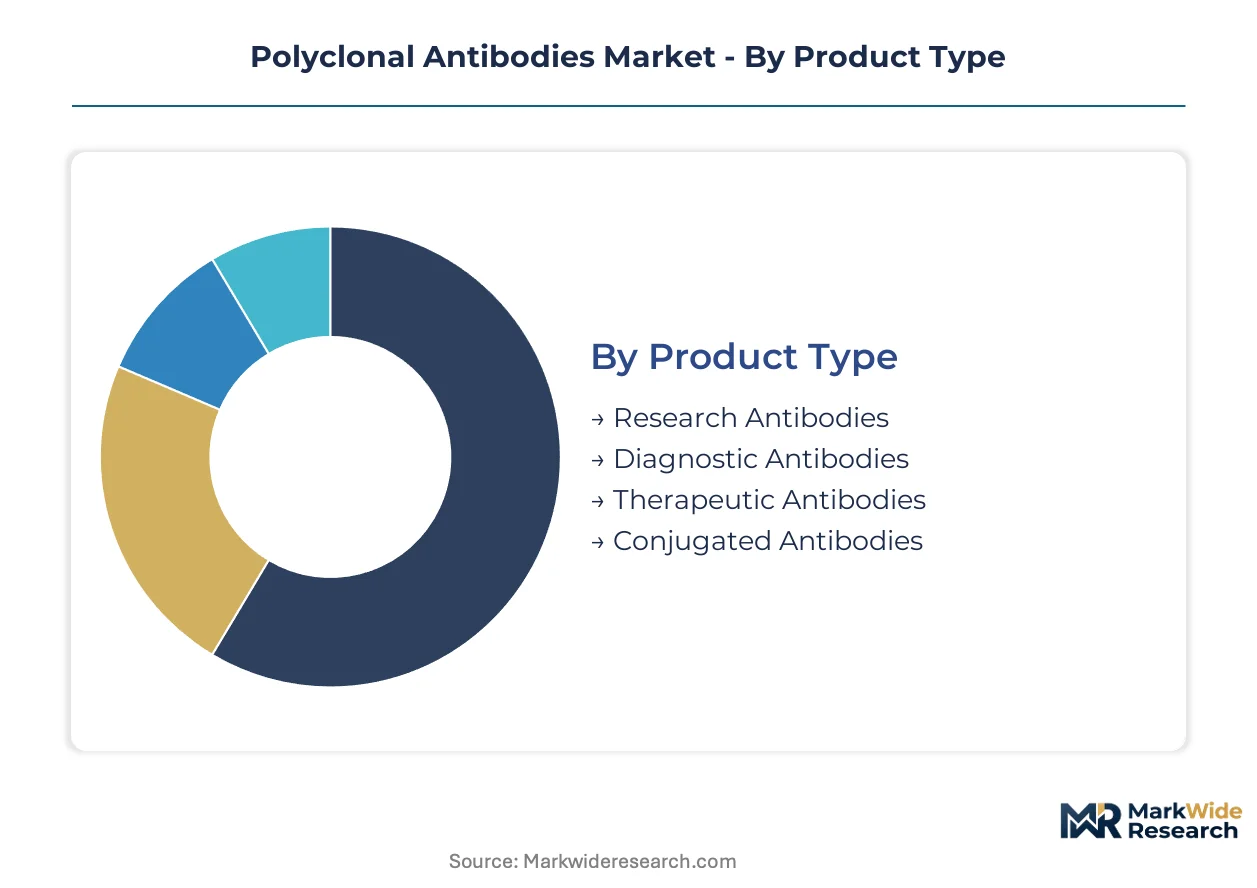
Segmentation in polyclonal antibodies reveals divergent quality thresholds across use cases. Regulatory stringency varies sharply between research-grade procurement and clinical diagnostic applications, reshaping supplier qualification requirements.
Product Type:
FDA and EMA diagnostic regulations stratify this category into certified and non-certified tiers, with ISO 13485 compliance determining market access depth.
- Research Antibodies:Heterogeneous immunoglobulin populations raised in rabbit, goat, or sheep hosts serve proteomics workflows and basic science detection. Academic institutes in the United States sustain volume through NIH funding cycles, though batch-to-batch variability limits clinical translation.
- Diagnostic Antibodies:Validated binding reagents for in vitro diagnostic kits face EMA IVDR transition requirements and FDA 510(k) analytical benchmarks. Contract research organizations running biomarker validation studies concentrate demand in ISO 17025-accredited supply channels.
- Therapeutic Antibodies:Hyperimmune sera for antivenom and envenomation treatment command premium per-unit economics.
- Conjugated Antibodies:Fluorophore- or enzyme-linked formats enable multiplexed immunohistochemistry protocols.
Research antibodies handle the majority of throughput; conjugated antibodies are expanding most quickly on share.
End User:
Procurement scale and quality documentation requirements separate institutional buyers, with federal funding mechanisms concentrating volume in specific customer types.
- Academic Research Institutes:University systems and multi-site consortia leverage NIH-funded framework agreements for research-grade reagent sourcing. Group purchasing organizations displace direct manufacturer relationships, extracting volume discounts through consolidated procurement.
- Contract Research Organizations:Biomarker validation service providers require ISO 17025-accredited antibody characterization for pharmaceutical sponsor contracts. Multiplexing protocol adoption drives conjugated format demand.
- Pharmaceutical Companies:Biopharma assay development groups seek semi-synthetic polyclonals with reduced cross-reactivity for biomarker panels.
- Hospitals:Clinical diagnostic laboratories source prequalified materials under WHO standards.
Academic institutes move the largest absolute volume; contract research organizations show the steepest expansion trajectory.
Technology:
Production methodology determines epitope breadth, affinity maturation potential, and regulatory documentation burden for master file submissions.
- Immunization Technology:Traditional host animal protocols using defined antigen immunization and serum collection timing generate heterogeneous multi-clone populations. USDA facility inspection cycles extend production timelines for serum-dependent manufacturers.
- Recombinant Technology:DNA-based antigen delivery enables synthetic immunization protocols producing narrower, higher-affinity serum populations. Affinity maturation platforms decompose the historical breadth-versus-specificity trade-off.
- Hybridoma Technology:Murine B-cell fusion methods generate monoclonal alternatives with batch consistency advantages.
- Phage Display:In vitro selection of antibody fragments bypasses host animal welfare compliance requirements.
Immunization technology retains dominant share; recombinant technology is climbing the fastest on adoption curves.
Application:
Functional use case dictates performance specifications, with diagnostic and therapeutic segments imposing stricter validation protocols than research applications.
- Research:Detection systems in proteomics and basic molecular biology tolerate batch variability in exchange for epitope breadth and signal amplification. Academic workflows in the United States, Germany, and Japan concentrate procurement.
- Diagnostics:In vitro diagnostic kit components face FDA lot-to-lot consistency documentation and EMA IVDR performance characterization metrics. Harmonization pressures between regulators determine multi-jurisdictional supplier viability.
- Therapeutics:Antivenom and hyperimmune sera applications require reproducible dosing profiles constrained by intrinsic polyclonal heterogeneity.
- Immunohistochemistry:Tissue staining protocols demand conjugated antibody formats for multiplexed visualization.
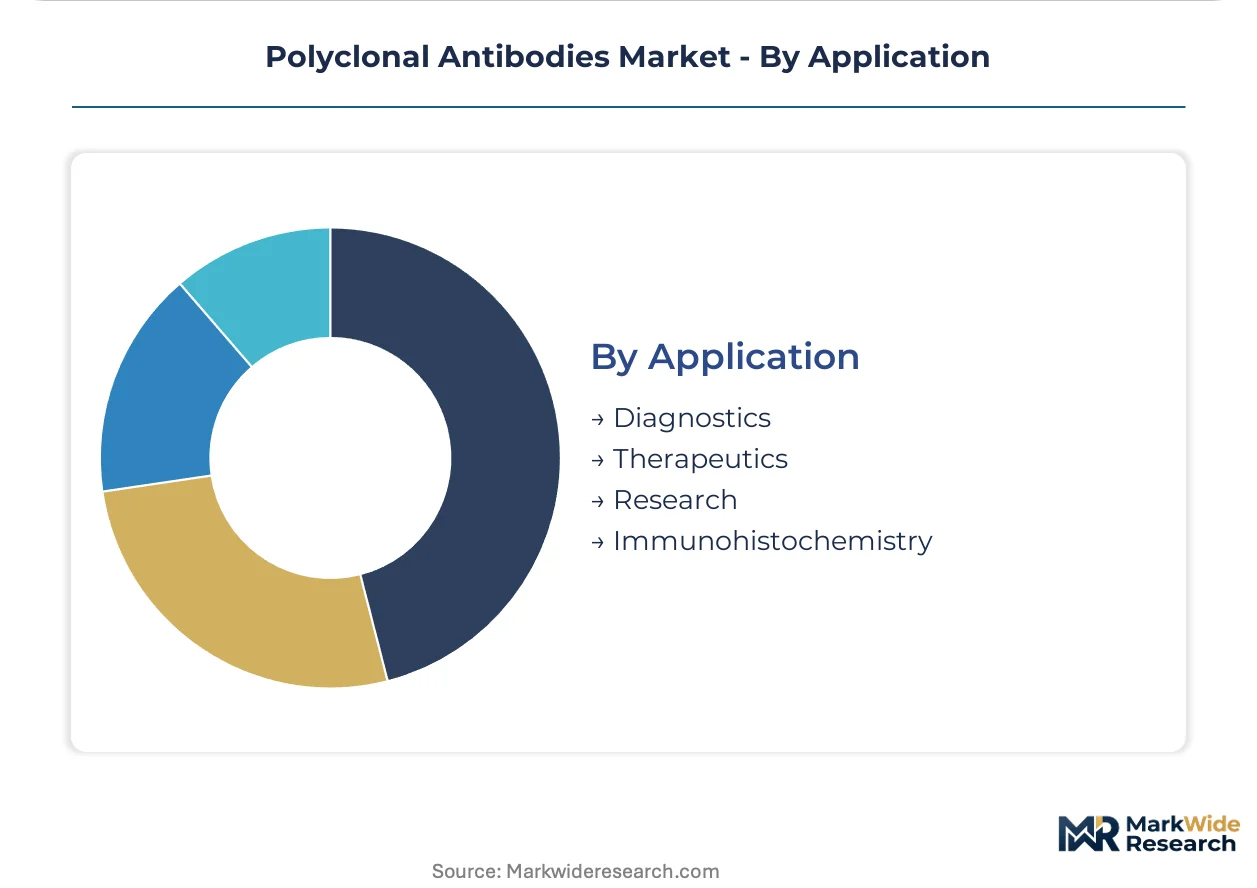
Research absorbs the greatest volume; diagnostics is gaining share fastest on regulatory-driven quality upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on antibody-based diagnostic validation and EMA's In Vitro Diagnostic Regulation transition are compressing supplier access across major markets. NIH funding cycles and biotech cluster density concentrate procurement in specific national jurisdictions.
United States
NIH funding cycles sustain consistent procurement volumes from academic institutes running proteomics workflows. FDA oversight of antibody-based diagnostic components shapes product registration pathways and manufacturing documentation burdens. The Greater Boston and San Francisco Bay Area biotech clusters anchor demand concentration for research-grade reagents.
Germany
EMA IVDR transition requirements accelerate demand for prequalified antibody materials in clinical diagnostic segments. The country's national pharmaceutical regulator enforces strict quality management system documentation for in vitro diagnostic reagents. The Rhine-Main and Munich biotech corridors concentrate contract research organization activity and biomarker validation studies.
China
Domestic biopharma assay development groups seek semi-synthetic polyclonals with reduced cross-reactivity for biomarker panels. NMPA oversight of diagnostic kit components extends validation timelines for new antibody submissions. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters host expanding proteomics infrastructure and research antibody procurement.
United Kingdom
Academic research institutes leverage framework agreements for consolidated antibody sourcing through group purchasing organizations. MHRA alignment with EMA IVDR standards constrains which producers can serve regulated clinical segments. The Cambridge-Oxford-London golden triangle concentrates life science research volume and detection reagent demand.
Japan
PMDA expectations for lot-to-lot consistency documentation favor ISO 13485-certified producers with established quality management systems. METI-supported biotech initiatives expand multiplexing protocol adoption in immunohistochemistry workflows. The Kanto region around Tokyo anchors pharmaceutical sponsor contracts and biomarker validation service demand.
Polyclonal Antibodies Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with captive serum sourcing infrastructure. The supply base compresses toward integrated quality-certified producers as regulatory documentation burdens intensify. Two strategic archetypes dominate: vertically integrated serum-to-antibody manufacturers and recombinant validation overlay specialists. Competitive moves concentrate on ISO 13485 certification acquisition and master file submission consolidation.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions anchored by scale advantages in purification infrastructure and global distribution networks. Abcam plc exemplifies the premium research-channel archetype through recombinant validation overlays on traditional polyclonal catalogs. These three entities represent the competitive poles around which mid-cap specialists and regional serum-dependent manufacturers organize their market access strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Abcam plc |
| Bio-Rad Laboratories Inc. |
| F. Hoffmann-La Roche Ltd |
| GenScript Biotech Corporation |
| Cell Signaling Technology Inc. |
| BioLegend Inc. |
| ProteoGenix |
| Others |
Value Network & Pricing Analysis
Synthetic immunization protocols replacing traditional host animal serum collection are redrawing supply geography toward recombinant-capable facilities while compressing pricing power for legacy polyclonal producers dependent on USDA-inspected livestock operations.
Pricing Analysis
Certification level creates the primary spread between research-grade and clinical-diagnostic tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 compliance status, with FDA-grade antibodies commanding substantial premiums over catalog research reagents. Cost compression in standard-tier rabbit-derived production is intensifying because serum input volatility constrains margin predictability. Academic research institutes demonstrate highest price sensitivity through consolidated group purchasing organization negotiations, while pharmaceutical assay development groups show lowest sensitivity due to biomarker validation requirements.
Supply Chain Analysis
Strategic stockpiling of host animal serum dominates inventory strategy among certified manufacturers seeking buffer against USDA facility inspection cycle disruptions. Supply concentrates in the United States, Germany, and China, with captive serum sourcing in USDA-inspected facilities anchoring North American production. Raw material dependencies center on rabbit, goat, and sheep serum, fluorophore conjugation chemistries, and affinity purification resins. Single-source vulnerability in high-titer rabbit serum collections from specific pathogen-free colonies creates concentration risk. Distribution runs through authorized distributors serving academic consortia and direct manufacturer relationships with diagnostic kit producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA IVDR transition and FDA diagnostic validation tightening constitute a dual regulatory inflection compressing viable supplier bases toward quality-certified producers with documented master file submissions.
For Market Incumbents: Consolidate supplier relationships through ISO 13485 certification acquisition and master file submission consolidation to defend against recombinant validation overlay specialists eroding premium positioning. Deepen backward integration into captive serum sourcing infrastructure to offset serum input volatility threatening margin predictability in rabbit-derived production. For New Entrants and Emerging Players: Lead with antivenom therapeutics as the most penetrable therapeutic application, exploiting underpenetrated hyperimmune sera demand with high per-unit value concentration. Target ISO 17025 accreditation for analytical testing capabilities to capture biomarker validation contracts from pharmaceutical sponsors seeking accredited antibody characterization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional serum-dependent manufacturers lacking ISO 13485 certification but possessing validated purification infrastructure suitable for quality system overlay. Long-term viability favors producers with recombinant technology capabilities and multi-jurisdictional regulatory submissions. Watch EMA-FDA harmonization progress on antibody performance characterization metrics as the signal indicating which suppliers retain cross-border market access without duplicative validation investments.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Unlocks FDA 510(k) diagnostic component pathways and EMA IVDR market access for clinical-tier supply. |
| Recombinant Validation Overlay Development | Commands premium positioning in research channels by combining polyclonal breadth with monoclonal confirmation layers. |
| Captive Serum Sourcing Infrastructure | Insulates margin predictability from USDA facility inspection cycles and host animal welfare compliance extensions. |
| Antivenom Therapeutic Pipeline Expansion | Captures high per-unit value concentration in underpenetrated envenomation treatment applications. |
| ISO 17025 Accreditation Investment | Enables biomarker validation contract capture from pharmaceutical sponsors requiring accredited analytical testing. |
Research Methodology
Cross-validation between primary interviews with serum production facility managers and secondary analysis of FDA 510(k) submission databases anchors the qualitative findings on regulatory pathway requirements. Conversations with diagnostic kit manufacturers, contract research organization procurement leads, academic institute purchasing committee directors, and biopharma assay development heads combined with EMA IVDR guidance documents, NIH funding disbursement records, USDA facility inspection reports, and ISO certification registries. Bottom-up segment sizing triangulates against top-down market reconstruction.
Sensitivity analysis on serum input cost trajectories and regulatory harmonization timelines informs projection robustness across the modeling period. Segmentation dimensions include product type, end user category, production technology, and application function. CAGRs derive from volume-weighted segment trajectories incorporating NIH funding cycle patterns, EMA IVDR transition pace, and multiplexing protocol adoption curves in immunohistochemistry workflows.
The analysis sits within stated boundaries; outcomes outside sustained federal research budgets or accelerated regulatory convergence would require recalibration. Forecasts reflect documented assumptions on certification penetration rates and host animal serum availability. Revision becomes warranted when EMA-FDA harmonization crosses implementation thresholds or synthetic immunization protocols achieve cost parity with traditional serum collection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Tetracycline Market