
 Global Pea Protein Ingredients Market | 2026-2036
Global Pea Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pea Protein Ingredients Market Foresight
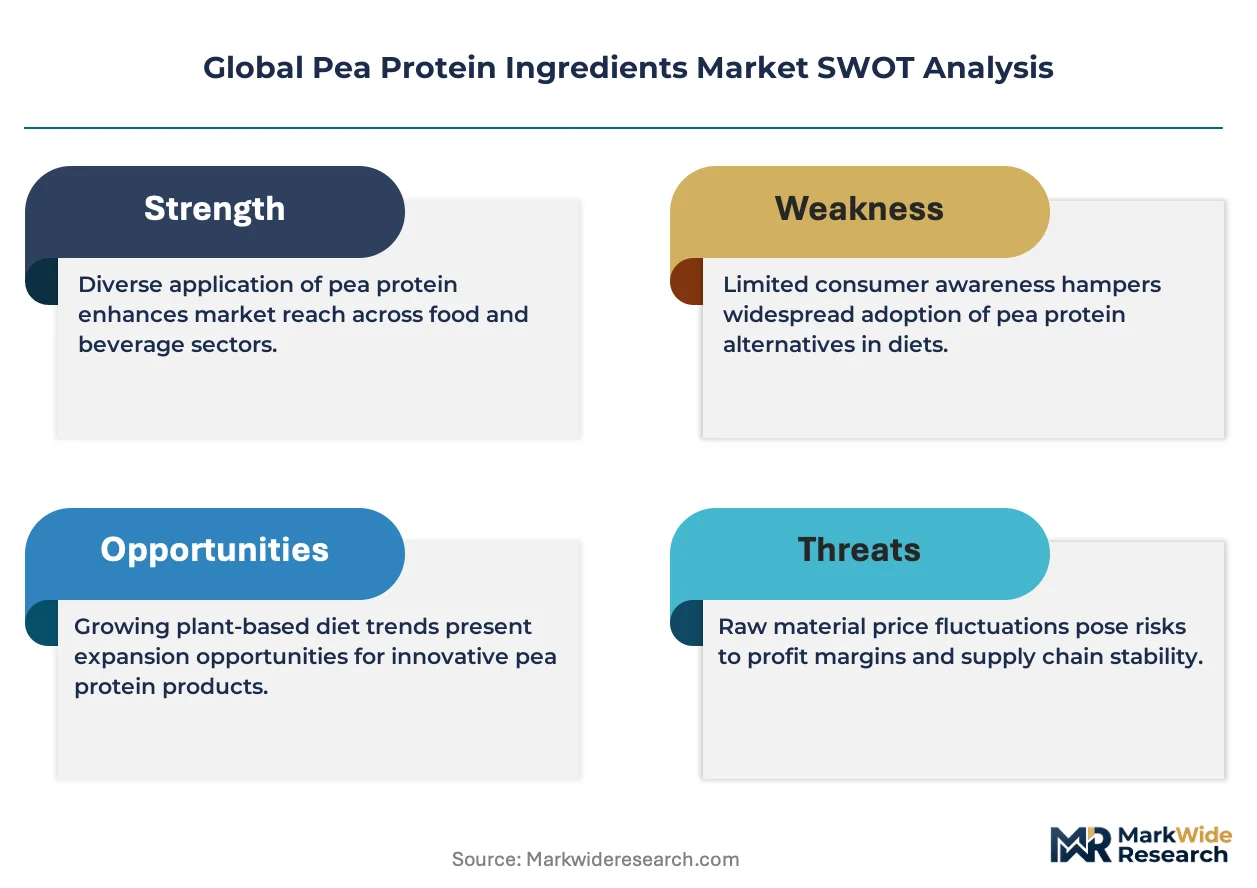
Subscription-based formulation services is expanding how ingredient suppliers monetize pea protein, shifting revenue from tonnage to recurring technical partnerships. Roquette Frères leverages its wet-fractionation expertise to anchor supply contracts with European dairy-alternative brands. Cargill competes through backward integration into North American yellow pea sourcing, controlling origination costs. Puris Proteins specializes in non-GMO and organic-certified isolates, differentiating on clean-label credentials that command premium positioning.
Pea protein ingredients are dry-milled or wet-fractionated extracts from Pisum sativum containing 80-90% protein in isolate form, functionalized through pH-shift precipitation to achieve solubility and emulsification properties required in meat analogues and beverage applications. Protein isolate commands the deepest margin pool due to extraction complexity and sports-nutrition pull, while textured formats lead volume through meat-substitute compounding. Bakery applications represent the fastest-growing demand channel as laminated dough and pan-bread formulations replace gluten with pea protein for structure and browning.
EFSA novel-food evaluations and FDA GRAS self-affirmation pathways shape market access timelines and label claims for pea protein entrants. The EU Green Deal protein-strategy targets and REACH chemical-safety registration requirements together redirect R&D investment toward domestically sourced legume processing. Stakeholders must monitor how carbon-accounting standards for Scope 3 emissions reshape supplier qualification criteria before committing to long-term offtake agreements.
Market Dynamics
EU Green Deal protein-diversification mandates are forcing ingredient substitution away from soy and dairy, while wet-fractionation capacity concentrates among European processors with captive yellow-pea supply chains.
Growth Catalysts
- EU Green Deal protein-strategy targets:Mandatory diversification away from imported soy creates domestic demand pull for Pisum sativum isolates in meat-analogue and dairy-alternative formulations.
- Sports-nutrition formulation briefs:Performance brands now specify pea protein isolate for amino-acid profiles and digestibility scores, replacing whey in premium-positioned powders and ready-to-drink beverages.
- German bakery reformulation:Laminated dough and pan-bread applications replace gluten with pea protein for structure and browning, advancing faster than other European markets due to retailer clean-label commitments.
Market Restraints
- Yellow-pea origination cost volatility:North American crop yields and rail-freight rates transmit directly into isolate input costs, compressing margin pools for non-integrated processors.
- EFSA novel-food evaluation timelines:Extended safety-assessment durations delay market access for new fractionation formats and modified-protein entrants seeking EU-wide approval.
- Soy protein isolate substitution threat:Established supply chains and lower unit economics in Asian-origin soy concentrate retain cost-sensitive meat-extender applications.
Strategic Opportunities
- Carbon-accounting Scope 3 qualification:Supplier emissions-verification protocols create first-mover advantage for processors with cradle-to-gate transparency in German and French dairy-alternative supply chains.
- Non-GMO and organic-certified isolate premiums:Clean-label credentialing commands price stratification in US natural-channel sports nutrition and European pharmacy-positioned medical foods.
- Subscription-based formulation services:Technical partnership models shift revenue from commodity tonnage to recurring R&D collaboration with emerging plant-based meat brands.
Industry Challenges
- Wet-fractionation capex intensity:pH-shift precipitation and membrane-filtration equipment requires substantial capital deployment, limiting entrant scale and consolidating capacity among established processors.
- REACH chemical-safety registration complexity:Novel extraction solvents and functionalization additives face extended toxicological review, delaying process-innovation deployment in EU manufacturing.
- Formulation-scientist talent scarcity:Protein-functionality expertise spanning emulsification, solubility, and thermal-gelation properties concentrates among legacy dairy and soy technologists, creating recruitment friction for pea-specialist roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pea Protein Ingredients Market |
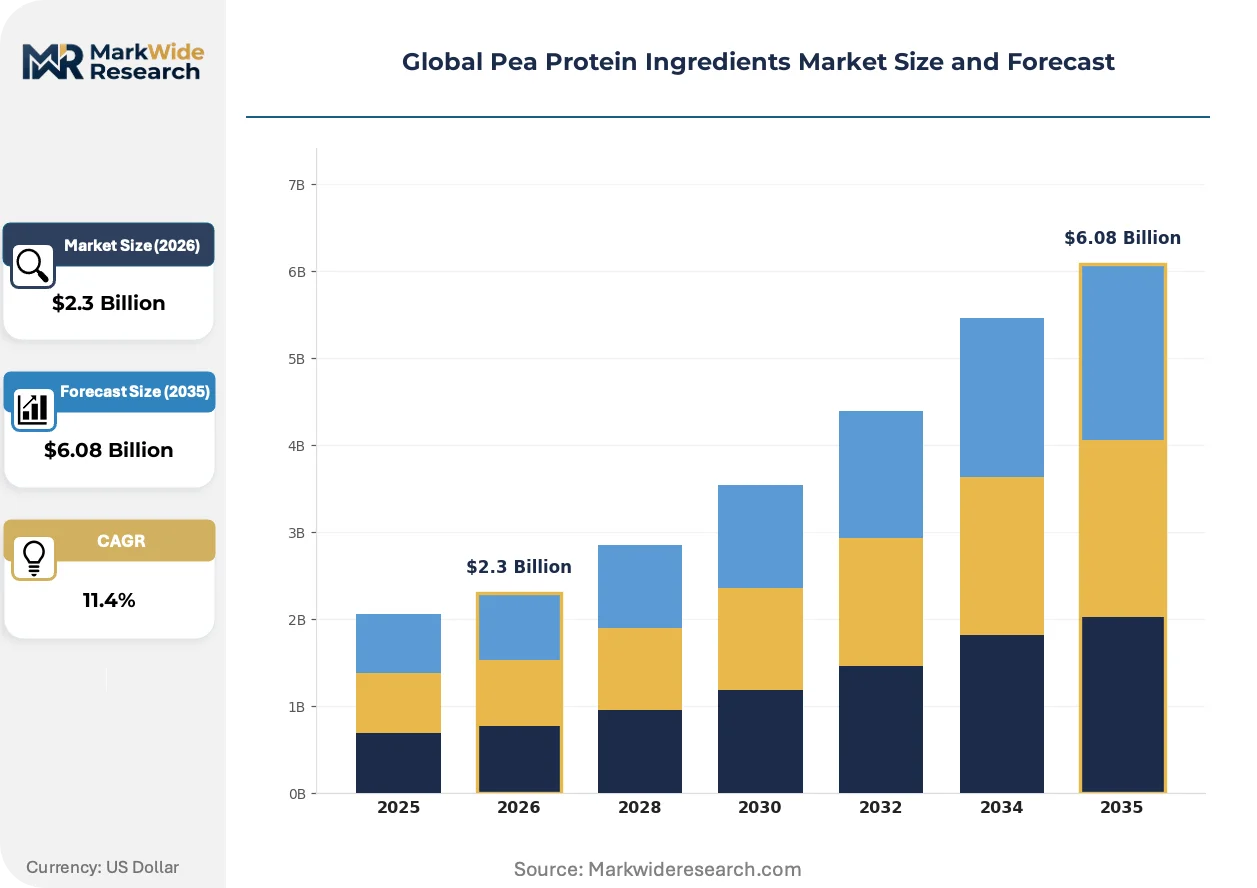
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $6.08 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Hydrolyzed Application: Sports Nutrition, Bakery, Dairy Alternatives, Meat Substitutes, Nutritional Supplements End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers, Personal Care Firms Packaging Type: Bag, Drum, Bulk, Sachet |
| Companies Covered | Roquette Frères, Cargill, Ingredion, Archer Daniels Midland Company, DuPont de Nemours, Puris Proteins, Burcon NutraScience Corporation, Nutri-Pea, The Scoular Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pea Protein Ingredients Market Shifts & Advancements
Fractionation technology convergence with precision-fermentation capabilities is restructuring how functional proteins reach formulation benches, while regulatory carbon-accounting frameworks reshape supplier-qualification protocols.
Fermentation-derived flavor-masking technology is integrating with conventional wet-fractionation lines to neutralize pea protein's characteristic grassy and beany off-notes. Sports-nutrition brands in Germany and the Netherlands are adopting these co-processed isolates at accelerated procurement cycles. The structural consequence is compressing the historical 18-24 month formulation-validation timeline for new protein entrants.
REACH chemical-safety registration requirements are tightening scrutiny of extraction solvents and processing aids in EU-based fractionation. Industrial consequence includes redirected R&D investment toward aqueous-mechanical separation methods that eliminate chemical inputs. German and French dairy-alternative manufacturers are responding by qualifying suppliers with pre-validated solvent-free process chains.
Buyer procurement patterns are consolidating around long-term offtake agreements with embedded technical-service provisions. Emerging plant-based meat brands in North America are displacing spot-market purchasing with multi-year supply contracts that lock capacity and secure formulation support. This behavior is most visible in California and Pacific Northwest clusters where venture-backed food-technology companies concentrate manufacturing partnerships.
Global Pea Protein Ingredients Market Segmentation
Pea protein ingredient specifications diverge sharply across extraction methods and functional requirements. Formulation scientists select grades based on solubility thresholds, emulsion stability, and thermal gelation properties demanded by end-use applications.
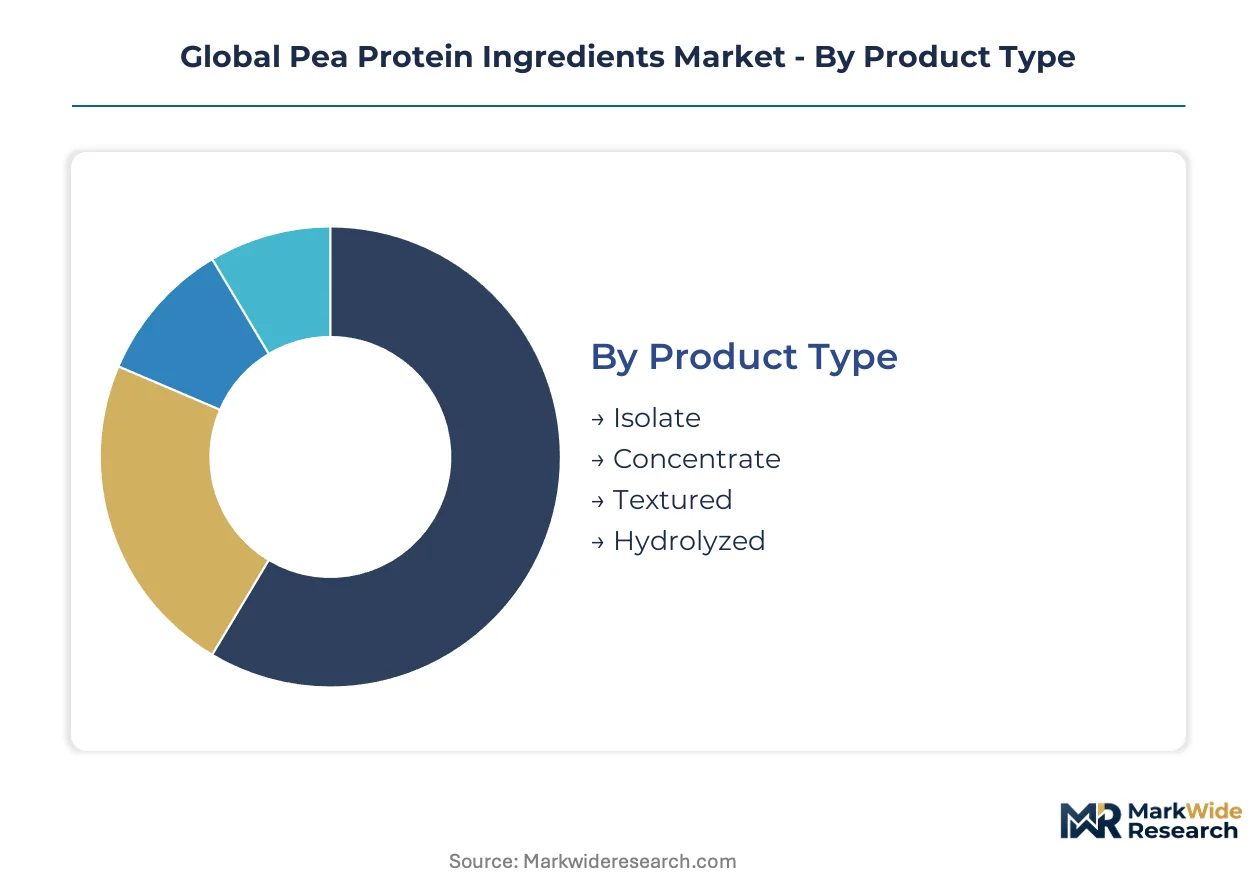
Product Type:
Standardization dominates isolate and concentrate grades, while textured and hydrolyzed formats require customization for specific mouthfeel and digestibility targets.
- Isolate:Dry-milled or wet-fractionated extracts containing 80-90% protein, functionalized through pH-shift precipitation for solubility and emulsification. Sports nutrition brands in Germany and the Netherlands specify this grade for amino-acid completeness and digestibility scores, displacing whey in premium-positioned powders.
- Concentrate:Lower-purity extracts retaining more starch and fiber, typically 60-75% protein content. Cost-sensitive meat-extender applications in North American processed foods rely on concentrate for partial protein fortification where full isolate functionality is unnecessary.
- Textured:Extruded protein with fibrous structure mimicking meat bite and chew. Plant-based meat brands specify customized particle sizes and hydration ratios for specific analogue formats.
- Hydrolyzed:Enzymatically cleaved peptides for enhanced solubility and reduced allergenic potential. Nutraceutical applications targeting rapid absorption require degree-of-hydrolysis specifications.
Most installed capacity flows through isolate extraction lines. Expansion is steepest in textured formats for meat-analogue compounding.
Application:
Volume concentration sits with legacy categories, while margin capture shifts toward emerging formats with technical barriers to substitution.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and recovery formulations specifying isolate for leucine content and PDCAAS scores. Formulation briefs now mandate pea protein explicitly, with German brands adopting fermentation-derived flavor-masking co-processes at accelerated procurement cycles.
- Bakery:Laminated dough and pan-bread applications replacing gluten with pea protein for structure, browning, and moisture retention. German retailer clean-label commitments advance reformulation faster than other European markets.
- Dairy Alternatives:Milk, yogurt, and cheese analogues requiring emulsion stability and neutral flavor profiles. EFSA novel-food evaluations shape acceptable protein grades for EU-wide distribution.
- Meat Substitutes:Burger patties, sausages, and whole-muscle analogues demanding thermal gelation and fibrous texture. Long-term offtake agreements with embedded technical service provisions dominate procurement.
- Nutritional Supplements:Medical foods, infant nutrition, and senior nutrition targeting specific amino-acid profiles. Pharmacy-positioned channels in France and Switzerland command organic-certified premiums.
Sports nutrition generates the deepest margin pools. Bakery applications are climbing the fastest as laminated dough formulations proliferate.
End User:
Procurement sophistication varies from commodity spot purchasing to multi-year partnerships with embedded R&D collaboration.
- Food & Beverage Manufacturers:Large-scale processors of meat analogues, dairy alternatives, and baked goods driving volume demand. California and Pacific Northwest venture-backed food-technology companies concentrate manufacturing partnerships with qualification protocols emphasizing cradle-to-gate carbon transparency.
- Nutraceutical Companies:Supplement brands and contract manufacturers specifying isolate grades for amino-acid fortification. Clean-label credentialing commands price stratification in US natural channels.
- Animal Feed Producers:Pet food and livestock feed applications utilizing lower-grade concentrates for protein supplementation.
- Personal Care Firms:Cosmetic and dermatological formulations exploiting film-forming and humectant properties of hydrolyzed peptides.
Food and beverage manufacturers lock the majority of contracted capacity. Nutraceutical procurement is gaining share fastest through premium-positioned isolate specifications.
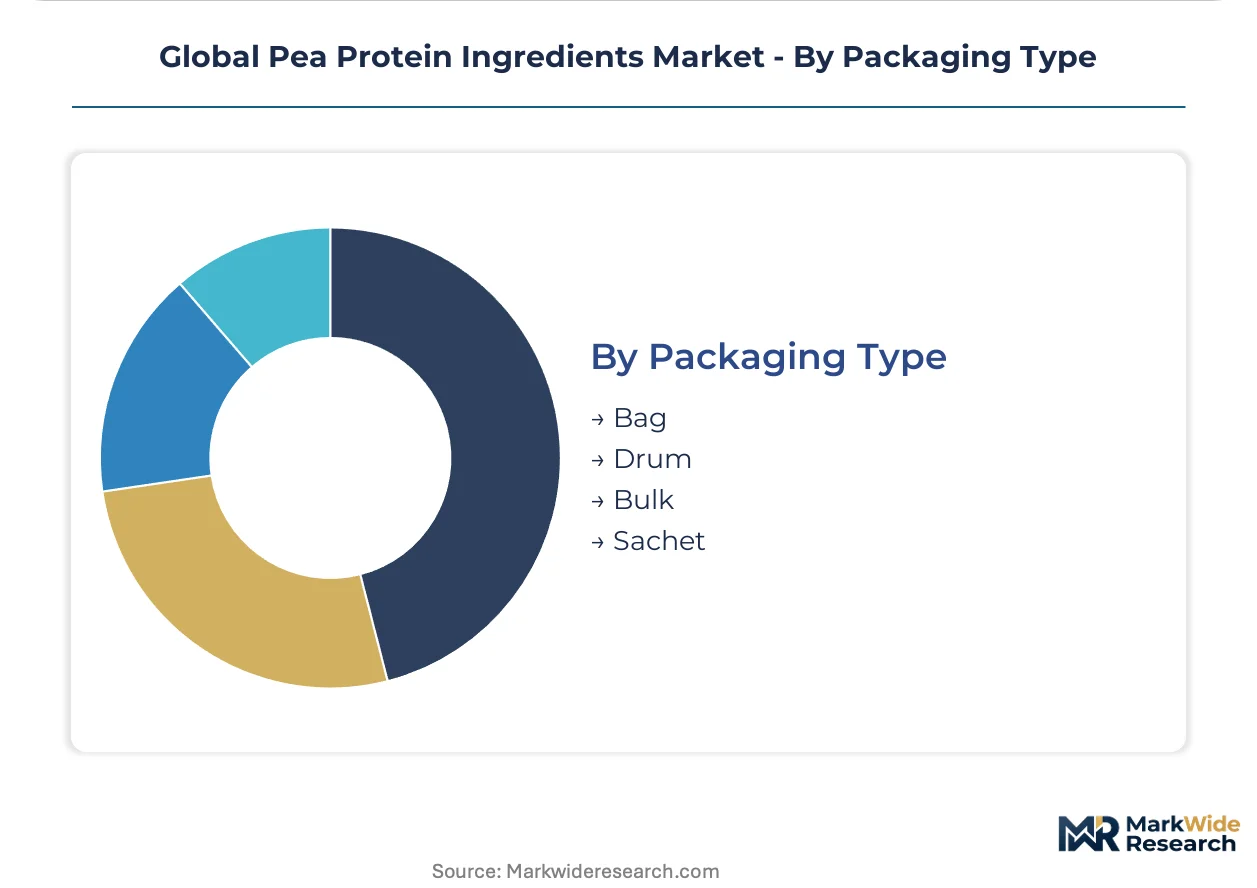
Packaging Type:
Scale economies and handling requirements segment packaging selection across integrated processors and distributed formulators.
- Bag:Standard 20-25kg multi-wall paper or polyethylene bags for mid-volume food manufacturing. Roquette Frères and similar European processors supply German dairy-alternative brands through this format.
- Drum:Fiber or steel drums with liner systems for moisture-sensitive isolates. Nutraceutical and personal care applications requiring contamination control specify drum packaging.
- Bulk:Tanker trucks and flexible intermediate bulk containers for high-volume meat-substitute compounding. Cargill's backward integration into North American yellow pea sourcing supports bulk logistics.
- Sachet:Single-serve and sample formats for sports nutrition direct-to-consumer channels. Puris Proteins leverages non-GMO and organic certifications for premium sachet positioning.
Most tonnage moves through bulk handling systems. Sachet formats are expanding most quickly through direct-to-consumer sports nutrition channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's bakery reformulation outpaces US sports-nutrition procurement velocity, while Canadian yellow-pea origination supplies North American wet-fractionation capacity.
Germany
Retailer clean-label commitments accelerate laminated dough and pan-bread applications replacing gluten with pea protein for structure and browning. EU Green Deal protein-diversification mandates create domestic demand pull for Pisum sativum isolates. The Cologne-Düsseldorf corridor anchors European dairy-alternative formulation partnerships with embedded technical-service provisions.
United States
Venture-backed food-technology companies in California and the Pacific Northwest lock multi-year offtake agreements displacing spot-market purchasing. FDA GRAS self-affirmation pathways shape label claims and market-access timelines for novel fractionation formats. Chicago and Minneapolis-St. Paul processing clusters concentrate backward-integrated yellow-pea origination infrastructure.
France
Pharmacy-positioned medical foods command organic-certified isolate premiums in senior and infant nutrition segments. EFSA novel-food evaluations filter acceptable protein grades for EU-wide distribution. The Lyon-Grenoble axis hosts precision-fermentation integration with conventional wet-fractionation lines for flavor-masked isolates.
Canada
Prairie provinces anchor North American yellow-pea origination with rail-freight connectivity to wet-fractionation capacity. Carbon-accounting Scope 3 protocols reshape supplier qualification criteria for German and French dairy-alternative manufacturers. Manitoba and Saskatchewan crop yields transmit directly into isolate input-cost structures.
Netherlands
Sports-nutrition brands adopt fermentation-derived flavor-masking co-processes at accelerated procurement cycles. REACH chemical-safety registration requirements redirect R&D toward aqueous-mechanical separation methods eliminating chemical inputs. The Rotterdam-Antwerp port cluster handles bulk logistics for meat-substitute compounding operations.
Global Pea Protein Ingredients Market Competitive Landscape
Top-tier vendors anchor wet-fractionation capacity with captive supply chains, while mid-scale specialists occupy clean-label certification niches. European processors leverage pH-shift precipitation expertise to secure long-term dairy-alternative contracts. North American players compete through backward integration into yellow-pea origination. Strategic moves concentrate on M&A for capacity consolidation and geographic expansion into German bakery-reformulation supply chains.
Within the premium-isolate tier, Roquette Frères and Puris Proteins exemplify divergent positioning strategies. Roquette Frères anchors European wet-fractionation capacity with embedded technical-service partnerships. Puris Proteins occupies the non-GMO and organic-certified credentialing space commanding price stratification in US natural channels. Cargill represents the backward-integrated archetype controlling North American yellow-pea origination costs.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill |
| Ingredion |
| Archer Daniels Midland Company |
| DuPont de Nemours |
| Puris Proteins |
| Burcon NutraScience Corporation |
| Nutri-Pea |
| The Scoular Company |
| Others |
Supply & Pricing Matrix
EU Green Deal protein-diversification mandates gate qualified supply access and premium-tier pricing power by requiring cradle-to-gate carbon transparency for German and French dairy-alternative procurement. Buyers lacking verified Scope 3 documentation face exclusion from formulation partnerships, while certified isolates command stratified premiums in pharmacy-positioned medical foods.
Pricing Analysis
Capacity additions in the Netherlands and France are reshaping price floors for isolate grades as wet-fractionation equipment deployment accelerates. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified isolates for nutraceutical channels from commodity concentrate grades for meat extenders. Cost compression in standard-tier isolates is intensifying because North American yellow-pea origination volatility transmits directly into input costs. Food and beverage manufacturers exhibit highest price sensitivity through spot-market purchasing patterns, while sports-nutrition brands demonstrate lowest sensitivity due to leucine-content specifications.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie provinces anchoring North American yellow-pea origination for wet-fractionation feedstock. Germany, France, and the Netherlands concentrate European processing capacity with pH-shift precipitation expertise. Raw material dependencies draw from yellow-pea crop yields, rail-freight capacity, and membrane-filtration equipment availability. Tariff exposure on Asian-origin soy concentrate creates substitution pull for domestically processed Pisum sativum isolates. Distribution runs through Rotterdam-Antwerp bulk logistics for meat-substitute compounding and Cologne-Düsseldorf technical-service partnerships for dairy-alternative formulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pea Protein Ingredients Market functions as a stable compounder anchored by EU regulatory mandates that structurally displace imported soy with domestic legume processing. Protein-diversification targets create durable demand pull independent of cyclical consumer trends.
For Market Incumbents: Cement wet-fractionation capacity advantages through captive yellow-pea supply chain partnerships in Manitoba and Saskatchewan. Lock multi-year offtake agreements with embedded technical-service provisions before emerging plant-based meat brands consolidate supplier relationships. Precision-fermentation integration for flavor-masking co-processes represents the priority R&D frontier. For New Entrants and Emerging Players: Bakery reformulation specialists in Germany represent an underserved buyer archetype demanding solvent-free process validation for laminated dough applications. Target aqueous-mechanical separation methods that eliminate REACH-registered chemical inputs, qualifying for retailer clean-label commitments faster than established processors. Position through subscription-based formulation services that shift revenue from commodity tonnage to recurring technical partnerships. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale organic-certified isolate processors because clean-label credentialing commands persistent price stratification in US natural channels and European pharmacy-positioned medical foods. The 5-to-10-year viability window favors targets with pre-validated carbon-accounting protocols. Watch for EFSA novel-food approval accelerations as inflection indicators for modified-protein entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow-Pea Origination | Cargill's prairie supply chain control insulates margin pools from rail-freight volatility. |
| Precision-Fermentation Co-Processing Deployment | Roquette Frères' Lyon-Grenoble integration compresses 18-month formulation-validation timelines. |
| Organic-Certified Capacity Expansion | Puris Proteins' non-GMO positioning captures pharmacy-channel premiums in Switzerland. |
| Long-Term Offtake Agreement Structuring | Venture-backed California brands displace spot purchasing with embedded technical-service contracts. |
| REACH-Compliant Solvent-Free Process Validation | German dairy-alternative manufacturers qualify suppliers eliminating chemical-safety registration delays. |
Research Methodology
Direct dialogue with wet-fractionation plant managers, formulation scientists at dairy-alternative brands, procurement leads at sports-nutrition companies, and regulatory affairs specialists at EFSA novel-food applicants grounded qualitative assessment. Secondary validation drew from EU Green Deal policy documentation, EFSA safety evaluation registers, REACH chemical-safety filings, and North American agricultural yield databases. Bottom-up capacity modeling triangulated against top-down protein-ingredient demand projections.
Segment-level value outputs across the analysis window reflect isolate, concentrate, textured, and hydrolyzed grade tiers intersecting with sports nutrition, bakery, dairy alternatives, meat substitutes, and nutraceutical applications. Modeled dimensions included extraction-method technology, certification status, and regional production-cluster dynamics. CAGRs derived from installed capacity expansion schedules, formulation-brief adoption velocities, and regulatory approval timeline assumptions. Crop-yield volatility and carbon-accounting protocol adoption curves served as key forecast inputs.
Underlying measurement precision varies by segment; sports-nutrition isolate specifications carry tighter precision than commodity concentrate grades for animal feed. Forecasts reflect assumptions about EU protein-strategy target enforcement, EFSA evaluation duration stability, and yellow-pea origination cost transmission. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Textural Food Ingredients Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Fermentation Ingredient Market
Ingredients
Non-GMO Soya Market
Ingredients
White Wheat Malt Market
Ingredients
Sesame Seed Extract Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Specialty Flours Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
North America Gelatin Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Centella Asiatica Extract Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Italy Soy Protein Market