
 Rice Bran Oil Market | 2026-2036
Rice Bran Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Bran Oil Market Intelligence
Palm oil is restructuring edible oil economics across South and Southeast Asia as food service chains and packaged food makers pivot toward rice bran oil for high-heat frying. Ricela Group leverages integrated solvent extraction and refining infrastructure across Punjab and Haryana to command supply security. Marico Ltd. sustains brand dominance in India's branded edible oil segment through its Saffola portfolio, which competes on heart-health positioning against commodity oils. Adani Wilmar Ltd. anchors volume throughput via its extensive procurement network, while Tsuno Group Co. Ltd. differentiates through gamma-oryzanol-enriched formulations for the Japanese functional foods market.
Rice bran oil is extracted from the outer bran layer of Oryza sativa, yielding a golden oil with a smoke point of 232°C and a fatty acid profile dominated by oleic (38-42%) and linoleic (34-38%) acids; its primary commercial purpose centers on culinary frying, cosmetic emollient systems, and pharmaceutical excipient applications. Refined oil dominates value capture due to broader retail distribution and longer shelf stability, while organic oil occupies premium shelf space in European and North American natural product channels. The cosmetic application segment leads growth trajectory as formulators substitute rice bran oil for mineral oil in skin care, though cooking still absorbs the majority of volume throughput across Asian markets.
FSSAI in India enforces progressively stricter trans-fat limits that push refiners toward rice bran oil's naturally low saturated fat content, while REACH in Europe governs cosmetic-grade oil imports through substance registration and safety dossier requirements. FDA oversight in the United States shapes pharmaceutical-grade oil specifications for tablet lubricant and capsule filler applications. Stakeholders must monitor how evolving national nutrition labeling standards and carbon accounting frameworks for agricultural commodities reshape procurement priorities and regional competitive positioning.
Market Dynamics
FSSAI's phased trans-fat reduction mandates are compressing India's edible oil landscape toward rice bran oil, as refiners retool solvent extraction capacity to exploit the bran's naturally low saturated fat profile and oxidative stability for high-heat frying.
Growth Catalysts
- Regulatory compression in India:FSSAI's 2022 trans-fat limits and 2025 enforcement timeline force packaged food manufacturers to reformulate frying oils. Rice bran oil's 232°C smoke point and neutral flavor accelerate substitution away from palm and hydrogenated blends.
- Cosmetic formulator pivot:European REACH-registered rice bran oil displaces mineral oil in emollient systems. Gamma-oryzanol extraction technology enables premium positioning in dermocosmetic channels.
- Rice milling cluster density:West Bengal and Odisha host integrated solvent extraction infrastructure proximate to bran supply. Captive raw material access reduces procurement friction for regional refiners.
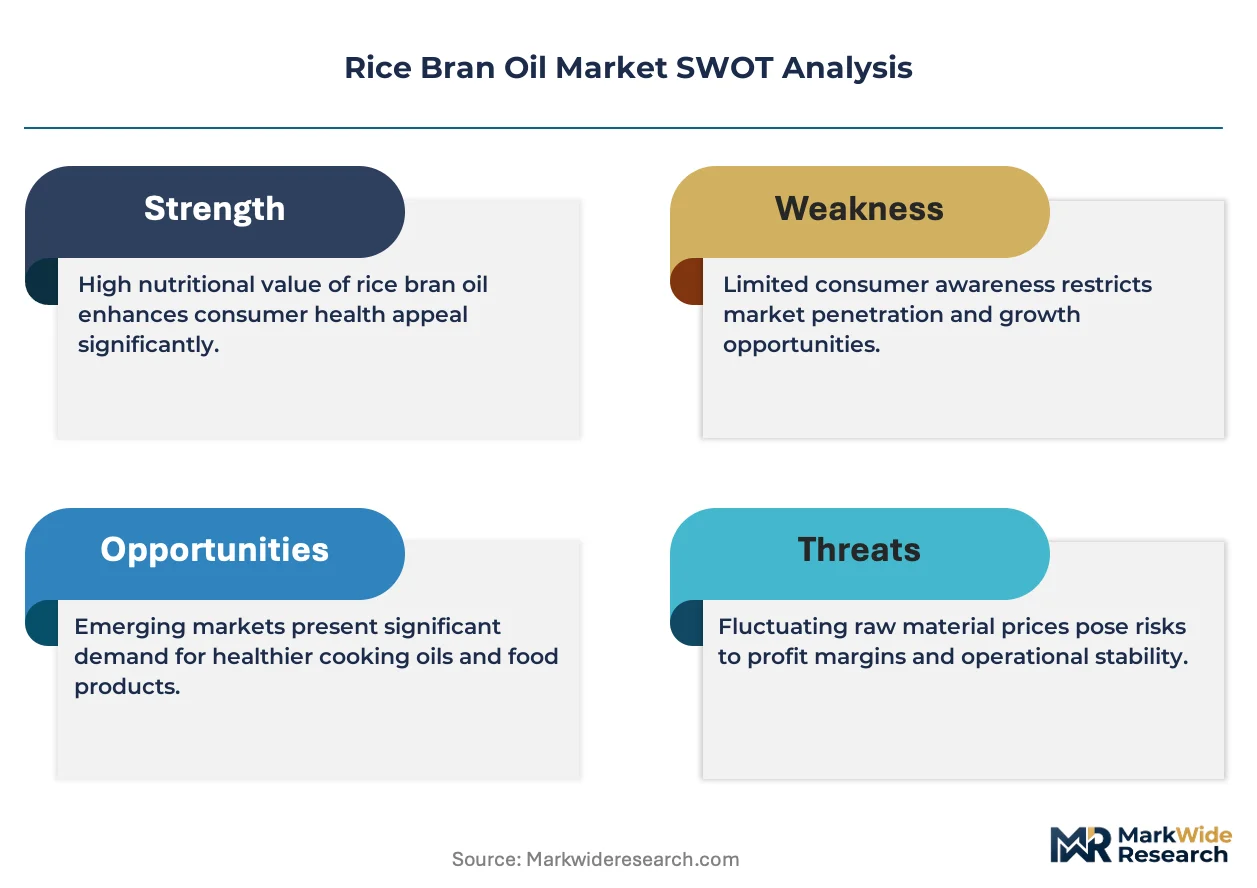
Market Restraints
- Input cost volatility:Rice bran availability fluctuates with monsoon-dependent paddy harvests across eastern India. Bran prices spike during lean procurement seasons, compressing refinery margins.
- Supply concentration risk:Over 60% of India's rice bran oil extraction capacity clusters in five eastern states. Logistics bottlenecks between milling and refining constrain national distribution.
- Technical limitation in cold-press extraction:Mechanical pressing yields 8-12% oil recovery versus 18-22% for solvent extraction. Premium organic positioning requires accepting volume penalties or chemical-free claims.
Strategic Opportunities
- Underpenetrated Bangladesh market:Cross-border bran supply from West Bengal and limited domestic refining capacity create import substitution potential. Local food service chains seek palm oil alternatives.
- Pharmaceutical excipient certification:US FDA drug master file pathways for rice bran oil in tablet lubrication remain sparsely populated. Early dossier submissions capture orphan positioning.
- EU Green Deal bioeconomy incentives:Cosmetic-grade rice bran oil qualifies for sustainability-linked procurement under CSRF disclosure requirements. German and French formulators prioritize vegetable-derived emollients.
Industry Challenges
- Skilled solvent extraction operator scarcity:Hexane recovery system expertise concentrates in legacy refinery towns. Workforce attrition threatens capacity utilization at greenfield installations.
- Refinery capex intensity:Continuous deodorization and winterization units require 18-24 month commissioning timelines. Working capital lockup during construction strains mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Bran Oil Market |
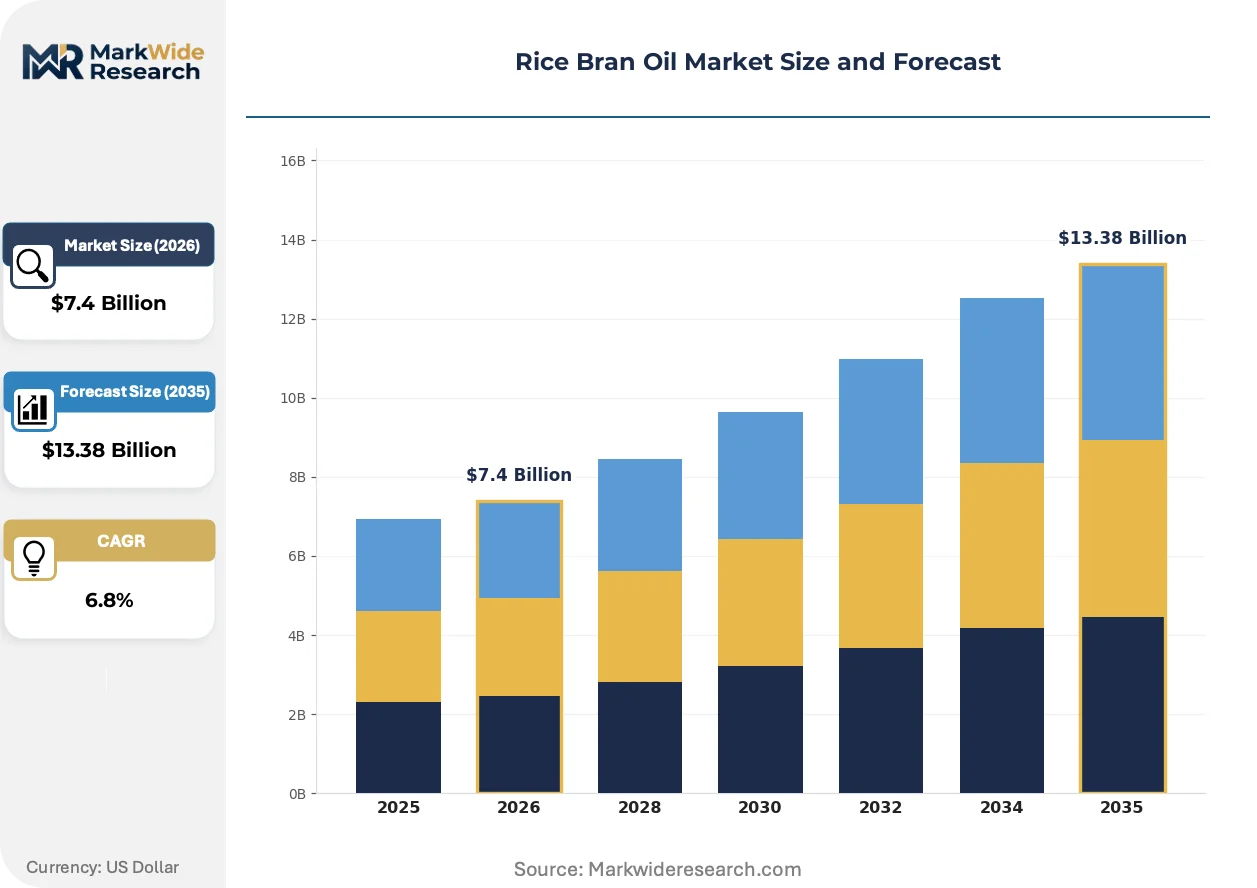
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Organic Oil, Enriched Oil Application: Cooking, Cosmetic, Pharmaceutical, Biofuel Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Bulk Containers Distribution Channel: Supermarkets, Online Retail, Local Markets, Wholesalers |
| Companies Covered | Ricela Group, Marico Ltd., Adani Wilmar Ltd., Tsuno Group Co. Ltd., King Rice Oil Group, Cargill Incorporated, Yihai Kerry Arawana Holdings, 3F Industries Ltd., Wilmar International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Bran Oil Market Strategic Shifts & Innovations
Supercritical CO2 extraction technology is disrupting traditional hexane-based refining, enabling toxin-free gamma-oryzanol concentration for functional food and cosmetic applications. Regulatory chemistry restrictions and clean-label procurement specifications accelerate capital redeployment.
Supercritical CO2 extraction is expanding into Japanese and South Korean nutraceutical manufacturing, replacing hexane-derived fractions in gamma-oryzanol supplements. PMDA and MFDS filing requirements favor solvent-free processes. The technology compresses extraction-to-retail timelines from 14 days to 72 hours, enabling just-in-contract manufacturing.
REACH Annex XVII restrictions on mineral oil hydrocarbons in cosmetics force European formulators toward vegetable-derived emollients. Rice bran oil's fatty acid compatibility with anhydrous skin care systems positions it as a direct MOSH/MOAH replacement. German contract manufacturers lead volume qualification, with French dermocosmetic brands following.
Food service procurement contracts now specify single-origin oil traceability for carbon accounting disclosures. Indian quick-service restaurant chains audit rice bran oil back to specific milling cooperatives in West Bengal. Third-party certification platforms capture margin premiums from Scope 3 emissions reporting requirements.
Rice Bran Oil Market Segmentation
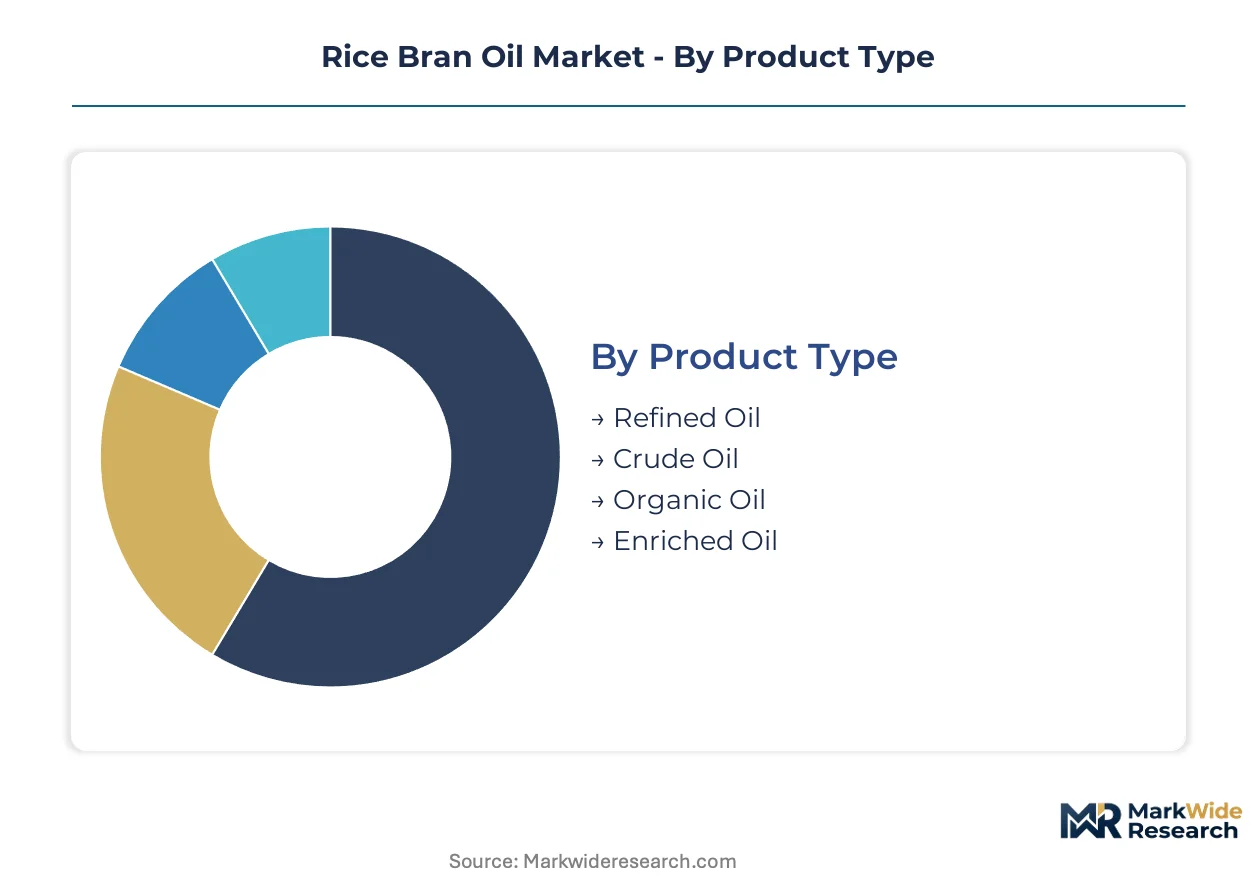
Rice bran oil's commercial versatility demands precise segmentation mapping. Each dimension reveals distinct margin structures, regulatory pathways, and procurement behaviors that separate commodity volume plays from premium value capture.
Product Type:
Customization intensity spans from standardized bulk grades to specification-driven certified variants, with processing depth determining price tier and customer access.
- Refined Oil:Deodorized and winterized to achieve 232°C smoke point with neutral flavor profile. Indian quick-service restaurant chains specify FSSAI-compliant refined grades for high-heat frying, locking in annual procurement contracts.
- Crude Oil:Solvent-extracted feedstock retaining waxes and free fatty acids, traded in tanker lots for downstream refining. Bangladeshi processors import crude from West Bengal mills to bypass limited domestic extraction capacity.
- Organic Oil:Cold-pressed or certified-organic solvent extraction with full traceability documentation. German natural product distributors require EU organic certification for shelf placement.
- Enriched Oil:Gamma-oryzanol concentrated through supercritical CO2 or molecular distillation. Japanese functional food manufacturers specify 10,000+ ppm oryzanol content for cholesterol-management positioning.
Leading the category by volume: Refined Oil. Growing fastest: Enriched Oil.
Application:
End-use concentration shifts from culinary commodity markets toward pharmaceutical and cosmetic specification tiers with divergent margin profiles.
- Cooking:Dominant volume absorption across Asian household and food service channels. Eastern Indian state governments procure fortified rice bran oil for public distribution schemes.
- Cosmetic:REACH-registered grades displace mineral oil in European emollient systems. Gamma-oryzanol enables antioxidant claims in French dermocosmetic formulations.
- Pharmaceutical:US FDA drug master file pathways for tablet lubricant and capsule filler applications remain underdeveloped. Early dossier submissions capture orphan excipient positioning.
- Biofuel:Fatty acid methyl ester feedstock for biodiesel blending mandates. Indian state transport corporations trial B20 blends from rice bran oil methyl ester.
Highest margin capture: Pharmaceutical. Expanding most quickly: Cosmetic.
Packaging Type:
Format selection tracks channel economics and shelf-life requirements, with premium positioning tied to material sustainability credentials.
- Glass Bottles:Premium retail positioning for organic and enriched grades. Japanese consumers associate amber glass with oxidation protection for high-oryzanol oils.
- Plastic Bottles:Standard 1-liter and 5-liter formats for Indian mass-market distribution. Marico's Saffola portfolio dominates this format through modern trade penetration.
- Tetra Packs:Aseptic filling extends shelf stability for export markets. Middle Eastern importers specify tetra pak for ambient logistics efficiency.
- Bulk Containers:ISO tankers and flexitanks for industrial pharmaceutical and cosmetic procurement. German contract manufacturers receive 20-tonne bulk shipments for formulation use.
Volume leadership: Plastic Bottles. Steepest expansion trajectory: Tetra Packs.
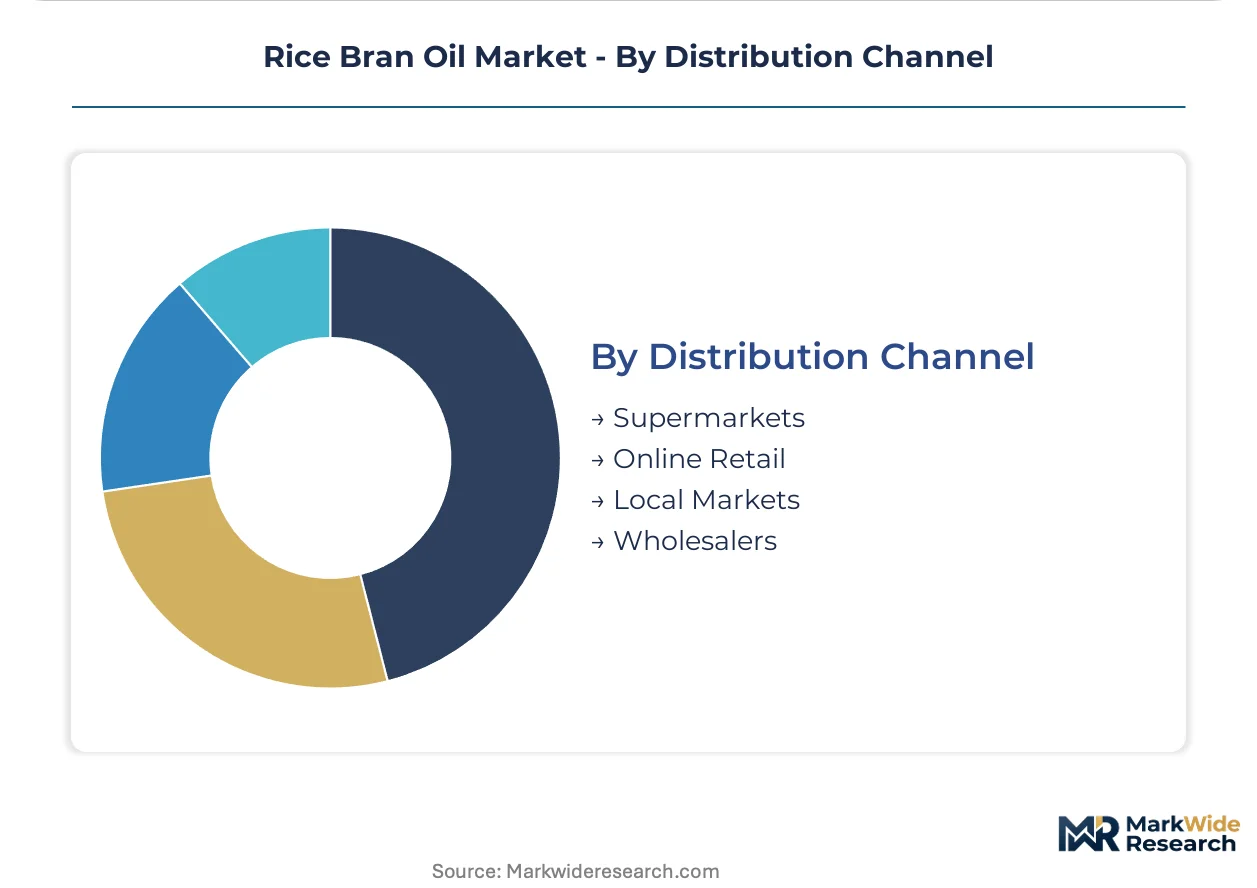
Distribution Channel:
Channel fragmentation reflects India's dual-speed retail modernization alongside persistent traditional trade dominance in eastern rice belt states.
- Supermarkets:Modern trade consolidation in Indian metropolitan markets. Organized retail chains negotiate private-label refined oil contracts with Punjab-based refiners.
- Online Retail:Direct-to-consumer growth for organic and enriched specialty grades. Amazon India and BigBasket capture urban premium segment migration.
- Local Markets:Kirana store networks and mandi aggregators in West Bengal and Odisha. Unbranded loose oil sales persist despite FSSAI packaged oil mandates.
- Wholesalers:Tanker-load distribution to Bangladesh and Nepal border markets. Cross-border traders arbitrage Indian surplus against limited domestic refining capacity.
Dominant volume: Local Markets. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in eastern India concentrate rice bran oil processing infrastructure. FSSAI trans-fat mandates and integrated milling clusters drive regional investment patterns.
India
West Bengal and Odisha host dense networks of rice milling and solvent extraction facilities. FSSAI's phased trans-fat reduction mandates force packaged food manufacturers to reformulate frying oils. Punjab-based refiners leverage captive bran supply from northern procurement networks.
Japan
Functional food manufacturers drive demand for gamma-oryzanol-enriched formulations. PMDA filing requirements favor supercritical CO2 extraction processes for nutraceutical applications. Tsuno Group anchors production in domestic rice-processing corridors.
China
Yihai Kerry Arawana Holdings processes rice bran oil through integrated edible oil distribution networks. SAMR food safety standards govern refining specifications for domestic retail channels. Yangtze River Delta clusters concentrate solvent extraction capacity proximate to rice milling infrastructure.
Germany
REACH-registered rice bran oil displaces mineral oil in cosmetic emollient systems. EU Green Deal bioeconomy incentives prioritize vegetable-derived ingredients for sustainability-linked procurement. Contract manufacturers in Baden-Württemberg lead volume qualification for dermocosmetic applications.
United States
FDA oversight shapes pharmaceutical-grade oil specifications for tablet lubricant and capsule filler applications. US drug master file pathways for rice bran oil excipients remain sparsely populated. Early dossier submissions capture orphan positioning in contract manufacturing channels.
Rice Bran Oil Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: integrated agribusiness conglomerates with captive milling networks, branded consumer oil portfolios competing on heart-health positioning, and regional solvent extraction specialists serving industrial bulk channels. Strategic moves center on backward integration into rice milling assets and supercritical CO2 technology licensing for premium-grade extraction.
Among Indian integrated processors, Ricela Group and 3F Industries Ltd. represent the solvent-extraction archetype with proximity-based supply security. Marico Ltd. occupies the branded portfolio tier through consumer-facing positioning. Japanese specialist Tsuno Group Co. Ltd. exemplifies the functional-food differentiation vector through gamma-oryzanol concentration capabilities.
| Leading Market Players |
|---|
| Ricela Group |
| Marico Ltd. |
| Adani Wilmar Ltd. |
| Tsuno Group Co. Ltd. |
| King Rice Oil Group |
| Cargill Incorporated |
| Yihai Kerry Arawana Holdings |
| 3F Industries Ltd. |
| Wilmar International Ltd. |
| Others |
Cost & Logistics Intelligence
Captive milling networks in eastern India anchor supply security for refiners while compressing procurement costs that determine competitive pricing floors. FSSAI trans-fat mandates amplify demand concentration where integrated operators can enforce contract premiums against spot-market volatility.
Pricing Analysis
Volume throughput concentrates in refined bulk grades for Indian quick-service restaurants, while margin capture concentrates in gamma-oryzanol-enriched formulations for Japanese nutraceutical channels. Price differentiation rests on certification tier and extraction technology, with supercritical CO2-derived oils commanding substantial premiums over hexane-extracted commodity grades. Cost compression in standard refined oil is intensifying because bran supply fluctuates with monsoon-dependent paddy harvests. Food service chains exhibit highest price sensitivity due to annual procurement contract structures, whereas cosmetic formulators in Germany demonstrate lowest sensitivity when sourcing REACH-registered grades.
Supply Chain Analysis
Regional distribution centers in Kolkata and Cuttack form hub-and-spoke patterns that feed solvent extraction facilities across West Bengal and Odisha. Raw material supply draws from rice milling clusters in eastern India, Bangladesh, and Myanmar, with hexane and supercritical CO2 equipment sourced from Japanese and German manufacturers. Single-source vulnerability concentrates in skilled solvent extraction operator pools legacy to specific refinery towns. Distribution runs through tanker-load wholesalers for cross-border trade into Bangladesh and Nepal, supplemented by flexitank shipments for European cosmetic contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into rice milling assets has become the decisive upstream lever as refiners compete for captive bran supply against volatile input costs.
For Market Incumbents: Deepen solvent extraction capacity in Punjab and Haryana to offset eastern supply concentration risk. Secure FSSAI-compliant refining certifications ahead of enforcement timelines to lock in packaged food manufacturer contracts. Prioritize supercritical CO2 technology licensing to defend margin position against hexane-based commodity competitors. For New Entrants and Emerging Players: REACH Annex XVII restrictions on mineral oil hydrocarbons in Europe open a window for vegetable-derived emollient positioning. Pursue pharmaceutical excipient certification through US FDA drug master file pathways where dossier submissions remain sparse. Establish gamma-oryzanol concentration capabilities to access Japanese functional food manufacturing contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness conglomerates seeking captive milling networks. Long-term viability favors operators with demonstrated supercritical CO2 extraction scale and multi-regulatory certification portfolios. Monitor FSSAI enforcement adherence as the inflection indicator separating compliant premium-positioned assets from stranded commodity refining capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Milling | Captive bran supply from West Bengal cooperatives reduces procurement friction and margin volatility. |
| Supercritical CO2 Extraction Scale-Up | PMDA-preferred solvent-free processes unlock Japanese nutraceutical contract manufacturing premiums. |
| REACH Registration for Cosmetic Grades | German formulators prioritize vegetable-derived emollients under EU Green Deal procurement incentives. |
| Pharmaceutical Excipient Certification | US FDA drug master file pathways for tablet lubricant applications remain underdeveloped for early entrants. |
| Cross-Border Distribution Expansion | Bangladesh import substitution potential leverages West Bengal bran surplus against limited domestic refining capacity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with solvent extraction plant managers, FSSAI compliance officers at refiners, cosmetic formulators in Germany, and pharmaceutical excipient procurement leads. Solvent Extractors Association of India production statistics, FSSAI trans-fat mandate documentation, REACH registration databases, and US FDA drug master file listings provided triangulation points against bottom-up capacity estimates and top-down demand modeling.
Data-stream reconciliation across extraction capacity surveys, bran availability estimates, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, packaging format, and distribution channel alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of historical production volumes against policy-driven demand inflection points, with supercritical CO2 technology adoption curves and FSSAI compliance timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hexane-free extraction scale-up would alter the outlook if capital redeployment accelerates beyond baseline assumptions. Forecasts reflect documented assumption sets regarding regulatory enforcement timing and milling cluster expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Chicory Root Fiber Market
Ingredients
Fiber Rich Flours Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Microencapsulated Oil Market
Ingredients
Hen Egg White Protein Market
Ingredients
North America Fats and Oils Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Dry Malt Products Market
Ingredients
Europe Protein Market
Ingredients
Gymnema Extract Market
Ingredients
Botanical Extracts Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
India Olive Oil Market
Ingredients
Hops Market