
 Specialty Starch Market | 2026-2036
Specialty Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Starch Market Analytics
Food ingredient distribution channels are rewriting procurement patterns across the specialty starch value chain. Cargill, Incorporated leverages its grain origination network to secure cost-advantaged waxy corn feedstock for modified starch production. Ingredion Incorporated anchors North American supply through integrated manufacturing plants that convert regional agricultural output directly into food-grade specialty grades. Roquette Frères competes from its European pea and potato starch base, capitalizing on non-GMO positioning and proximity to major food processors.
Specialty starch comprises physically, chemically, or enzymatically altered native starch polymers engineered for specific viscosity, stability, or film-forming properties in industrial applications. Manufacturers achieve these modifications through oxidation, cross-linking, or pregelatinization processes that expand temperature tolerance and shear resistance beyond standard native starch limits. Modified starch captures the dominant value share as food and beverage formulators replace synthetic hydrocolloids with label-friendly alternatives. Resistant starch represents the fastest-expanding product category, driven by fiber fortification trends in functional nutrition and digestive health products. Pregelatinized starch maintains steady demand from instant food manufacturers requiring cold-water solubility without additional heat processing.
FDA food additive regulations govern modified starch safety assessments and labeling requirements in the United States, while EFSA and REACH frameworks in Europe enforce chemical migration limits and sustainability disclosure for bio-based ingredients. These regulatory structures elevate compliance costs for smaller producers but simultaneously create market access advantages for established operators with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving clean-label definitions and carbon accounting standards that will determine which specialty starch variants qualify for premium positioning in tomorrow's ingredient procurement decisions.
Market Dynamics
Clean-label mandates from EU Green Deal packaging regulations and REACH chemical governance are compressing synthetic additive demand while pulling bio-based starch alternatives into formulation pipelines across European food manufacturing.
Growth Catalysts
- EU Green Deal packaging mandates:Binding sustainability targets for bio-based materials in food contact applications accelerate modified starch substitution for petroleum-derived films and coatings in Germany, France, and Netherlands processing corridors.
- Resistant starch fiber fortification:Digestive health positioning in functional nutrition products drives prebiotic ingredient demand from supplement manufacturers and medical food formulators seeking clinically validated fiber claims.
- Waxy corn feedstock concentration:North American grain origination networks deliver cost-advantaged raw material access for modified starch producers serving instant food and beverage stabilization applications.
Market Restraints
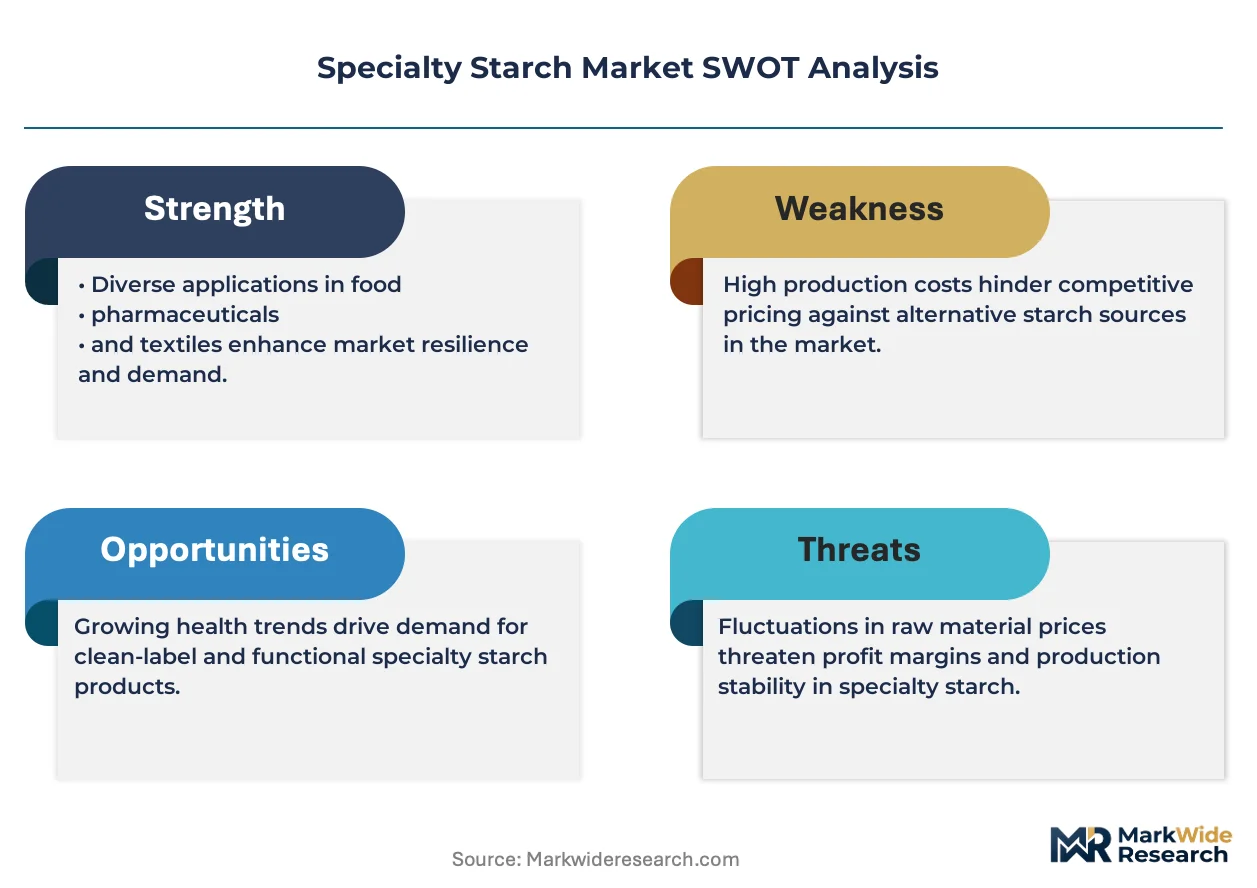
- Native corn price volatility:Weather-driven yield fluctuations and biofuel policy competition for starch feedstock create margin compression risk for unhedged specialty starch processors.
- Pea protein diversion:Roquette Frères and European competitors face raw material competition from plant-based meat manufacturers bidding for identical pea starch extraction feedstock.
- Enzymatic modification capacity scarcity:Limited toll manufacturing infrastructure for precision enzymatic processing constrains rapid scaling of clean-label modified starch variants.
Strategic Opportunities
- India FSSAI clean-label recognition:Emerging regulatory framework for natural ingredient claims creates first-mover positioning for pregelatinized starch in instant noodle and ready-meal manufacturing.
- Pharmaceutical excipient qualification:USP-NF and EP monograph compliance for tablet disintegration and controlled-release applications opens high-margin channel beyond food and beverage.
- Carbon accounting disclosure requirements:EU CSRD scope 3 reporting obligations favor suppliers with verified lifecycle data, enabling premium positioning for regenerative agriculture-linked starch sourcing.
Industry Challenges
- Cross-functional regulatory expertise scarcity:Simultaneous FDA food additive, EFSA novel food, and REACH chemical registration requirements demand rare hybrid skill sets in toxicology and polymer chemistry.
- Retrofitting legacy spray-drying infrastructure:Cold-water solubility specifications for instant applications require capital-intensive dryer modifications or greenfield construction with extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Starch Market |
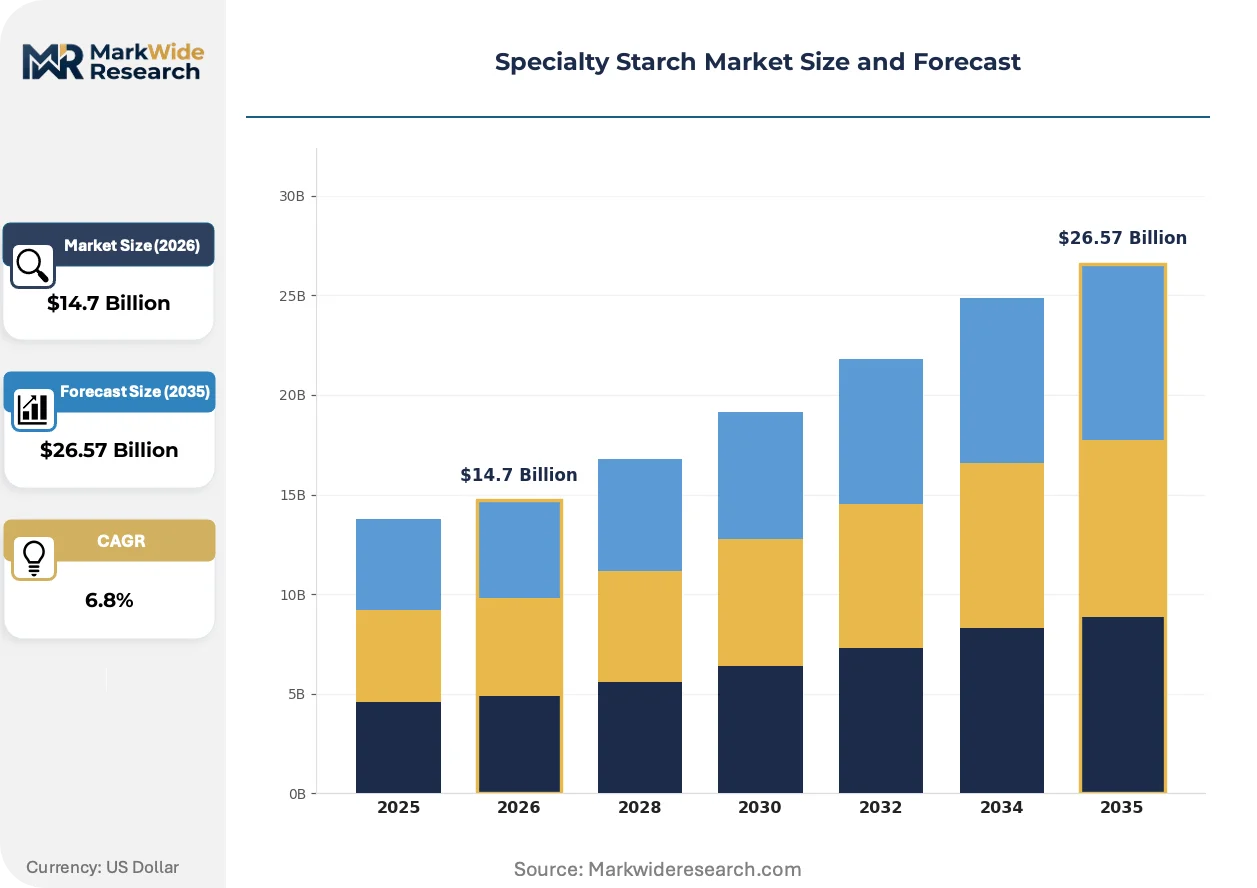
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Pregelatinized Starch, Resistant Starch Application: Food & Beverage, Pharmaceuticals, Cosmetics, Industrial Form: Powder, Granule, Liquid, Gel End User: Food Industry, Personal Care, Textile, Paper |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Avebe U.A., AGRANA Beteiligungs-AG, KMC Kartoffelmelcentralen A.M.B.A., Emsland-Stärke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Starch Market Evolving Landscape
Physical, chemical, and enzymatic modification techniques are converging to produce starch polymers with engineered functionality that satisfies clean-label requirements without synthetic hydrocolloid performance trade-offs.
Dual-modification processing is hybridizing oxidation and cross-linking protocols to achieve simultaneous clarity, freeze-thaw stability, and shear resistance in single-ingredient solutions. Sauces and dressings formulators in North American retail channels are adopting these hybrid grades at accelerating rates. The technology is compressing formulation complexity by eliminating multi-hydrocolloid blends previously required for equivalent performance.
REACH chemical migration limits and sustainability disclosure frameworks are elevating compliance thresholds for bio-based ingredients entering European food contact applications. Manufacturers must now document carbon intensity and biodegradability credentials alongside traditional safety assessments. Modified starch variants with third-party regenerative agriculture certification command preferential placement in German and Benelux procurement decisions.
Direct supplier relationships are displacing traditional ingredient distribution intermediaries as large food processors seek supply chain transparency for scope 3 emissions reporting. Cargill, Incorporated and Ingredion Incorporated have established dedicated account structures for multinational customers requiring farm-to-factory traceability. This pattern concentrates procurement volume with integrated manufacturers possessing captive origination networks and granular sustainability data infrastructure.
Specialty Starch Market Segmentation
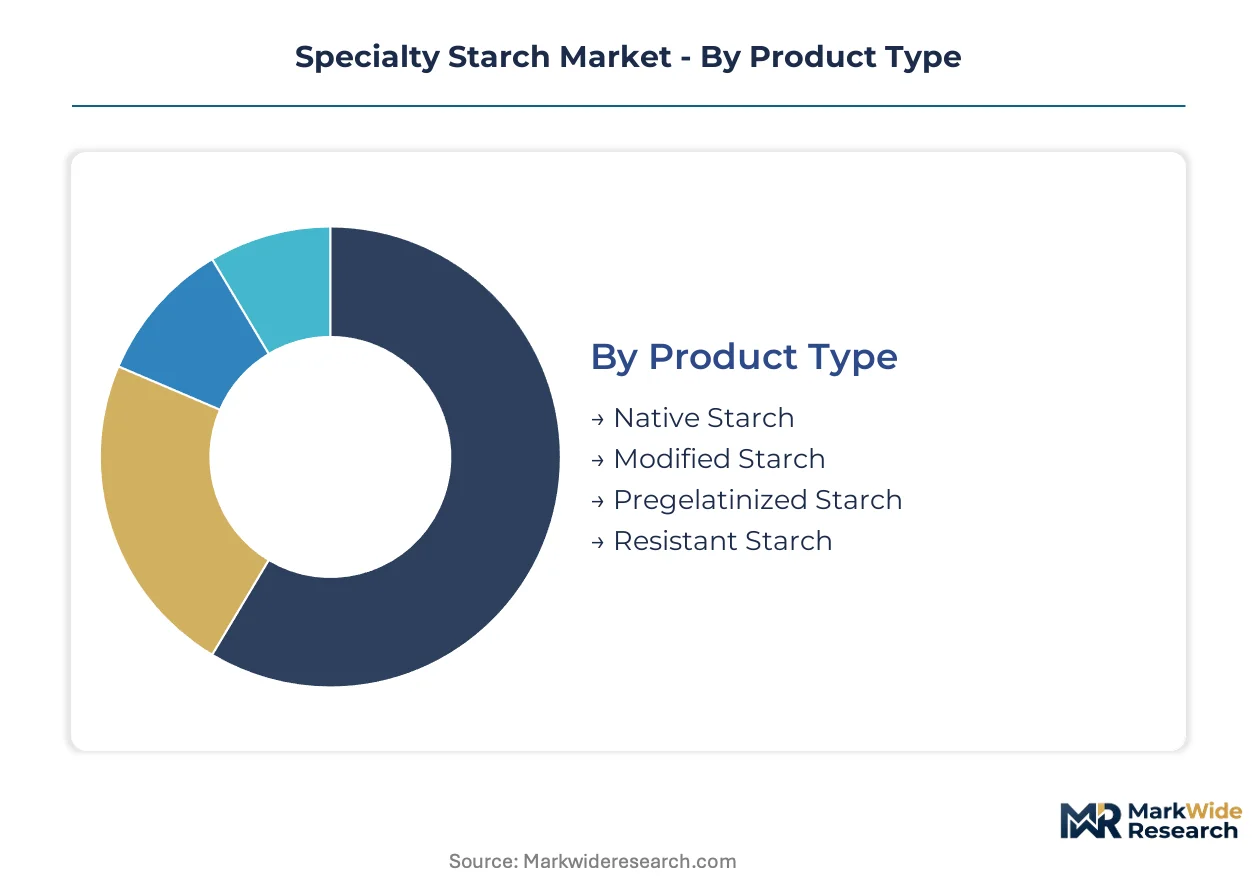
Specialty starch procurement cycles vary dramatically across product categories, with instant food manufacturers rotating pregelatinized inventories quarterly while pharmaceutical buyers lock in resistant starch supply contracts spanning multiple years. Understanding these velocity differentials enables suppliers to calibrate working capital and pricing structures to specific segment economics.
Product Type:
Modified starch turns inventory fastest in European food processing corridors, while resistant starch sits in longer production cycles tied to clinical validation timelines and fiber fortification formulation lock-ins.
- Native Starch:Unaltered amylose-amylopectin polymers extracted from corn, potato, or cassava feedstock serve as baseline inputs for downstream modification or direct use in cost-sensitive applications. Demand concentrates in Asian noodle manufacturing and European paper sizing operations where processors prioritize raw material cost over functional performance.
- Modified Starch:Chemically, physically, or enzymatically altered polymers deliver engineered viscosity, stability, and film-forming properties that native starches cannot achieve. Food and beverage formulators in Germany and the Netherlands specify cross-linked and oxidized grades to replace synthetic hydrocolloids under EU Green Deal clean-label mandates.
- Pregelatinized Starch:Thermally processed for cold-water solubility eliminates cooking requirements in instant applications. Ready-meal and instant soup manufacturers in India source these grades under emerging FSSAI clean-label recognition frameworks.
- Resistant Starch:Digestive-resistant polymers function as prebiotic fiber in functional nutrition and medical food products. Supplement manufacturers and clinical nutrition formulators drive demand through validated digestive health claims requiring extended stability testing and regulatory substantiation cycles.
Modified starch dominates installed base across food manufacturing. Resistant starch is where expansion concentrates as fiber fortification claims penetrate mainstream retail channels.
Application:
Cost tiers separate commodity-scale food volume from premium pharmaceutical and cosmetic specifications, with regulatory compliance burden and performance validation requirements determining margin architecture.
- Food & Beverage:Texture modification, stabilization, and clean-label replacement of synthetic additives drive formulation decisions across sauces, dressings, bakery, and dairy applications. EU EFSA and US FDA food additive frameworks govern safety assessments while REACH chemical migration limits constrain packaging-adjacent uses in European markets.
- Pharmaceuticals:Tablet disintegration, controlled-release matrices, and excipient functionality require USP-NF and EP monograph compliance. High-margin positioning reflects qualification timelines and batch certification requirements that commodity food grades bypass entirely.
- Cosmetics:Film-forming and rheology modification in personal care formulations leverage starch biocompatibility for natural positioning. Formulators specify non-GMO and regenerative agriculture-linked sourcing to satisfy scope 3 reporting obligations under EU CSRD disclosure mandates.
- Industrial:Paper sizing, textile sizing, and adhesive applications consume volume grades where performance tolerances permit broader specification ranges. Price sensitivity concentrates procurement with integrated manufacturers possessing captive grain origination networks.
Food and beverage commands volume leadership. Pharmaceuticals deliver margin expansion through excipient qualification barriers.
Form:
Supply concentration favors powder processing infrastructure, while liquid and gel formats require specialized dispersion equipment that fragments manufacturing bases.
- Powder:Spray-dried particulates dominate dry-blend applications across instant food, pharmaceutical tableting, and powder cosmetic formulations. German and Benelux processing corridors specify powder grades for compatibility with existing pneumatic conveying and blending systems.
- Granule:Agglomerated particles reduce dusting and improve flow properties for high-speed packaging lines. Seasoning and soup manufacturers in North American retail channels specify granule formats for production efficiency gains.
- Liquid:Pre-dispersed starch slurries eliminate hydration time in continuous processing environments. Sauces and dressings manufacturers with limited batch tank capacity source liquid grades to accelerate throughput.
- Gel:Fully hydrated starch pastes serve specialized cosmetic and pharmaceutical applications requiring immediate rheological functionality without heat activation. Medical gel formulations and topical delivery systems specify gel formats for processing simplicity.
Powder dominates installed base. Liquid is gaining share fastest in continuous processing environments.
End User:
Customer type determines specification stringency, with pharmaceutical and personal care buyers imposing certificate-of-analysis requirements that food and textile processors rarely match.
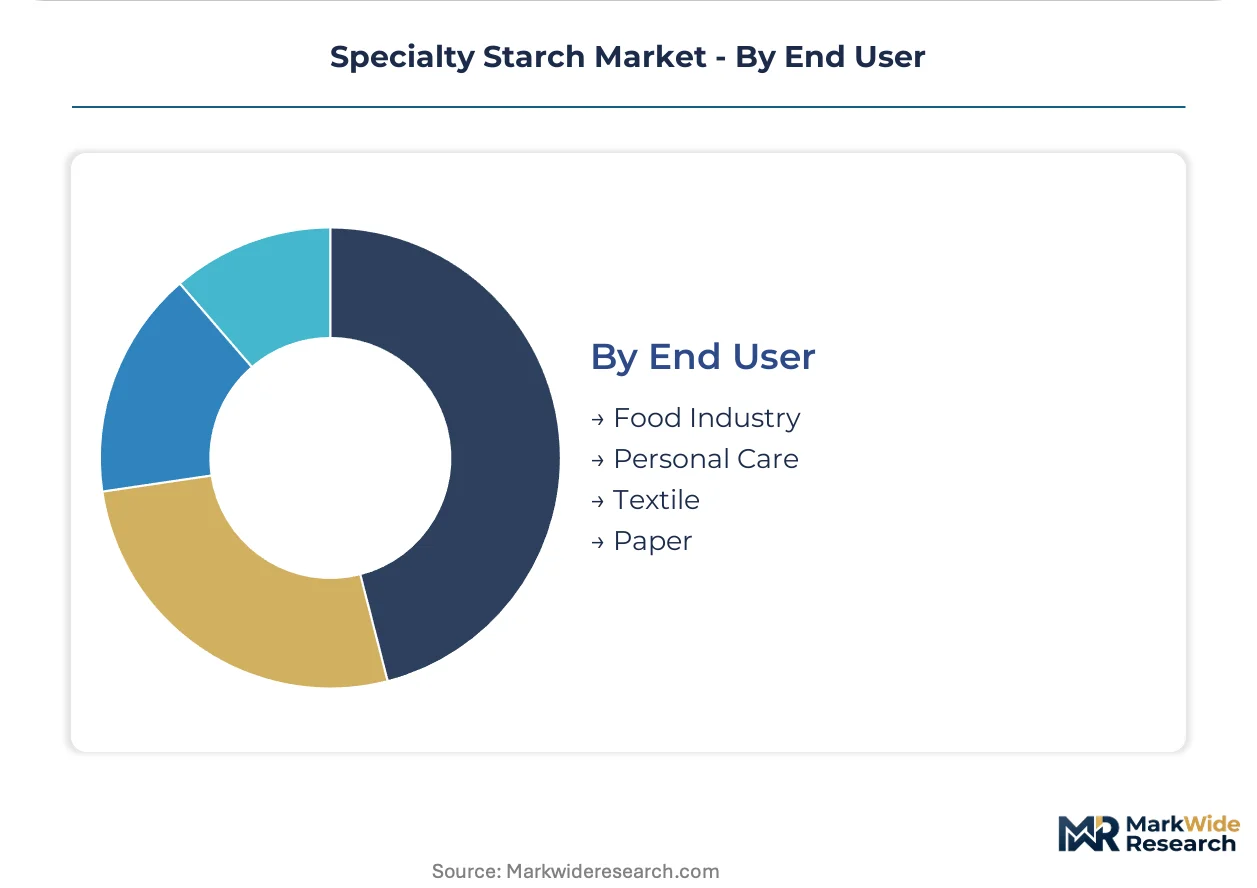
- Food Industry:Ingredient buyers across bakery, dairy, convenience foods, and beverage manufacturing prioritize clean-label positioning and supply chain transparency for scope 3 emissions reporting. Direct supplier relationships with integrated manufacturers displace traditional distribution intermediaries.
- Personal Care:Cosmetic formulators specify non-GMO, organic-certified, and regenerative agriculture-linked starches to support natural product claims. EU REACH sustainability disclosure requirements elevate documentation burdens that favor established suppliers with verified lifecycle data infrastructure.
- Textile:Warp sizing and finishing applications consume cost-optimized grades where film strength and abrasion resistance determine specification. Asian textile manufacturing clusters source volume through regional trading networks.
- Paper:Surface sizing and coating applications require specific viscosity profiles and binder compatibility. European paper mills specify modified starch grades to satisfy bio-based content targets under EU Green Deal packaging mandates.
Food industry commands installed base. Personal care is climbing the fastest as natural positioning penetrates premium cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River grain corridor underwrites North American specialty starch supply security, with barge terminals at St. Louis and New Orleans anchoring cost-efficient feedstock movement from Midwest corn belts to Gulf Coast processing clusters.
United States
Modified starch demand from clean-label sauce and dressing formulators concentrates in Midwest food processing corridors. FDA food additive regulations govern safety assessments for cross-linked and oxidized grades entering interstate commerce. Chicago and Minneapolis-St. Paul metropolitan areas host ingredient procurement headquarters for multinational food manufacturers prioritizing supply chain transparency.
Germany
EU Green Deal packaging mandates accelerate bio-based starch substitution for petroleum-derived films in food contact applications. REACH chemical migration limits and EFSA frameworks enforce sustainability disclosure requirements for modified starch entering European markets. The Rhine-Ruhr industrial corridor and Bavarian processing clusters dominate procurement volume for premium modified grades.
India
FSSAI clean-label recognition frameworks for natural ingredient claims drive pregelatinized starch uptake in instant noodle and ready-meal manufacturing. Bureau of Indian Standards (BIS) quality specifications govern food-grade starch imports and domestic production certification. Maharashtra and Gujarat industrial belts concentrate processing infrastructure for modified starch serving domestic food manufacturers.
China
Modified starch capacity expansion targets in national starch industry development plans prioritize functional food-grade variants. SAMR food safety regulations and GB standards govern additive approvals and labeling requirements for chemically modified polymers. Shandong Province and Yangtze River Delta manufacturing clusters integrate corn wet-milling with downstream specialty starch modification.
Netherlands
REACH sustainability disclosure obligations elevate documentation burdens for bio-based ingredients entering Benelux food manufacturing channels. EU CSRD scope 3 reporting requirements favor suppliers with verified lifecycle carbon data for regenerative agriculture-linked sourcing. Rotterdam port infrastructure and Randstad logistics networks facilitate feedstock import and specialty starch distribution across Northwestern Europe.
Specialty Starch Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness operators with captive grain origination networks and dedicated modification infrastructure. Three strategic archetypes dominate: multinational grain processors with backward integration into specialty starch, European potato and pea starch specialists leveraging non-GMO positioning, and regional toll manufacturers serving pharmaceutical excipient qualification requirements. Competitive moves center on capacity expansion in enzymatic modification infrastructure and direct supplier relationship structures displacing traditional ingredient distribution intermediaries.
Among North American integrated processors, Cargill, Incorporated and Ingredion Incorporated occupy positions defined by captive corn origination networks and direct account structures for multinational food manufacturers. Roquette Frères exemplifies the European specialist archetype, anchoring non-GMO pea and potato starch supply from French and Benelux processing bases. Tate & Lyle PLC represents the reformulation partnership model, embedding technical service capabilities with food and beverage customers seeking clean-label hydrocolloid replacements.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Avebe U.A. |
| AGRANA Beteiligungs-AG |
| KMC Kartoffelmelcentralen A.M.B.A. |
| Emsland-Stärke GmbH |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr industrial corridor's enzymatic modification capacity concentration grants German processors outsized leverage in premium modified starch contract negotiations, compressing margins for toll-dependent competitors while elevating returns for integrated operators with captive feedstock origination.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment. Pharmaceutical excipient qualification commands the highest tier, while industrial paper sizing absorbs economy grades with minimal documentation. Price differentiation rests on regenerative agriculture certification and carbon intensity verification under EU CSRD scope 3 frameworks. Cost compression in standard food-grade modified starch is intensifying because of native corn price volatility and biofuel policy competition for feedstock. Industrial textile processors exhibit the highest price sensitivity, whereas clinical nutrition formulators prioritize performance validation over unit cost.
Supply Chain Analysis
Toll manufacturing concentration for precision enzymatic processing sits with Roquette Frères in France and Benelux, Cargill's North American wet-milling network, and Ingredion's integrated US plants. Geographic supply concentrates in the United States, Germany, and the Netherlands, with emerging capacity expansion in India and China. Raw material dependencies center on waxy corn hybrids, pea starch extraction feedstock, and potato tuber supply. Single-source vulnerability from weather-driven corn yield fluctuations in the Midwest grain belt threatens unhedged processors. Distribution runs through direct supplier relationships with multinational food manufacturers, displacing traditional ingredient distribution intermediaries seeking scope 3 emissions transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty starch incumbents face substitution pressure from synthetic hydrocolloid reformulations and emerging fermentation-derived texturants, requiring defensive positioning around clean-label credibility and regulatory qualification barriers.
For Market Incumbents: Build regulatory moat through simultaneous FDA food additive, EFSA novel food, and REACH chemical registration capabilities that smaller competitors cannot replicate. Deepen backward integration into regenerative agriculture-linked waxy corn origination to secure cost-advantaged feedstock and verified carbon intensity data for EU CSRD disclosure compliance. Target enzymatic modification capacity expansion in the Rhine-Ruhr corridor to capture premium positioning from clean-label mandate acceleration. For New Entrants and Emerging Players: Build out pharmaceutical excipient qualification infrastructure serving USP-NF and EP monograph requirements, where incumbent concentration is lowest and margin architecture supports new entrant economics. Target India's FSSAI clean-label recognition framework for pregelatinized starch in instant noodle and ready-meal manufacturing, where domestic supply gaps persist. Pursue toll manufacturing partnerships with established European pea starch processors to bypass capital-intensive greenfield construction timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enzymatic modification capacity scarcity and hybrid regulatory expertise requirements favor scaled operators with dedicated compliance infrastructure. Acquisition target archetype: mid-cap European potato or pea starch specialists with non-GMO positioning and proximity to Benelux food processing corridors. Monitor India FSSAI enforcement patterns and EU Green Deal packaging mandate implementation timelines as inflection signals for geographic demand reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | Captures clean-label demand from EU Green Deal packaging mandates in German processing corridors. |
| Regenerative Agriculture Sourcing Certification | Enables premium positioning under EU CSRD scope 3 carbon disclosure requirements. |
| Pharmaceutical Excipient Monograph Compliance | Opens high-margin USP-NF and EP channels beyond commodity food-grade competition. |
| Direct Account Structures for Multinationals | Displaces distribution intermediaries for scope 3 emissions traceability requirements. |
| India FSSAI Clean-Label Market Entry | Secures first-mover positioning in instant food manufacturing under emerging natural ingredient frameworks. |
Research Methodology
A spread of perspectives from plant managers at wet-milling facilities, procurement leads at downstream food manufacturers, technical R&D directors, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation from customs and trade data, SEC 10-K filings, EU EFSA submissions, and industry association reports from ACC and Cefic. Bottom-up capacity and demand estimates were triangulated against top-down macroeconomic indicators to produce converged market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product modification type, application end-use, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation validated against industry capacity expansion announcements and feedstock origination patterns. Key forecast inputs included corn yield volatility projections, EU Green Deal implementation pacing, and pharmaceutical excipient qualification pipeline status.
Stress conditions across native corn price volatility, enzymatic processing capacity constraints, and REACH chemical migration limit enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and clean-label definition evolution. Quarterly review of EU CSRD disclosure adoption rates, India FSSAI enforcement patterns, and pharmaceutical monograph submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Peanut Flour Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Acacia Gum Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Horehound Extract Market
Ingredients
Europe Corn Glucose Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Citrus Pectin Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Safflower Oil Market
Ingredients
United States Corn Glucose Market
Ingredients
Freeze-Dried Pea Isolates Market