
 Food Amino Acids Market | 2026-2036
Food Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Food Amino Acids Market Analysis
Sports nutrition is shifting from niche bodybuilding channels toward mainstream wellness retail, broadening the addressable base for condition-specific amino acid premixes. Ajinomoto Co., Inc. leverages its fermentation technology leadership to supply pharmaceutical-grade L-glutamine for clinical nutrition. CJ CheilJedang Corporation anchors its position through captive lysine capacity serving integrated animal protein operations. Evonik Industries AG differentiates via precision crystallization processes that yield high-purity branched-chain amino acids for infant formula and medical foods.
Food amino acids are nitrogen-containing organic compounds produced via microbial fermentation, enzymatic synthesis, or protein hydrolysis, typically specified at minimum purity thresholds between 98% and 99.5% for human-grade applications. These compounds function as building blocks for protein synthesis, flavor precursors, and metabolic regulators across food, feed, and pharmaceutical systems. L-glutamine and L-leucine dominate volume flows due to their established roles in muscle preservation formulations and clinical recovery protocols, while L-arginine generates premium pricing from cardiovascular and erectile dysfunction supplement positioning. Powder forms capture the largest share of production volume owing to stability in bulk handling and compatibility with dry-blend manufacturing, though liquid concentrates gain traction in ready-to-drink sports beverages where solubility speed determines consumer preference.
FDA GRAS self-affirmation pathways and EFSA novel food evaluations shape market entry timelines for fermentation-derived amino acids in the United States and European Union respectively, with China's NMPA and SAMR enforcing stricter purity and origin labeling for imported feed-grade materials. The EU F-Gas Regulation indirectly pressures manufacturers to adopt lower-emission fermentation cooling systems, raising capital requirements for new capacity. Stakeholders must monitor evolving amino acid maximum level regulations in infant formula across major jurisdictions, as tightening thresholds could disqualify current supply sources and trigger reformulation cycles before the next investment planning horizon.
Market Dynamics
Fermentation capacity concentration in East Asia and tightening EU Green Deal compliance requirements are restructuring competitive positioning in food amino acids, forcing Western processors to secure long-term offtake agreements or build captive biomanufacturing assets.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Sourcing transparency requirements for feed and food amino acids are accelerating traceability investments across European supply chains.
- Sports nutrition formulation budgets:Condition-specific premix demand from wellness retail channels is expanding the addressable consumer base beyond traditional bodybuilding segments.
- China domestic lysine and glutamine output:Integrated production serving local nutraceutical makers and export animal feed compounders is consolidating regional supply leverage.
Market Restraints
- Input cost volatility in corn and sugar feedstocks:Fermentation substrate prices fluctuate with agricultural commodity cycles, compressing margin predictability for bulk amino acid producers.
- Supply concentration in Chinese fermentation clusters:Geographic clustering of lysine and glutamine capacity creates vulnerability to localized energy rationing or environmental enforcement actions.
- EFSA novel food evaluation timelines:Extended safety assessment protocols for fermentation-derived amino acids delay European market entry by 18-36 months versus GRAS pathways.
Strategic Opportunities
- Underpenetrated clinical nutrition segments:Pharmaceutical-grade L-glutamine for recovery protocols remains underserved in North American hospital formulary systems.
- EU F-Gas Regulation cooling system retrofits:Lower-emission fermentation infrastructure mandates create first-mover advantage for biomanufacturers with upgraded thermal management.
- Ready-to-drink sports beverage channels:Liquid concentrate amino acid formats are displacing powder sachets in convenience retail formats across urban China.
Industry Challenges
- Fermentation process engineer scarcity:Specialized talent for large-scale amino acid biomanufacturing commands premium compensation in competing biopharma sectors.
- Infant formula maximum level compliance:Tightening purity thresholds across FDA, EFSA, and SAMR jurisdictions threaten disqualification of existing supply sources.
- Multi-jurisdiction certification synchronization:Divergent GRAS self-affirmation, novel food, and feed additive approval timelines fragment product launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Amino Acids Market |
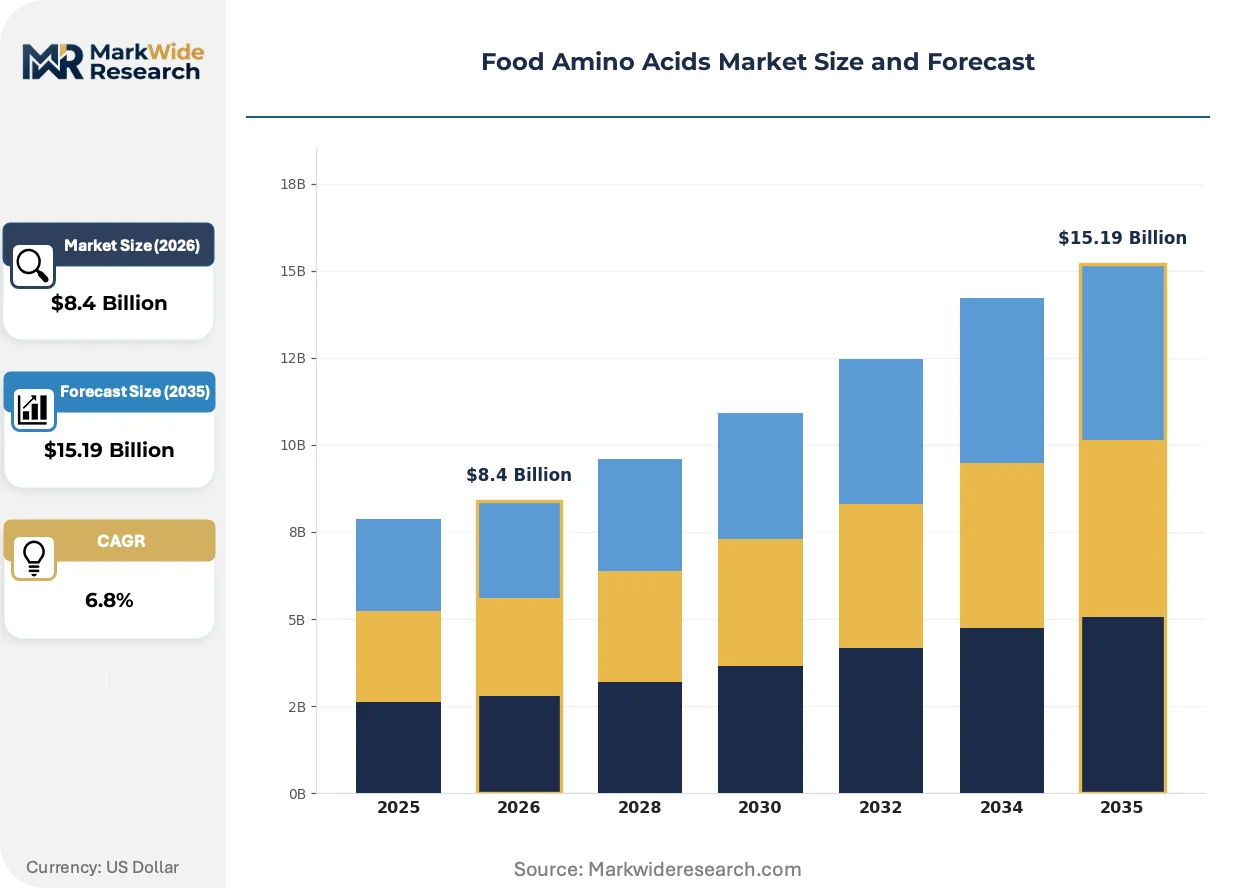
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamine, L-Leucine, L-Arginine, L-Valine Form: Powder, Liquid, Granule, Capsule Application: Nutritional Supplements, Animal Feed, Functional Foods, Sports Nutrition End User: Health Conscious Consumers, Athletes, Pets, Bodybuilders |
| Companies Covered | Archer-Daniels-Midland Company, Daesang Corporation, Ajinomoto Co., Inc., Fufeng Group Limited, Meihua Holdings Group Co., Ltd., Evonik Industries AG, CJ CheilJedang Corporation, Cargill, Incorporated, Kyowa Hakko Bio Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Amino Acids Market Emerging Trajectories
Precision fermentation and enzymatic synthesis technologies are compressing production economics while regulatory frameworks in major jurisdictions recalibrate purity and origin standards for human-grade applications.
Continuous fermentation systems with real-time metabolite monitoring are converging with AI-driven process control to enable dynamic nutrient feeding strategies. Mid-scale nutraceutical manufacturers in Germany and Japan are piloting these integrated platforms to reduce batch-to-batch variability. The technology is converging with traditional fed-batch methods to compress capital requirements for pharmaceutical-grade amino acid production.
The EU F-Gas Regulation is forcing adoption of ammonia-based and absorption cooling systems in fermentation facilities, raising capital intensity for new capacity. Manufacturers serving European infant formula and medical food markets must retrofit existing infrastructure or source from compliant third parties. This regulatory pressure is concentrating supply relationships with engineering firms possessing cryogenic and industrial refrigeration expertise.
Direct-to-consumer subscription models for personalized amino acid stacks are displacing traditional retail pharmacy and mass-market e-commerce channels. Wellness platforms in California and Seoul are bundling condition-specific premixes with biometric tracking services. This channel evolution is most visible in sports nutrition and longevity supplement verticals where consumer education investments justify premium positioning.
Food Amino Acids Market Segmentation
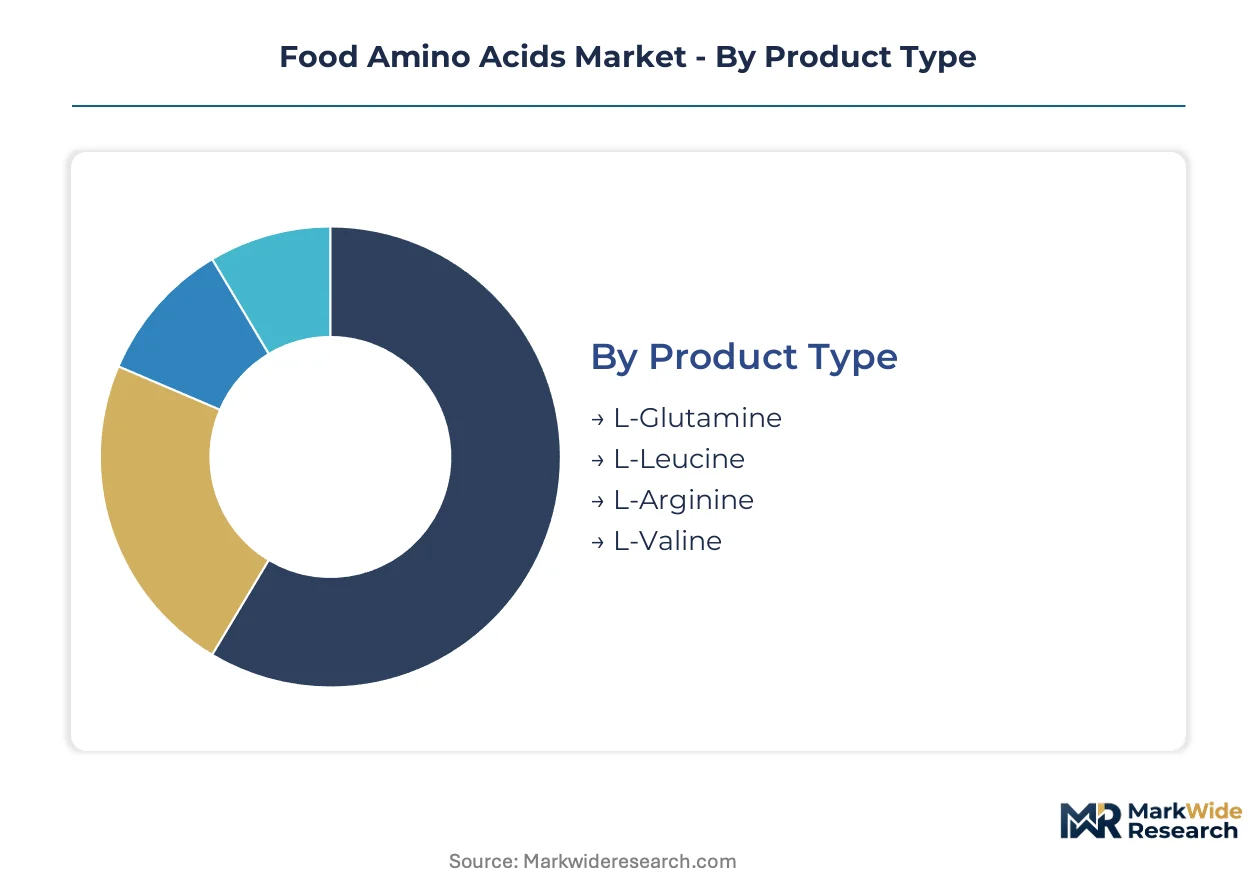
Amino acid specification tiers determine pricing power and regulatory pathway complexity across food, feed, and pharmaceutical applications. Manufacturers align fermentation scale and purity thresholds to specific segment requirements rather than pursuing universal production platforms.
Product Type:
Fermentation-derived amino acids separate into distinct purity grades and functional positioning based on carbon skeleton complexity and downstream processing intensity.
- L-Glutamine:Pharmaceutical-grade specifications demand 99.5% minimum purity with endotoxin controls for clinical nutrition and recovery protocols. Hospital formulary systems in Germany and Japan drive demand for intravenous-grade material, while sports nutrition channels absorb food-grade volumes for muscle preservation formulations.
- L-Leucine:Branched-chain amino acid with superior mTOR pathway activation for muscle protein synthesis. Infant formula manufacturers in the Netherlands and medical food compounders in the United States specify crystalline grades with heavy metal thresholds below 10 ppm, tightening supplier qualification requirements.
- L-Arginine:Nitric oxide precursor commanding premium positioning in cardiovascular and erectile dysfunction supplements. Korean nutraceutical brands and Brazilian pharmacy chains represent primary offtake channels for sustained-release formulations.
- L-Valine:BCAA component with lower standalone demand, typically blended with leucine and isoleucine in 2:1:1 ratios for sports nutrition premixes. Chinese feed compounders integrate valine into swine and poultry rations for stress reduction during transport.
Mature deployment sits with L-glutamine across clinical nutrition infrastructure. Newer deployment is concentrated in L-arginine for longevity and metabolic health positioning.
Form:
Physical presentation determines handling economics, shelf stability, and formulation flexibility across manufacturing environments.
- Powder:Dominant format for bulk handling and dry-blend compatibility. German nutraceutical contract manufacturers and Chinese feed mills specify powder for high-throughput mixing operations where flowability and caking resistance determine process efficiency.
- Liquid:Rapid-dissolution concentrates gaining share in ready-to-drink sports beverages. Convenience retail channels in Seoul and Los Angeles favor liquid shots for on-premise consumption, though cold chain requirements constrain distribution radius.
- Granule:Intermediate format for tableting operations and controlled-release formulations. Japanese pharmaceutical excipient suppliers specify granule flow properties for direct compression processes.
- Capsule:Pre-measured unit dosing for subscription wellness platforms and pharmacy retail. California-based personalized nutrition services bundle capsule stacks with biometric tracking applications.
Volume concentration remains in powder for industrial-scale compounding. Steepest expansion trajectory belongs to liquid formats in urban convenience retail.
Application:
End-use specifications diverge sharply between human consumption, animal nutrition, and clinical intervention contexts.
- Nutritional Supplements:Broad consumer wellness positioning with GRAS self-affirmation or novel food compliance requirements. Direct-to-consumer brands in the United Kingdom and Australia drive demand for condition-specific premixes targeting sleep, cognition, and immune function.
- Animal Feed:Lysine and methionine dominate volume, though glutamine and arginine gain traction for gut health and stress mitigation. Brazilian integrated pork operations and Vietnamese aquaculture facilities specify feed-grade amino acids for low-protein diet formulations.
- Functional Foods:Amino acid fortification in beverages, bars, and dairy alternatives. Spanish and Italian food processors incorporate leucine-enriched proteins for senior nutrition products targeting sarcopenia prevention.
- Sports Nutrition:Condition-specific premixes for muscle preservation, endurance, and recovery. Wellness retail expansion in France and Canada broadens addressable base beyond traditional bodybuilding channels.
Established penetration characterizes animal feed applications with price-sensitive procurement. Emerging traction concentrates in functional foods for demographic-specific nutrition.
End User:
Consumer segmentation reflects education level, performance orientation, and purchasing channel preference rather than demographic alone.
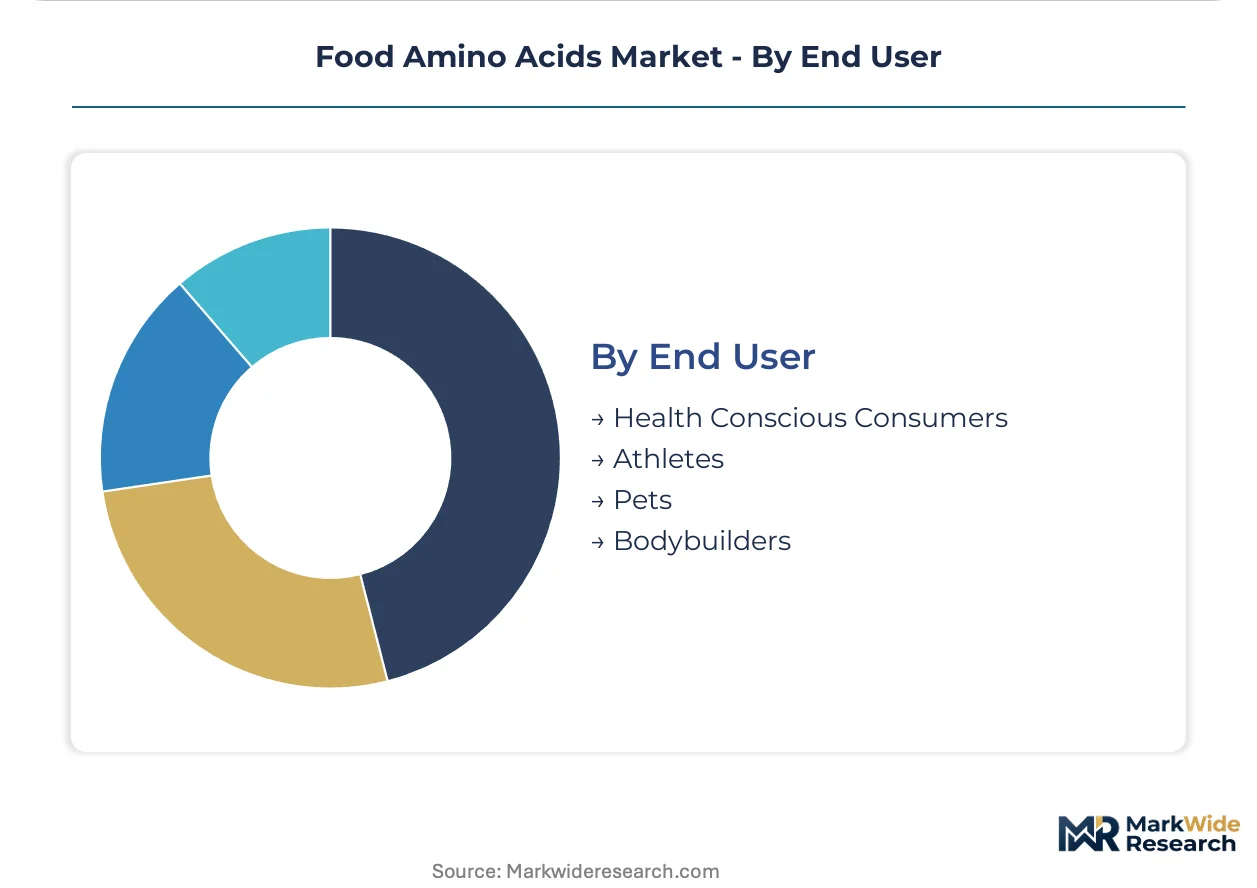
- Health Conscious Consumers:General wellness seekers purchasing through mass retail and e-commerce platforms. Subscription services in California and Seoul bundle personalized amino acid stacks with biomarker tracking.
- Athletes:Performance-optimized formulations with batch-tested certification for competitive compliance. NCAA and Olympic testing protocols drive demand for third-party verified products in the United States and Switzerland.
- Pets:Companion animal nutrition with amino acid profiles mimicking human sports nutrition trends. Premium pet food manufacturers in Japan and the United Kingdom incorporate taurine and arginine for cardiovascular support in aging animals.
- Bodybuilders:Traditional core segment with established brand loyalty and high per-capita consumption. Specialized retail in Eastern Europe and Middle Eastern gym ecosystems maintains dedicated distribution.
Legacy volume concentration sits with bodybuilders through specialized retail. Fastest-growing engagement emerges from health conscious consumers via subscription wellness platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhangjiagang Free Trade Zone and Jiangsu Special Economic Development Area concentrate Chinese lysine and glutamine fermentation capacity, drawing multinationals seeking integrated feedstock-to-finished-product infrastructure.
China
Domestic nutraceutical manufacturers and export-oriented animal feed compounders absorb the majority of lysine and glutamine output. SAMR enforces stricter purity and origin labeling for imported feed-grade materials. Heilongjiang and Shandong provinces host the largest fermentation clusters, where integrated producers serve both local supplement brands and international protein operations.
United States
Hospital formulary systems and sports nutrition brands drive pharmaceutical-grade L-glutamine demand. FDA GRAS self-affirmation pathways enable faster market entry for fermentation-derived amino acids versus European alternatives. California wellness platforms and Illinois-based contract manufacturers concentrate formulation and direct-to-consumer distribution capabilities.
Germany
Infant formula manufacturers and medical food compounders specify crystalline amino acid grades with heavy metal thresholds below 10 ppm. EFSA novel food evaluation timelines extend European market entry by 18-36 months relative to American pathways. Bavarian engineering firms and North Rhine-Westphalian chemical processors dominate cooling system retrofits under EU F-Gas Regulation mandates.
Japan
Pharmaceutical-grade intravenous L-glutamine for clinical recovery protocols commands premium positioning. METI coordinates industrial biomanufacturing policy with PMDA pharmaceutical oversight. Kansai region fermentation specialists and Tokyo-area nutraceutical formulators maintain integrated supply relationships with domestic hospital networks.
Brazil
Integrated pork operations and pharmacy chains absorb feed-grade lysine and sustained-release L-arginine supplements respectively. ANVISA regulates amino acid fortification in functional foods and sports nutrition products. São Paulo-state compounders and Paraná-based feed mills anchor South American distribution infrastructure.
Food Amino Acids Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade and infant formula supply, while mid-scale fermentation specialists and agricultural-commodity processors populate the standard and feed-grade tiers. Market structure reflects concentration in East Asian biomanufacturing capacity alongside Western formulation and certification expertise. Three archetypes dominate: integrated fermentation-to-finished-product conglomerates, pure-play amino acid specialists with crystallization technology advantages, and diversified agribusiness operators leveraging captive corn and sugar feedstock access. Competitive moves concentrate on long-term offtake agreements for fermentation capacity and retrofits of cooling infrastructure to satisfy EU F-Gas Regulation compliance.
Within the integrated fermentation tier, Ajinomoto Co., Inc. and CJ CheilJedang Corporation exemplify conglomerate structures spanning amino acid production through downstream protein and nutraceutical applications. Evonik Industries AG occupies a position among specialty chemical operators with precision crystallization capabilities for high-purity grades.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Daesang Corporation |
| Ajinomoto Co., Inc. |
| Fufeng Group Limited |
| Meihua Holdings Group Co., Ltd. |
| Evonik Industries AG |
| CJ CheilJedang Corporation |
| Cargill, Incorporated |
| Kyowa Hakko Bio Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Infant formula compounders and medical food manufacturers command premium pricing through multi-year offtake agreements, while feed-grade buyers negotiate spot-indexed contracts tied to corn futures volatility. This bifurcation concentrates margin protection upstream with fermentation specialists serving pharmaceutical-grade tiers.
Pricing Analysis
Short lead-time premiums apply to pharmaceutical-grade L-glutamine and crystalline L-leucine for hospital formulary systems, whereas spot inventory discounts characterize feed-grade lysine transactions. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels separates purity certification tiers with endotoxin controls and heavy metal thresholds. Cost compression in feed-grade segments is intensifying because Chinese fermentation capacity expansions outpace regional demand absorption. Animal feed compounders exhibit highest price sensitivity due to protein substitution alternatives, while clinical nutrition procurement shows lowest elasticity given patient safety requirements.
Supply Chain Analysis
EFSA novel food evaluations and FDA GRAS self-affirmation pathways gate market entry for fermentation-derived amino acids, extending qualification timelines for new suppliers. Manufacturing concentrates in China, Germany, and Japan, with Jiangsu and Heilongjiang provinces anchoring lysine and glutamine output. Raw material draws from corn and sugar feedstocks, fermentation process engineering talent, and precision crystallization equipment. Single-source vulnerability concentrates in East Asian fermentation clusters exposed to energy rationing directives. Distribution runs through integrated nutraceutical contract manufacturers and direct-to-consumer wellness platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity in pharmaceutical-grade tiers props pricing power for qualified suppliers, creating supply-constrained conditions through the forecast horizon.
For Market Incumbents: Deepen captive lysine and glutamine capacity in Heilongjiang and Shandong provinces to offset margin compression from Chinese environmental enforcement actions. Lock multi-year offtake agreements with European infant formula manufacturers ahead of EU F-Gas Regulation cooling retrofits. Prioritize precision crystallization R&D for branched-chain amino acid purity thresholds below 10 ppm heavy metal specifications. For New Entrants and Emerging Players: Begin with liquid concentrate formats for ready-to-drink sports beverage channels in Seoul and Los Angeles convenience retail, where cold chain infrastructure gaps deter incumbent powder specialists. Target underpenetrated North American hospital formulary systems for intravenous-grade L-glutamine. Pursue direct-to-consumer subscription bundling with biometric tracking services to bypass established pharmacy distribution. For Investors and Strategic Acquirers: The window for entry favors pure-play fermentation specialists with novel food approval progress in EFSA evaluation pipelines. Mid-cap biomanufacturers with ammonia-based cooling retrofits completed offer strongest 5-10 year positioning. Monitor SAMR purity labeling enforcement as inflection signal for import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU F-Gas Cooling Retrofit | First-mover advantage accrues to Bavarian engineering partnerships with cryogenic expertise. |
| Pharmaceutical-Grade Capacity Expansion | Ajinomoto fermentation technology leadership anchors clinical nutrition supply security. |
| Direct-to-Consumer Channel Launch | California wellness platforms displace traditional pharmacy retail through subscription bundling. |
| Long-Term Feedstock Supply Agreement | Corn and sugar offtake contracts with Shandong agricultural processors stabilize margin predictability. |
| Joint Venture with Crystallization Specialist | Evonik precision processes enable infant formula heavy metal compliance below 10 ppm thresholds. |
Methodological Framework
Multi-period observation of fermentation capacity utilization rates, EFSA novel food evaluation pipelines, and SAMR enforcement patterns anchored the trend analysis, supplemented by interviews with amino acid plant managers, nutraceutical procurement leads at German contract manufacturers, infant formula regulatory affairs directors, and hospital formulary pharmacists in Japan. Secondary validation drew from FDA GRAS notification databases, EFSA novel food catalog entries, Chinese customs trade data, and SEC 10-K filings of listed fermentation specialists. Bottom-up capacity modeling and top-down demand segmentation were triangulated for cross-verification.
Input-output matrices mapped fermentation substrate flows through crystallization intensity tiers to end-use price realizations across the projection horizon. Segmentation dimensions included purity grade tier, application context, physical form factor, and regional regulatory cluster. CAGRs were derived from capacity expansion schedules correlated with demand elasticity estimates by buyer archetype. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and Chinese dual carbon policy enforcement intensity.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications carry tighter precision than feed-grade volumes due to certification documentation density. Forecasts reflect documented assumptions on regulatory evaluation timelines and feedstock price correlation stability. A model refresh is warranted upon material change in SAMR import purity enforcement or EU Green Deal Farm to Fork traceability mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Beetroot Powder Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Potato Peel Powder Market
Ingredients
Mirepoix Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Horehound Extract Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Egg Membrane Powder Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Vegetable Powder Market
Ingredients
Jojoba Oil Market
Ingredients
Aroma Ingredients Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Coconut Oil Market