
 Vegetable Concentrates Market | 2026-2036
Vegetable Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Concentrates Market Analytics
Single-source reliance on fresh vegetable procurement is decoupling from concentrate manufacturing as processors build multi-origin supply networks. Cargill leverages backward integration into agricultural sourcing across multiple growing regions to secure raw material consistency. Ingredion anchors its position through R&D intensity in modified concentrate functionalities for beverage applications. Kerry Inc competes on flavor-system integration, combining vegetable concentrates with complementary taste technologies.
Vegetable concentrates are dehydrated or reduced-moisture products derived from tomatoes, carrots, spinach, beets, and other edible plants, typically processed through evaporation, spray drying, or aseptic concentration to achieve soluble solids content of 28–36 degrees Brix; they serve as shelf-stable flavor carriers, colorants, and nutritional fortifiers in formulated foods and drinks. Powder concentrates capture the widest margin pool due to lower transport costs and extended ambient stability versus puree or juice forms. The beverage industry segment leads volume absorption, while food processing applications sustain premium pricing for certified-organic and non-GMO concentrate grades.
EFSA sets maximum residue limits and additive rules that govern concentrate purity for European food manufacturers. The FDA enforces FSMA preventive controls on imported vegetable concentrates entering US processing facilities. India's FSSAI mandates labeling and contaminant thresholds that shape export-ready concentrate specifications for suppliers targeting South Asian markets. Stakeholders must monitor evolving pesticide residue standards and carbon-footprint disclosure requirements that will determine which concentrate suppliers retain preferred-vendor status with multinational food brands.
Market Dynamics
Clean-label reformulation mandates from EFSA and the EU Green Deal are compressing traditional fresh-procurement cycles, forcing beverage processors toward shelf-stable concentrate inputs with verified carbon-footprint credentials. This regulatory pressure is restructuring supplier relationships across the value chain.
Growth Catalysts
- EU Green Deal compliance deadlines:Food manufacturers in Germany accelerate concentrate adoption to meet Scope 3 emission reduction targets, bypassing fresh vegetable transport emissions.
- Beverage clean-label demand:North American processors replace artificial colorants with beet and carrot concentrates for natural hue stability in extended shelf-life products.
- Aseptic concentration technology:India-based exporters deploy advanced evaporation systems to achieve 28–36 Brix solids content for tropical climate distribution without cold chain dependency.
Market Restraints
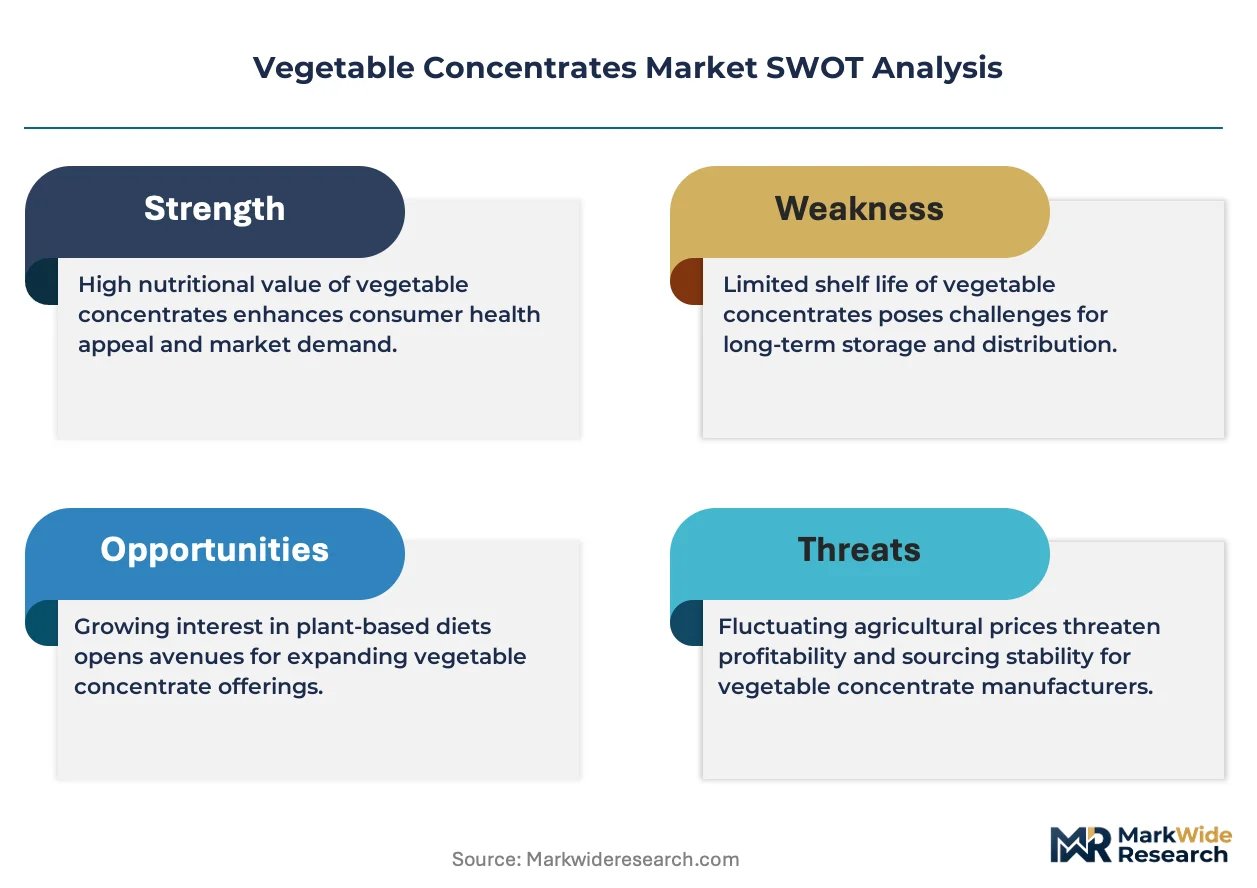
- Input cost volatility:Tomato concentrate processors face margin compression from irrigation water scarcity in California's Central Valley growing regions.
- Supply concentration risk:Single-origin spinach concentrate dependency on Maharashtra, India exposes buyers to monsoon failure and FSSAI contaminant enforcement variability.
- Substitution threat:Synthetic colorants and flavor modulators from fermentation-derived sources compete on price for non-organic beverage applications.
Strategic Opportunities
- Underpenetrated ready-to-drink soups:US meal-replacement brands seek carrot and butternut squash concentrates for ambient-stable savory beverage launches.
- CSRD disclosure mandates:European food brands require concentrate suppliers to provide verified carbon-footprint data, creating premium positioning for compliant processors.
- Direct-to-manufacturer e-procurement:Digital platforms connect Indian concentrate exporters with mid-sized European bakery chains, bypassing traditional importer margins.
Industry Challenges
- Specialized process engineering talent:Aseptic evaporation system operators with Brix calibration expertise command scarcity premiums in emerging production hubs.
- Organic certification timeline:Three-year transition periods for pesticide-free vegetable sourcing delay concentrate suppliers' access to premium-grade contracts.
- Legacy ERP integration:Batch traceability systems for concentrate lot tracking require costly middleware upgrades at family-owned European processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Concentrates Market |
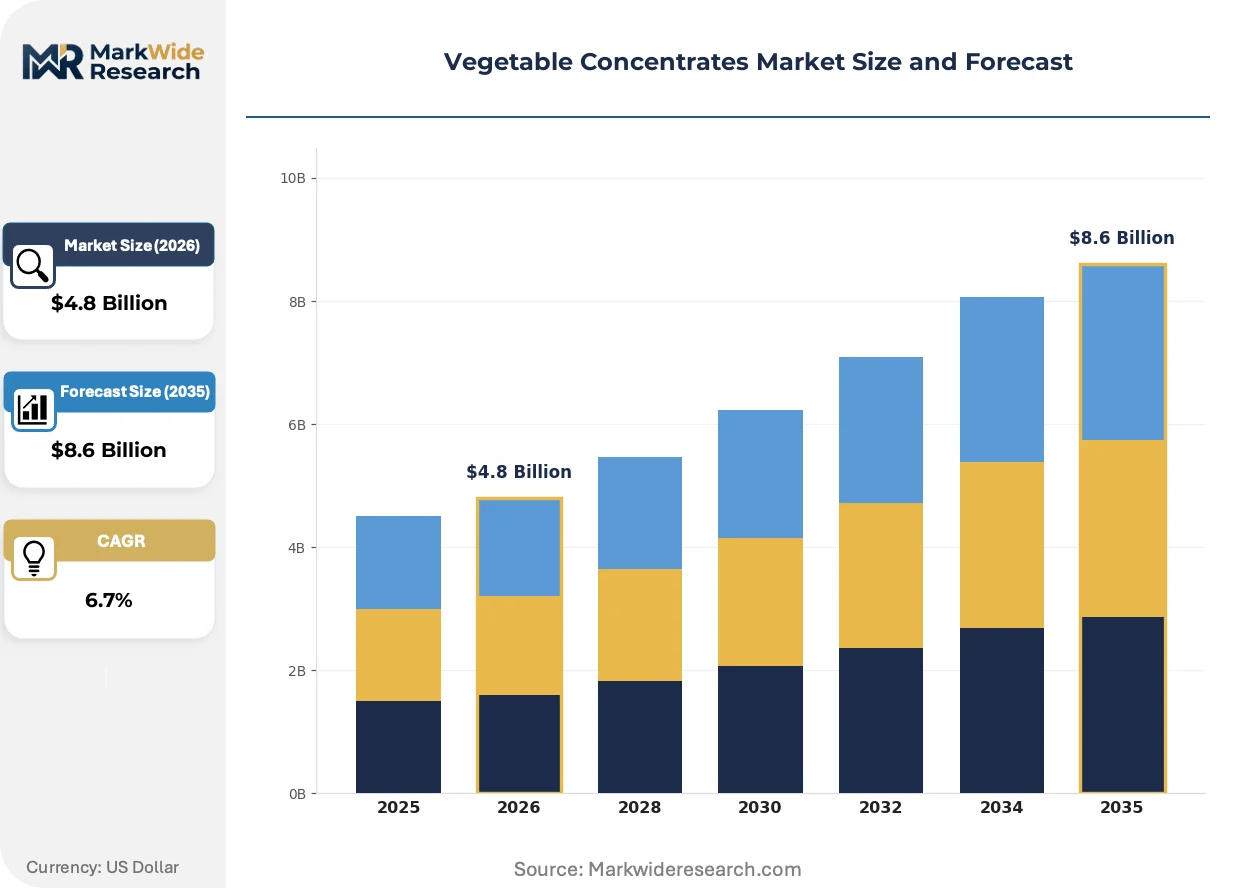
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Juice, Powder, Granule Packaging Type: Glass Bottle, Pouch, Tetra Pack, Bulk Container End User: Food Processing, Beverage Industry, Catering Services, Household Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Ingredion, Cargill, Döhler GmbH, SVZ Industrial Fruit & Vegetable Ingredients, Kerry Inc, Sensient Technologies Corporation, Tate & Lyle, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Concentrates Market Evolving Landscape
Pulse-drying and electrostatic spray technologies are compressing moisture removal timelines while preserving heat-sensitive phytonutrients. These advances are enabling new concentrate formats that expand beyond traditional beverage applications into functional food matrices.
Ohmic heating technology is electrifying vegetable concentrate production by applying direct electrical resistance to reduce thermal degradation of carotenoids and anthocyanins. Premium organic juice brands in Germany and the Netherlands adopt ohmic-processed concentrates at pilot scale. This thermal approach is electrifying competitive positioning for suppliers seeking EFSA-approved clean-label status without sulfite preservatives.
EFSA's updated maximum residue limits for pesticide metabolites in processed vegetables force concentrate exporters to implement multi-point testing protocols. The regulation compresses acceptable contamination thresholds for tomato and spinach concentrates entering European food manufacturing facilities. Indian and Turkish suppliers are responding by deploying blockchain-integrated farm-to-facility traceability systems to document compliance.
Ingredient sourcing teams at multinational food brands now mandate carbon-footprint disclosure alongside price and quality metrics in concentrate procurement evaluations. Direct supplier relationships are replacing spot-market purchasing for organic-certified tomato and beet concentrates. This behavioral shift is most pronounced among German and French retail private-label programs with 2030 net-zero commitments.
Vegetable Concentrates Market Segmentation
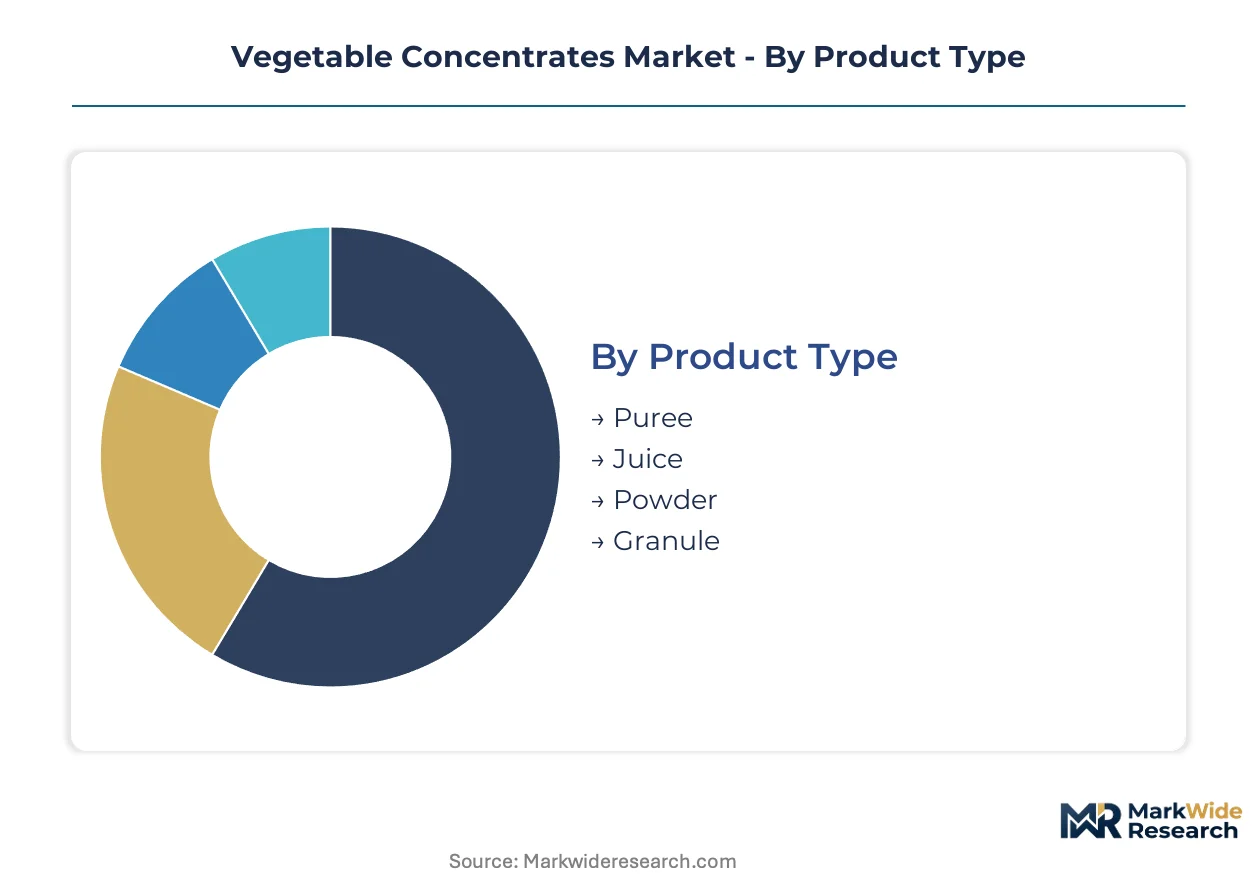
Segmentation in vegetable concentrates reveals how processing intensity, packaging economics, and channel access determine margin capture. Buyers upgrade across formats based on shelf-life requirements, transport cost thresholds, and clean-label positioning needs.
Product Type:
Upgrade cycles in product type track the trade-off between moisture removal investment and downstream logistics savings, with beverage manufacturers driving the shift toward lower-weight formats.
- Powder:Spray-dried or drum-dried concentrates achieve sub-5% moisture content, enabling ambient storage and containerized ocean freight without cold chain dependency. German beverage compounders and US meal-replacement brands absorb volume for dry-blend manufacturing, paying freight savings forward into procurement premiums for certified-organic grades.
- Juice:Aseptically concentrated to 28–36 degrees Brix, juice forms retain volatile aromatic compounds for flavor-critical applications. Indian exporters deploy advanced evaporation to serve tropical markets where powder reconstitution infrastructure remains underdeveloped.
- Puree:Single-strength or lightly concentrated vegetable purees serve prepared food manufacturers requiring texture body in sauces and soups.
- Granule:Agglomerated particles improve dispersibility in instant beverage applications.
Powder sits at the top of the volume ranking, with granule climbing the fastest as instant-format brands seek improved solubility.
Packaging Type:
Packaging selection concentrates margin in formats that reconcile food safety validation with freight cube optimization, diverging sharply between retail-facing and industrial procurement.
- Bulk Container:Aseptic bag-in-drum or bag-in-box systems for 200–1000 liter payloads dominate ingredient procurement by European dairy and beverage processors. The format eliminates glass handling costs and enables pump-off direct-to-mixing operations.
- Tetra Pack:Multilayer aseptic cartons with aluminum foil barriers extend ambient shelf life for retail juice concentrates. German and Dutch retail private-label programs specify this format for organic carrot and beet concentrates.
- Glass Bottle:Premium positioning for specialty food retail and gift segments.
- Pouch:Flexible stand-up formats for single-use foodservice portions.
Bulk container commands the highest procurement volume, with Tetra Pack gaining share fastest in retail organic certification tiers.
End User:
End-user segmentation reflects diverging technical specifications between industrial scale formulation and small-batch preparation, with regulatory compliance burden varying sharply across categories.
- Beverage Industry:Clean-label reformulation drives concentrate absorption for natural color stability and flavor carriers in extended shelf-life products. North American processors replace synthetic dyes with beet and carrot concentrates, while EU Green Deal compliance accelerates Scope 3 emission reductions through concentrate logistics savings.
- Food Processing:Prepared sauce, soup, and baby food manufacturers specify low-microbial-load concentrates with documented pesticide residue compliance. FSSAI thresholds shape export-ready specifications for Indian suppliers targeting South Asian markets.
- Catering Services:Institutional kitchens prioritize portion-control formats and reconstitution speed.
- Household:Retail concentrate sales for home cooking remain concentrated in specialty and ethnic food channels.
Beverage Industry leads procurement volume, with Food Processing expanding most quickly as clean-label mandates penetrate prepared food categories.
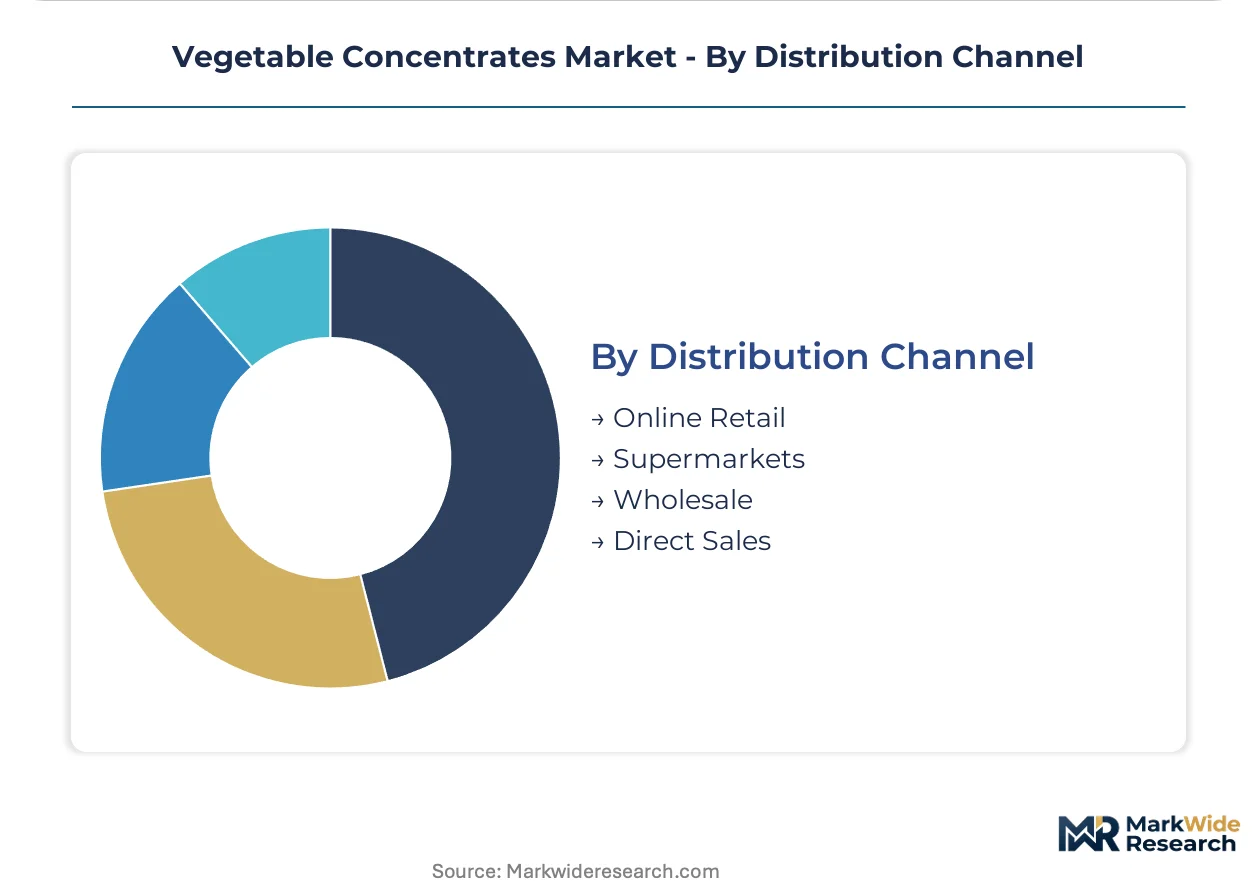
Distribution Channel:
Channel structure determines working capital intensity and traceability burden, with direct procurement relationships displacing spot-market purchasing among carbon-footprint-conscious buyers.
- Direct Sales:Long-term supply agreements between concentrate processors and multinational food brands enable verified carbon-footprint documentation for CSRD disclosure compliance. German and French retail private-label programs with net-zero commitments mandate this channel for organic-certified tomato and beet concentrates.
- Wholesale:Distributor networks serve mid-sized European bakery chains and regional beverage processors requiring smaller lot sizes and consolidated sourcing.
- Online Retail:Digital platforms connect Indian exporters directly with European buyers, bypassing traditional importer margins.
- Supermarkets:Retail shelf presence for household-format concentrates in specialty food aisles.
Direct Sales captures the highest procurement value, with online retail ascending fastest as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's beverage compounding cluster around Hamburg anchors procurement volume for clean-label reformulation, with processors substituting fresh vegetable inputs for carbon-verified concentrates to meet CSRD disclosure deadlines.
Germany
Beverage manufacturers in Hamburg and Munich accelerate concentrate absorption to bypass fresh-procurement emissions under EU Green Deal Scope 3 targets. EFSA maximum residue limits for pesticide metabolites compress acceptable thresholds for tomato and spinach concentrates entering German processing facilities. Ingredient sourcing teams at retail private-label programs in Bavaria mandate direct supplier relationships with verified carbon-footprint documentation.
United States
Meal-replacement brands in California and ready-to-drink soup processors in the Midwest drive demand for carrot and butternut squash concentrates in ambient-stable savory beverage launches. FDA preventive controls under FSMA govern imported concentrate purity for US food manufacturing facilities. Tomato concentrate processors in California's Central Valley face margin pressure from irrigation water scarcity affecting raw material costs.
India
Exporters in Maharashtra and Gujarat deploy advanced evaporation systems to achieve 28–36 Brix solids content for tropical climate distribution without cold chain dependency. FSSAI labeling mandates and contaminant thresholds shape export-ready specifications for suppliers targeting South Asian markets. Pune-based processors build multi-origin supply networks to reduce single-origin spinach concentrate dependency on monsoon-exposed growing regions.
Netherlands
Organic juice brands in Rotterdam and Amsterdam pilot ohmic-heated concentrates for EFSA-approved clean-label status without sulfite preservatives. EU Green Deal reformulation deadlines compress traditional fresh-procurement cycles toward shelf-stable inputs. Dutch retail private-label programs with 2030 net-zero commitments mandate carbon-footprint disclosure alongside price and quality metrics in concentrate procurement evaluations.
France
Food processing facilities around Lyon and Paris specify low-microbial-load concentrates with documented pesticide residue compliance for prepared sauce and baby food manufacturing. ECHA REACH regulations govern chemical inputs in concentrate processing equipment and packaging materials. French retail chains accelerate direct-to-manufacturer e-procurement relationships with Indian exporters to bypass traditional importer margins.
Vegetable Concentrates Market Competitive Landscape
Global majors compete with regional champions across supply chain integration and clean-label certification tiers. The vendor base separates into three distinct strata: multinational ingredient conglomerates with backward integration into agricultural sourcing, mid-scale European specialists in flavor-system integration, and Asia-Pacific exporters leveraging aseptic concentration technology for tropical distribution. Consolidation pressure intensifies around carbon-footprint verification capabilities and organic certification timelines. Dominant competitive moves include strategic partnerships for farm-to-facility traceability and capacity expansion in low-cost production hubs.
Among North American-based conglomerates, Cargill and Archer Daniels Midland Company occupy positions anchored by multi-region agricultural sourcing networks. European specialists including Döhler GmbH and SVZ Industrial Fruit & Vegetable Ingredients exemplify the flavor-system integration archetype, while Kerry Inc represents the premium-tier positioning built on complementary taste technologies. Ingredion anchors the modified concentrate functionality segment through R&D intensity in beverage applications. These named entities sit within a competitive matrix where EFSA compliance capabilities and CSRD-ready carbon disclosure increasingly determine preferred-vendor status with multinational food brands.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion |
| Cargill |
| Döhler GmbH |
| SVZ Industrial Fruit & Vegetable Ingredients |
| Kerry Inc |
| Sensient Technologies Corporation |
| Tate & Lyle |
| Givaudan |
| Others |
Value Network & Pricing Analysis
Multinational beverage compounders in Germany and North America command pricing leverage through long-term offtake agreements, locking in volume discounts that compress margins for spot-market suppliers. This buyer concentration forces tiered pricing structures where organic-certified concentrates capture substantial premiums over conventional grades.
Pricing Analysis
Input-cost pass-through from irrigation water scarcity in California's Central Valley and monsoon-dependent spinach growing regions in Maharashtra compresses processor margins. Three-tier pricing structure across premium, standard, and economy levels separates EU organic-certified grades from conventional industrial inputs and commodity spot offerings. Price differentiation hinges on carbon-footprint verification and FSSAI contaminant compliance tiers. Pricing pressure stems from synthetic colorant substitution threats in non-organic beverage applications. Mid-sized European bakery chains exhibit highest price sensitivity, while German retail private-label programs with net-zero commitments show lowest sensitivity for CSRD-compliant documentation.
Supply Chain Analysis
EFSA maximum residue limits and organic certification requirements gate supplier eligibility for European food manufacturing facilities. Geographic supply concentration centers on India, Germany, and the United States, with Maharashtra and Gujarat anchoring aseptic evaporation capacity. Raw material dependencies draw from tomato, carrot, and spinach cultivation networks vulnerable to climate volatility. Single-origin spinach concentrate dependency on monsoon-exposed Indian growing regions creates supply chain risk. Distribution runs through direct sales agreements for carbon-verified grades and wholesale networks for standard-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vegetable concentrates rests on logistics cost savings from powder format adoption and premium pricing for EFSA-compliant organic grades with verified carbon footprints.
For Market Incumbents: Anchor market position through backward integration into multi-origin agricultural sourcing across California, Maharashtra, and Mediterranean growing regions to mitigate climate exposure. Invest in ohmic heating and pulse-drying R&D to preserve heat-sensitive phytonutrients for clean-label positioning. Defend against synthetic fermentation-derived colorants by accelerating organic certification timelines and blockchain-integrated traceability deployment. For New Entrants and Emerging Players: The price-point gap between premium organic-certified concentrates and economy-grade conventional inputs offers white-space opportunity in mid-tier carbon-verified grades. Target underpenetrated ready-to-drink soup applications in US meal-replacement channels with carrot and butternut squash concentrate formulations. Deploy direct-to-manufacturer e-procurement platforms to bypass traditional importer margins and capture mid-sized European bakery chain accounts. For Investors and Strategic Acquirers: Beverage ingredient conglomerates with backward integration capabilities are the most active acquirer in this space, seeking carbon-footprint verification assets. Long-term viability over a five-to-ten year window favors processors with CSRD-ready disclosure systems and multi-origin supply networks. Acquisition target archetype: mid-scale European specialists in flavor-system integration with EFSA compliance infrastructure. Monitor CSRD disclosure mandate enforcement as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Cargill's multi-region sourcing networks secure raw material consistency against climate volatility. |
| Ohmic Heating Technology Deployment | Dutch organic juice brands pilot electrical resistance processing for sulfite-free clean-label concentrates. |
| Blockchain-Integrated Farm Traceability | Indian exporters document EFSA pesticide compliance through integrated farm-to-facility tracking systems. |
| Direct-to-Manufacturer E-Procurement | Digital platforms connect Maharashtra processors with European buyers, eliminating importer margin layers. |
| Carbon-Footprint Verification Investment | German retail private-label programs mandate verified documentation for Scope 3 emission reduction targets. |
Research Methodology
Multiple input streams — executive interviews with concentrate processors, procurement leads at multinational beverage brands, and regulatory affairs specialists — were reconciled against customs trade data, EFSA guidance documents, and FSSAI contaminant threshold notifications. Primary fieldwork with plant managers at aseptic evaporation facilities, category buyers at German retail chains, and agricultural sourcing directors informed operational cost structures. Secondary validation drew from EU Green Deal policy releases, FDA FSMA preventive control guidelines, and SEC filings of listed ingredient conglomerates. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Data-stream reconciliation across product type, packaging format, end-use application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included irrigation water cost trajectories in California's Central Valley and organic certification transition timelines for Indian vegetable sourcing networks.
The model assumes a particular technology adoption path; alternative pathways for ohmic heating and electrostatic spray drying would alter the outlook for heat-sensitive nutrient preservation. Forecasts reflect assumptions around EFSA maximum residue limit enforcement intensity and EU Green Deal Scope 3 compliance deadlines. A model refresh is warranted upon material change in CSRD disclosure mandate implementation or California agricultural water allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Canola Meal Market
Ingredients
Cottonseed Oil Market
Ingredients
Soy Derivatives Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
High Protein Flour Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Egg Free Premix Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Rooster Comb Extract Market
Ingredients
Almond Ingredients Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Bread Flour Market
Ingredients
Global Dry Yeast Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Middle East and Africa Dairy Ingredients Market