
 African Brewing Enzymes Market | 2026-2036
African Brewing Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
African Brewing Enzymes Market Outlook
The capital-intensity divergence between integrated multinationals and regional distributors is redrawing competitive boundaries in African brewing enzymes. DuPont de Nemours Inc. leverages its global fermentation technology portfolio to supply high-purity amylase formulations to large-scale breweries in South Africa and Nigeria. Kerry Group PLC anchors its position through direct technical service teams stationed in Nairobi and Lagos, offering on-site enzyme optimization for malt processing clients. Porex SA (Biochem) competes primarily on logistics agility, maintaining regional warehousing that cuts delivery lead times for craft breweries across sub-Saharan Africa.
Brewing enzymes are specialized protein catalysts—predominantly amylase, protease, glucoamylase, and β-glucanase—derived from microbial fermentation or plant extraction, functioning optimally at specific temperature and pH ranges to accelerate starch conversion and protein solubilization during mashing and fermentation. Their primary commercial purpose is to enhance extract yield, accelerate brewing cycles, and enable the use of adjunct grains such as sorghum and maize that dominate African grist bills. Amylase commands the largest volume share because no commercial brewery can achieve complete starch liquefaction without thermal-stable alpha-amylase, while β-glucanase is expanding fastest as brewers process more unmalted barley and adjuncts with high β-glucan content that cause lautering problems. Craft breweries represent the most contested end-user segment because their smaller batch sizes and variable grain bills demand customized enzyme dosing protocols that carry higher technical service margins than standardized supply contracts with multinational beverage companies.
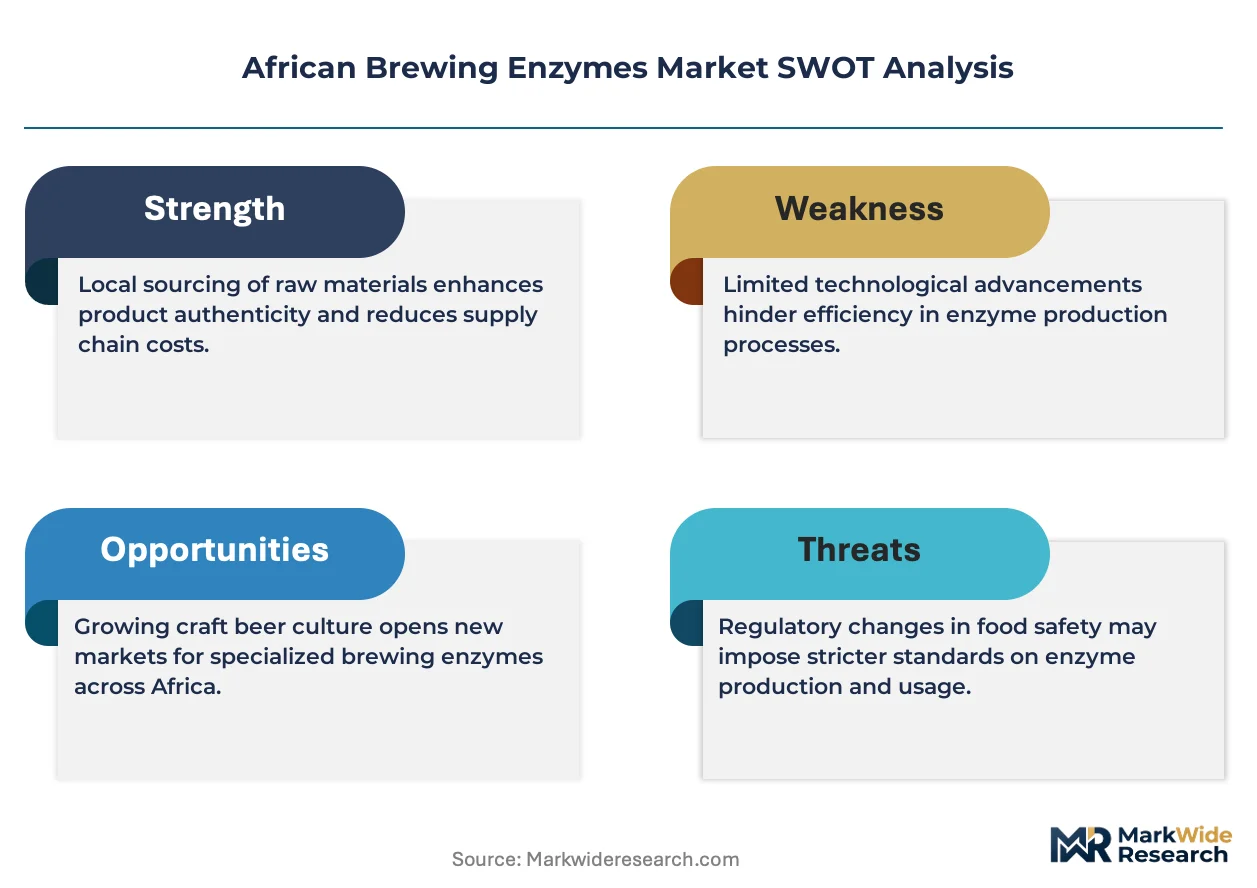
National food safety regulators across Africa—including South Africa's Department of Health, Nigeria's National Agency for Food and Drug Administration and Control, and Kenya's Bureau of Standards—are harmonizing enzyme import specifications with Codex Alimentarius guidelines, which raises compliance costs for uncertified suppliers while creating preferential access for ISO 22000-certified manufacturers. The African Continental Free Trade Area's phased tariff reductions on processed food inputs are lowering cross-border enzyme shipment costs between member states, reshaping distribution channel economics for wholesalers operating multi-country portfolios. Stakeholders must monitor how rapidly evolving national biotechnology regulations classify genetically modified microbial strains used in enzyme production, as this classification determines registration pathways and labeling requirements that could disrupt established supply relationships.
Market Dynamics
The African brewing enzymes market is being fundamentally restructured by the convergence of adjunct-heavy grist formulations and tightening import certification standards that favor ISO 22000-certified suppliers over uncertified traders.
Growth Catalysts
- Sorghum and maize adjunct processing:Commercial breweries across Nigeria and Kenya require thermal-stable alpha-amylase to liquefy high-starch adjuncts that now dominate African grist bills, driving volume demand for specialized enzyme formulations.
- African Continental Free Trade Area tariff reductions:Phased elimination of duties on processed food inputs between member states is lowering cross-border shipment costs for enzyme distributors operating multi-country portfolios.
- Codex Alimentarius harmonization:South Africa's Department of Health and Nigeria's National Agency for Food and Drug Administration and Control are aligning enzyme import specifications with international food safety guidelines, creating preferential market access for certified manufacturers.
Market Restraints
- Input cost volatility:Fermentation-derived enzymes depend on microbial substrate costs that fluctuate with global carbohydrate feedstock markets, compressing margin predictability for regional formulators.
- Supply concentration risk:High-purity amylase production concentrates among integrated multinationals with captive fermentation capacity, leaving African craft breweries dependent on imported formulations with extended lead times.
- Genetically modified strain classification uncertainty:Evolving national biotechnology regulations across the continent create registration pathway ambiguity for enzymes produced from GM microbial hosts, delaying product approvals.
Strategic Opportunities
- Ethiopian commercial brewing expansion:New malt beverage production facilities in Addis Ababa and Hawassa are commissioning enzyme-optimized processing lines without legacy equipment constraints, creating greenfield specification opportunities.
- Technical service unbundling:Craft breweries in Lagos and Nairobi are separating enzyme supply contracts from on-site optimization services, enabling specialized consultants to capture higher-margin dosing protocol development.
- East African beverage cluster consolidation:Kenya's Bureau of Standards is accelerating food-grade enzyme import approvals for manufacturers demonstrating HACCP compliance, shortening time-to-market for certified entrants.
Industry Challenges
- Enzyme dosing optimization skill scarcity:Craft brewery operators lack trained brewing chemists capable of calibrating variable grain bill formulations, forcing reliance on supplier technical teams that extend response cycles.
- Multi-standard certification complexity:Suppliers must simultaneously satisfy South African Department of Health, NAFDAC, and Kenya Bureau of Standards requirements that lack mutual recognition, multiplying compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | African Brewing Enzymes Market |
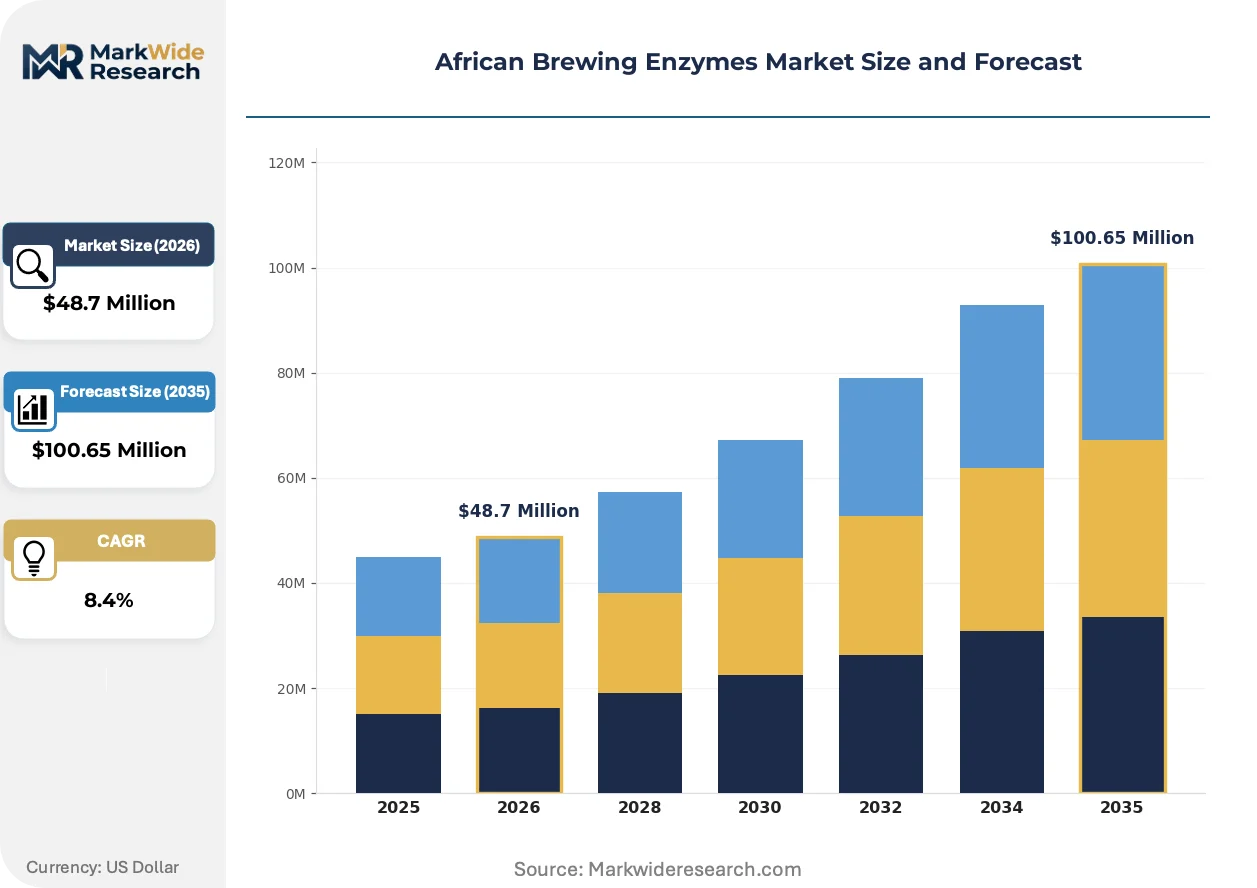
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Glucoamylase, β-Glucanase Application: Beer Production, Malt Processing, Distilled Spirits, Fermentation End User: Craft Breweries, Large Scale Breweries, Beverage Companies, Research Institutions Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | AEB Africa (PTY) Ltd, BrewCraft Int., DuPont de Nemours Inc., DSM, Lallemand Inc., Kerry Group PLC, Porex SA (Biochem), AB Enzymes, Novozymes A/S, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
African Brewing Enzymes Market Strategic Shifts
Thermostable enzyme engineering and regional regulatory harmonization are compressing the competitive window for traditional supply models while reshaping how African breweries source and deploy processing aids.
Recombinant alpha-amylase variants with extended temperature stability are displacing conventional fungal-derived formulations in large-scale Nigerian and South African breweries. These engineered catalysts maintain activity across broader pH ranges, enabling simultaneous liquefaction of mixed adjunct streams. Integrated multinationals with proprietary strain libraries are capturing specification lock-in as brewers retrofit brewhouses for higher-temperature mashing protocols.
South Africa's Department of Health is implementing BIS-equivalent national standards for food-grade enzyme imports that mandate ISO 22000 certification and batch-level traceability documentation. This regulatory tightening is systematically excluding uncertified trading houses that previously supplied informal craft segments. Kenyan and Ethiopian regulators are observing this framework for potential adoption, signaling continent-wide compliance elevation.
Craft breweries in Lagos, Nairobi, and Cape Town are fragmenting their supplier relationships, separating bulk enzyme procurement from technical service contracts that were historically bundled. This unbundling is compressing distributor margins on commodity formulations while elevating specialist consultancies that deliver customized dosing protocols. The shift is most pronounced among 10,000-50,000 hectoliter annual capacity operations with variable grain bills and no in-house brewing chemistry expertise.
African Brewing Enzymes Market Segmentation
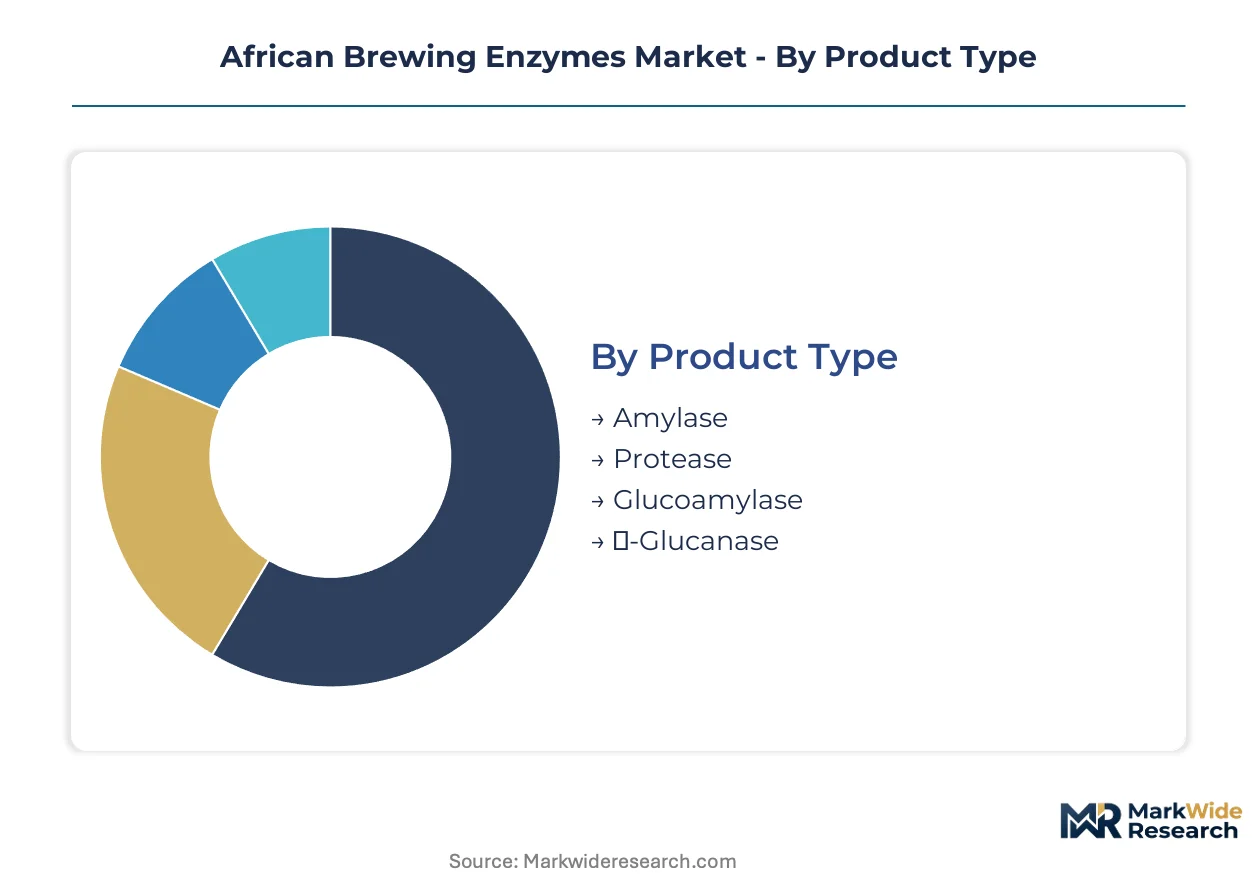
Brewing enzyme procurement patterns in Africa diverge sharply by customer scale and technical sophistication. Large-scale breweries in South Africa and Nigeria negotiate direct supply contracts with integrated multinationals, while craft operators across sub-Saharan Africa depend on fragmented distributor networks with extended technical service cycles.
Product Type:
Channel economics vary substantially across enzyme categories—amylase and glucoamylase move primarily through direct sales to multinational breweries, while protease and β-glucanase formulations reach craft segments via regional distributors with technical support capabilities.
- Amylase:Thermal-stable alpha-amylase formulations catalyze starch liquefaction in high-temperature mashing protocols. Demand concentrates among large-scale breweries in Nigeria and South Africa processing sorghum and maize adjuncts that require aggressive starch breakdown. South Africa's Department of Health ISO 22000 certification requirements favor established suppliers with batch-level traceability documentation.
- β-Glucanase:Enzymes targeting β-glucan polymers in unmalted barley and adjunct grains. Nairobi and Lagos craft breweries are expanding adoption fastest to resolve lautering problems from variable grain bills, though dosing optimization skill scarcity extends supplier response cycles. Kenya's Bureau of Standards is accelerating import approvals for HACCP-compliant manufacturers.
- Protease:Protein-solubilizing catalysts derived from microbial fermentation, primarily serving malt processing applications in Ethiopian commercial brewing expansion.
- Glucoamylase:Saccharification enzymes completing starch-to-sugar conversion, standardized formulations supplied through direct sales channels to beverage companies with captive technical teams.
By volume, amylase leads. By growth pace, β-glucanase is climbing the fastest.
Application:
Margin structures align with application complexity—beer production commands premium pricing for customized dosing protocols, while fermentation applications standardize around commodity formulations with compressed distributor margins.
- Beer Production:Enzyme deployment spans mashing, lautering, and fermentation stages with formulation customization for adjunct-heavy grist bills. Large-scale Nigerian breweries are retrofitting brewhouses for recombinant alpha-amylase variants with extended temperature stability, locking in specification relationships with proprietary strain libraries.
- Malt Processing:Diastatic enzyme applications in commercial malting facilities, concentrated in Ethiopia's expanding production clusters in Addis Ababa and Hawassa where greenfield specification opportunities exist without legacy equipment constraints.
- Distilled Spirits:High-gravity fermentation enzyme formulations for ethanol production, primarily serving East African beverage manufacturing.
- Fermentation:Standardized enzyme additions accelerating yeast metabolism, procured through bulk supply contracts with minimal technical service components.
Beer production generates the highest service-margin capture. Malt processing offers the steepest expansion trajectory from greenfield capacity.
End User:
Customer scale determines procurement modality—multinational beverage companies centralize purchasing through global supply agreements, while craft breweries fragment relationships between bulk procurement and specialized technical consultancies.
- Craft Breweries:10,000-50,000 hectoliter annual capacity operations with variable grain bills and no in-house brewing chemistry expertise. Lagos, Nairobi, and Cape Town operators are unbundling enzyme supply from on-site optimization services, elevating specialist consultancies for dosing protocol development.
- Large Scale Breweries:Integrated multinationals with captive fermentation capacity and direct supplier relationships, primarily in South Africa and Nigeria where thermal-stable alpha-amylase specifications lock in proprietary formulations.
- Beverage Companies:Diversified drinks manufacturers with centralized procurement functions and standardized enzyme specifications across multiple production facilities.
- Research Institutions:Academic and development centers testing novel enzyme applications, minimal commercial volume but influence on regulatory acceptance pathways.
Large scale breweries dominate volume absorption. Craft breweries are fragmenting procurement fastest.
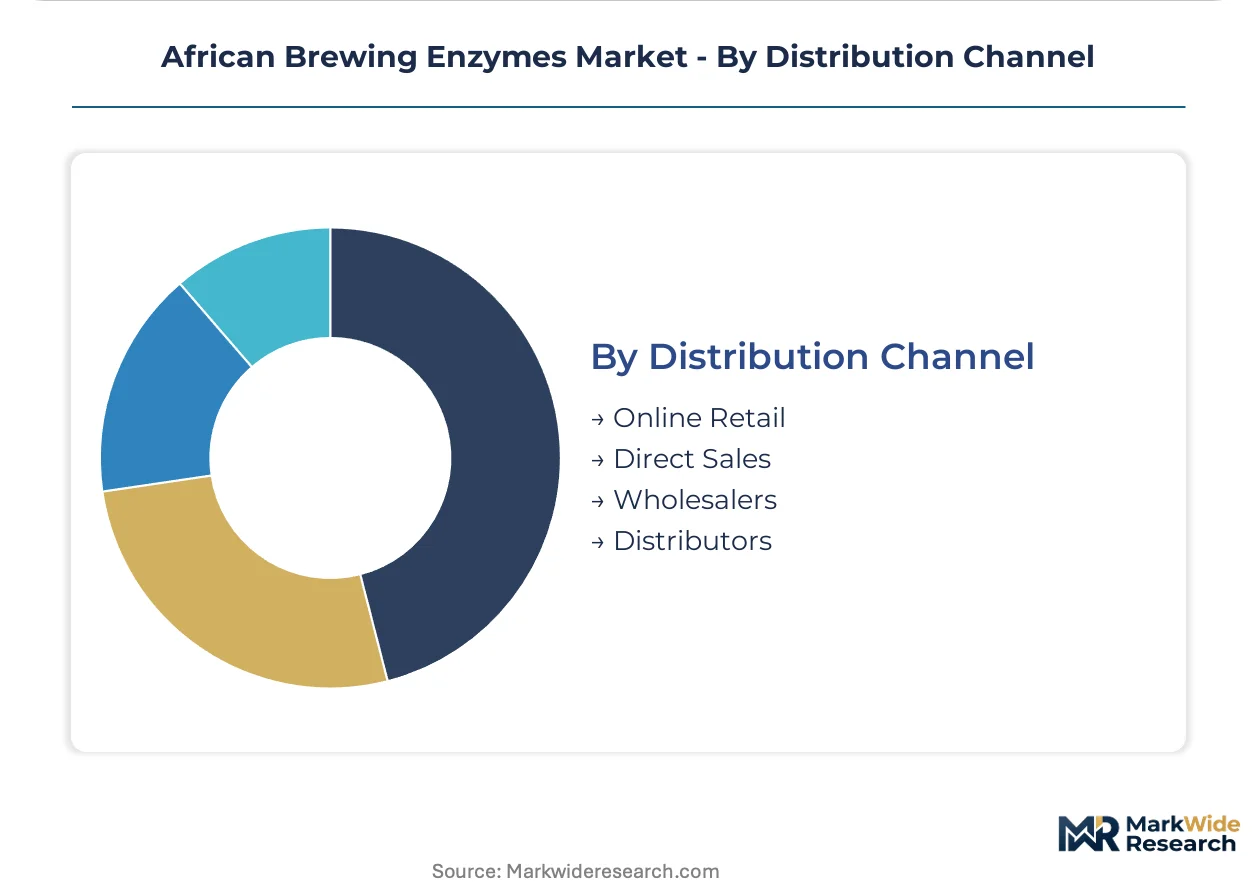
Distribution Channel:
Geographic coverage requirements and technical service intensity shape channel selection—direct sales anchor multinational relationships while regional warehousing determines craft segment competitiveness.
- Direct Sales:Supplier technical teams stationed in Nairobi and Lagos delivering on-site enzyme optimization for malt processing clients, capturing higher margins than standardized supply contracts.
- Distributors:Regional warehousing networks cutting delivery lead times for craft breweries across sub-Saharan Africa, competing primarily on logistics agility.
- Wholesalers:Multi-country portfolio operators benefiting from African Continental Free Trade Area tariff reductions on processed food inputs between member states.
- Online Retail:Emerging channel for standardized enzyme formulations with documented specifications, limited by cold-chain requirements and technical consultation needs.
Direct sales capture the highest margin per liter. Distributor networks are expanding geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands pricing leverage over Nigerian buyers due to mature certification infrastructure and concentrated multinational supply relationships. East African markets are compressing procurement costs through regional warehousing networks that bypass traditional import channels.
South Africa
Large-scale breweries in Johannesburg and Cape Town process sorghum-heavy grist bills requiring thermal-stable alpha-amylase formulations. The Department of Health enforces ISO 22000 certification and batch-level traceability for all food-grade enzyme imports. Durban's commercial brewing cluster is retrofitting brewhouses for recombinant enzyme variants with extended temperature stability ranges.
Nigeria
Lagos-based craft breweries are fragmenting procurement relationships between bulk supply and technical service contracts. NAFDAC aligns enzyme import specifications with Codex Alimentarius guidelines, raising compliance barriers for uncertified traders. New malt beverage facilities in Ibadan are commissioning enzyme-optimized processing lines without legacy equipment constraints.
Kenya
Nairobi's beverage manufacturing cluster is expanding commercial brewing capacity fastest in East Africa. The Bureau of Standards accelerates food-grade enzyme import approvals for HACCP-compliant manufacturers, shortening time-to-market. Mombasa distributors are leveraging African Continental Free Trade Area tariff reductions to cut cross-border shipment costs for regional portfolios.
Ethiopia
Addis Ababa and Hawassa are commissioning greenfield malt processing facilities with enzyme-optimized production lines. The country's national food safety regulator is observing South Africa's BIS-equivalent standards framework for potential adoption. These new commercial brewing installations specify thermal-stable formulations without retrofitting legacy equipment.
Ghana
Accra's emerging craft brewing segment is importing β-glucanase formulations to resolve lautering problems from variable unmalted barley bills. The country's food and drugs authority maintains import documentation requirements that favor ISO-certified suppliers over informal trading channels. Tema's logistics hub is attracting regional enzyme distributors seeking West African coverage expansion.
African Brewing Enzymes Market Competitive Environment
Concentration sits with integrated multinationals possessing captive fermentation capacity and proprietary strain libraries. Regional distributors compete on logistics agility and warehousing proximity rather than manufacturing scale. Three archetypes dominate: global biotechnology conglomerates with direct brewery relationships, regional formulators serving craft segments, and specialized technical service providers. Competitive moves center on certification compliance investments and geographic warehousing expansion rather than price undercutting.
Among the integrated multinational tier, DuPont de Nemours Inc. and DSM exemplify archetypes leveraging global fermentation technology portfolios for specification lock-in with large-scale breweries. Kerry Group PLC occupies a position emphasizing direct technical service deployment. Regional logistics specialists including Porex SA (Biochem) represent the agility-focused competitive vector competing on delivery lead time compression across sub-Saharan craft segments.
| Leading Market Players |
|---|
| AEB Africa (PTY) Ltd |
| BrewCraft Int. |
| DuPont de Nemours Inc. |
| DSM |
| Lallemand Inc. |
| Kerry Group PLC |
| Porex SA (Biochem) |
| AB Enzymes |
| Novozymes A/S |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Nigerian large-scale breweries and integrated multinationals lock in thermal-stable alpha-amylase supply access while compressing price visibility for craft operators dependent on spot-market enzyme formulations. This contract-structure divergence concentrates procurement leverage among ISO 22000-certified suppliers with batch-level traceability, systematically excluding uncertified trading houses from formal supply relationships.
Pricing Analysis
Configured-to-order pricing for customized dosing protocols commands substantial premiums over standardized amylase formulations moving through bulk supply contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and technical service intensity, with HACCP-compliant formulations capturing margin premiums in Nairobi and Lagos. Cost compression in economy-tier commodity enzymes is intensifying because regional distributors compete aggressively on logistics agility. Craft breweries with variable grain bills exhibit highest price sensitivity, while large-scale Nigerian breweries with captive technical teams demonstrate lowest sensitivity due to specification lock-in with proprietary strain libraries.
Supply Chain Analysis
Strategic stockpile preferences dominate among South African large-scale breweries buffering against extended lead times for recombinant enzyme variants, while just-in-time inventory strategies prevail among Nairobi craft operators with fragmented distributor relationships. Manufacturing concentration rests on Belgium, Denmark, and the Netherlands for high-purity fermentation-derived enzymes, with microbial substrate costs tethered to global carbohydrate feedstock markets. Single-source vulnerability concentrates in thermal-stable alpha-amylase production among integrated multinationals with captive fermentation capacity. Distribution runs through regional warehousing networks in Mombasa and Tema cutting delivery lead times for sub-Saharan craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in technical service unbundling as craft breweries across Lagos, Nairobi, and Cape Town separate enzyme procurement from on-site optimization contracts, creating specialist consultancy niches previously captured by bundled distributor relationships.
For Market Incumbents: Consolidate specification relationships with large-scale Nigerian and South African breweries through proprietary recombinant alpha-amylase strain libraries that resist substitution. Deepen backward integration into microbial fermentation capacity to buffer margin compression from global carbohydrate feedstock volatility. Investment in ISO 22000 certification maintenance anchors preferential access as Kenya's Bureau of Standards accelerates HACCP-aligned import approvals. For New Entrants and Emerging Players: Technical service gaps in craft brewery dosing optimization present immediate white-space capture potential, as supplier response cycles extend due to brewing chemist scarcity among 10,000-50,000 hectoliter operators. Ethiopian greenfield malt processing facilities in Addis Ababa and Hawassa offer most penetrable geography absent legacy equipment constraints and established supplier relationships. Go-to-market execution should anchor on specialized dosing protocol development delivered through direct technical deployment rather than commodity enzyme distribution. For Investors and Strategic Acquirers: Regional formulators with HACCP compliance infrastructure and established Kenya Bureau of Standards relationships represent priority acquisition archetypes positioned for East African beverage cluster consolidation. Long-term viability framing centers on technical service margin capture expanding faster than commodity formulation returns across the analysis window. Signal to watch is accelerated national biotechnology regulation harmonization classifying genetically modified microbial strains, which would trigger registration pathway disruption favoring compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | ISO 22000 compliance anchors preferential market access as South Africa's Department of Health tightens import specifications. |
| Regional Warehousing Expansion | Mombasa and Tema logistics hubs compress delivery lead times for craft brewery segments across sub-Saharan Africa. |
| Technical Service Unbundling | Separating enzyme supply from dosing optimization captures higher-margin consultancy relationships with fragmented craft operators. |
| Proprietary Strain Library Development | Recombinant alpha-amylase specifications lock in long-term offtake relationships with large-scale Nigerian breweries. |
| Greenfield Specification Capture | Ethiopian commercial brewing expansion in Addis Ababa creates enzyme-optimized processing line opportunities without retrofit constraints. |
Study Parameters
The analysis maps amylase, β-glucanase, protease, and glucoamylase formulation segments, each validated through brewing chemists, procurement leads at multinational beverage companies, distributor operations managers, and regulatory affairs specialists at national food safety agencies. Primary interview data combines with secondary validation from Codex Alimentarius documentation, Kenya Bureau of Standards import approval records, and African Continental Free Trade Area tariff schedule filings. Bottom-up volume triangulation against top-down macroeconomic indicators ensures consistency across modeling approaches.
Consistency-check validation against external benchmarks anchored volume and value outputs to observed brewery capacity expansions and enzyme intensity ratios throughout the forecast period. Segmentation dimensions modeled span product type, application stage, end-user scale, and distribution channel complexity alongside regional regulatory cluster alignment. CAGRs derive from installed capacity trajectories and enzyme penetration assumptions across greenfield versus retrofit brewery investments. Forecast inputs incorporate sorghum and maize adjunct processing intensity shifts and thermal-stable formulation adoption curves.
Underlying assumptions cover regulatory harmonization timelines, microbial substrate cost stability, and biotechnology classification outcomes, with deviation risk concentrated in genetically modified strain registration pathway disruptions. Forecasts reflect these assumptions with explicit sensitivity to national food safety regulator adoption of BIS-equivalent standards frameworks. Revision becomes warranted when biotechnology classification thresholds cross regulatory implementation triggers or when African Continental Free Trade Area tariff reduction schedules accelerate beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pig Protein Concentrate Market
Ingredients
Fermentation Ingredient Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Global Pulse Flours Market
Ingredients
Savory Ingredients Market
Ingredients
Cocoa Butter Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Smoked Yeast Market
Ingredients
Ahiflower Oil Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Icing Shortening Market
Ingredients
Cacao Extracts Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market