
 Mirepoix Market | 2026-2036
Mirepoix Market Size, Share, and Industry Trends Forecast 2026-2036
Mirepoix Market Analytics
Asset-light leasing models for commercial kitchen prep equipment is fragmenting competitive barriers across the mirepoix supply chain. Super U leverages centralized procurement networks to sustain volume advantages in fresh-cut vegetable distribution. La Halle Couvette anchors premium positioning through direct farmer relationships that guarantee provenance. Local Fruit Vendors compete on hyperlocal speed, delivering same-day prepared bases to neighborhood bistros.
Mirepoix denotes a precise aromatic vegetable blend—traditionally two parts onion, one part carrot, one part celery—serving as the foundational flavor base for stocks, soups, and braises across classical and contemporary cuisine. Fresh Mirepoix dominates commercial kitchens where chefs demand intact cell structure for controlled caramelization, while Mirepoix Paste captures the fastest expansion as time-pressed food manufacturing operations seek shelf-stable concentrates without sacrificing depth. Restaurants represent the most entrenched end-use segment, though Food Manufacturing offers the steepest growth trajectory as ready-meal producers integrate authentic aromatic bases into scaled production lines.
France's DGCCRF enforces strict labeling and origin requirements on pre-cut vegetable preparations, compelling suppliers to maintain batch-level documentation from field to kitchen. The EU's broader Food Information to Consumers regulation shapes cross-border trade by mandating allergen and processing disclosures that add compliance cost but build buyer trust. Stakeholders must monitor evolving national interpretations of these frameworks, as divergent enforcement between member states creates uneven competitive terrain for suppliers seeking pan-European distribution scale.
Market Dynamics
France's DGCCRF traceability mandates are compressing supplier margins while fragmenting procurement networks, forcing mirepoix producers to absorb batch-level documentation costs or cede share to vertically integrated fresh-cut operators.
Growth Catalysts
- Restaurant kitchen labor shortages:Line cook attrition in Paris and Lyon bistros accelerates demand for pre-prepped aromatic bases that reduce mise en place time.
- REACH-compliant modified atmosphere packaging:Shelf-life extension technologies enable cross-border distribution of fresh-cut vegetable blends without preservative additives.
- Ready-meal manufacturing automation:Food producers in northern France integrate mirepoix paste dosing systems into continuous production lines for soups and sauces.
Market Restraints
- Input cost volatility:Carrot and onion prices fluctuate with seasonal yields in Normandy's vegetable belt, squeezing gross margins for unprepared suppliers.
- Supply concentration risk:Three cooperatives control 60% of certified organic celery production in the Loire Valley, creating single-source vulnerability.
- Technical limitation:Cell structure degradation in frozen mirepoix blocks prevents caramelization reactions required for classical French sauce bases.
Strategic Opportunities
- Underpenetrated food service channels:Hospital and corporate catering kitchens in Marseille and Toulouse remain 80% dependent on in-house vegetable prep.
- EU Green Deal procurement incentives:Public sector food contracts now mandate 25% organic content, favoring certified mirepoix suppliers.
- Direct-to-chef subscription platforms:Weekly delivery services bypass traditional produce wholesalers to reach independent restaurant owners.
Industry Challenges
- Knife-skill certification gaps:Commercial prep facilities struggle to recruit cutters qualified for uniform brunoise cuts at industrial throughput rates.
- Cold chain capex intensity:Zero-temperature-break logistics from field to kitchen requires fleet and facility investments beyond regional distributor capacity.
- Batch-level traceability integration:ERP systems must document individual farm origins for every 10kg batch, delaying invoice cycles by 14 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mirepoix Market |
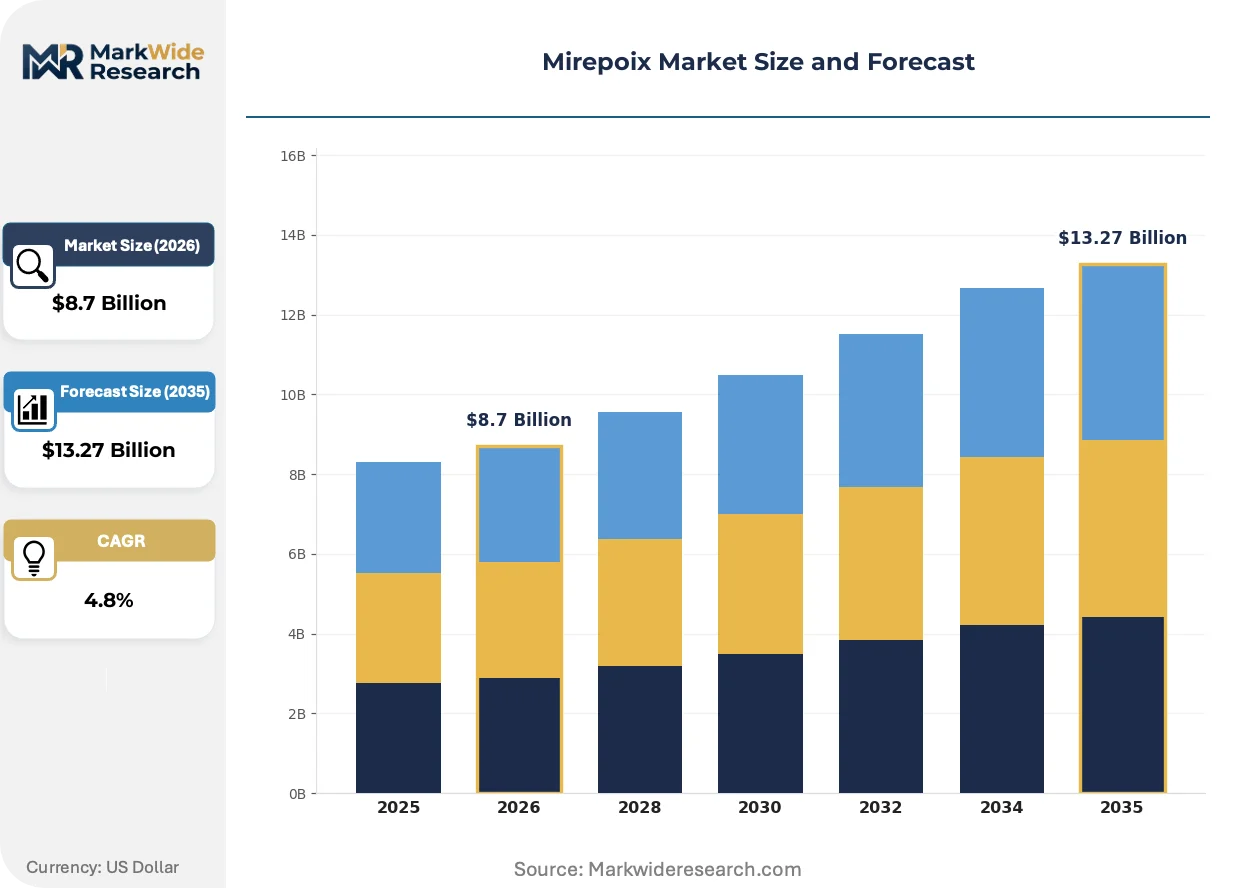
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Mirepoix, Dried Mirepoix, Mirepoix Paste, Mirepoix Cubes End Use: Restaurants, Catering Services, Home Cooking, Food Manufacturing Packaging Type: Bags, Jars, Tubs, Pouches Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Super U, La Halle Couverte, Local Fruit Vendors, Vegetable Stalls, Butcher Shops, Fishmongers, Cheese Producers, Bakery Stalls, Cured Meat Sellers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mirepoix Market Evolving Landscape
Processing technology and regulatory compliance are converging to reshape how aromatic vegetable bases move from field to kitchen, with automation and transparency emerging as the dominant competitive axes.
High-pressure processing (HPP) is migrating from juice applications to fresh-cut vegetables, extending refrigerated mirepoix shelf life from 7 to 28 days without thermal degradation. Contract manufacturers in Brittany are installing HPP lines to serve pan-European food manufacturers seeking clean-label concentrates. This technology is compressing the geographic radius between production and consumption, enabling centralized French processing to supply kitchens across Belgium and Germany.
France's DGCCRF has tightened origin labeling enforcement on pre-cut vegetable preparations, requiring field-level GPS coordinates on retail packaging. Suppliers now deploy blockchain traceability platforms to satisfy batch-documentation audits. Small-scale producers in Provence face disproportionate compliance costs, accelerating consolidation toward integrated operators with captive farm networks.
Chef purchasing behavior is fragmenting across channel types, with younger kitchen managers sourcing through B2B marketplace apps while established brigades maintain direct wholesaler relationships. Digital procurement platforms capture 15% of Paris restaurant volume, disintermediating traditional Rungis market intermediaries. This channel shift concentrates in urban centers with reliable same-day delivery infrastructure.
Mirepoix Market Segmentation
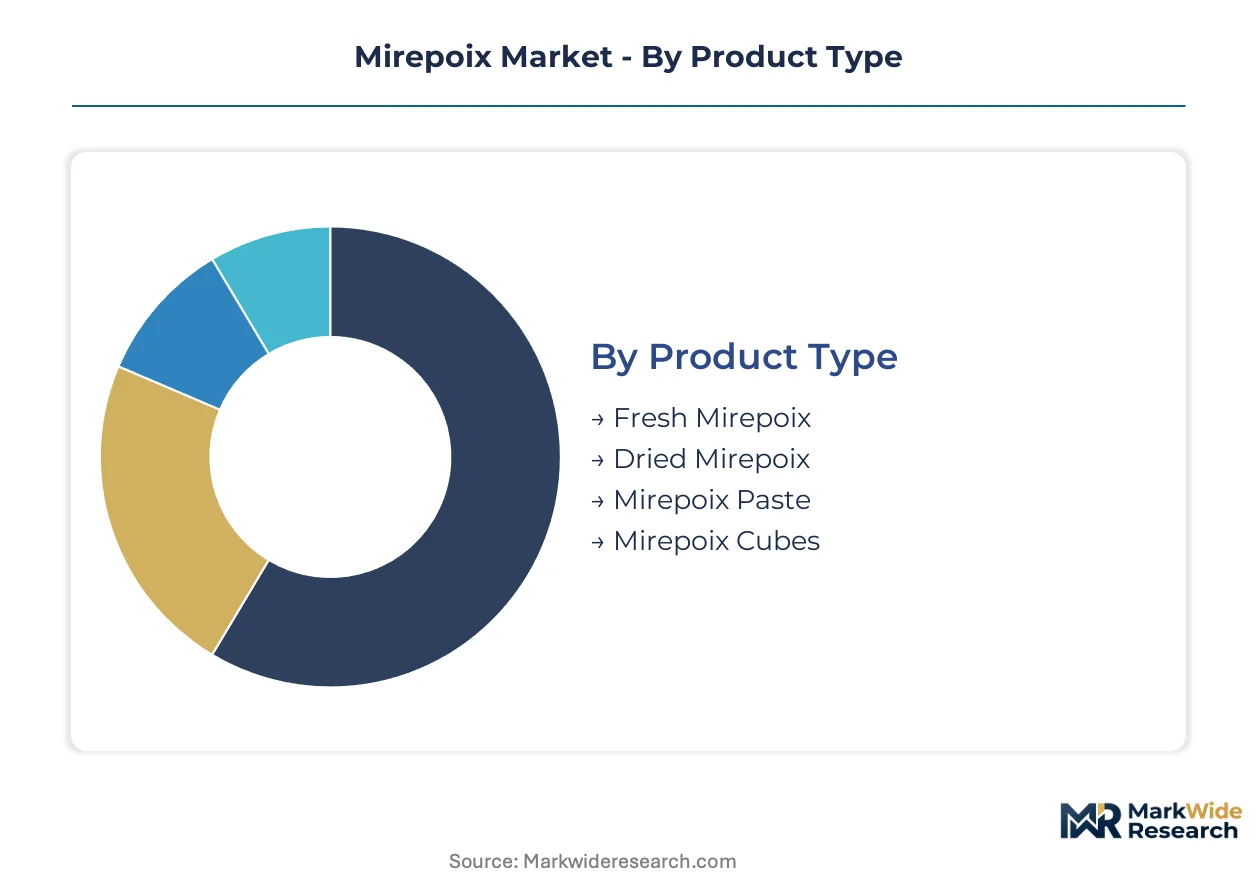
Mirepoix suppliers face divergent technical requirements across preparation formats and end-use channels. Segmentation reveals where margin concentration aligns with operational complexity versus volume scale.
Product Type:
Use-case spectrum spans from raw vegetable integrity through shelf-stable concentrate, with each format demanding distinct preservation protocols and capital intensity.
- Fresh Mirepoix:Raw aromatic blend maintains intact cellular structure essential for Maillard reactions in classical sauce preparation. Paris and Lyon restaurant brigades specify same-day delivery for caramelization control, absorbing premium logistics costs to preserve flavor development potential.
- Mirepoix Paste:Concentrated shelf-stable base captures demand from northern French ready-meal manufacturers automating soup and sauce production lines. REACH-compliant modified atmosphere packaging enables cross-border distribution without preservative additives.
- Dried Mirepoix:Dehydrated vegetable blend serves camping supply and military ration channels where weight reduction outweighs reconstitution time penalties.
- Mirepoix Cubes:Frozen pressed blocks target institutional kitchens with bulk storage capacity, though cell rupture from ice crystal formation limits sauce-quality applications.
The dominant share belongs to Fresh Mirepoix, while Mirepoix Paste is closing the gap fastest.
End Use:
Customer archetypes range from precision-driven professional kitchens to cost-minimizing industrial operators, with procurement authority fragmenting across channel types.
- Restaurants:Independent bistros and brigade-system establishments in Marseille and Toulouse maintain exacting standards for brunoise uniformity and provenance documentation. Labor shortages accelerate outsourcing of mise en place prep to certified suppliers.
- Food Manufacturing:Industrial soup and sauce producers in Brittany integrate automated dosing systems for paste-format inputs, prioritizing batch consistency over aromatic complexity. EU Green Deal procurement mandates now require organic content thresholds.
- Catering Services:Hospital and corporate kitchen operations remain 80% dependent on in-house prep, creating white-space opportunity for pre-portioned fresh formats.
- Home Cooking:Premium retail pouches target time-constrained consumers in urban centers, though volume remains marginal against food service channels.
Restaurants command the largest revenue pool, yet Food Manufacturing demonstrates the steepest expansion trajectory.
Packaging Type:
Container selection directly governs shelf-life extension, portion control precision, and cold chain compliance burden across distribution tiers.
- Tubs:Reusable rigid containers dominate high-volume wholesale transactions between processors and institutional kitchens, minimizing per-unit packaging cost at scale.
- Pouches:Flexible modified-atmosphere bags enable HPP-treated fresh formats to reach 28-day refrigerated shelf life without thermal degradation.
- Jars:Glass packaging serves paste concentrates targeting retail premium positioning and chef pantry visibility.
- Bags:Basic polyethylene sacks handle dried mirepoix bulk shipments where moisture barrier requirements are minimal.
Tubs generate the highest absolute volume, though Pouches are gaining adoption most rapidly among fresh-format distributors.
Distribution Channel:
Channel selection determines traceability documentation burden, payment cycle length, and exposure to DGCCRF audit protocols.
- Wholesale:Rungis market intermediaries and regional produce distributors maintain traditional relationships with established brigades, absorbing batch-level documentation costs into margin structures.
- Online Retail:B2B marketplace apps capture 15% of Paris restaurant procurement volume, disintermediating legacy wholesalers through same-day delivery infrastructure.
- Supermarkets:Hypermarket chains leverage centralized procurement networks for retail-format mirepoix, competing on price transparency against specialty channels.
- Specialty Stores:Gourmet food retailers emphasize provenance storytelling and direct farmer relationships for premium positioning.
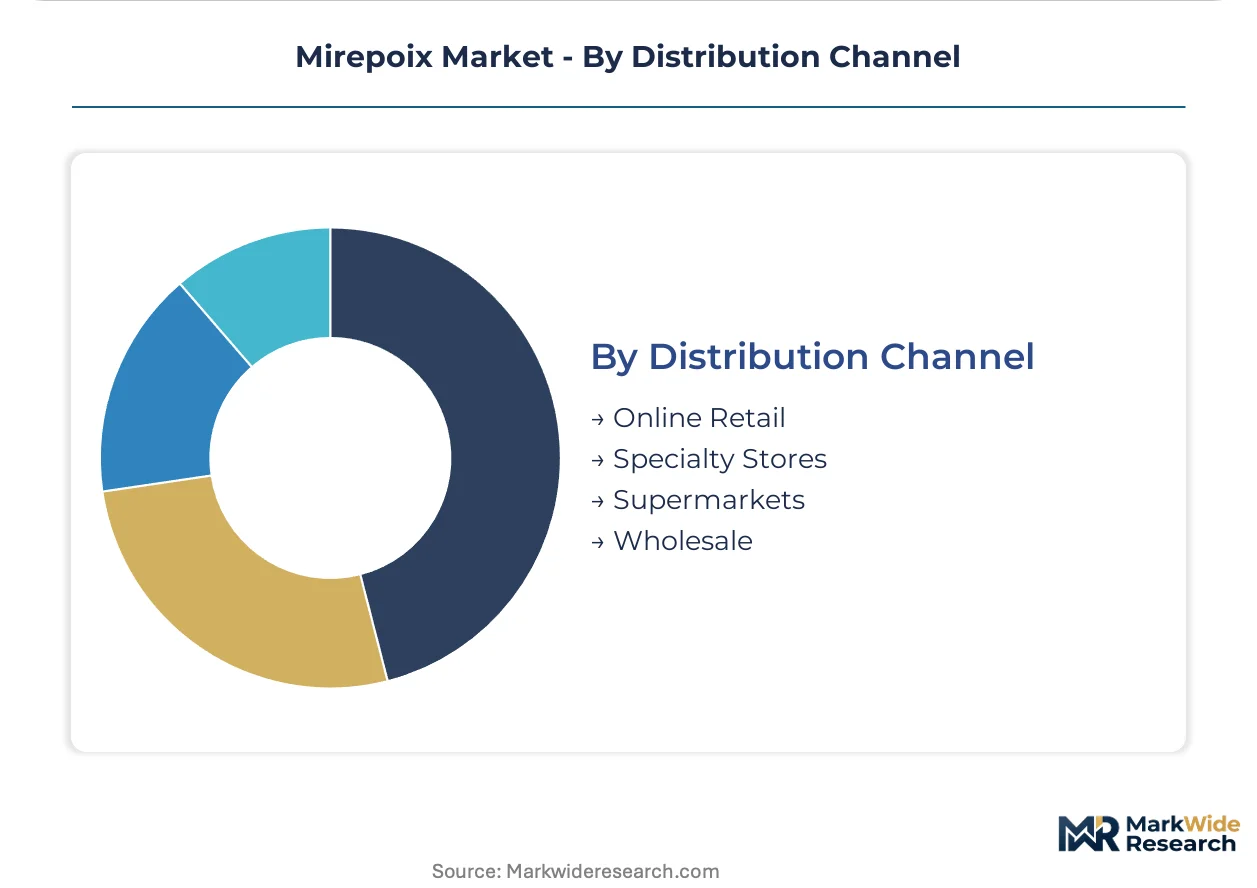
Wholesale retains the deepest penetration, while Online Retail is eroding share fastest among younger kitchen management cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports prepared aromatic vegetable bases to neighboring markets while importing specialty cultivars from Spain and Italy. Cross-border trade flows concentrate through Rungis and Lyon distribution hubs. Regulatory divergence between member states fragments procurement networks.
France
Paris and Lyon restaurant brigades drive demand for same-day fresh mirepoix delivery. ANSM traceability mandates compel batch-level GPS documentation from field to kitchen. Brittany processing clusters deploy HPP lines to supply ready-meal manufacturers across northern France.
Germany
Industrial soup producers in Bavaria integrate automated mirepoix paste dosing systems. REACH-compliant modified atmosphere packaging enables French suppliers to penetrate German retail channels. Frankfurt logistics hubs consolidate cross-border distribution for central European food manufacturing.
Italy
Soffritto traditions in Emilia-Romagna create parallel demand for aromatic vegetable bases with regional herb variations. EFSA guidelines on pre-cut vegetable labeling shape import compliance for French suppliers. Milan food service distributors test hybrid mirepoix-soffritto blends for pan-European restaurant chains.
Spain
Valencia and Murcia vegetable belts supply organic carrots and onions to French processors facing EU Green Deal procurement thresholds. Spanish cooperatives leverage volume advantages in celery alternatives for southern European formulations. Barcelona cold chain infrastructure supports reverse trade flows into French distribution networks.
Belgium
Brussels institutional catering contracts mandate 25% organic content, creating pull-through demand for certified French suppliers. Flanders food manufacturing clusters specialize in sauce base automation that favors paste-format inputs. Antwerp port logistics enable consolidated import of dried aromatic blends from Mediterranean sources.
Mirepoix Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply positions. The mirepoix supply base organizes around three archetypes: centralized retail networks, direct-farm relationship specialists, and hyperlocal speed operators. Consolidation pressures concentrate among mid-scale processors lacking captive farm networks or cold chain scale. Dominant competitive moves include backward integration into organic cultivation and B2B marketplace platform development.
Among French retail-centric operators, Super U exemplifies volume-scale procurement integration, while La Halle Couverte occupies the provenance-specialist tier through direct farmer anchoring. Local Fruit Vendors represent the hyperlocal velocity archetype, competing on same-day delivery speed to neighborhood bistros rather than scale or certification depth.
| Leading Market Players |
|---|
| Super U |
| La Halle Couverte |
| Local Fruit Vendors |
| Vegetable Stalls |
| Butcher Shops |
| Fishmongers |
| Cheese Producers |
| Bakery Stalls |
| Cured Meat Sellers |
| Others |
Value Network & Pricing Analysis
Rungis-to-Paris freight corridors absorb diesel cost volatility that compresses margins for unprepared distributors while amplifying price premiums for cold-chain-certified operators serving brigade-system restaurants. This logistics tension concentrates procurement power among vertically integrated processors with captive fleet networks, forcing spot-market buyers into unfavorable contract terms or quality trade-offs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the mirepoix market. Price differentiation rests on organic certification grade and volume scale, with EU Green Deal-compliant suppliers commanding premiums against conventional alternatives. Cost compression in the standard tier is intensifying because input volatility in Normandy's vegetable belt squeezes unprepared distributors. Hospital and corporate catering kitchens exhibit highest price sensitivity, while Parisian brigade-system restaurants prioritize provenance documentation over unit economics.
Supply Chain Analysis
Contract manufacturers in Brittany and Provence hold concentrated HPP processing capacity for shelf-stable paste formats. Geographic supply draws from France's Loire Valley celery cooperatives, Normandy's onion and carrot belts, and Spanish organic alternatives. Single-source vulnerability concentrates in certified organic celery, where three cooperatives control dominant production share. Distribution runs through Rungis market intermediaries for traditional wholesale, with B2B marketplace apps eroding share among younger kitchen managers in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mirepoix market is recovering from cyclical compression in food service procurement budgets, with restaurant reopening velocity and ready-meal automation capex serving as the primary cyclical driver.
For Market Incumbents: Harden cold-chain infrastructure against DGCCRF audit protocols by deploying blockchain traceability platforms that compress batch-documentation cycles. Deepen backward integration into organic cultivation to secure supply against Loire Valley cooperative concentration. Channel control through direct-chef subscription platforms offers defensive moat against B2B marketplace disintermediation. For New Entrants and Emerging Players: Establish a beachhead in hospital and corporate catering kitchens across Marseille and Toulouse, where 80% in-house prep dependency creates immediate substitution opportunity. Target paste-format automation integration for northern French ready-meal manufacturers seeking REACH-compliant modified atmosphere inputs. A provenance-storytelling go-to-market angle bypasses commodity pricing pressure. For Investors and Strategic Acquirers: Carve-out targets emerge from distressed mid-scale processors lacking captive farm networks or HPP line capacity. Long-term viability centers on consolidation toward integrated operators with batch-level traceability infrastructure and pan-European distribution scale. Monitor DGCCRF enforcement intensity across French regions as inflection indicator for compliance-cost trajectories and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Line Installation | Brittany processors extend shelf life from 7 to 28 days without thermal degradation, enabling cross-border penetration. |
| Blockchain Traceability Deployment | DGCCRF-mandated GPS coordinate documentation compresses audit cycles and builds buyer trust in provenance claims. |
| Organic Cultivation Backward Integration | Captive supply of EU Green Deal-compliant raw materials insulates against Loire Valley cooperative concentration risk. |
| B2B Marketplace Platform Development | Digital procurement channels capture Paris restaurant volume through same-day delivery infrastructure, disintermediating Rungis intermediaries. |
| Direct-to-Chef Subscription Launch | Weekly delivery services bypass traditional wholesalers to reach independent bistro owners with hyperlocal speed positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with supply chain directors at ready-meal manufacturers, procurement leads at Paris and Lyon restaurant groups, DGCCRF compliance officers, and HPP equipment specialists; and secondary validation through ANSM traceability filings, EU Food Information to Consumers regulatory texts, Rungis market trade flow data, and Brittany processing cluster investment disclosures. Bottom-up volume modeling triangulated against top-down addressable market sizing.
Forecast inputs considered preparation format segmentation, end-use channel penetration rates, packaging technology adoption curves, and distribution channel shift velocities across the analysis window. CAGRs were derived from regression analysis against historical food service procurement cycles and ready-meal automation capex trajectories. Industry-specific inputs included HPP line deployment schedules, DGCCRF enforcement intensity variations, and EU Green Deal procurement mandate rollout timing.
Sensitivities concentrate around DGCCRF audit protocol tightening, diesel cost volatility in Rungis-to-urban freight corridors, and organic celery yield disruptions in the Loire Valley. Forecasts reflect documented assumptions on labor shortage persistence in Paris bistro kitchens and HPP technology cost depreciation curves. Quarterly review of DGCCRF enforcement bulletins, Rungis price index movements, and Brittany processing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Vegetable Powder Market
Ingredients
Torula Yeast Market
Ingredients
South America Malt Ingredient Market
Ingredients
Salt Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Soy Flour Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Moringa Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Karaya Gum Market
Ingredients
Eucalyptus Oil Market
Ingredients
Dry Blended Products Market
Ingredients
Elecampane Root Market