
 Global Pregelatinized Starch Market | 2026-2036
Global Pregelatinized Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pregelatinized Starch Market Foresight
Pharmaceutical companies are redrawing procurement priorities for excipient-grade starches, shifting volume toward suppliers with certified GMP compliance and documented elemental impurity profiles. Ingredion Incorporated leverages its global manufacturing footprint to supply modified starch variants across multiple pharmacopeial grades. Cargill Incorporated sustains backward integration into corn wet milling, securing captive feedstock for North American excipient production. Roquette Frères anchors European supply through pea and potato starch specialization, competing on non-GMO and allergen-free positioning.
Pregelatinized starch is starch that has been cooked and dried to rupture all or part of the granules, rendering it cold-water soluble and capable of forming gels or viscous dispersions without heat; it typically exhibits moisture content of 10-14% and particle sizes tailored to specific dissolution rates. Its primary commercial purpose spans pharmaceutical tableting as a binder and disintegrant, food processing as a thickener and texturizer, and adhesive formulations as a carrier and viscosity modifier. Corn starch dominates volume due to established supply chains and cost structures, while tapioca starch represents the fastest-expanding category in clean-label food applications where consumers reject genetically modified sources. Wheat starch occupies a mature niche in European paper and packaging adhesives, where regional grain surplus supports localized production economics.
The US FDA enforces excipient qualification through its Inactive Ingredient Database and ICH Q3D elemental impurity guidelines, forcing starch processors to invest in heavy-metal testing and supply chain documentation. India's CDSCO aligns with ICH standards while implementing BIS certification for pharmaceutical raw materials, creating dual compliance burdens for exporters serving both markets. The EU's REACH regulation and EMA excipient master file requirements add further layers of chemical safety and quality documentation. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs, as divergence in specification limits directly determines which suppliers qualify for multi-regional contracts.
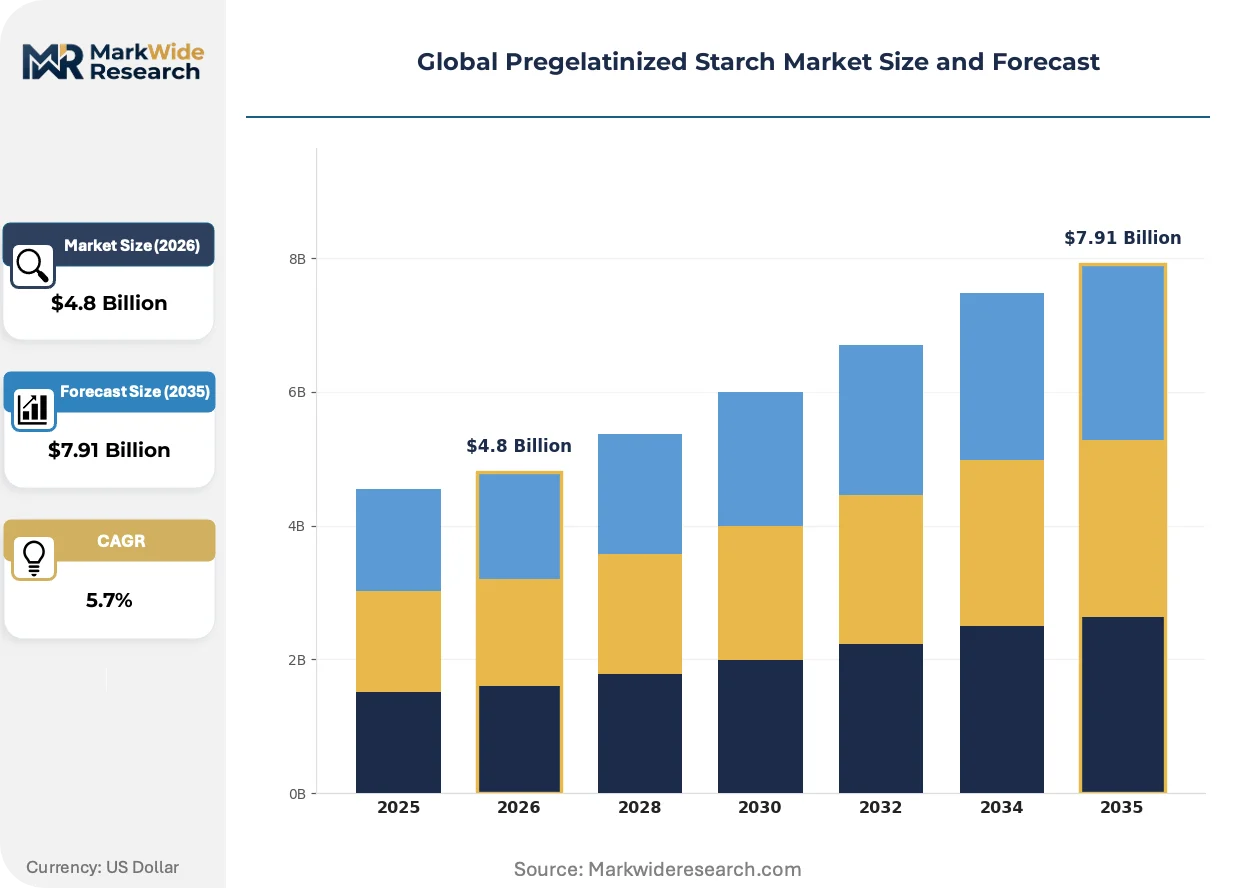
Market Dynamics
Pharmaceutical excipient qualification standards are compressing supplier margins while concentrating volume toward processors with certified elemental impurity documentation and multi-pharmacopeial compliance capabilities.
Growth Catalysts
- ICH Q3D Alignment:Harmonized elemental impurity guidelines across USP-NF, EP, and JP monographs are streamlining multi-regional supplier qualification and reducing redundant testing burdens for compliant processors.
- India PLI Scheme:Production-linked incentive disbursements for domestic pharmaceutical manufacturing are accelerating local sourcing of excipient-grade starches and reducing import dependency.
- Clean-Label Migration:Food manufacturers are reformulating with non-GMO tapioca starch to meet consumer rejection of genetically modified ingredients in premium product lines.
Market Restraints
- Corn Feedstock Volatility:Weather-driven fluctuations in North American corn harvests transmit directly into input cost instability for wet-milling operations supplying pharmaceutical-grade material.
- Supplier Concentration:Captive corn wet milling infrastructure in the United States limits viable excipient-grade sources, creating single-geography dependency for high-volume buyers.
- Substitution Pressure:Microcrystalline cellulose and croscarmellose sodium are displacing pregelatinized starch in certain rapid-disintegration tablet formulations where faster breakup kinetics are required.
Strategic Opportunities
- ASEAN Manufacturing Expansion:Vietnam and Indonesia pharmaceutical production growth is outpacing local excipient supply, creating import substitution openings for certified regional processors.
- Pea Starch Specialization:Non-GMO and allergen-free positioning of pea-derived variants is unlocking premium pricing in European pediatric and hypoallergenic drug formulations.
- Continuous Processing Adoption:Direct compression tableting technology convergence with pre-mixed excipient systems is enabling value-added formulation services beyond commodity starch supply.
Industry Challenges
- Multi-Pharmacopeial Certification Timelines:Parallel USP-NF, EP, and JP monograph compliance processes extend qualification cycles to 18-24 months for new manufacturing sites.
- Heavy-Metal Testing Infrastructure:ICP-MS instrumentation and validated analytical methods require seven-figure capital deployment per facility to meet ICH Q3D documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pregelatinized Starch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Starch, Wheat Starch, Potato Starch, Tapioca Starch, Rice Starch Application: Pharmaceuticals, Paper & Packaging, Adhesives, Food & Beverages, Textile Processing End User Industry: Consumer Goods Manufacturers, Chemical Producers, Pharmaceutical Companies, Textile Mills, Packaging Firms Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers, Exporters |
| Companies Covered | Ingredion Incorporated, Agrana Beteiligungs-AG, Cargill Incorporated, Visco Starch, Emsland Group, Tate & Lyle PLC, Roquette Frères, Grain Processing Corporation, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pregelatinized Starch Market Shifts & Advancements
Processing technology and regulatory documentation requirements are converging to reshape competitive positioning among starch suppliers, with differentiation increasingly anchored in analytical capabilities rather than commodity scale.
Modified starch functionalization is miniaturizing particle size distributions to enable direct compression tableting without pre-granulation steps. Pharmaceutical contract manufacturers are adopting these engineered grades to eliminate wet granulation bottlenecks and reduce processing energy. This compression of manufacturing steps is miniaturizing equipment footprints and shifting value capture toward excipient suppliers with formulation science capabilities.
REACH registration dossier updates under ECHA's 2023-2027 substance evaluation work program are mandating additional toxicological endpoints for starch derivatives used in food contact applications. European processors are consolidating testing resources through shared consortia to defray compliance costs. The regulatory friction falls most heavily on small-volume specialty starch variants where per-tonne registration burdens exceed margin absorption capacity.
Consolidated pharmaceutical procurement organizations are unbundling excipient sourcing from formulation development services, creating separate contract tiers for commodity supply versus technical partnership. This disintermediation of bundled relationships is compressing pricing transparency and accelerating third-party audit requirements. The pattern is most visible in India, where CDSCO-mandated supplier qualification is driving centralized purchasing decisions at the holding company level rather than individual manufacturing site discretion.
Global Pregelatinized Starch Market Segmentation
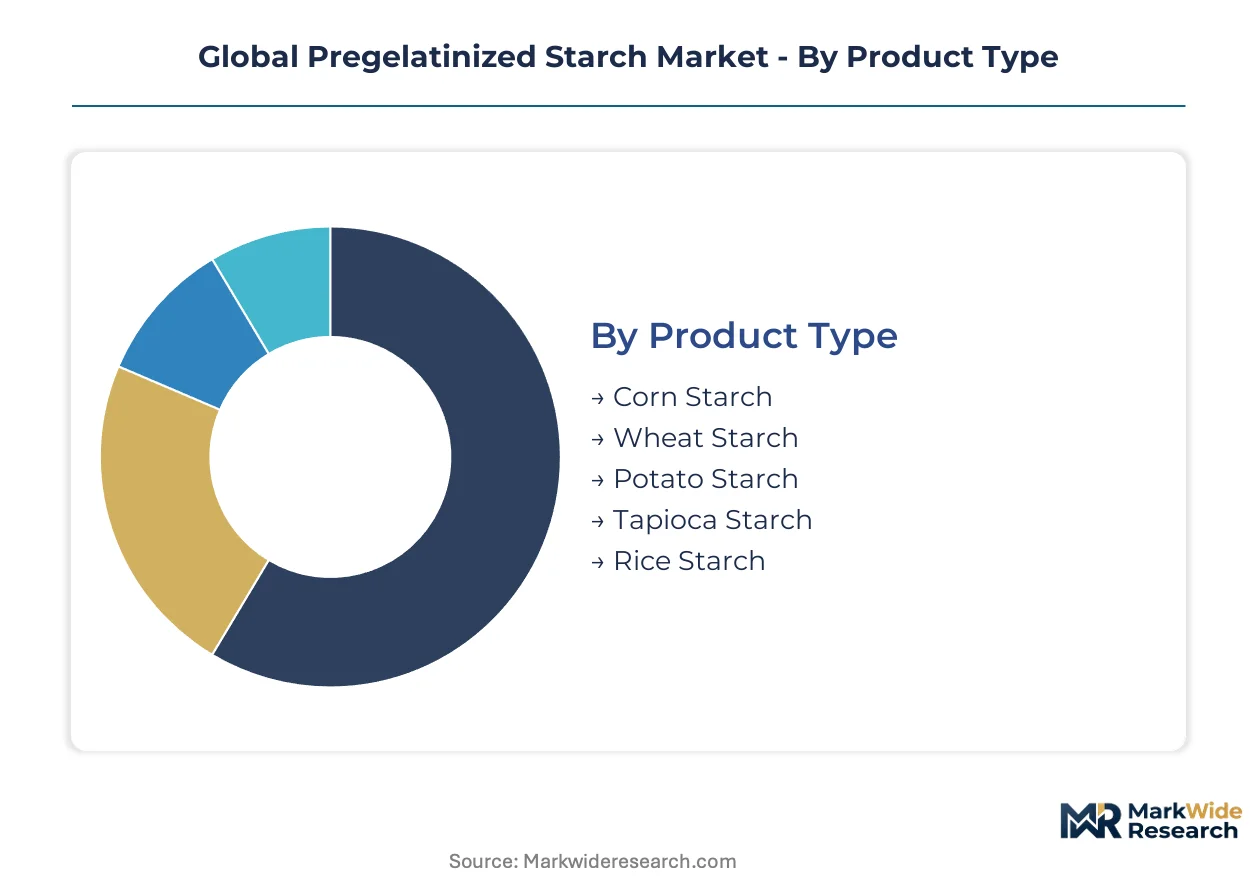
Pregelatinized starch markets fragment across botanical origin, end-use performance requirements, and channel access economics. Regulatory compliance thresholds for pharmaceutical grades versus food-grade specifications create divergent margin structures across each segment axis.
Product Type:
USP-NF, EP, and JP monograph alignment requirements favor suppliers with multi-pharmacopeial certification for pharmaceutical-grade material, while food-grade sourcing prioritizes non-GMO documentation and allergen-free positioning.
- Corn Starch:Wet-milled maize derivatives dominate pharmaceutical excipient volumes due to established USP-NF monograph acceptance and cost-efficient North American supply infrastructure. Tablet binders and disintegrants in US and Indian pharmaceutical manufacturing concentrate procurement here, though genetically modified status limits clean-label food penetration.
- Tapioca Starch:Cassava-derived material offers non-GMO and allergen-free credentials that unlock premium positioning in European pediatric formulations and clean-label food applications. Vietnamese and Thai processing clusters are expanding capacity to serve ASEAN pharmaceutical growth and Western food manufacturer reformulation mandates.
- Wheat Starch:European paper and packaging adhesives sustain mature demand, with regional grain surplus supporting localized production economics.
- Potato Starch:Roquette Frères and Benelux processors specialize in this variant for allergen-sensitive drug delivery systems.
- Rice Starch:Hypoallergenic properties serve niche Japanese and South Korean pharmaceutical applications where corn and wheat sensitivities drive alternative sourcing.
Established volume favors corn starch; emerging adoption favors tapioca starch.
Application:
End-use performance specifications determine qualification timelines, with pharmaceutical tableting requiring 18-24 month multi-pharmacopeial certification versus immediate commercial deployment in adhesive formulations.
- Pharmaceuticals:ICH Q3D elemental impurity documentation and GMP compliance compress supplier margins while concentrating volume toward processors with ICP-MS testing infrastructure. Direct compression tableting adoption is accelerating demand for engineered particle size distributions that eliminate wet granulation steps.
- Food & Beverages:Clean-label migration and non-GMO rejection are reformulating thickener and texturizer specifications across premium product lines. Tapioca-derived variants are climbing fastest in Western European and North American natural product segments.
- Paper & Packaging:Wheat starch anchors European adhesive demand, with regional grain surplus supporting cost-competitive localized supply.
- Adhesives:Lower regulatory barriers enable rapid commercial deployment compared to pharmaceutical grades.
- Textile Processing:Sizing and finishing applications sustain steady demand in Indian and Bangladeshi mill clusters.
Pharmaceutical applications command qualification premiums; food and beverage applications are expanding most quickly.
End User Industry:
Procurement centralization varies by industry consolidation, with pharmaceutical holding companies implementing CDSCO-mandated supplier qualification at corporate level while textile mills maintain site-level purchasing discretion.
- Pharmaceutical Companies:Consolidated procurement organizations are unbundling excipient sourcing from formulation development services, creating separate contract tiers for commodity supply versus technical partnership. CDSCO-mandated supplier qualification in India is driving centralized purchasing decisions.
- Consumer Goods Manufacturers:Clean-label pressure and reformulation timelines compress supplier switching costs in food and personal care applications.
- Chemical Producers:Adhesive and industrial adhesive formulators prioritize consistent viscosity profiles over pharmacopeial compliance.
- Packaging Firms:European paper and corrugated board producers sustain wheat starch demand through regional supply integration.
- Textile Mills:Indian and Bangladeshi sizing operations source commodity-grade material with minimal certification burden.
Pharmaceutical concentration favors qualified suppliers; consumer goods fragmentation favors flexible sourcing.
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and geographic proximity to manufacturing clusters.
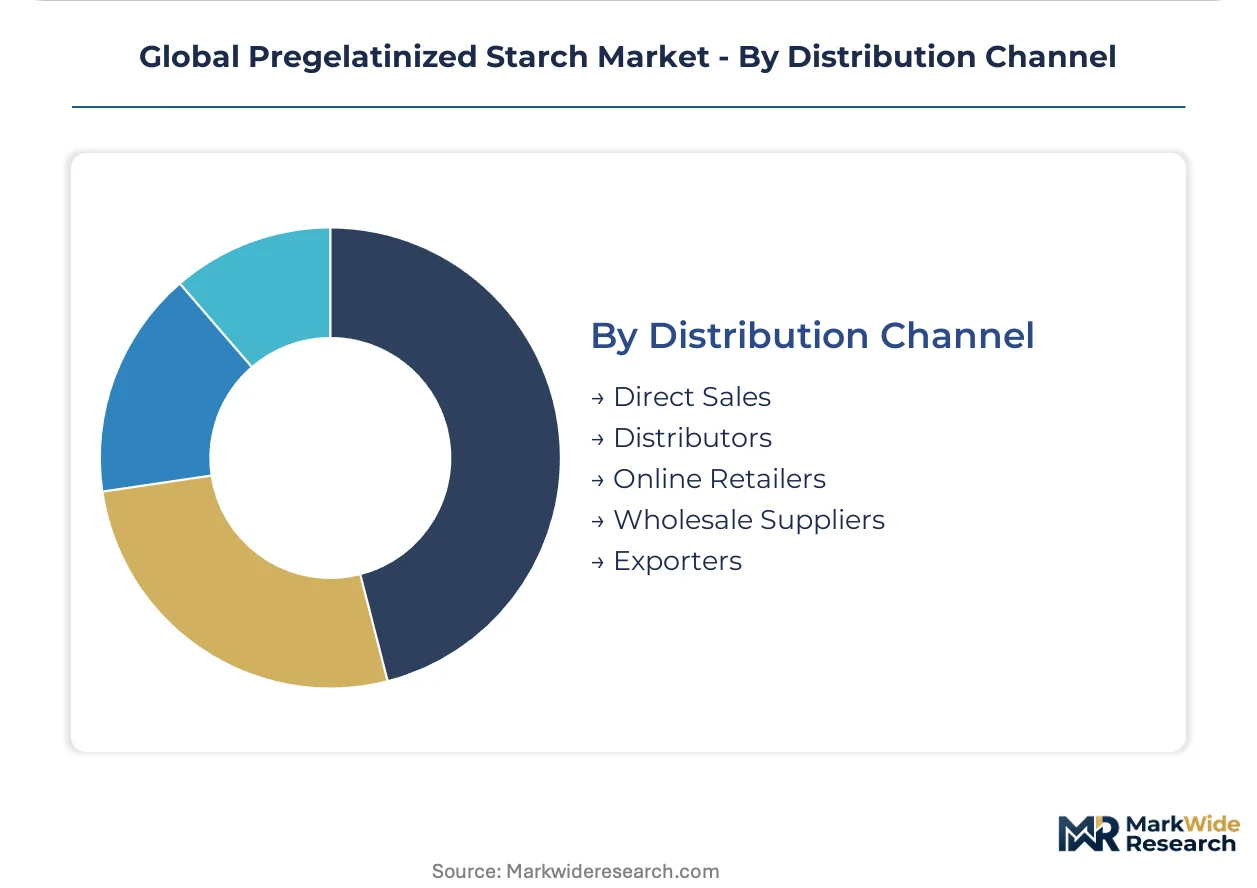
- Direct Sales:Multi-ton pharmaceutical contracts with documented elemental impurity profiles and audit trails bypass intermediary markup.
- Distributors:Regional chemical distributors serve mid-volume food and adhesive manufacturers requiring technical support.
- Wholesale Suppliers:Aggregated procurement for textile and paper applications prioritizes cost over certification depth.
- Exporters:Indian and ASEAN pharmaceutical manufacturers source excipient-grade material through specialized export channels with CDSCO-aligned documentation.
- Online Retailers:Niche laboratory and small-batch food producers access specification-grade material without minimum order constraints.
Direct sales capture pharmaceutical volume; distributor networks serve fragmented food and adhesive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk and dry cargo infrastructure underwrites European starch derivative trade flows, while Union Pacific's rail network connects Midwest corn belt processors to coastal export terminals. These logistics assets determine regional sourcing economics for pharmaceutical and food-grade material.
United States
Pharmaceutical tablet manufacturing in New Jersey and North Carolina drives excipient-grade corn starch procurement, with FDA's ICH Q3D enforcement concentrating volume toward suppliers with elemental impurity documentation. The Corn Belt wet-milling corridor spanning Iowa, Illinois, and Indiana supplies captive feedstock to integrated processors, with rail spurs linking Decatur and Cedar Rapids facilities to East Coast pharmaceutical clusters.
Germany
Roquette Frères anchors European pea and potato starch specialization from Benelux processing sites, serving EMA excipient master file requirements for pediatric and hypoallergenic drug formulations. REACH registration dossier updates under ECHA's substance evaluation program mandate additional toxicological endpoints for food contact applications, with shared industry consortia defraying compliance costs across Frankfurt and Mannheim chemical clusters.
India
CDSCO-mandated supplier qualification and PLI scheme disbursements for domestic pharmaceutical manufacturing are accelerating local sourcing of excipient-grade starches in Maharashtra and Gujarat. The BIS certification framework for pharmaceutical raw materials creates dual compliance burdens for exporters, with Mumbai and Ahmedabad processing clusters expanding capacity to serve both domestic and ASEAN export demand.
China
NMPA alignment with ICH Q3D standards is reshaping elemental impurity documentation requirements for starch excipients serving domestic pharmaceutical production. The Yangtze River Delta pharmaceutical manufacturing belt spanning Shanghai, Suzhou, and Taizhou is driving demand for certified material, with port infrastructure at Ningbo-Zhoushan facilitating tapioca starch imports from Southeast Asian processing clusters.
Vietnam
Cassava cultivation in the Central Highlands and Mekong Delta supports expanding tapioca starch processing capacity for ASEAN pharmaceutical growth and Western food manufacturer reformulation mandates. The country's national pharmaceutical regulator is implementing excipient qualification standards aligned with ASEAN harmonization protocols, with Ho Chi Minh City and Binh Duong industrial zones attracting investment in certified processing infrastructure.
Global Pregelatinized Starch Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock integration, with publicly traded processors leveraging capital market access for ICP-MS testing infrastructure while family-held operators compete on regional relationship density. The vendor base fragments across three tiers: integrated agribusiness conglomerates with captive corn wet milling, independent specialty starch processors with pharmacopeial certification, and regional distributors serving fragmented food and adhesive demand. Strategic moves concentrate on multi-pharmacopeial certification timelines and backward integration into non-GMO feedstock sourcing.
Within the integrated agribusiness tier, Ingredion Incorporated and Cargill Incorporated exemplify scale-driven positioning through global manufacturing footprints and captive supply chain control. Roquette Frères occupies a specialist position in European non-GMO and allergen-free starch derivatives, representing the premium-tier archetype focused on pediatric and hypoallergenic drug formulation demand.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Agrana Beteiligungs-AG |
| Cargill Incorporated |
| Visco Starch |
| Emsland Group |
| Tate & Lyle PLC |
| Roquette Frères |
| Grain Processing Corporation |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month qualification timelines for multi-pharmacopeial certification concentrate pricing power among established processors with ICP-MS testing infrastructure, while corn feedstock volatility transmits directly into contract renegotiation leverage for North American wet-milling operations serving pharmaceutical buyers.
Pricing Analysis
Volume-discount tiering structures stratify across excipient-grade certification levels, with USP-NF/EP/JP-aligned material commanding substantial premiums over food-grade equivalents. Price differentiation hinges on elemental impurity documentation depth and GMP audit trail completeness, with pharmaceutical procurement organizations least sensitive to unit cost and textile mills most responsive to spot-market fluctuations. Cost compression in standard-grade corn starch intensifies as Indian domestic capacity expansion undercuts import parity, while premium tapioca variants sustain pricing resilience through non-GMO positioning in European pediatric formulations.
Supply Chain Analysis
Union Pacific rail corridors through Iowa, Illinois, and Indiana constitute a critical chokepoint for North American pharmaceutical-grade corn starch, with captive wet-milling infrastructure drawing from Midwest harvests and feeding East Coast tablet manufacturing clusters. Raw material dependencies center on maize cultivation cycles, cassava harvests in Vietnam and Thailand, and pea protein processing byproducts in Benelux facilities. Single-geography concentration for high-purity excipient-grade material creates vulnerability to weather-driven supply interruptions. Distribution runs through direct sales channels for multi-ton pharmaceutical contracts and regional chemical distributors serving fragmented food and adhesive demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and feedstock specializations creates entry niches for processors with targeted analytical capabilities, as CDSCO-mandated supplier qualification in India and ASEAN harmonization protocols multiply the addressable supplier base beyond incumbent agribusiness conglomerates.
For Market Incumbents: Shield market position through backward integration into non-GMO tapioca feedstock sourcing in Vietnamese Central Highlands processing clusters, countering substitution pressure from microcrystalline cellulose in rapid-disintegration tablet formulations. Prioritize ICP-MS instrumentation deployment across secondary manufacturing sites to compress multi-pharmacopeial qualification timelines for new capacity additions.
For New Entrants and Emerging Players: Differentiate on pea starch specialization for European pediatric and hypoallergenic drug formulations, exploiting Roquette Frères' capacity constraints in Benelux processing infrastructure. Target ASEAN pharmaceutical manufacturing expansion in Vietnam and Indonesia, where excipient supply lags behind formulation demand and national regulators are implementing qualification standards aligned with harmonized protocols.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because CDSCO-mandated supplier qualification and ICH Q3D documentation requirements are raising capital barriers beyond mid-scale independent processors. Acquisition candidates include regional Indian starch processors with BIS certification infrastructure and Vietnamese tapioca operations with nascent pharmaceutical-grade capacity. The signal to watch is ASEAN regulatory harmonization completion, which would unlock cross-border contract eligibility for certified regional suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Pharmacopeial Certification Investment | ICP-MS infrastructure deployment enables USP-NF, EP, and JP contract eligibility across Mumbai and Ahmedabad processing clusters. |
| Backward Integration into Non-GMO Feedstock | Captive cassava cultivation in Vietnam's Central Highlands secures clean-label tapioca starch supply for European pediatric formulations. |
| Continuous Processing Technology Adoption | Direct compression-compatible particle engineering eliminates wet granulation steps for pharmaceutical contract manufacturers. |
| ASEAN Manufacturing Footprint Expansion | Ho Chi Minh City and Binh Duong facilities capture import substitution demand from Vietnamese and Indonesian pharmaceutical growth. |
| Shared REACH Registration Consortia | ECHA substance evaluation compliance cost pooling protects small-volume specialty starch variant margins in European food contact applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical procurement directors, excipient quality assurance leads, starch processing plant managers, and CDSCO regulatory affairs specialists; and secondary validation through USP-NF monograph databases, EMA excipient master file submissions, Indian BIS certification records, and corn wet-milling industry trade data. Bottom-up capacity and demand modeling triangulated against top-down market sizing from customs flows and pharmaceutical production statistics.
Across the projection horizon, the analytical framework modeled volume and value trajectories by botanical origin, application performance tier, end-user industry procurement centralization level, and regional regulatory cluster. CAGRs derived from segment-specific demand elasticity coefficients and supply-side capacity expansion schedules, with pharmaceutical direct compression adoption rates and clean-label food reformulation timelines as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained ICH Q3D alignment across USP-NF, EP, and JP monographs, or abrupt corn feedstock price dislocations, would require recalibration. Practitioners should keep alternative scenarios live as ASEAN regulatory harmonization implementation and Indian PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cognitive Ingredients Market
Ingredients
Ice Cream Ingredients Market
Ingredients
Peanut Flour Market
Ingredients
North America Soybean Oil Market
Ingredients
Green Gram Powder Market
Ingredients
Cheese Powder Market
Ingredients
Agar Market
Ingredients
Kairomones Market
Ingredients
Mirepoix Market
Ingredients
Textured Milk Protein Market
Ingredients
Hydroxytyrosol Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Black Seed Oil Market
Ingredients
Marine Peptides Market
Ingredients
South America Phytosterols Market
Ingredients
Europe Pea Starch Market