
 Africa Food Ingredients Market | 2026-2036
Africa Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Ingredients Market Analysis
Ingredient-as-a-service contracting is broadening how African food manufacturers access technical formulations and flavor libraries. Cargill, Incorporated leverages its pan-African grain and oilseed infrastructure to supply localized emulsifier blends. Kerry Group anchors technical service teams in Johannesburg and Lagos to support bakery and confectionery clients with application-specific solutions.
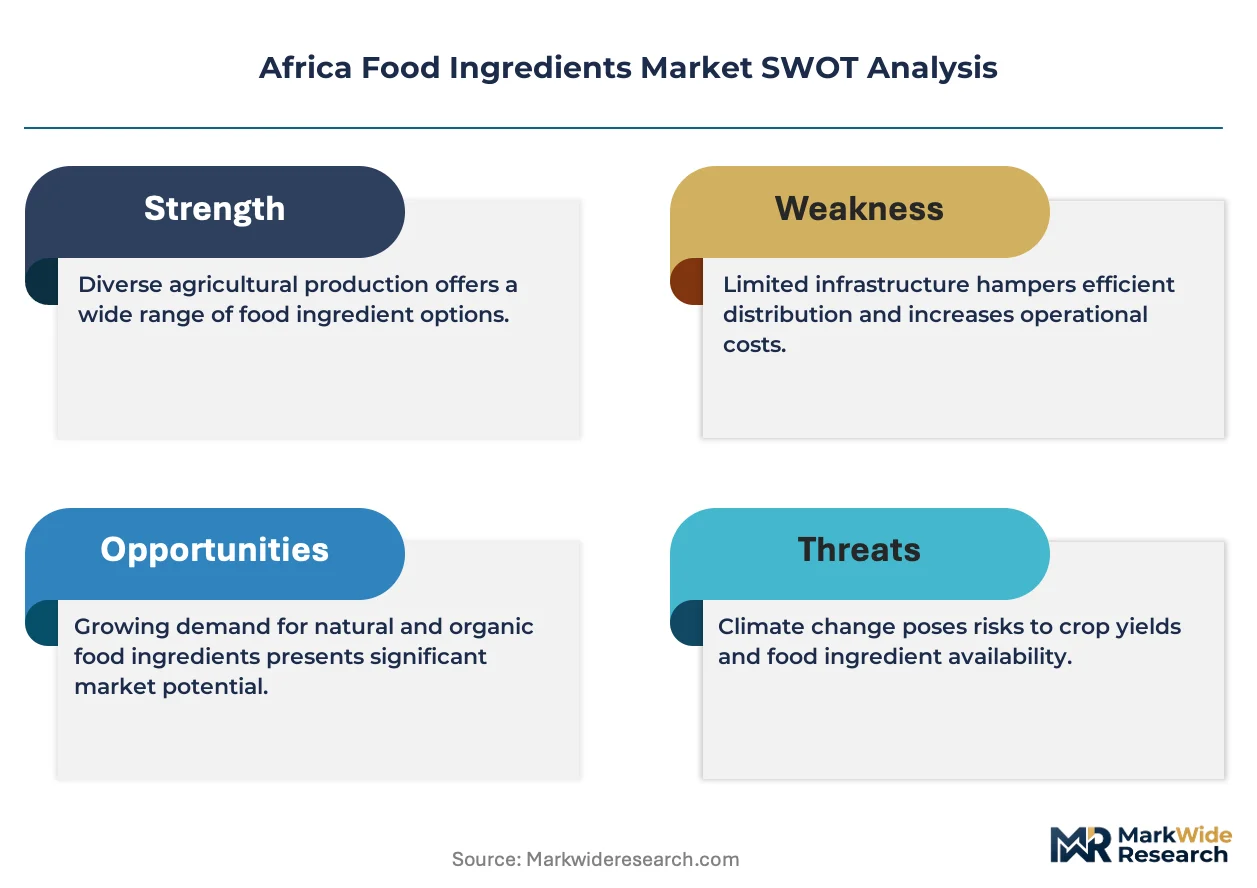
Africa food ingredients comprise functional additives, flavor systems, texturizers, and preservation chemistries formulated to withstand tropical supply chains and variable cold-chain reliability. Natural preservatives such as nisin and rosemary extract face solubility challenges in high-humidity processing environments that synthetic alternatives avoid. Preservatives command structural importance due to shelf-life extension demands in retail and wholesale channels lacking consistent refrigeration. Flavoring agents represent the fastest-growing product type as multinational fast-moving consumer goods firms localize taste profiles for Nigerian, Ethiopian, and Moroccan palates.
South Africa's Department of Health enforces additive maximum limits aligned with Codex Alimentarius frameworks, while Kenya's Bureau of Standards mandates batch-level preservative testing for imported ingredient lots. Nigeria's National Agency for Food and Drug Administration and Control requires pre-market approval for novel sweetener compounds, slowing product introduction timelines. Stakeholders must monitor harmonization negotiations between the African Continental Free Trade Area and existing national standards bodies to anticipate certificate-of-origin and mutual-recognition shifts that will reshape cross-border ingredient trade.
Market Dynamics
Clean-label additive substitution is compressing formulation cycles across African food manufacturing, as tropical supply chain instability and FSSAI-equivalent disclosure mandates force rapid preservative and emulsifier replacement. This structural pressure is redrawing procurement relationships between ingredient suppliers and processed food producers.
Growth Catalysts
- East Africa Dairy Value Chain Expansion:Kenyan and Ethiopian processors are scaling UHT milk and yogurt production, driving demand for stabilizers and probiotic cultures. Cold-chain investments in Nairobi and Addis Ababa are extending distribution reach for temperature-sensitive ingredients.
- REACH-Aligned Additive Harmonization:South Africa's Department of Health is aligning maximum residue limits with Codex Alimentarius frameworks. This regulatory convergence is simplifying cross-border formulation approvals for multinational ingredient suppliers.
- Cassava Processing Corridor Industrialization:Nigeria's integrated starch and sweetener plants are creating captive demand for modified starches and hydrocolloids. West African processors are substituting imported wheat extenders with locally sourced cassava derivatives.
Market Restraints
- Natural Preservative Solubility Failure:Nisin and rosemary extract formulations face precipitation and efficacy loss in high-humidity processing environments. Nigerian bakeries report 15-20% spoilage rates when switching from synthetic to natural preservation chemistries.
- Import Dependency for Specialty Emulsifiers:Distilled monoglycerides and DATEM supplies concentrate through Durban and Lagos port corridors. Container delays and currency volatility are extending lead times for bakery and confectionery manufacturers.
- NAFDAC Novel Compound Approval Friction:Nigeria's pre-market approval requirements for alternative sweeteners are extending product introduction timelines by 18-24 months. Stevia and monk fruit extract formulations remain in regulatory queue.
Strategic Opportunities
- Moroccan Flavor Localization:Multinational FMCG firms are adapting taste profiles for North African spice-forward palates. Custom savory and confectionery flavor houses are establishing technical service presence in Casablanca.
- Ingredient-as-a-Service Contracting:Technical formulation libraries and application-specific solutions are displacing transactional commodity purchasing. Kenyan mid-market bakeries are accessing Kerry Group flavor systems through subscription-based technical support.
- AfCFTA Certificate-of-Origin Harmonization:Mutual recognition negotiations between African Continental Free Trade Area and national standards bodies are poised to reshape cross-border ingredient trade documentation requirements.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation chemistry and tropical supply chain management expertise is concentrated in Johannesburg and Lagos. Mid-tier processors in secondary cities face recruitment bottlenecks for clean-label transition projects.
- Batch-Level Testing Compliance Burden:Kenya's Bureau of Standards mandates preservative testing for every imported ingredient lot. Testing facility capacity constraints in Mombasa are creating customs clearance delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Ingredients Market |
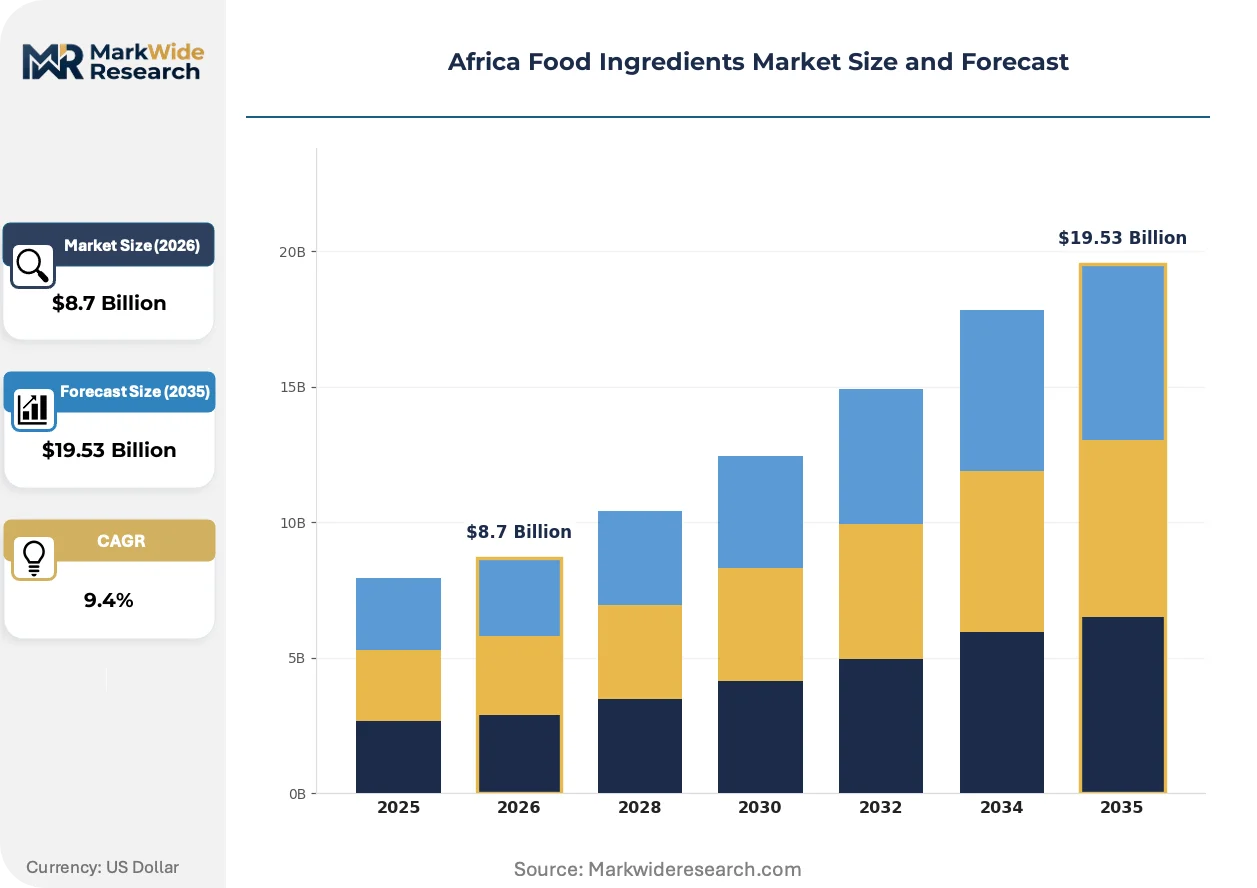
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Emulsifiers, Sweeteners, Flavoring Agents End User: Bakeries, Confectioneries, Dairy Products, Beverages Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Food Processing, Meat Products, Snack Foods, Sauces |
| Companies Covered | Givaudan S.A., Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, BASF SE, Kerry Group, Ajinomoto Co., Inc., Cape Food Ingredients, DuPont de Nemours, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Ingredients Market Emerging Trajectories
Electrification of ingredient processing infrastructure is converging with digital traceability platforms to reshape how African manufacturers verify additive provenance and manage tropical supply chain integrity. These forces are accelerating substitution timelines and reconfiguring buyer-supplier relationships.
Encapsulation technology for heat-sensitive natural preservatives is electrifying formulation possibilities in high-temperature processing environments. Nigerian tomato paste and palm oil processors are piloting lipid-shell nisin delivery systems to bypass solubility failures. This technology is compressing the performance gap between synthetic and natural preservation chemistries in ambient-stable retail products.
South Africa's Department of Health is enforcing additive maximum limits aligned with Codex Alimentarius frameworks. This regulatory convergence is eliminating duplicate testing requirements for suppliers serving both domestic and export markets. Bakery and confectionery segments are responding by consolidating formulation specifications across Southern African Development Community trade zones.
Subscription-based technical service contracts are displacing transactional ingredient purchasing among mid-tier African food manufacturers. Kenyan and Nigerian bakeries are accessing flavor libraries and application laboratories through annual service agreements rather than per-kilogram procurement. This model shift is most visible in Lagos and Nairobi, where ingredient suppliers are embedding formulation chemists directly into client production facilities.
Africa Food Ingredients Market Segmentation
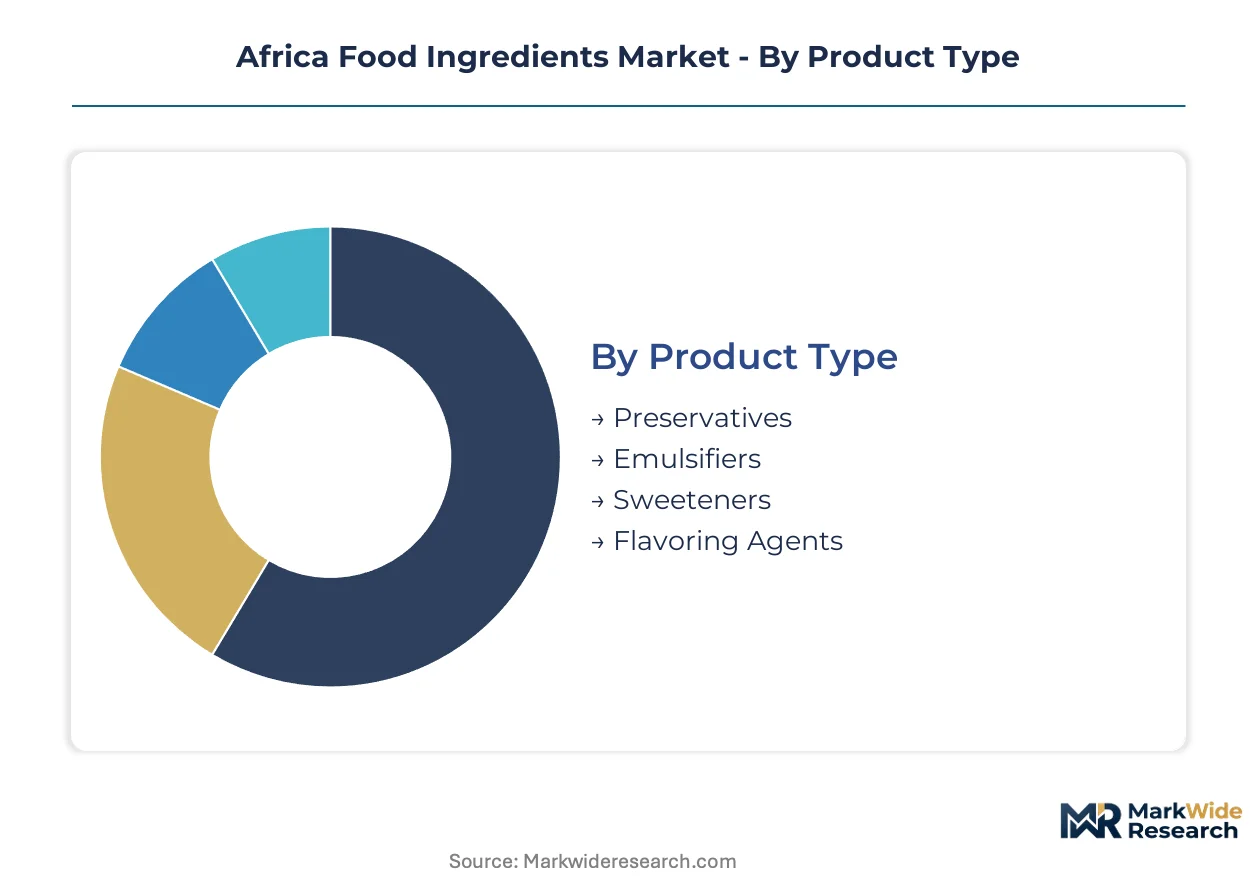
Ingredient procurement in African food manufacturing follows distinct technical and commercial logics. Buyers prioritize tropical stability, regulatory compliance, and supply security when selecting across product categories.
Product Type:
Formulation chemistry determines shelf-life performance in high-humidity climates.
- Preservatives:Sorbates, benzoates, and natural alternatives extend ambient stability where cold-chain gaps persist. Nigerian tomato paste processors consume bulk volumes to manage tropical spoilage risk.
- Flavoring Agents:Custom savory and confectionery systems adapt multinational taste profiles for Nigerian, Ethiopian, and Moroccan palates. Casablanca technical service teams localize spice-forward formulations for North African markets.
- Emulsifiers:Mono- and diglycerides stabilize fat-water interfaces in bakery and dairy applications.
- Sweeteners:Caloric and high-intensity alternatives face NAFDAC approval queues in Nigeria.
Volume sits with Preservatives; growth tilts toward Flavoring Agents.
End User:
Processing scale and cold-chain access segment buyer requirements across manufacturing tiers.
- Dairy Products:Kenyan and Ethiopian UHT milk and yogurt processors drive stabilizer and probiotic culture demand. Cold-chain investments in Nairobi and Addis Ababa extend distribution reach for temperature-sensitive inputs.
- Beverages:Carbonated and juice manufacturers source acidulants, colorants, and flavor systems. West African bottlers prioritize heat-stable formulations.
- Bakeries:Mid-tier Nigerian and Kenyan operators access technical formulation libraries through subscription contracts.
- Confectioneries:Chocolate and candy producers import specialty fats and emulsifiers through Durban and Lagos corridors.
Procurement scale concentrates in Dairy Products; application complexity peaks in Beverages.
Distribution Channel:
Supply security and technical support availability shape channel selection.
- Direct Sales:Multinational ingredient suppliers embed formulation chemists in Lagos and Nairobi production facilities. Annual service agreements displace transactional purchasing for mid-tier manufacturers.
- Wholesale:Regional distributors aggregate imports through Mombasa and Durban ports. Currency volatility extends lead times for bakery and confectionery clients.
- Retail:Small-scale processors source packaged additives through local chemical traders.
- Online:Digital platforms emerge for standardized ingredient procurement in South African urban centers.
Transaction value flows through Direct Sales; channel expansion is fastest in Wholesale.
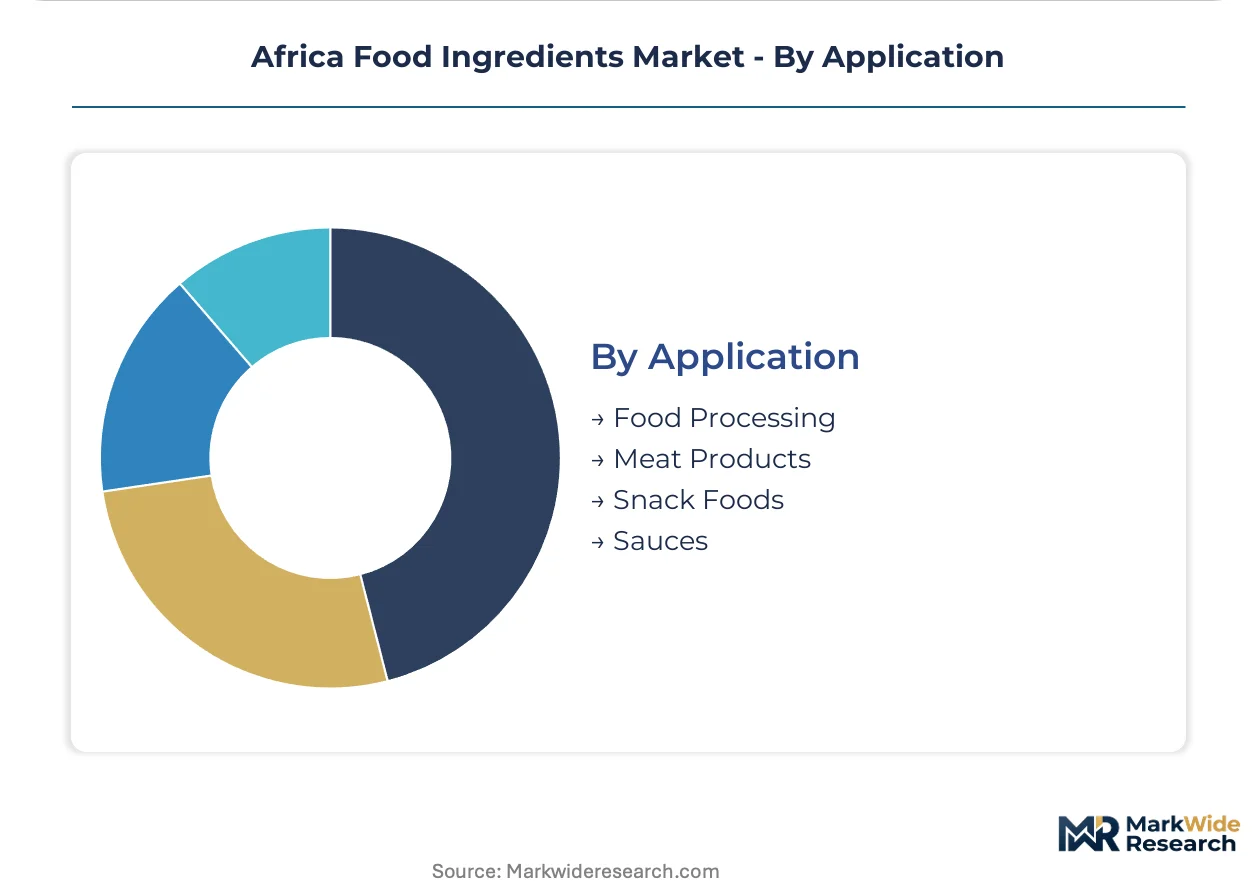
Application:
Processing temperature and water activity define functional ingredient requirements.
- Food Processing:Integrated starch and sweetener plants in Nigeria's cassava corridor create captive demand for modified starches and hydrocolloids. Local wheat extender substitution drives volume.
- Snack Foods:Extruded and fried products require oxidative stability and texture control. Palm oil processors pilot encapsulated preservative delivery systems.
- Meat Products:Cured and processed meat applications face Kenya Bureau of Standards batch-level testing mandates.
- Sauces:Tomato paste and condiment manufacturers prioritize ambient shelf-life extension.
Ingredient tonnage concentrates in Food Processing; technical innovation is most active in Snack Foods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors the West African food ingredient trade corridor, with Apapa and Tin Can Island ports handling bulk emulsifier and preservative imports for Nigerian tomato paste and bakery processors. The city's industrial zones concentrate formulation technical services and regional distribution networks serving Ghana and Côte d'Ivoire.
Nigeria
Cassava starch and sweetener plants in Ogun State drive captive demand for modified hydrocolloids and local wheat extender substitutes. NAFDAC enforces pre-market approval requirements for novel sweetener compounds, extending stevia and monk fruit extract introduction timelines. Kano's integrated food processing clusters are substituting imported inputs with domestically sourced cassava derivatives.
South Africa
UHT milk and yogurt processors in Gauteng province scale stabilizer and probiotic culture procurement as cold-chain investments extend distribution reach. The Department of Health aligns additive maximum limits with Codex Alimentarius frameworks, eliminating duplicate testing for export-bound suppliers. Durban's port corridor concentrates specialty fat and emulsifier imports for confectionery manufacturers.
Kenya
Nairobi and Addis Ababa dairy processors drive East African demand for temperature-sensitive cultures and stabilizers as regional cold-chain infrastructure expands. The Bureau of Standards mandates batch-level preservative testing for every imported ingredient lot, creating Mombasa customs clearance bottlenecks. Kenya's mid-market bakeries access flavor libraries through subscription-based technical service contracts.
Morocco
Casablanca technical service teams localize spice-forward savory and confectionery formulations for North African FMCG taste adaptation. The country's national food safety regulator enforces additive disclosure standards aligned with regional trade harmonization initiatives. Tangier-Med port logistics support ingredient re-export to West African francophone markets.
Ethiopia
Addis Ababa's emerging dairy processing sector sources stabilizers and probiotic cultures for scaled UHT and yogurt production serving domestic and regional markets. The Ethiopian Food and Drug Authority implements phased additive registration requirements for imported ingredient categories. Industrial zones around the capital attract technical service investment from regional ingredient distributors.
Africa Food Ingredients Market Vendor Landscape
Capital-heavy integrated producers compete with asset-light technical service specialists across the African food ingredient supply base. The market structure concentrates around multinational grain processors with pan-African infrastructure and regional formulation laboratories serving mid-tier manufacturers. Three archetypes dominate: integrated agribusiness conglomerates with captive supply chains, flavor and nutrition specialists with embedded technical service teams, and regional distributors aggregating imports through port corridors. Competitive moves center on backward integration into local raw material sourcing and subscription-based contracting models that displace transactional procurement.
Among Swiss and Irish flavor and nutrition specialists, Givaudan S.A. and Kerry Group occupy positions exemplifying the technical service archetype, embedding application chemists directly into client production facilities across Lagos and Nairobi. Cargill, Incorporated represents the integrated agribusiness model, leveraging pan-African grain and oilseed infrastructure to supply localized emulsifier blends. These three companies anchor the competitive structure, with regional distributors and local compounders filling gaps in secondary city markets lacking direct multinational presence.
| Leading Market Players |
|---|
| Givaudan S.A. |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| BASF SE |
| Kerry Group |
| Ajinomoto Co., Inc. |
| Cape Food Ingredients |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between Codex-aligned premium formulations and commodity-grade alternatives manifests in both procurement premiums and port-of-entry distribution patterns. Premium-tier suppliers command annual service contract pricing through embedded technical teams in Lagos and Nairobi, while commodity traders compete on landed cost via Mombasa and Durban bulk corridors.
Pricing Analysis
Margin tightening in natural preservative tiers reflects solubility failure remediation costs and encapsulation technology premiums. Three-tier pricing structure across premium, standard, and economy levels separates Codex-certified multinational suppliers from regional compounders and unpackaged chemical traders. Price differentiation hinges on batch-level testing compliance and tropical stability certification. Mid-tier Nigerian bakeries exhibit highest price sensitivity, while UHT dairy processors in Kenya and Ethiopia absorb premium stabilizer costs to secure cold-chain reliability.
Supply Chain Analysis
Dual-sourcing requirements from Kenyan and Nigerian processors mandate qualified supplier lists spanning both European REACH-aligned producers and Asian specialty chemical manufacturers. Geographic supply concentration centers on India, China, and the Netherlands for distilled monoglycerides, DATEM, and encapsulated nisin systems. Raw material dependencies include palm oil derivatives, cassava starch feedstocks, and fermentation-based cultures. Single-source vulnerability persists for lipid-shell encapsulation technology. Distribution runs through direct technical service contracts for multinational accounts and wholesale aggregators for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC's pre-market approval requirements for novel sweeteners erect a cost-of-compliance barrier that rewards incumbents with established regulatory dossiers and testing infrastructure.
For Market Incumbents: Deepen backward integration into Nigerian cassava starch production to secure captive hydrocolloid supply and offset currency volatility on imported wheat extenders. Expand technical service embedding in Addis Ababa dairy clusters before regional cold-chain investments mature. Codex alignment investments in South Africa create export pathway advantages as AfCFTA mutual recognition advances. For New Entrants and Emerging Players: Launch via subscription-based flavor library access targeting Kenyan mid-market bakeries underserved by direct multinational presence. White-space opportunity concentrates in Moroccan savory localization for North African FMCG adaptation and Ethiopian probiotic culture supply as UHT capacity scales. Technical service partnerships with regional distributors bypass port-clearance bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with asset-light technical service specialists given subscription contracting displacement of transactional procurement. Long-term viability favors flavor and nutrition platforms with embedded application laboratories across Lagos, Nairobi, and Casablanca. Signal to monitor: AfCFTA certificate-of-origin harmonization implementation pace as inflection trigger for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Lipid-shell nisin delivery systems close performance gaps with synthetic preservatives in Nigerian tomato paste processing. |
| Cassava Corridor Backward Integration | Ogun State starch plants reduce import dependency for modified hydrocolloids serving West African wheat substitution demand. |
| Technical Service Embedding | Application chemists in client facilities lock in annual contracting relationships with mid-tier Kenyan and Nigerian bakeries. |
| Codex Alignment Certification | South African Department of Health convergence eliminates duplicate testing for suppliers serving SADC export markets. |
| Regional Distributor Acquisition | Mombasa and Durban port aggregators capture customs clearance value from Kenya Bureau of Standards batch-testing mandates. |
Methodological Framework
Trade statistics from national customs authorities, Bureau of Standards regulatory filings, and pan-African grain processor disclosures formed the secondary backbone. Primary interviews with formulation chemists at multinational ingredient suppliers, procurement managers at Nigerian tomato paste processors, Kenya Bureau of Standards testing officials, and cold-chain logistics operators in Nairobi and Addis Ababa validated demand-side assumptions. Bottom-up volume modeling across preservatives, flavoring agents, emulsifiers, and sweeteners triangulated against top-down macro consumption trends.
Historical trendline analysis of import volumes through Lagos, Mombasa, and Durban ports established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, end-user industry, distribution channel, and application-specific functional requirements. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity expansion announcements. Forecast inputs included NAFDAC approval queue timelines and AfCFTA harmonization negotiation milestones.
The model assumes a particular technology adoption path; alternative pathways for encapsulated natural preservatives would alter the outlook if solubility failures persist at scale. Deviation in Kenya Bureau of Standards testing facility capacity expansion would shift customs clearance timelines and import cost structures materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Edible Oil Market
Ingredients
Oat Ingredients Market
Ingredients
Valerian Root Oil Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Mastic Gum Market
Ingredients
Birch Sap Market
Ingredients
Plant Extracts Market
Ingredients
Commercial Amino Acids Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Codonopsis Extract Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Sea Salt Market
Ingredients
Organic Pastry Flour Market
Ingredients
Lupine Peptides Market
Ingredients
Vitamin C Ingredients Market