
 Histopathology Services Market | 2026-2036
Histopathology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Histopathology Services Market Outlook
Oncology service lines within hospital systems is recalibrating how histopathology capacity gets sourced across North America and Europe. Sonic Healthcare leverages its multi-national laboratory footprint to sustain high-throughput tissue processing contracts with large health networks. Quest Diagnostics anchors its position through dense geographic coverage of community hospital systems. Neo Genomics Laboratories specializes in cancer-focused molecular pathology, differentiating its service portfolio from generalist competitors.
Histopathology services encompass the preparation, staining, microscopic examination, and diagnostic interpretation of tissue specimens using formalin-fixed paraffin-embedded blocks, microtome sectioning at 3-5 micron thickness, and hematoxylin-eosin or specialized immunohistochemical staining protocols to detect cellular abnormalities for clinical decision-making. Digital pathology now leads technology investment as laboratories replace conventional microscopy workflows with whole-slide imaging and AI-driven analysis platforms. Immunohistochemistry commands premium pricing within service type segmentation due to antibody reagent costs and specialized technician training requirements. Hospitals remain the dominant end user channel, though diagnostic laboratories capture faster growth through independent reference testing consolidation.
FDA digital pathology enforcement discretion policies, CAP laboratory accreditation standards, and CLIA certification requirements collectively shape market access barriers and quality benchmarks for service providers entering the United States market. The European Union's In Vitro Diagnostic Regulation imposes new conformity assessment obligations on histopathology reagent and instrument suppliers serving laboratories across member states. Stakeholders must monitor evolving reimbursement pathways for remote pathology interpretation as telepathology coverage determinations shift under Medicare and major commercial payers.
Market Dynamics
The transition from glass-slide microscopy to whole-slide imaging systems is compressing diagnostic turnaround times and forcing laboratories to restructure technician workflows around digital file management rather than physical specimen handling.
Growth Catalysts
- FDA enforcement discretion policies:The FDA's 2023 guidance on digital pathology devices is accelerating validation pathways for AI-assisted diagnostic algorithms, reducing time-to-market for computational pathology platforms.
- Oncology service line expansion:Academic medical centers in the United States, Germany, and China are consolidating histopathology contracts with high-throughput reference laboratories to manage rising biopsy volumes from precision oncology programs.
- Immunohistochemistry protocol automation:Robotic staining systems are standardizing antibody application consistency, enabling laboratories to scale complex biomarker testing without proportional technician hiring.
Market Restraints
- Antibody reagent cost volatility:Specialized immunohistochemistry antibodies carry per-test material costs that fluctuate with biopharma supplier pricing power, compressing margins on cancer diagnostic panels.
- Pathologist supply concentration:The United States faces acute shortages of board-certified anatomic pathologists, with training program output failing to match biopsy volume growth from aging populations and cancer screening expansion.
- CLIA certification complexity:Laboratory accreditation requirements for high-complexity testing create multi-year barriers to entry for new service providers seeking Medicare reimbursement eligibility.
Strategic Opportunities
- Telepathology reimbursement expansion:Medicare coverage determinations for remote diagnostic interpretation are creating new revenue streams for laboratories serving rural and underserved hospital systems.
- China's centralized pathology network buildout:Provincial health authorities are consolidating district-level laboratories into regional hubs, generating demand for digital pathology infrastructure and managed service contracts.
- AI-driven quality assurance convergence:Integration of whole-slide imaging with automated artifact detection is reducing diagnostic error rates while enabling leaner staffing models for overnight and weekend coverage.
Industry Challenges
- Digital pathology technician reskilling:Conventional microscopists require extensive retraining in whole-slide navigation software and digital file management systems, creating workforce transition friction during platform migrations.
- Legacy LIS integration complexity:Digital pathology platforms must interface with established laboratory information systems that lack native support for multi-gigabyte image files, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histopathology Services Market |
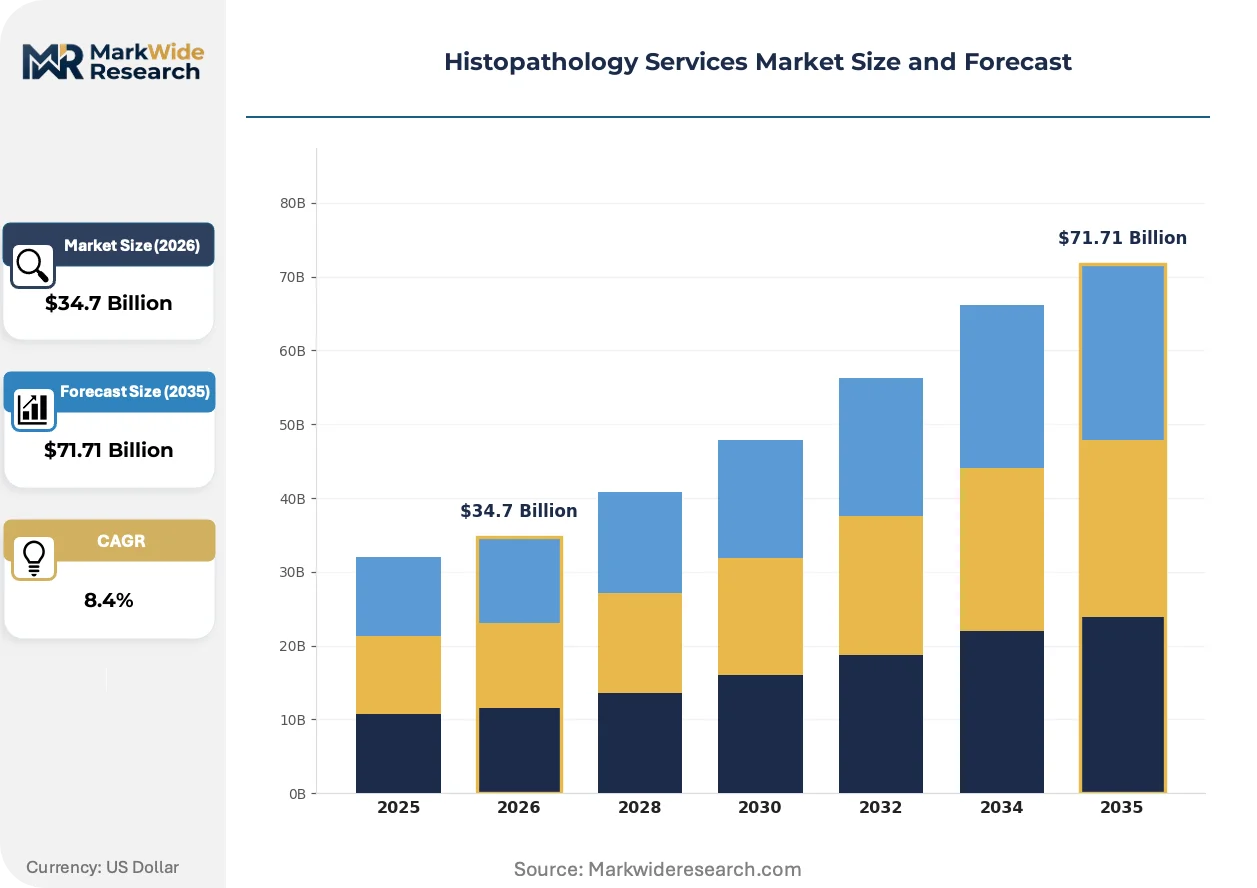
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $71.71 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tissue Processing, Staining, Digital Pathology, Immunohistochemistry End User: Hospitals, Diagnostic Laboratories, Research Institutes, Academic Institutions Application: Cancer Diagnostics, Infectious Diseases, Genetic Disorders, Autoimmune Diseases Technology: Conventional Microscopy, Automated Systems, AI-Driven Analysis, Telepathology |
| Companies Covered | Sonic Healthcare, Laboratory Corporation of America Holdings, Quest Diagnostics, Charles River Laboratories, Eurofins Scientific, Neo Genomics Laboratories, ACM Global Laboratories, Unilabs, Cerba Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histopathology Services Market Strategic Shifts
Computational pathology is displacing manual pattern recognition as the primary diagnostic modality, with machine learning algorithms now qualifying for independent biomarker quantification tasks previously reserved for specialist pathologists.
Whole-slide imaging technology is integrating convolutional neural networks for automated region-of-interest detection, compressing the time pathologists spend navigating irrelevant tissue areas. Academic medical centers in the United States are deploying these platforms for primary diagnosis of routine cases, reserving specialist consultation for complex or ambiguous specimens. The structural consequence is a bifurcation of the pathologist labor pool into algorithm supervisors and complex-case specialists.
The European Union's In Vitro Diagnostic Regulation is imposing new conformity assessment obligations on histopathology reagent and instrument suppliers, forcing manufacturers to generate clinical evidence packages for antibody and staining systems previously marketed under self-certification. Laboratories across Germany, France, and Italy are experiencing supply disruptions as suppliers withdraw non-compliant product lines. The segment most affected is specialized immunohistochemistry, where antibody diversity exceeds the regulatory resubmission capacity of smaller reagent vendors.
Hospital procurement departments are consolidating histopathology contracts under multi-year managed service agreements that bundle slide preparation, staining, imaging, and specialist interpretation into per-case pricing. Community hospital systems in the United States are displacing in-house pathology departments with reference laboratory partnerships that guarantee turnaround time service levels. This pattern is most visible in the southeastern states, where health system consolidation has concentrated purchasing power among regional hospital networks.
Histopathology Services Market Segmentation
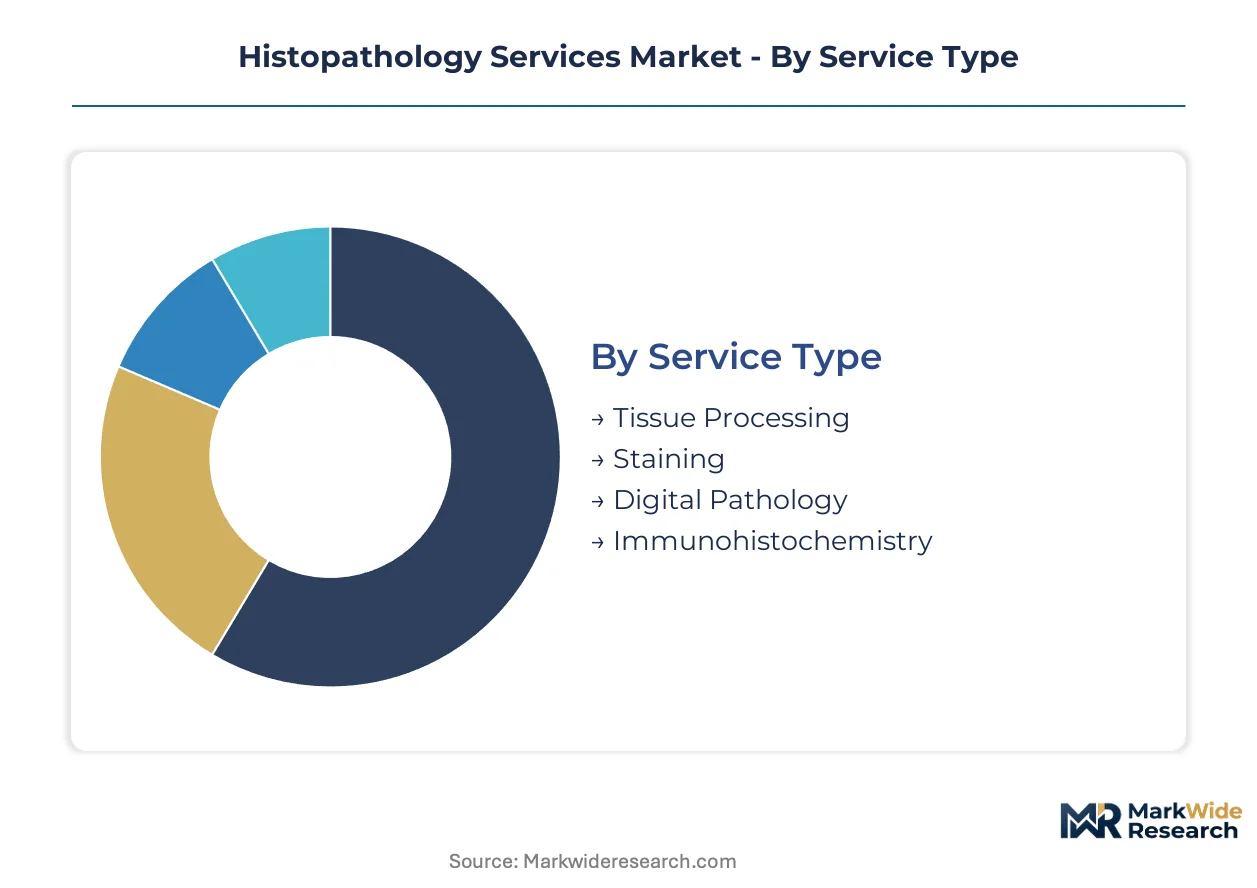
Histopathology service providers structure portfolios around four intersecting dimensions: technical complexity tiers, institutional purchasing power, disease-specific testing volumes, and digital infrastructure maturity. Each segmentation axis reveals distinct margin profiles and competitive entry barriers.
Service Type:
Volume-driven commoditized services generate cash flow while premium specialized offerings capture margin expansion from precision oncology demand.
- Immunohistochemistry:Antibody-based protein detection protocols requiring specialized reagent inventories and CAP-accredited technician certification. Demand concentrates at academic medical centers in the United States and Germany running companion diagnostic panels for targeted cancer therapies, with antibody cost volatility compressing margins on routine biomarker testing.
- Digital Pathology:Whole-slide imaging, image management infrastructure, and computational analysis platforms replacing physical slide handling. Sonic Healthcare and Neo Genomics Laboratories are consolidating high-throughput contracts with health networks seeking AI-assisted diagnostic validation pathways under FDA enforcement discretion policies.
- Tissue Processing:Formalin fixation, paraffin embedding, and microtome sectioning at standardized 3-5 micron thickness for downstream analysis. Quest Diagnostics anchors community hospital system coverage through dense geographic processing networks.
- Staining:Hematoxylin-eosin and specialized histochemical protocols for cellular morphology visualization. Regional reference laboratories compete on turnaround time guarantees for routine case volumes.
Today's leader: Immunohistochemistry. Tomorrow's challenger: Digital Pathology.
End User:
Institutional purchasing scale determines contract structure, with integrated delivery networks extracting per-case pricing concessions unavailable to standalone facilities.
- Diagnostic Laboratories:Independent reference testing consolidation is accelerating faster than hospital channel growth. Quest Diagnostics and Sonic Healthcare leverage multi-national footprints to secure multi-year managed service agreements bundling preparation, staining, imaging, and interpretation.
- Hospitals:In-house pathology departments face displacement as community hospital systems in the United States outsource to guarantee turnaround service levels. Procurement departments in southeastern states are consolidating contracts under regional network purchasing power.
- Academic Institutions:Precision oncology programs generate rising biopsy volumes requiring high-complexity interpretation and research collaboration privileges.
- Research Institutes:Preclinical toxicology and biomarker discovery services operate outside reimbursement pathways, demanding flexible protocol customization.
Diagnostic Laboratories are gaining share fastest as hospital outsourcing accelerates.
Application:
Disease prevalence and reimbursement density determine addressable market expansion trajectories across therapeutic areas.
- Cancer Diagnostics:Solid tumor biopsy analysis, lymphoma classification, and biomarker quantification for therapy selection. China's provincial health authorities are consolidating district laboratories into regional hubs to manage precision oncology program volumes.
- Infectious Diseases:Tissue-based pathogen detection for deep-seated infections and antimicrobial resistance profiling.
- Genetic Disorders:Congenital anomaly tissue examination and hereditary cancer syndrome confirmation.
- Autoimmune Diseases:Organ-specific inflammation grading and treatment response monitoring.
Cancer Diagnostics commands absolute revenue concentration; Autoimmune Diseases present the steepest expansion trajectory from underpenetrated testing protocols.
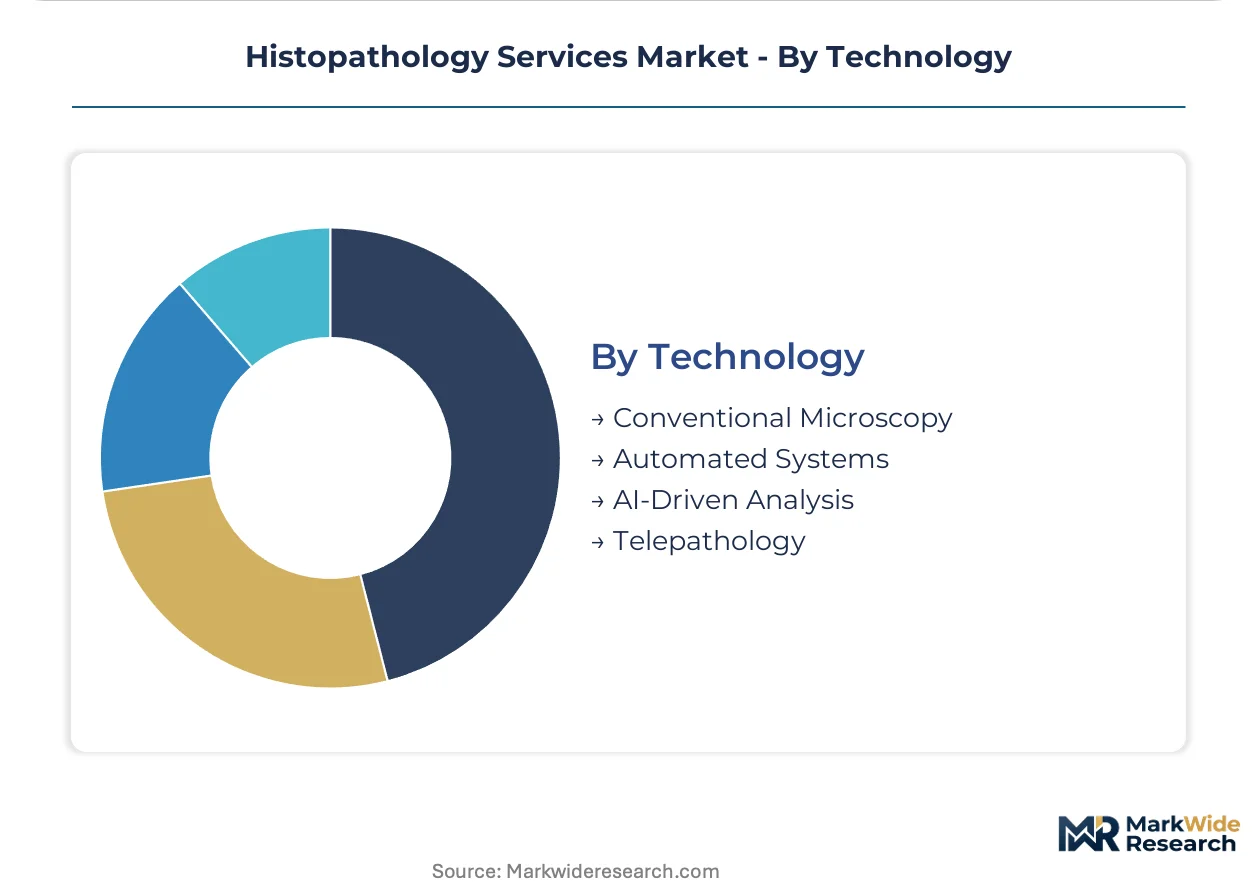
Technology:
Automation intensity separates legacy microscopists from algorithm-supervised diagnostic workflows.
- AI-Driven Analysis:Convolutional neural networks for automated region-of-interest detection and independent biomarker quantification. Academic medical centers in the United States deploy these platforms for primary diagnosis of routine cases, reserving specialist consultation for complex specimens.
- Telepathology:Remote diagnostic interpretation enabling rural and underserved hospital system coverage. Medicare coverage determinations are creating new revenue streams for reference laboratories with overnight and weekend staffing capabilities.
- Automated Systems:Robotic staining platforms standardizing antibody application consistency without proportional technician hiring.
- Conventional Microscopy:Glass-slide examination by board-certified pathologists, now reserved for complex cases and regulatory validation requirements.
AI-Driven Analysis is displacing manual pattern recognition fastest; Conventional Microscopy persists as the compliance anchor for ambiguous specimen escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where histopathology service providers establish high-throughput processing capacity, with laboratories migrating operations toward jurisdictions offering streamlined CLIA-equivalent certification pathways and favorable reimbursement density for digital pathology platforms.
United States
Precision oncology programs at academic medical centers in Boston and Houston are driving biopsy volume concentration, while FDA enforcement discretion policies accelerate AI-assisted diagnostic validation. The southeastern states exhibit the fastest outsourcing velocity as regional hospital networks consolidate pathology contracts under multi-year managed service agreements.
Germany
The EU In Vitro Diagnostic Regulation imposes new conformity assessment obligations on reagent suppliers, creating compliance cost advantages for laboratories with established quality management systems. Bavaria and North Rhine-Westphalia host the densest clusters of CAP-accredited reference laboratories serving cross-border contracts from neighboring member states.
China
Provincial health authorities in Guangdong and Jiangsu are consolidating district-level laboratories into regional hubs, generating procurement demand for whole-slide imaging infrastructure. NMPA regulatory harmonization with international standards is enabling domestic laboratories to qualify for multinational pharmaceutical trial work.
United Kingdom
NHS pathology network consolidation is compressing vendor relationships toward fewer high-volume contractors capable of guaranteeing 24-hour turnaround service levels. London and the Midlands concentrate digital pathology deployment as trusts replace legacy microscopy workflows with centralized image analysis platforms.
India
CDSCO regulatory alignment with ICH-GCP standards is positioning metropolitan reference laboratories in Mumbai and Bangalore for preclinical toxicology contracts from multinational pharmaceutical sponsors. Private diagnostic chains are capturing share from hospital-based pathology departments through franchise network expansion into tier-two cities.
Histopathology Services Market Competitive Environment
Capacity expansion dominates the current landscape as reference laboratories scale automated processing infrastructure to secure multi-year managed service agreements with consolidating health networks. The vendor base separates into three tiers: multinational diagnostic conglomerates with dense geographic footprints, cancer-focused molecular pathology specialists, and regional reference laboratories competing on turnaround time guarantees. Strategic differentiation concentrates on telepathology coverage capabilities and AI-assisted diagnostic platform deployment.
Among the multinational tier, Sonic Healthcare and Quest Diagnostics exemplify scale-driven positioning through multi-national laboratory footprints, while Neo Genomics Laboratories occupies a specialization position within cancer-focused molecular pathology. These three entities represent contrasting archetypes for market participation: geographic density, service breadth, and therapeutic area depth respectively.
| Leading Market Players |
|---|
| Sonic Healthcare |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics |
| Charles River Laboratories |
| Eurofins Scientific |
| Neo Genomics Laboratories |
| ACM Global Laboratories |
| Unilabs |
| Cerba Healthcare |
| Others |
Value Chain & Pricing Dynamics
EU In Vitro Diagnostic Regulation compliance gates qualified antibody supply and premium-tier immunohistochemistry pricing access. Laboratories lacking established quality management systems face exclusion from high-margin companion diagnostic panels as reagent vendors withdraw non-compliant product lines.
Pricing Analysis
Distributor margin compression from reference laboratory consolidation forces per-case pricing concessions on community hospital contracts. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited academic medical center rates from regional reference laboratory bids and commodity tissue processing. Cost compression in standard-tier staining services is intensifying because robotic automation eliminates technician labor arbitrage. Standalone hospitals exhibit highest price sensitivity; integrated delivery networks extract volume discounts unavailable to independent facilities.
Supply Chain Analysis
Returns and refurbishment flows for automated staining platforms concentrate refurbishment capacity in Germany and the United States. Antibody reagent production draws from biopharma suppliers in Switzerland and the United States, with specialized enzyme and chromogen inputs sourced from Japanese chemical manufacturers. Single-source vulnerability in CLIA-certified technician training pipelines creates bottleneck risk for laboratories scaling immunohistochemistry throughput. Distribution runs through direct managed service agreements rather than distributor intermediaries for high-volume health network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
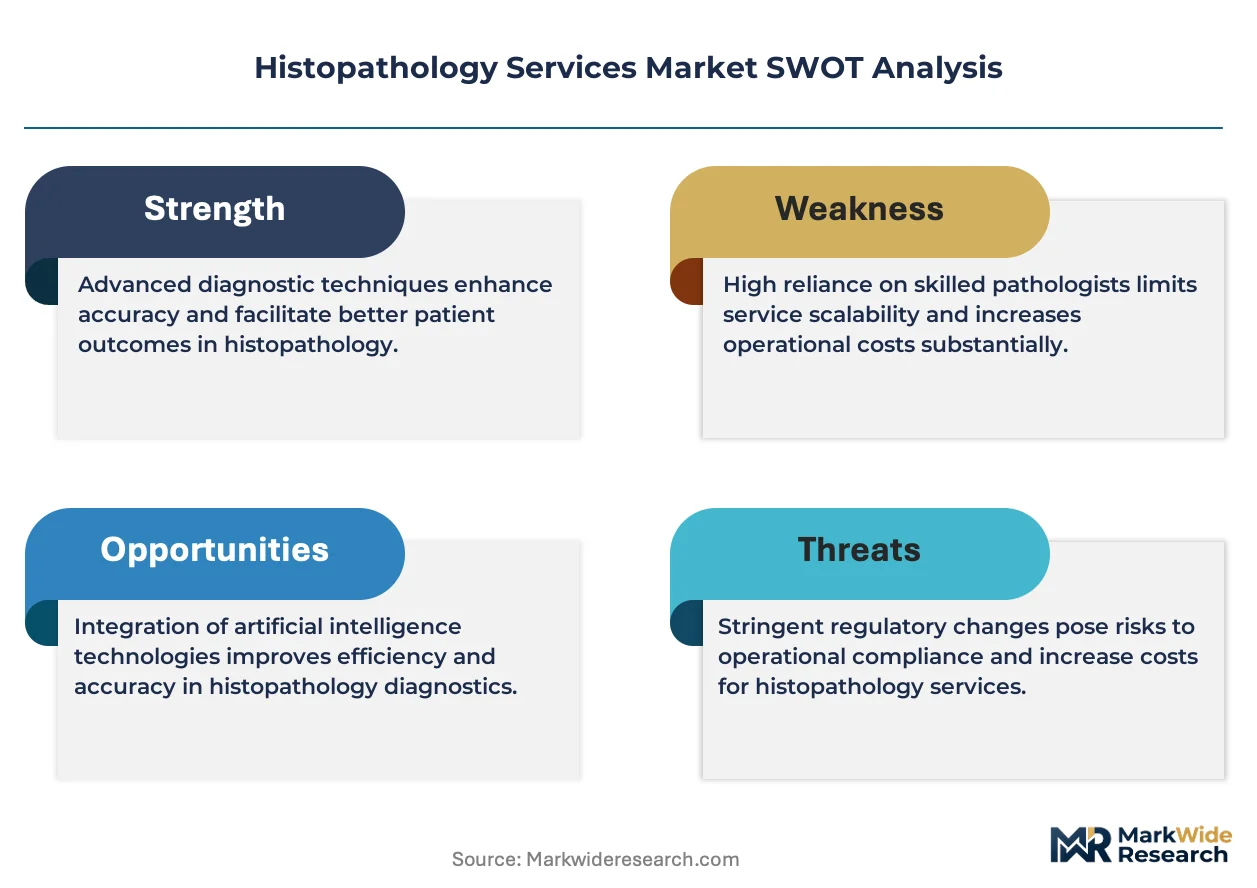
The histopathology services market functions as a stable compounder anchored by irreversible biopsy volume growth from aging demographics and precision oncology expansion.
For Market Incumbents: Deploy telepathology coverage capabilities to defend against digital-native entrants targeting rural hospital systems. Consolidate CLIA-certified technician pipelines through backward integration into training program partnerships. Anchor multi-year managed service agreements with turnaround time guarantees that lock out regional competitors. For New Entrants and Emerging Players: Direct-to-pathologist SaaS platforms offer lowest customer acquisition cost entry into AI-assisted diagnostic validation. Target autoimmune disease testing protocols as the most penetrable application segment with underdeveloped biomarker standardization. Pursue white-label digital pathology infrastructure partnerships with provincial health authorities in China. For Investors and Strategic Acquirers: Roll-up economics work for regional reference laboratories because Medicare reimbursement density varies dramatically across U.S. states, creating arbitrage opportunities for consolidated platforms. Five-to-ten-year viability rests on capturing telepathology-enabled overnight coverage capabilities. Monitor FDA enforcement discretion policy expansion for AI-independent diagnostic algorithms as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Diagnostic Validation | FDA enforcement discretion policies accelerate computational pathology platform commercialization timelines. |
| Telepathology Infrastructure Deployment | Medicare coverage determinations for remote interpretation unlock rural hospital system revenue streams. |
| CLIA Certification Investment | High-complexity testing accreditation creates multi-year barriers against unqualified market entrants. |
| Antibody Reagent Supplier Consolidation | EU IVD Regulation compliance costs force smaller vendors to exit, concentrating supply power. |
| Provincial Hub Partnership | China's regional laboratory consolidation generates demand for whole-slide imaging managed services. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down reference laboratory capacity tracking forms the analytical core of this study. Primary interviews with anatomic pathologists, laboratory operations directors, GPO contracts managers, and diagnostic reagent procurement leads combined with secondary validation against CAP accreditation databases, FDA 510(k) filings, CMS Medicare reimbursement schedules, and EU MDR conformity assessment records. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of biopsy volume growth and outsourcing velocity informed projection assumptions across the analysis window. Segmentation dimensions modeled include service type complexity tier, end-user institutional scale, disease application area, and digital infrastructure maturity. CAGRs derive from regression analysis against precision oncology program expansion rates and pathologist supply constraints. Forecast inputs incorporate CLIA certification pipeline data and NMPA regulatory harmonization progress.
Antibody reagent cost volatility, pathologist training program output shortfalls, and telepathology reimbursement policy reversals are the dominant revision risks to modeled outcomes. Practitioners should monitor these triggers for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
LIMS Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Pathology Services Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Assessment Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Laboratory Disposable Products Market