
 Sera and Reagents Market | 2026-2036
Sera and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Sera and Reagents Market Analytics
China is reconfiguring bioproduction supply chains through domestic serum fractionation investments and recombinant protein reagent manufacturing hubs. Thermo Fisher Scientific leverages its Gibco brand portfolio and cGMP-compliant production sites to anchor North American supply security. Merck KGaA sustains European market presence through its Sigma-Aldrich channel and biosafety testing reagent specialization. Bio-Rad Laboratories competes in clinical diagnostics reagents, particularly blood typing and infectious disease immunoassay components.
Sera and reagents comprise sterile biological fluids and chemically defined formulations that support cell propagation, molecular detection, and analytical calibration in controlled laboratory environments. Fetal bovine serum retains defined endotoxin thresholds below 10 EU/mL and protein concentrations standardized by lot for reproducible cell growth kinetics across biopharmaceutical applications. Reagents for diagnostics applications command premium pricing due to ISO 13485 certification burdens and batch-to-batch consistency requirements enforced by reference laboratories. Research institutions represent a volume-driven segment where price sensitivity intensifies competition among distributor-consolidated supply channels.
The FDA enforces current Good Manufacturing Practice standards for ancillary materials used in cell and gene therapy manufacturing, compelling reagent suppliers to implement drug master files and quality agreements. The European Medicines Agency's Annex 1 revision on sterile manufacturing extends contamination control expectations to critical reagents classified as Category 1 raw materials. Stakeholders must monitor evolving pharmacopeial standards for serum-free and chemically defined alternatives that reduce supply chain exposure to bovine spongiform encephalopathy risk factors.
Market Dynamics
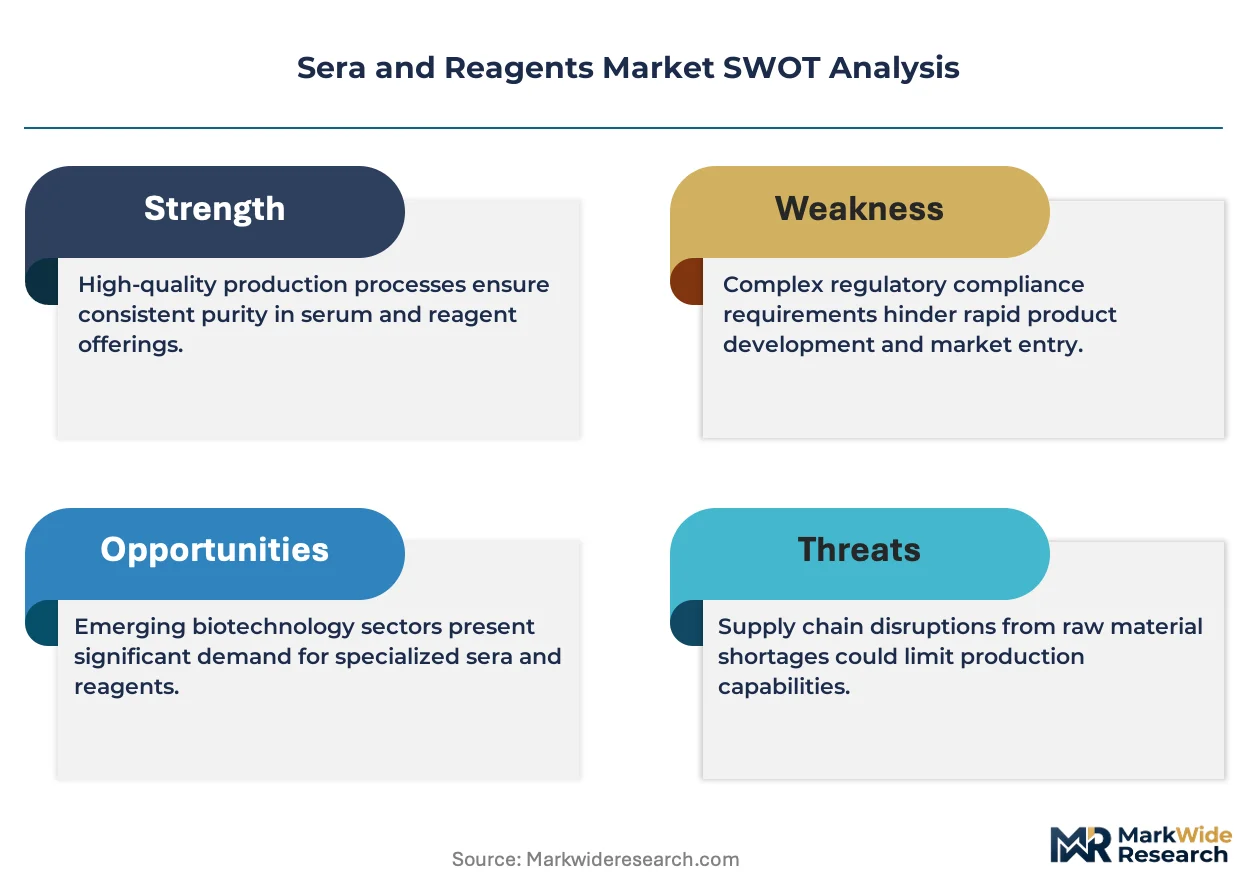
Biopharmaceutical manufacturers are compressing serum-dependent workflows into chemically defined alternatives, driven by FDA raw material traceability mandates and EMA Annex 1 contamination controls that now classify critical reagents as Category 1 raw materials requiring drug master file submissions.
Growth Catalysts
- Cell and gene therapy manufacturing scale-up:Viral vector production facilities in the United States are expanding capacity, pulling serum volumes for adherent cell propagation in bioreactor systems.
- EMA Annex 1 revision:The updated sterile manufacturing guidance elevates reagent quality agreements to mandatory status, forcing supplier qualification investments that lock in premium-tier vendors.
- Recombinant protein reagent hubs:China is domesticating fractionation capacity and chemically defined formulation manufacturing, reducing import dependency for bioproduction inputs.
Market Restraints
- Fetal bovine serum supply concentration:Harvesting operations cluster in Australia, New Zealand, and select South American territories, exposing buyers to climatic disruption and export quota volatility.
- Bovine spongiform encephalopathy regulatory friction:FDA and EMA sourcing restrictions on cattle-origin materials from specified risk materials countries block certain geographic supply pools entirely.
- ISO 13485 certification cost burden:Diagnostics-grade reagent manufacturing requires quality management system investments that price out smaller regional formulators.
Strategic Opportunities
- Serum-free media formulation:Chemically defined alternatives eliminate BSE traceability risks while meeting FDA guidance on ancillary materials for advanced therapy manufacturing.
- India bioproduction infrastructure:CDSCO is streamlining biologics manufacturing approvals, creating demand for GMP-compliant reagent supply localized to South Asian contract manufacturing.
- Digital batch record integration:Reagent suppliers embedding eBR compatibility capture preference from biopharmaceutical clients automating compliance documentation.
Industry Challenges
- cGMP compliance talent scarcity:Quality assurance professionals with cell therapy raw material experience command premium compensation, constraining mid-tier supplier expansion.
- Batch-to-batch consistency validation:Reference laboratories enforce tighter coefficient-of-variation thresholds, extending lot release timelines for serum-dependent applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sera and Reagents Market |
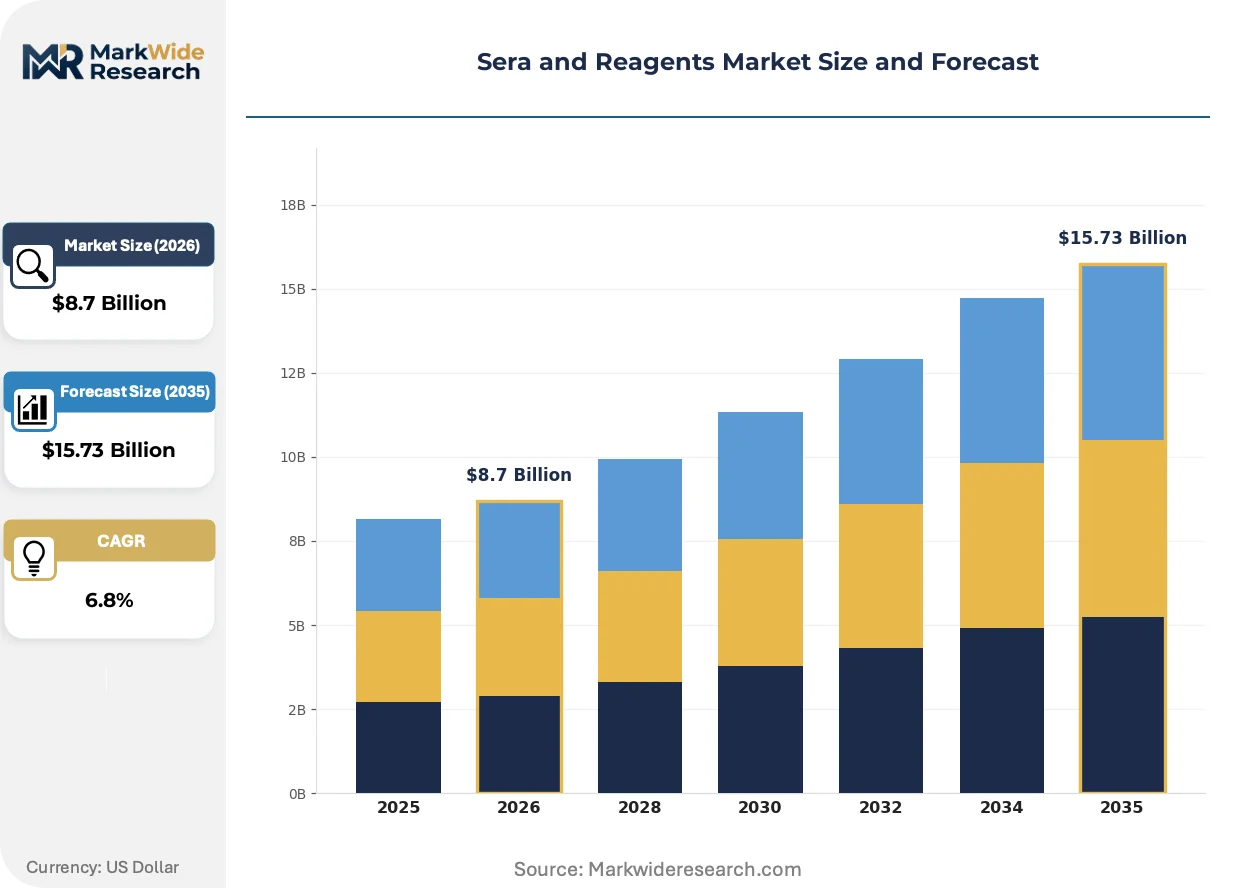
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sera, Reagents, Antigens, Antibodies Application: Diagnostics, Research, Therapeutics, Clinical Testing End User: Laboratories, Hospitals, Research Institutions, Clinics Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Bio-Rad Laboratories, Lonza, Sartorius AG, Corning, BD, Danaher Corporation, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sera and Reagents Market Evolving Landscape
Synthetic biology workflows and precision fermentation are compressing traditional serum-dependent cell culture into engineered protein production systems, while regulatory data integrity requirements force reagent suppliers to rebuild quality infrastructure around electronic systems.
Plant-derived recombinant protein supplements are collapsing the functional gap between fetal bovine serum and chemically defined media for CHO cell propagation. Biopharmaceutical manufacturers in the United States and Germany are validating these alternatives for monoclonal antibody production. The structural consequence is collapsing price premiums for premium-grade FBS as performance parity erodes differentiation.
REACH chemical registration requirements are extending substance identity obligations to reagent components used in European diagnostics manufacturing. Formulators must now document full supply chain composition for downstream medical device integration. In vitro diagnostic manufacturers are responding by consolidating supplier bases to reduce registration burden duplication.
Consolidated distributor channels are losing share to direct manufacturer relationships as biopharmaceutical procurement teams centralize reagent sourcing under single quality agreements. Large-scale CDMOs are bypassing traditional life science distributors, negotiating volume commitments directly with Gibco and Sigma-Aldrich production sites. This disintermediation concentrates most visibly in North American viral vector manufacturing clusters.
Sera and Reagents Market Segmentation
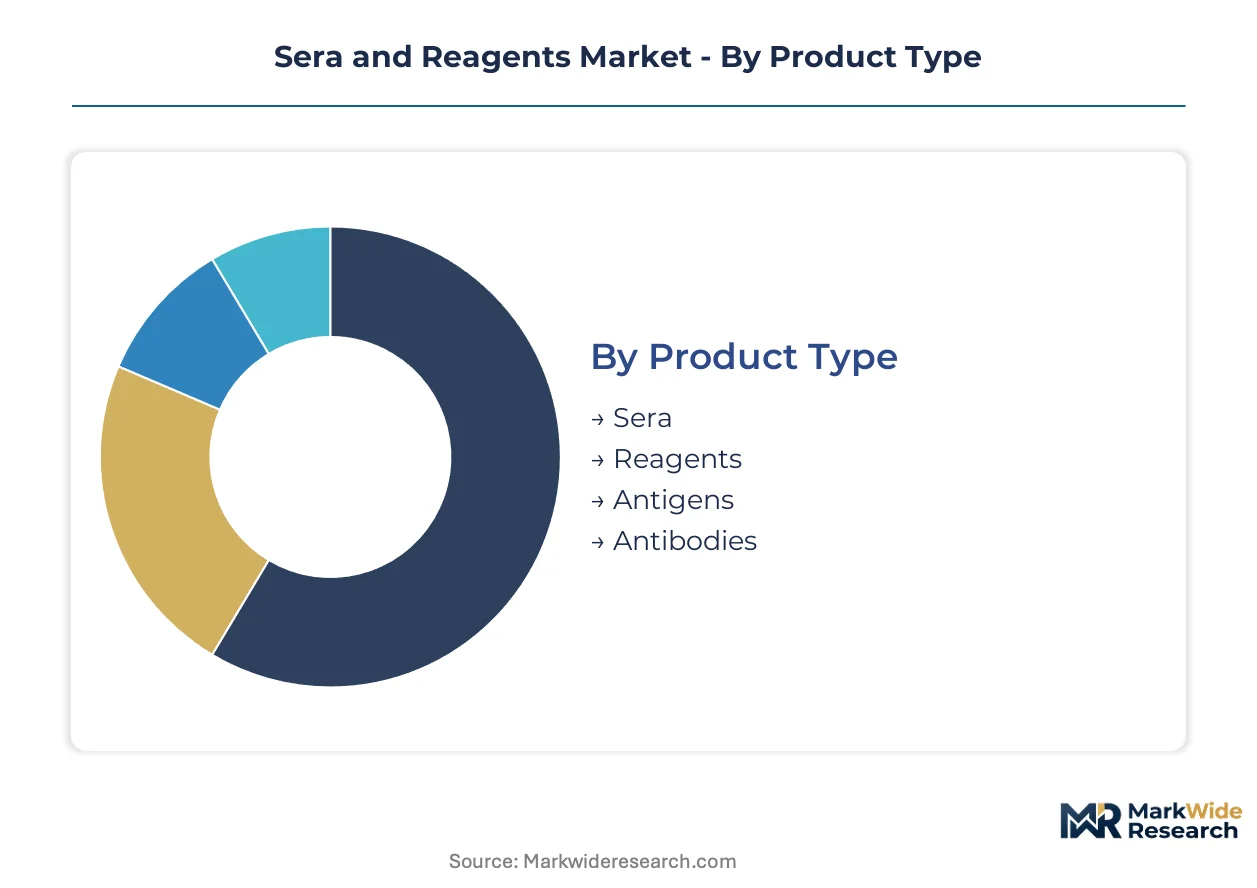
Segmentation in the Sera and Reagents Market reflects divergent quality specifications, regulatory burdens, and procurement behaviors across end-use environments. Each dimension carries distinct margin structures and supplier qualification requirements that reshape competitive positioning.
Product Type:
Cost tier differentiation separates commodity-grade inputs from certified ancillary materials for cell therapy manufacturing.
- Sera:Fetal bovine serum retains endotoxin thresholds below 10 EU/mL with standardized protein concentrations per lot. Biopharmaceutical manufacturers in the United States pull volumes for adherent cell propagation in viral vector bioreactors, though FDA traceability mandates are compressing serum-dependent workflows.
- Reagents:Chemically defined formulations include growth factors, buffers, and detection substrates with full composition disclosure. EMA Annex 1 now classifies critical reagents as Category 1 raw materials, forcing drug master file submissions that lock in premium-tier vendors.
- Antigens:Purified immunological targets for assay development and vaccine research.
- Antibodies:Monoclonal and polyclonal binding proteins for diagnostic immunoassays and therapeutic quality control.
Sera commands the established base. The steepest expansion runs through Reagents.
Application:
Application scope determines certification grade, with clinical environments imposing ISO 13485 burdens that research settings escape.
- Diagnostics:Blood typing reagents, infectious disease immunoassay components, and clinical chemistry substrates require batch-to-batch consistency enforced by reference laboratories. ISO 13485 quality management systems price out smaller formulators, consolidating supply around established manufacturers.
- Research:Volume-driven demand from academic institutions intensifies price competition through distributor-consolidated channels. China is domesticating recombinant protein reagent manufacturing to reduce import dependency for basic science applications.
- Therapeutics:cGMP-compliant ancillary materials for cell and gene therapy manufacturing with drug master file obligations.
- Clinical Testing:Point-of-care and laboratory-based assay reagents with regulatory submission requirements.
Diagnostics captures the revenue concentration. Research is climbing the fastest as funding expands for synthetic biology workflows.
End User:
Customer type shapes procurement centralization, with large-scale buyers negotiating direct manufacturer relationships that bypass traditional distribution.
- Laboratories:Reference and clinical testing facilities enforce tight coefficient-of-variation thresholds, extending lot release timelines. Consolidated distributor channels are losing share as procurement teams centralize sourcing under single quality agreements.
- Hospitals:In-house diagnostic laboratories demand just-in-time reagent supply with temperature-controlled logistics. India's CDSCO is streamlining biologics manufacturing approvals, creating demand for GMP-compliant reagent supply localized to South Asian contract manufacturing.
- Research Institutions:Academic and government laboratories with grant-funded purchasing and price sensitivity.
- Clinics:Smaller diagnostic facilities relying on distributor intermediaries for fragmented ordering patterns.
Laboratories anchor volume commitments. Hospitals are gaining share fastest through integrated health system procurement.
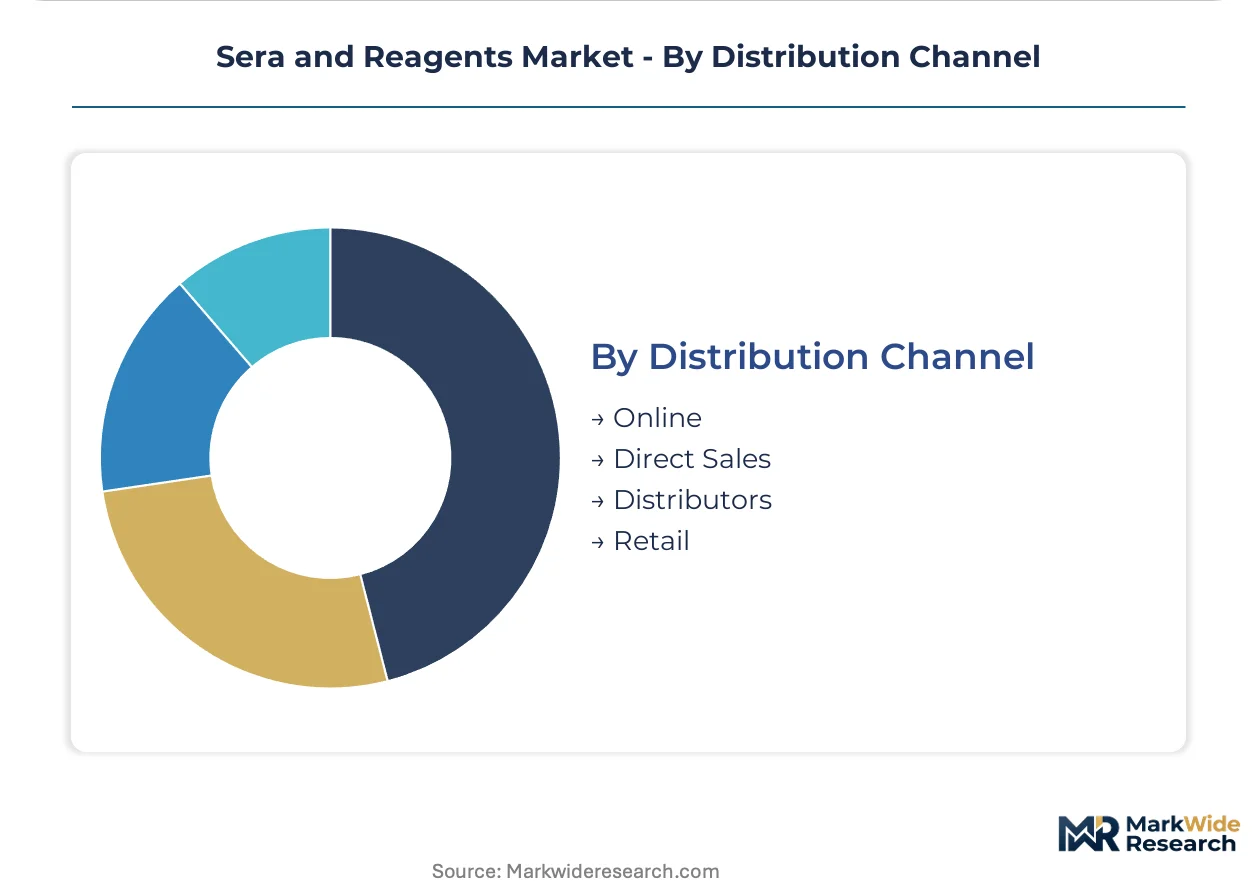
Distribution Channel:
Channel structure is reshaping around disintermediation, with direct relationships capturing preference from biopharmaceutical procurement teams.
- Direct Sales:Volume commitments negotiated between large-scale CDMOs and production sites for cGMP-compliant reagents. North American viral vector manufacturing clusters concentrate this shift most visibly.
- Distributors:Consolidated life science channels serving fragmented research and clinical customers with inventory aggregation.
- Online:E-procurement platforms for standardized catalog items with digital batch record compatibility.
- Retail:Limited presence for basic laboratory consumables in geographic markets with underdeveloped distribution infrastructure.
Distributors retain the broadest reach. Direct Sales is expanding most quickly as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes cGMP-compliant ancillary materials for cell therapy manufacturing, while China accelerates domestic fractionation capacity to reduce import dependency for basic research inputs. Germany and Switzerland anchor European demand through precision diagnostics manufacturing, with India emerging as a bioproduction outsourcing destination requiring localized reagent supply.
United States
Viral vector production facilities in Massachusetts and North Carolina are pulling serum volumes for adherent cell propagation in bioreactor systems. The FDA enforces current Good Manufacturing Practice standards for ancillary materials, compelling drug master file submissions from critical reagent suppliers. Greater Boston and Research Triangle Park concentrate contract development and manufacturing organization expansion, locking in premium-tier vendor relationships through centralized procurement.
Germany
Precision diagnostics manufacturers in Baden-Württemberg and Bavaria command ISO 13485-certified reagents for blood typing and infectious disease immunoassays. The EMA Annex 1 revision on sterile manufacturing elevates quality agreements to mandatory status, forcing supplier qualification investments. The Rhine-Main and Upper Bavaria clusters house reference laboratories enforcing tighter coefficient-of-variation thresholds, extending lot release timelines for serum-dependent applications.
China
Domestic serum fractionation investments and recombinant protein reagent manufacturing hubs are reconfiguring bioproduction supply chains. The NMPA streamlines biologics manufacturing approvals while tightening raw material traceability requirements. The Yangtze River Delta and Pearl River Delta are consolidating chemically defined formulation capacity, reducing import dependency for synthetic biology workflows.
India
The CDSCO is streamlining biologics manufacturing approvals, creating demand for GMP-compliant reagent supply localized to South Asian contract manufacturing. Hyderabad and Bengaluru bioclusters are expanding viral vector and biosimilar production capacity. Maharashtra and Gujarat house emerging fill-finish operations requiring just-in-time reagent supply with temperature-controlled logistics infrastructure.
Switzerland
Swissmedic maintains stringent oversight of ancillary materials for advanced therapy manufacturing, reinforcing premium-tier supplier concentration. Basel and Zurich anchor precision diagnostics and biopharmaceutical headquarters operations with integrated quality agreement frameworks. The country's contract manufacturing organizations are negotiating direct manufacturer relationships that bypass traditional life science distribution channels.
Sera and Reagents Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct vendor categories: diversified life science conglomerates with cGMP-compliant production networks, specialized diagnostics reagent formulators with ISO 13485 certification, and emerging regional fractionators capturing domestic supply security mandates. Consolidation pressures intensify as large-scale contract manufacturing organizations centralize procurement under single quality agreements, while regulatory data integrity requirements force quality infrastructure rebuilds around electronic systems.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify positioning anchored by production site networks and channel reach. Thermo Fisher's Gibco brand portfolio represents the cGMP-compliant supply security archetype, while Merck KGaA's Sigma-Aldrich channel occupies the diagnostics-specialized reagent position. Bio-Rad Laboratories sits within the clinical diagnostics-focused specialist category, with Lonza representing the contract manufacturing-integrated supply model. These four names illustrate how competitive positioning fragments across certification grade, geographic production footprint, and end-use segment concentration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Bio-Rad Laboratories |
| Lonza |
| Sartorius AG |
| Corning |
| BD |
| Danaher Corporation |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Bovine spongiform encephalopathy sourcing restrictions from specified risk materials countries determine both the premium commanded by Australian and New Zealand fetal bovine serum and the three-tier supplier network that funnels certified product toward cell therapy manufacturers.
Pricing Analysis
Geographic price spreads between Australian-origin fetal bovine serum and South American alternatives have widened as FDA traceability mandates compress acceptable sourcing pools. Certification grade and ISO 13485 quality management system investments drive differentiation, with diagnostics-grade reagents commanding substantial premiums over research-grade equivalents. Cost compression in the research-grade tier is intensifying because Chinese domestic fractionation capacity is displacing import volumes. Academic institutions exhibit the highest price sensitivity, while cell and gene therapy CDMOs prioritize supply security over unit economics.
Supply Chain Analysis
Extended payment terms from large-scale biopharmaceutical CDMOs are forcing mid-tier reagent suppliers to access supply-chain finance facilities, compressing working capital cycles throughout the distribution network. Raw material harvesting concentrates in Australia, New Zealand, and select South American territories, with chemically defined formulation capacity expanding in China and India. The supply chain rests on fetal bovine serum raw material dependencies, recombinant protein expression systems, and cGMP-compliant ancillary material production networks. Single-source vulnerability runs through Australian serum fractionators exposed to climatic disruption and export quota volatility. Distribution runs through direct manufacturer relationships for premium-tier volumes and consolidated life science distributors for fragmented research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital batch record integration and quality agreement management services are expanding faster than base reagent volumes, creating recurring-revenue layers that attach to every hardware shipment.
For Market Incumbents: Harden cGMP-compliant production site networks against emerging Chinese recombinant protein reagent hubs by securing exclusive quality agreements with North American viral vector CDMOs. Deepen upstream control over Australian and New Zealand serum fractionation capacity through long-term offtake contracts that lock out emerging regional competitors. The priority defensive investment is electronic batch record infrastructure that automates FDA data integrity compliance for cell therapy clients. For New Entrants and Emerging Players: India's CDSCO-streamlined biologics manufacturing approvals represent the most penetrable entry point for GMP-compliant reagent supply localized to South Asian contract manufacturing. Chemically defined media formulations for CHO cell propagation in biosimilar production offer a second white-space target with lower certification barriers than cell therapy ancillary materials. The optimal go-to-market angle is temperature-controlled logistics partnerships that solve just-in-time delivery gaps for Hyderabad and Bengaluru bioclusters. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated production site networks with existing drug master file portfolios. Long-term viability across the projection horizon hinges on regulatory data integrity capabilities rather than commodity volume scale. Acquisition targets should display ISO 13485 certification with embedded eBR compatibility and direct relationships with at least two large-scale CDMOs. The signal to watch is EMA Annex 1 enforcement actions that disqualify non-compliant suppliers and accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Submission | FDA cGMP compliance for ancillary materials locks in premium-tier vendor status with cell therapy manufacturers. |
| Serum-Free Media Formulation | Chemically defined alternatives eliminate BSE traceability risks while meeting FDA guidance on advanced therapy manufacturing. |
| Direct CDMO Relationship | Volume commitments with North American viral vector manufacturers bypass distributor intermediaries and capture procurement centralization. |
| Digital Batch Record Integration | eBR compatibility captures preference from biopharmaceutical clients automating compliance documentation and quality agreements. |
| Australian Fractionation Capacity | Long-term offtake contracts secure BSE-free serum supply against climatic disruption and export quota volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biopharmaceutical quality assurance directors, CDMO procurement leads, reference laboratory managers, and reagent supplier regulatory affairs specialists; and secondary validation against FDA drug master file databases, EMA Annex 1 guidance documents, CDSCO biologics approval records, and customs trade data for serum and reagent imports. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from production capacity disclosures and end-use demand modeling.
Forecast inputs considered serum-dependent versus chemically defined media substitution rates, viral vector manufacturing capacity expansion across the analysis window, and regulatory enforcement intensity for Category 1 raw material classification. Segmentation dimensions modeled include product type tier, application certification grade, end-user procurement centralization, and distribution channel structure. CAGRs were derived from slope-intercept analysis of historical trajectory and forward-looking capacity buildout schedules, with biopharmaceutical manufacturing intensity and diagnostics testing volume serving as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical capital expenditure cycles, trade policy affecting Australian serum export quotas, or regulatory harmonization between FDA and EMA would shift the trajectory. Forecasts reflect documented assumptions about substitution elasticity and enforcement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Pathology Services Market
Laboratory Services
Central Lab Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
LIMS Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Clinical Laboratory Services Market