
 Connected Parking Solutions Market | 2026-2036
Connected Parking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Parking Solutions Market Analytics
The capital-intensity divergence between hardware manufacturers and software platform operators is unwinding as integrated solution providers capture larger contract values. Siemens Mobility GmbH leverages its rail and traffic management heritage to bundle parking systems with broader urban mobility contracts. Kapsch TrafficCom anchors its position through long-term concession agreements with European transport authorities. EasyPark Group competes via mobile-first reservation platforms that reduce friction for private operators entering digital parking.
Connected parking solutions integrate IoT sensors, cloud computing architectures, and mobile payment interfaces to automate space detection, occupancy monitoring, and transaction processing for urban and commercial parking assets. These systems typically deploy ultrasonic or camera-based detection with sub-minute latency to central management platforms, enabling dynamic pricing and real-time availability mapping for drivers. Parking Management Systems dominate current revenue pools due to recurring software licensing and maintenance contracts, while Reservation Platforms represent the fastest-expanding segment as consumer expectations shift toward guaranteed space availability. IoT Sensors constitute the most mature technology layer with established supplier bases, whereas Mobile Payments command disproportionate margin contribution through transaction fee structures.
The EU Green Deal and F-Gas Regulation shape equipment standards for sensor networks deployed in European urban environments, while the US DOT and municipal procurement codes influence interoperability requirements for on-street deployments. FDA and FCC frameworks do not directly govern this sector, though FCC Part 15 compliance governs wireless sensor communications in US installations. Stakeholders must monitor how evolving data privacy standards affect camera-based occupancy detection and whether procurement consolidation among municipalities favors bundled platform providers over point-solution vendors.
Market Dynamics
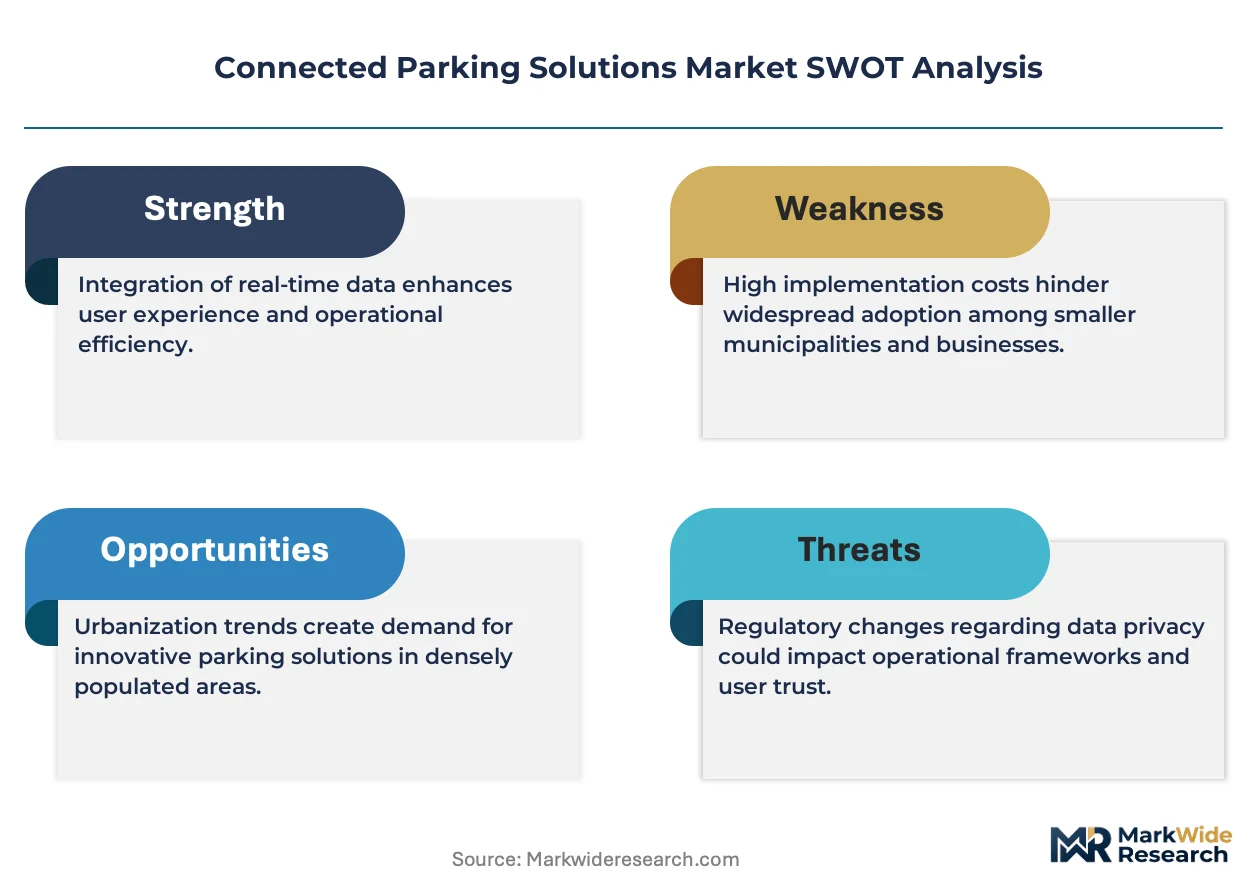
Municipal procurement consolidation is compressing vendor margins as cities favor bundled platform contracts over discrete sensor purchases, forcing hardware specialists toward software integration or niche defense.
Growth Catalysts
- EU Green Deal urban mobility mandates:Binding emissions targets for city centers are compelling transport authorities to deploy intelligent traffic management with embedded parking optimization.
- Ultrasonic sensor networks:Sub-minute latency occupancy detection is enabling dynamic pricing algorithms that maximize asset utilization for commercial garage operators.
- Germany:Federal funding for smart city infrastructure is channeling investment toward integrated parking management systems in metropolitan transport hubs.
Market Restraints
- Camera module supply concentration:Dependence on East Asian sensor fabricators creates input cost volatility and delivery timeline risk for vision-based detection systems.
- F-Gas Regulation compliance:EU equipment standards for outdoor sensor housings are raising manufacturing complexity and certification costs for European deployments.
- Mobile payment fragmentation:Proliferation of incompatible transaction platforms is forcing operators to maintain multiple integration layers, elevating technical debt.
Strategic Opportunities
- France:Underpenetrated secondary cities outside Paris present whitespace for reservation platform operators targeting municipal concession tenders.
- Edge-AI convergence with 5G:On-device inference combined with low-latency cellular is enabling real-time occupancy prediction without cloud dependency.
- US DOT MUTCD alignment incentives:Federal guidance on intelligent transportation system interoperability is creating procurement preference for standards-compliant integrated platforms.
Industry Challenges
- Embedded systems firmware expertise:Scarcity of engineers proficient in ultra-low-power IoT programming is constraining product development cycles for sensor manufacturers.
- Legacy parking access control integration:Retrofitting cloud-native platforms onto decades-old barrier and payment infrastructure demands costly custom middleware development.
- GDPR data governance:Camera-based vehicle recognition systems face extended legal review timelines for biometric data handling protocols in European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Parking Solutions Market |
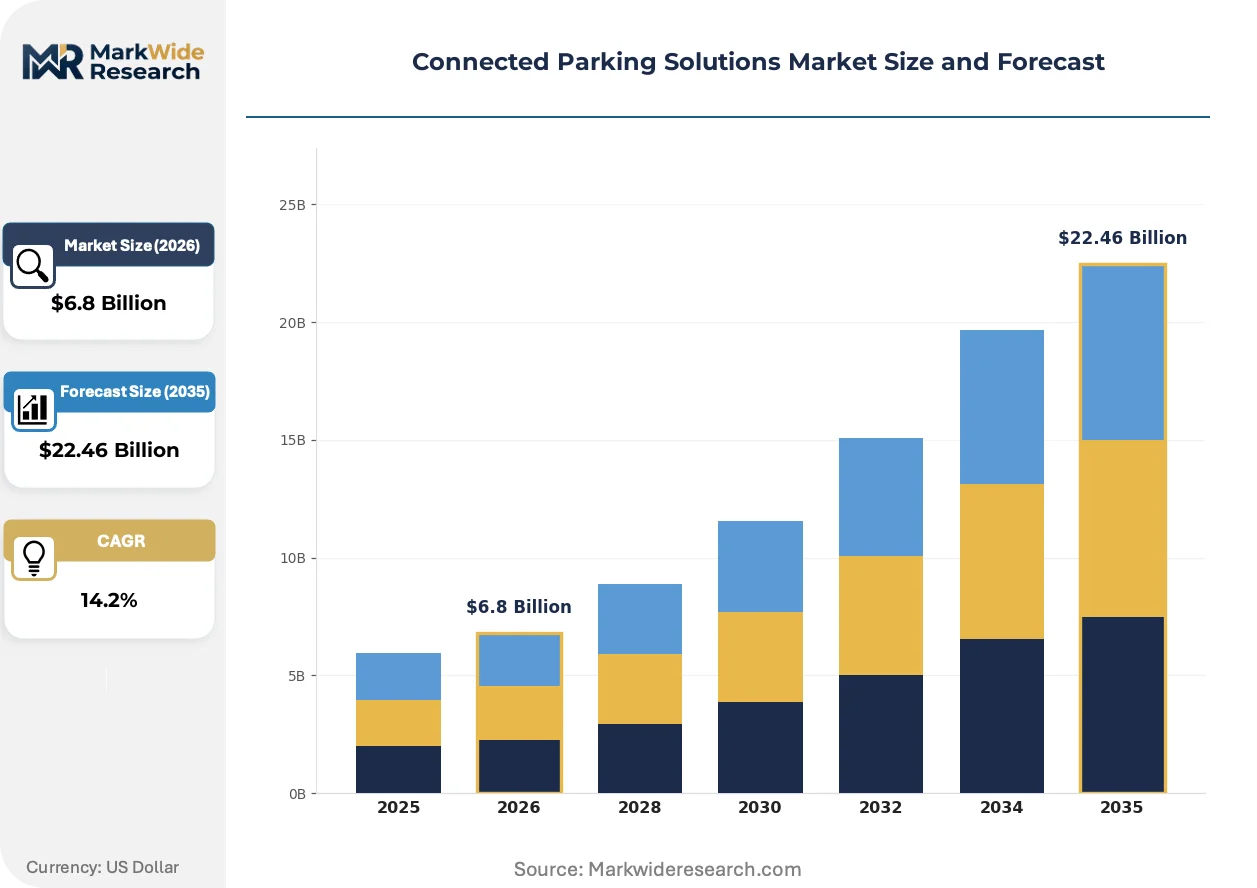
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Parking Meters, Parking Management Systems, Reservation Platforms, Mobile Apps Technology: IoT Sensors, Cloud Computing, RFID, Mobile Payments End User: Municipalities, Private Operators, Retail Establishments, Universities Deployment: On-Street Solutions, Off-Street Solutions, Hybrid Systems, Multi-Storey Facilities |
| Companies Covered | ParkMobile, LLC, IPS Group, Inc., Kapsch TrafficCom, Siemens Mobility GmbH, Robert Bosch GmbH, SKIDATA AG, Amano McGann, Inc., EasyPark Group, NWAVE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Parking Solutions Market Evolving Landscape
Edge computing architectures are redistributing processing load away from centralized cloud platforms, while regulatory pressure on embodied carbon is reshaping equipment procurement criteria across municipal buyers.
Camera-based computer vision with on-device license plate recognition is supplanting magnetic loop detectors and ultrasonic sensors in high-throughput urban deployments. Municipal transport authorities in Germany and the Netherlands are adopting these systems at accelerated pace for congestion pricing zones. The shift is compressing maintenance contract values for legacy sensor vendors while expanding software licensing revenue pools for integrated platform providers.
The EU AI Act's risk classification framework is imposing documentation and human-oversight requirements on automated parking enforcement systems using biometric identification. Equipment manufacturers must now maintain algorithmic audit trails and bias-testing protocols for camera-based vehicle recognition. French and Italian operators are responding by segregating data processing pipelines to isolate high-risk identification functions from routine occupancy detection.
Subscription-based platform access is displacing perpetual license sales among commercial parking asset managers seeking to convert capex to opex. Large retail and airport operators in Spain and the UK are driving this transition, demanding usage-based pricing tied to transaction volumes rather than fixed annual fees. The model is most visible in multi-site portfolios where centralized platform management reduces per-location IT overhead.
Connected Parking Solutions Market Segmentation
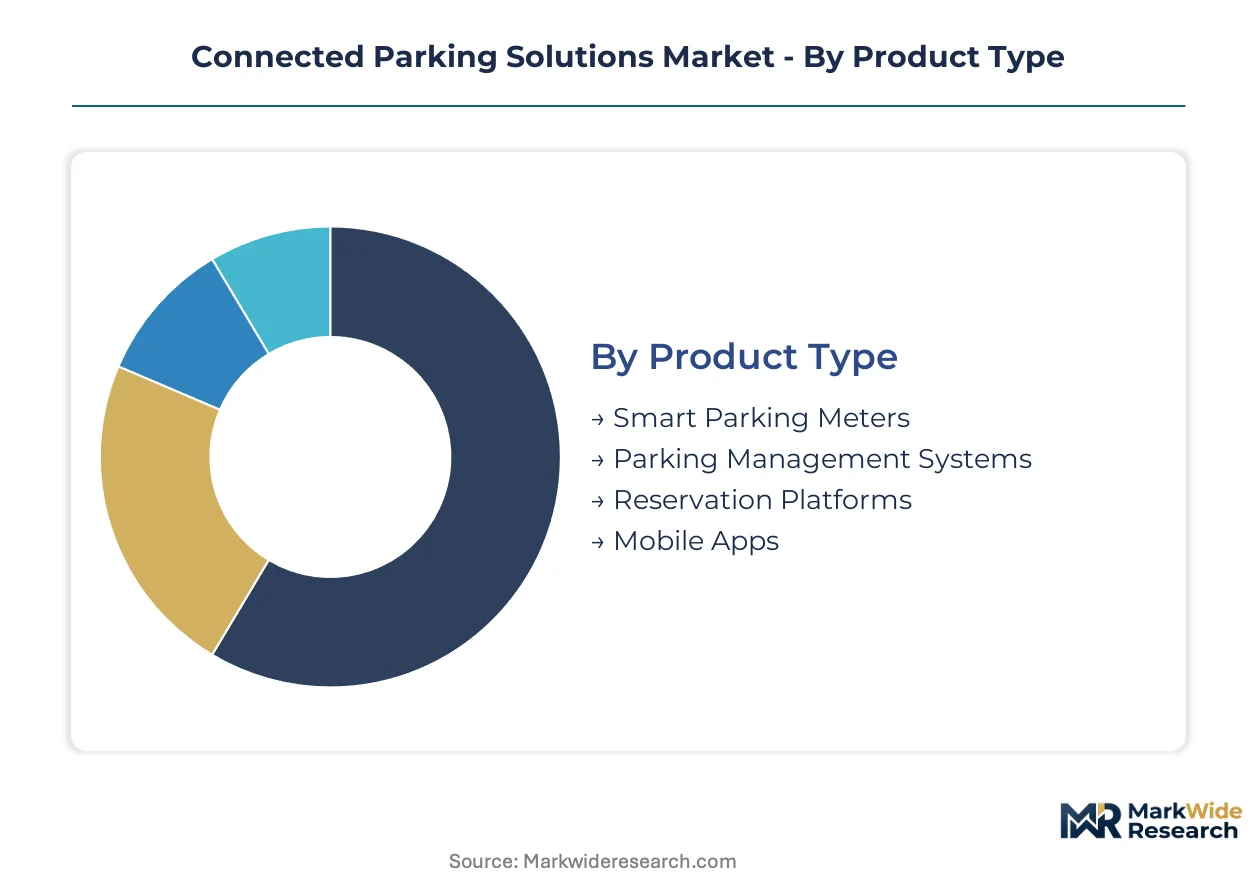
Connected parking solutions fragment across four intersecting dimensions that determine procurement pathways and margin structures. Product type governs whether vendors sell through municipal RFPs, SaaS subscriptions, or hardware tenders. Technology choices dictate integration complexity and recurring revenue potential for platform operators.
Product Type:
Channel mix varies sharply across product categories, with integrated platforms flowing through multi-year municipal concessions while point solutions distribute via direct sales to private asset managers.
- Parking Management Systems:Centralized software platforms orchestrating space allocation, enforcement, and revenue collection across distributed parking assets. Siemens Mobility GmbH and Kapsch TrafficCom anchor municipal pipelines in Germany where federal smart city funding concentrates demand for bundled urban mobility contracts. These systems generate recurring licensing and maintenance revenue pools that exceed hardware margins.
- Reservation Platforms:Cloud-native booking engines enabling guaranteed space availability through mobile interfaces. EasyPark Group competes aggressively in France's underpenetrated secondary cities outside Paris, where municipal concession tenders favor mobile-first operators reducing friction for private entrants. Expansion concentrates here as consumer expectations shift toward certainty.
- Smart Parking Meters:Connected payment terminals with integrated card, mobile, and contactless transaction processing.
- Mobile Apps:Consumer-facing interfaces for space discovery, navigation, and cashless payment completion.
Parking Management Systems dominate installed base. Reservation Platforms are where expansion concentrates.
Technology:
Cost tier stratification separates mature hardware components from software layers commanding disproportionate margin contribution.
- IoT Sensors:Ultrasonic and camera-based detection hardware with sub-minute latency to central platforms. These constitute the most mature technology layer with established supplier bases concentrated in East Asian fabrication centers, creating input cost volatility for European deployments facing F-Gas Regulation compliance for outdoor housings.
- Mobile Payments:Transaction processing infrastructure capturing fees per parking session. Proliferation of incompatible platforms forces operators to maintain multiple integration layers, elevating technical debt while generating recurring revenue streams that software specialists prioritize.
- Cloud Computing:Centralized data architectures for occupancy analytics and dynamic pricing algorithms.
- RFID:Radio-frequency identification for automated vehicle entry and exit credentialing.
IoT Sensors anchor hardware procurement volumes. Mobile Payments command the steepest margin expansion trajectory.
End User:
Customer type determines pricing model preference, with municipalities favoring capex-heavy integrated systems while private operators shift toward opex-converting SaaS structures.
- Municipalities:City transport authorities procuring through concession agreements and smart city infrastructure grants. EU Green Deal urban mobility mandates bind emissions targets that compel intelligent traffic management adoption, particularly in German metropolitan hubs where federal funding channels investment.
- Private Operators:Commercial garage and lot managers seeking usage-based platform access. Large retail and airport operators in Spain and the UK drive subscription displacement of perpetual licenses, demanding pricing tied to transaction volumes rather than fixed annual fees.
- Retail Establishments:Store-anchored parking assets integrating loyalty program tie-ins.
- Universities:Campus transportation departments managing permit and visitor parking workflows.
Municipalities anchor long-term contract value. Private Operators are expanding most quickly through SaaS conversion.
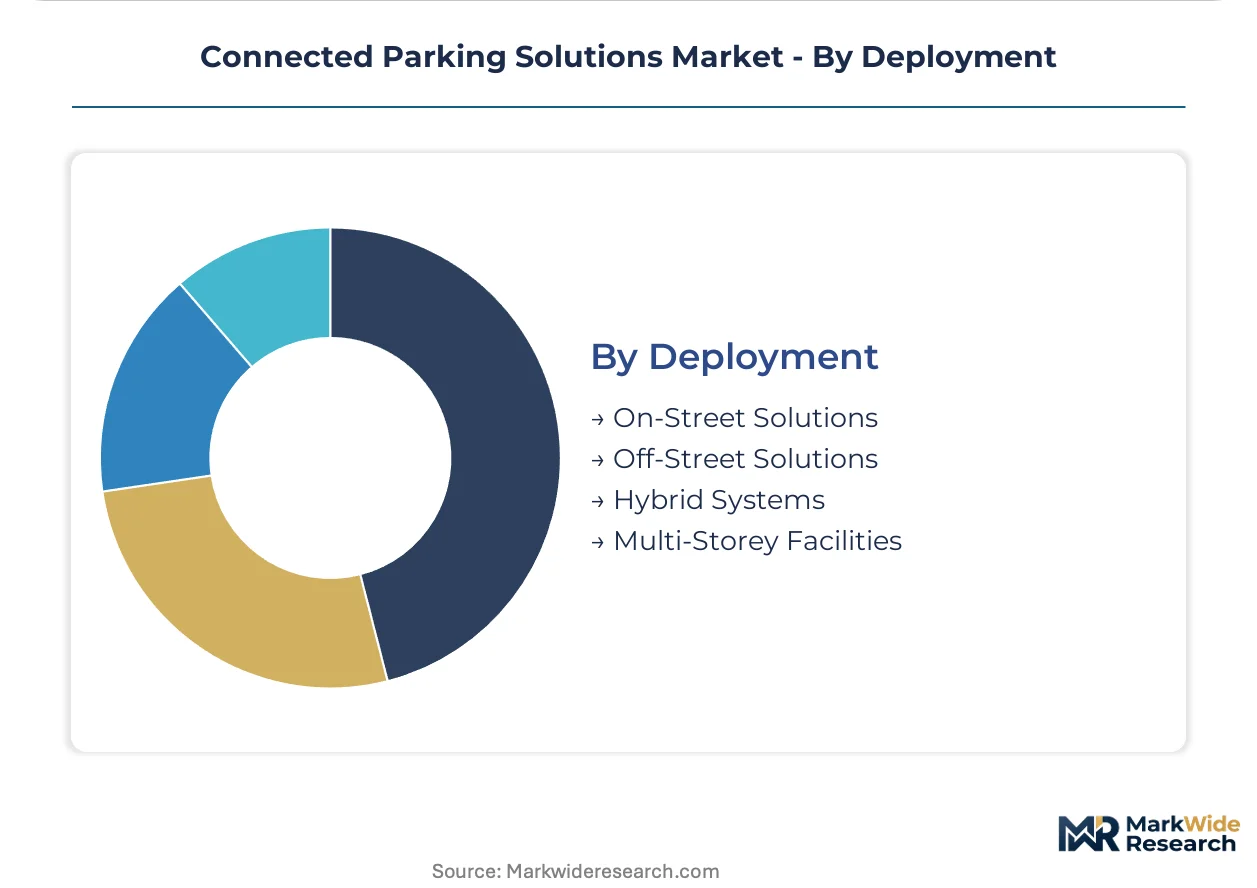
Deployment:
Application context shapes sensor density requirements and integration complexity with legacy access control infrastructure.
- On-Street Solutions:Curb-side metering and enforcement systems for urban thoroughfares. Camera-based computer vision with on-device license plate recognition supplants magnetic loop detectors in German and Dutch congestion pricing zones, compressing maintenance values for legacy sensor vendors.
- Off-Street Solutions:Surface lots and standalone facilities with gated entry and exit control.
- Multi-Storey Facilities:Vertical structures requiring guided parking and level-specific occupancy mapping. Retrofitting cloud-native platforms onto decades-old barrier infrastructure demands costly custom middleware development that constrains deployment timelines.
- Hybrid Systems:Combined on-street and off-street management under unified platform architecture.
On-Street Solutions concentrate technology upgrade cycles. Multi-Storey Facilities present the deepest integration challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement elasticity varies sharply across geographies, with German transport authorities exhibiting lowest price sensitivity due to federal smart city subsidies, while Spanish private operators demand usage-based SaaS conversion to minimize capex exposure.
Germany
Federal smart city infrastructure grants and EU Green Deal urban mobility mandates concentrate demand for bundled parking management systems. KBA vehicle standards and F-Gas Regulation compliance requirements shape equipment procurement for outdoor sensor networks. Metropolitan transport hubs in Berlin, Munich, and Hamburg anchor project pipelines where Siemens Mobility GmbH and Kapsch TrafficCom compete for long-term concession agreements.
France
Secondary cities outside Paris present whitespace for reservation platform operators as municipal concession tenders favor mobile-first entrants reducing friction for private operators. CNIL data governance protocols and GDPR biometric handling requirements extend legal review timelines for camera-based vehicle recognition systems. Lyon and Marseille transport authorities are accelerating deployment of intelligent traffic management with embedded parking optimization.
United States
Commercial garage operators and airport authorities drive subscription displacement of perpetual licenses, demanding pricing tied to transaction volumes rather than fixed annual fees. FCC Part 15 compliance governs wireless sensor communications, while US DOT MUTCD alignment incentives create procurement preference for standards-compliant integrated platforms. California and New York metropolitan clusters lead technology upgrade cycles for congestion pricing zone deployments.
Spain
Large retail and airport operators in Madrid and Barcelona are converting capex-heavy parking investments to opex structures through subscription-based platform access. National procurement codes influence interoperability requirements for multi-site portfolio management. Barcelona's smart city infrastructure program channels investment toward cloud-native reservation platforms with centralized IT overhead reduction.
Netherlands
Municipal transport authorities in Amsterdam and Rotterdam are adopting camera-based computer vision with on-device license plate recognition at accelerated pace for congestion pricing zones. REACH and RoHS equipment standards reshape supplier qualification criteria for sensor network deployments. Dutch metropolitan hubs concentrate technology upgrade cycles that compress maintenance contract values for legacy sensor vendors.
Connected Parking Solutions Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform providers commanding premium contract values through bundled urban mobility offerings while hardware specialists compete on sensor fabrication scale. The vendor base stratifies across three tiers: multinational conglomerates with rail and traffic management heritage, mobile-first SaaS operators, and point-solution sensor fabricators. Consolidation pressure favors archetypes with software integration capabilities. Dominant competitive moves include municipal concession aggregation and edge-AI capability acquisition.
Among Germany-based integrated platform providers, Siemens Mobility GmbH and Kapsch TrafficCom exemplify the concession-anchored archetype, while EasyPark Group represents the mobile-first reservation platform specialist. Siemens Mobility GmbH occupies a position leveraging rail and traffic management heritage, Kapsch TrafficCom anchors long-term transport authority relationships, and EasyPark Group sits within the fastest-expanding segment as consumer expectations shift toward guaranteed space availability.
| Leading Market Players |
|---|
| ParkMobile, LLC |
| IPS Group, Inc. |
| Kapsch TrafficCom |
| Siemens Mobility GmbH |
| Robert Bosch GmbH |
| SKIDATA AG |
| Amano McGann, Inc. |
| EasyPark Group |
| NWAVE |
| Others |
Value Network & Pricing Analysis
Camera-based computer vision supplanting ultrasonic sensors in high-throughput urban deployments simultaneously redraws procurement geography toward East Asian module fabricators and compresses hardware margin pools while expanding software licensing premiums for integrated platform providers.
Pricing Analysis
After-sales maintenance contracts and recurring SaaS subscriptions drive lifetime value capture, with Parking Management Systems commanding three-tier pricing structures across premium bundled urban mobility offerings, standard modular deployments, and economy sensor-only configurations. Price differentiation rests on certification tier—F-Gas Regulation compliance for EU outdoor housings versus baseline FCC Part 15 configurations—and integration depth with legacy barrier infrastructure. Pricing pressure intensifies in hardware tiers as municipal procurement consolidation favors bundled platform contracts over discrete sensor purchases. Private operators in Spain and the UK exhibit lowest price sensitivity, accepting usage-based SaaS conversion, while secondary French municipalities remain most cost-conscious.
Supply Chain Analysis
Inbound logistics costs through East Asian shipping lanes and container availability constraints at major European ports shape total landed cost for camera module and ultrasonic sensor shipments. Component fabrication concentrates in China, South Korea, and Taiwan for CMOS image sensors and edge-AI chipsets, while Germany and the Netherlands anchor final system integration for EU-compliant deployments. Raw material dependencies span rare earth elements for sensor magnetics, semiconductor-grade silicon, and aluminum alloys for outdoor housings. Single-source vulnerability in CMOS sensor supply creates exposure to export restriction shocks. Distribution runs through municipal concession aggregators and direct sales channels to private garage operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation has shifted bargaining power toward city transport authorities, with bundled concession tenders favoring integrated platform providers over point-solution vendors and compressing margins for hardware specialists.
For Market Incumbents: Shield recurring revenue streams by deepening software integration capabilities and securing long-term concession renewals before edge-AI entrants displace legacy sensor maintenance contracts. Siemens Mobility GmbH and Kapsch TrafficCom demonstrate this through rail and traffic management heritage bundling. Prioritize backward integration into edge-AI chip design to reduce dependence on East Asian semiconductor supply. For New Entrants and Emerging Players: Lead with mobile-first reservation platforms targeting underpenetrated secondary French cities outside Paris, where municipal tenders favor operators reducing friction for private entrants. France's whitespace offers lowest competitive density among major European markets. Pursue usage-based SaaS pricing tied to transaction volumes rather than fixed licensing to align with Spanish and UK private operator preferences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mobile payment platform specialists lacking edge-AI capabilities or municipal concession relationships. Long-term viability over the projection horizon hinges on software integration depth and recurring revenue share. Monitor EU AI Act enforcement timelines for biometric handling compliance costs as an inflection signal for camera-based system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Capability Acquisition | On-device inference reduces cloud dependency and latency for real-time occupancy prediction in 5G-enabled deployments. |
| Municipal Concession Aggregation | Bundled urban mobility contracts in German metropolitan hubs capture multi-year recurring revenue pools exceeding hardware margins. |
| Mobile-First Platform Launch | Reservation platforms in French secondary cities address whitespace where consumer expectations shift toward guaranteed space availability. |
| Backward Integration into Sensor Design | In-house CMOS module development mitigates East Asian supply concentration and F-Gas Regulation compliance cost volatility. |
| SaaS Pricing Conversion | Usage-based models align with Spanish retail and airport operator demand for opex structures minimizing capex exposure. |
Research Methodology
Desk research of EU regulatory filings, municipal procurement databases, and smart city infrastructure grant disclosures preceded structured interviews with parking asset managers, transport authority procurement officers, IoT sensor engineering leads, and mobile payment platform executives. Secondary validation drew from KBA equipment standards documentation, FCC Part 15 compliance records, and concession tender archives. Bottom-up segment sizing triangulated against top-down smart city infrastructure spending flows.
Variance decomposition across product type, technology layer, end-user category, and deployment context shaped the analytical framework. Segmentation dimensions modeled include hardware-software integration depth, municipal versus private procurement pathway, and on-street versus off-street application context. CAGRs derived from installed base growth rates, replacement cycle timing, and pricing trajectory assumptions. Edge-AI adoption curves and 5G deployment timelines informed technology transition inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding levels, stable East Asian semiconductor supply, or unchanged GDPR biometric handling protocols would require recalibration. Forecasts reflect documented assumptions regarding municipal procurement consolidation pace and SaaS conversion rates among private operators. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Global Ridesharing Market