
 North America Car Wash Market | 2026-2036
North America Car Wash Market Size, Share, and Industry Trends Forecast 2026-2036
North America Car Wash Market Insights
Multi-site outsourcing from fragmented single-location operators is pivoting toward branded express tunnel networks. Mister Car Wash leverages its scale to dominate Sun Belt metropolitan expansion. Driven Brands Holdings Inc. anchors its position through diversified automotive service adjacencies. Quick Quack Car Wash Holdings LLC differentiates via aggressive subscription conversion and rapid buildout timelines.
North America car wash services encompass automated cleaning, finishing, and drying of passenger and commercial vehicles using conveyor tunnel, in-bay automatic, self-service bay, or hand-detailing configurations operating at pressures from 1,000 to 2,500 PSI with water reclamation thresholds often exceeding 80 percent reuse. Tunnel wash systems lead volume throughput while water recycling technology commands premium positioning amid municipal discharge restrictions. Subscription payment models now outpace pay-per-wash frequency in new site economics, with fleet operator contracts representing the fastest-expanding revenue pool.
EPA Clean Water Act discharge standards, state-level drought emergency ordinances in California and Texas, and local municipal water-use permitting shape equipment specifications and site operating economics across the region. NHTSA vehicle surface finish guidelines indirectly influence brush material and chemical formulation standards for commercial fleet contracts. Stakeholders must monitor evolving municipal water pricing structures and subscription fatigue thresholds as the sector shifts from unit-volume to recurring-revenue valuation models.
Market Dynamics
Subscription payment models are compressing customer acquisition costs while locking fleet operators into multi-year service agreements that reshape site-level economics across the Sun Belt.
Growth Catalysts
- Water recycling mandates:EPA Clean Water Act discharge standards and California drought emergency ordinances force equipment upgrades that differentiate compliant operators.
- Fleet outsourcing contracts:Logistics and rental companies consolidate vendor relationships, favoring tunnel networks with standardized service level agreements.
- Express tunnel buildout:Metropolitan corridors in Texas, Florida, and California concentrate new construction where land costs and vehicle density align.
Market Restraints
- Water input volatility:Municipal pricing structures in southwestern states impose unpredictable operating cost swings on high-volume sites.
- Site concentration risk:Premium real estate scarcity in dense metropolitan cores limits expansion velocity for branded networks.
- Brush material limitations:NHTSA surface finish guidelines constrain chemical formulation flexibility for commercial fleet contracts.
Strategic Opportunities
- Underpenetrated secondary metros:Mid-sized cities in Arizona, Nevada, and New Mexico lack express tunnel density relative to vehicle registrations.
- Technology convergence:License plate recognition systems integrate with subscription billing platforms to reduce friction at tunnel entry.
- Distribution innovation:Mobile detailing units attached to fleet contracts extend service reach beyond fixed-site infrastructure.
Industry Challenges
- Technician skill gaps:Water reclamation system maintenance requires specialized training that outpaces regional vocational pipeline output.
- Capex intensity:Tunnel equipment packages and land preparation demands exceed $3 million per greenfield site, constraining independent operator entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Car Wash Market |
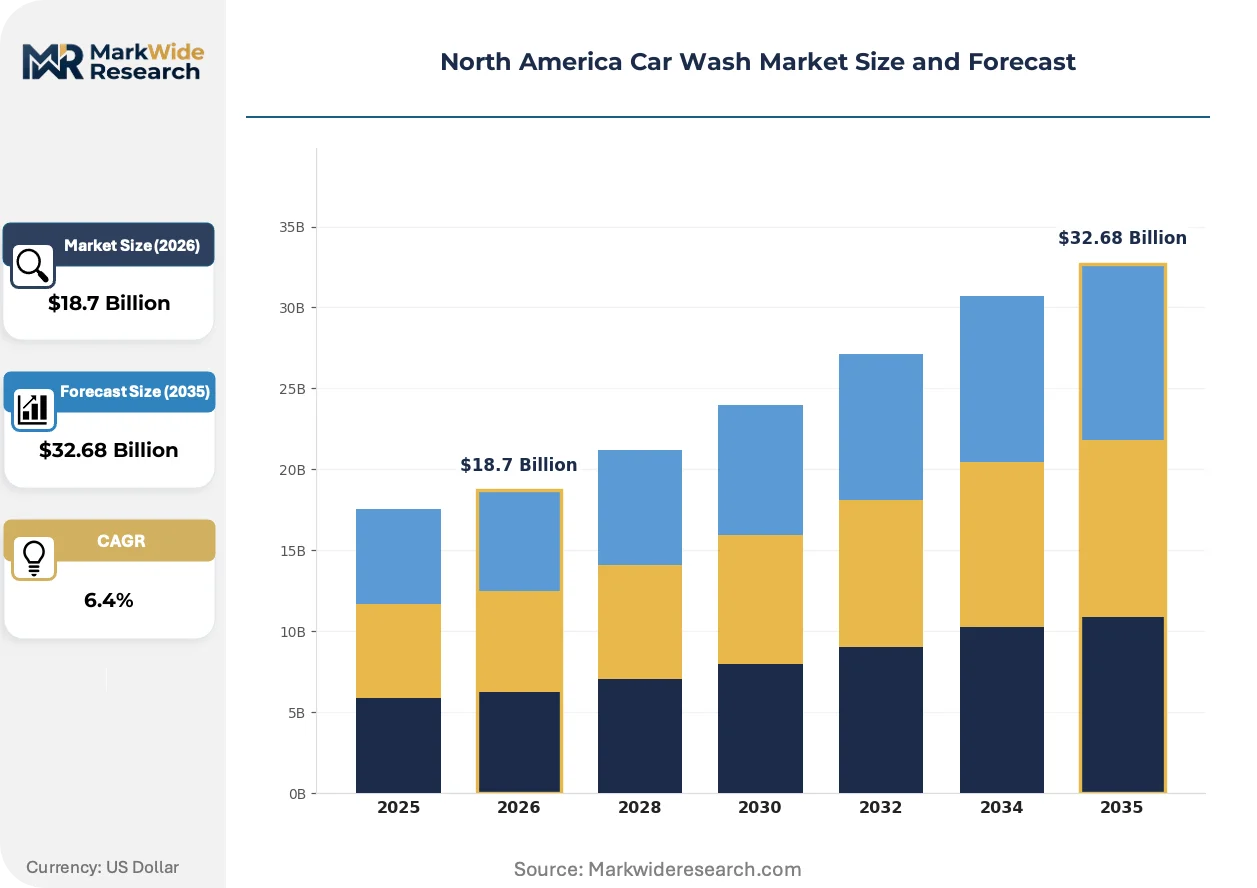
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Touchless, Hand Wash, Self-Service, Tunnel Wash End User: Individual Car Owners, Fleet Operators, Dealerships, Commercial Users Technology: Water Recycling, Biodegradable Products, High-Pressure Wash, Automated Systems Payment Model: Pay-Per-Wash, Subscription, Membership, Package Deals |
| Companies Covered | Mister Car Wash, Driven Brands Holdings Inc., Quick Quack Car Wash Holdings LLC, Zips Car Wash, Tommy's Express, Autobell Car Wash Inc., Splash Car Wash, Wash Depot Holdings Inc., GO Car Wash, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Car Wash Market Trends and Innovations
Water reclamation technology is advancing filtration precision while subscription billing platforms compress payment friction. Regulatory pressure on discharge quality intensifies equipment specification requirements. Fleet procurement centralization favors vendors with multi-site service consistency.
Closed-loop water treatment systems is expanding into express tunnel networks as municipalities tighten effluent standards. Large fleet operators in California and Texas mandate 85 percent reuse thresholds in vendor selection. This technology is expanding into mid-market metropolitan corridors previously served by basic in-bay automatics.
EPA discharge standards and state-level drought ordinances in California and Texas now require real-time monitoring of effluent quality. Equipment manufacturers must certify systems against evolving municipal permitting conditions. Tunnel operators in water-stressed counties face accelerated replacement cycles for legacy filtration infrastructure.
Fleet procurement departments now centralize vendor relationships across hundreds of locations rather than site-level contracting. This consolidation favors tunnel networks with standardized chemical protocols and unified billing platforms. The shift is most visible among rental car operators and last-mile delivery fleets operating across multiple southwestern states.
North America Car Wash Market Segmentation
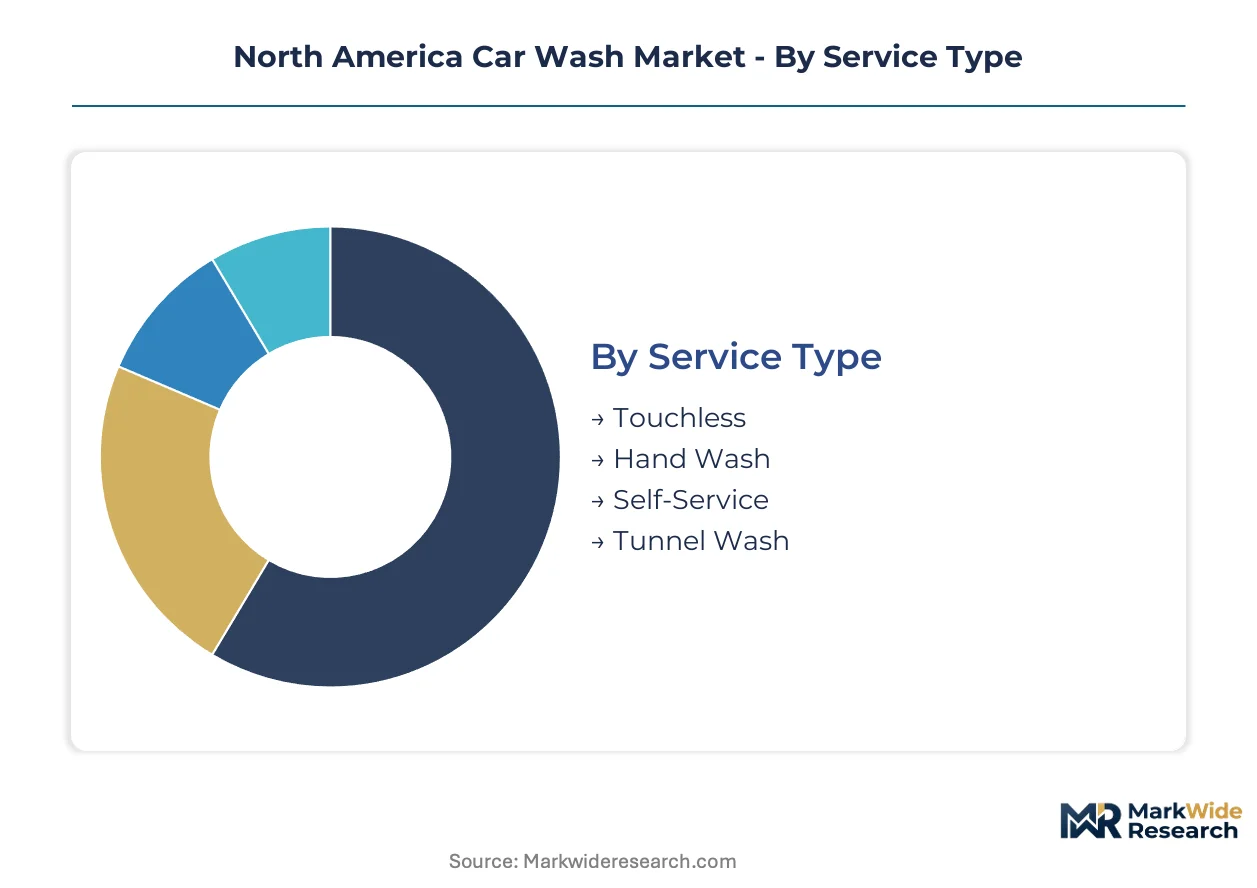
Car wash operators configure service portfolios around throughput economics, regulatory compliance thresholds, and customer retention mechanics. Segment boundaries blur where subscription platforms integrate multiple service types under unified billing.
Service Type:
Volume throughput and labor intensity separate profitable formats from marginal operations in metropolitan corridors.
- Tunnel Wash:Conveyor systems process 60 to 180 vehicles hourly using soft-cloth or touchless configurations at 1,200 to 2,500 PSI. Texas and Florida metropolitan buildouts concentrate here where land costs and vehicle density justify $3 million-plus equipment investments.
- Touchless:High-pressure water jets and chemical application eliminate physical contact, preserving delicate automotive finishes demanded by luxury vehicle owners and commercial fleets under NHTSA surface finish guidelines. California water recycling mandates accelerate adoption in drought-stressed counties.
- Hand Wash:Labor-intensive detailing commands premium pricing for ceramic coating preparation and paint correction, concentrated in affluent California and Florida suburbs where disposable income supports $50-plus per-visit spend.
- Self-Service:Coin-operated bays with wand sprayers serve price-sensitive customers and commercial vehicle operators with irregular schedules, persisting in rural Texas corridors and secondary Arizona metros where express tunnel penetration remains thin.
Tunnel Wash leads volumes today; Touchless is gaining share fastest.
End User:
Procurement centralization versus individual decision-making creates divergent margin profiles and contract structures.
- Fleet Operators:Logistics and rental companies consolidate vendor relationships across multi-state footprints, mandating standardized service level agreements and 85 percent water reuse thresholds. Subscription contracts spanning hundreds of locations reshape operator economics toward recurring revenue valuation.
- Individual Car Owners:Subscription conversion rates now exceed pay-per-wash frequency in Sun Belt metros, with monthly unlimited plans locking in predictable site-level cash flows.
- Commercial Users:Ride-share drivers and delivery contractors demand rapid throughput at price points between fleet contracts and retail retail, often queueing at express tunnels during off-peak hours.
- Dealerships:New and used vehicle preparation services require consistent finish quality for customer delivery standards, sourcing from tunnel networks with chemical protocol certification.
Individual Car Owners anchor current revenue; Fleet Operators are expanding most quickly.
Technology:
Regulatory pressure and operating cost reduction drive capital allocation toward closed-loop systems.
- Water Recycling:Closed-loop filtration systems achieve 80 to 90 percent reuse rates through reverse osmosis and membrane bioreactor stages. EPA Clean Water Act discharge standards and California drought emergency ordinances mandate real-time effluent monitoring, forcing replacement cycles for legacy infrastructure.
- Automated Systems:License plate recognition and tunnel entry automation reduce labor costs and subscription billing friction, integrating with mobile payment platforms at new Texas and Florida sites.
- High-Pressure Wash:2,000-plus PSI systems reduce chemical consumption while maintaining cleaning efficacy, favored in water-stressed southwestern metros where municipal pricing volatility compresses margin.
- Biodegradable Products:Plant-derived surfactants and wax formulations respond to municipal discharge restrictions and fleet sustainability procurement criteria, particularly in California where environmental scoring influences vendor selection.
Water Recycling dominates capital expenditure; Automated Systems are climbing the fastest.
Payment Model:
Revenue predictability and customer lifetime value separate subscription economics from transactional volatility.
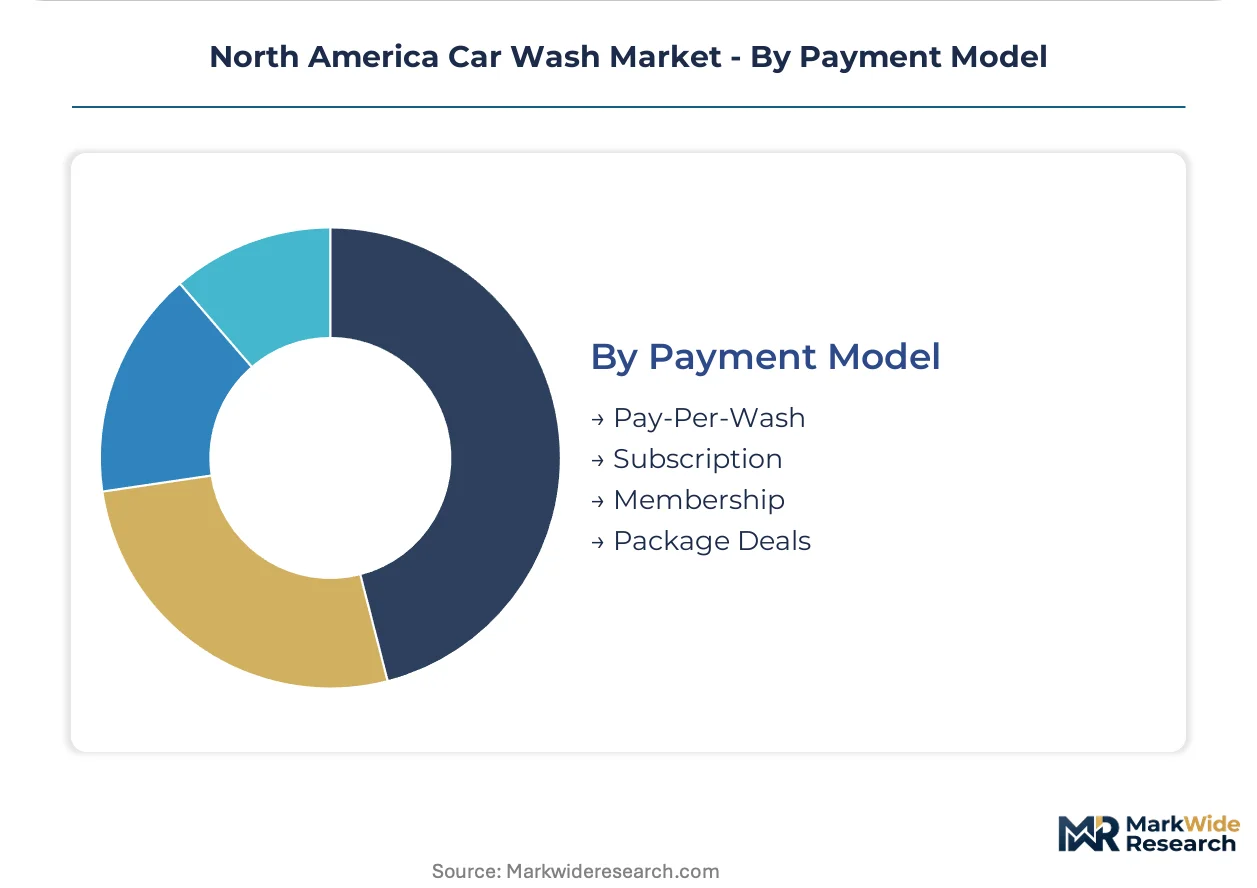
- Subscription:Monthly unlimited plans now outpace pay-per-wash frequency in new site pro formas, with Quick Quack and Mister Car Wash leveraging aggressive conversion rates to justify metropolitan real estate premiums.
- Pay-Per-Wash:Single-visit pricing persists at legacy in-bay automatics and self-service bays, concentrated in secondary Arizona and New Mexico markets where subscription penetration lags.
- Membership:Tiered plans with add-on detailing services capture high-value customers in California and Florida suburbs, bundling exterior washes with interior cleaning credits.
- Package Deals:Prepaid multi-visit books serve occasional users and gift purchasers, maintaining relevance at dealership-affiliated locations and airport rental return facilities.
Subscription leads new site economics; Package Deals retain niche utility in specific channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth Metroplex anchors North American tunnel wash deployment with over 200 express facilities serving fleet operators and retail subscribers across Texas and neighboring states.
United States
Texas, Florida, and California metropolitan corridors concentrate new express tunnel construction where vehicle density and subscription economics justify capital outlays. EPA Clean Water Act discharge standards and California drought emergency ordinances mandate 80-plus percent water reuse thresholds. Phoenix and Las Vegas lead southwestern technology upgrades as municipal water pricing volatility accelerates closed-loop filtration adoption.
Canada
Toronto and Vancouver metropolitan areas sustain tunnel wash growth through fleet contracts from logistics operators serving cross-border trade corridors. Environment Canada effluent guidelines and provincial water-use permits in Ontario and British Columbia shape equipment specifications. Calgary and Edmonton express tunnel networks expand as subscription models penetrate secondary prairie markets previously served by in-bay automatics.
Mexico
Monterrey and Mexico City industrial zones drive commercial fleet wash demand from manufacturing supply chain operators and rental car networks. SEMARNAT water discharge regulations and NOM environmental standards govern effluent quality for tunnel operators near metropolitan water systems. Guadalajara and Querétaro express tunnel construction accelerates as branded networks target middle-income vehicle ownership growth in central Mexico.
North America Car Wash Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue secondary metropolitan penetration through rapid buildout timelines and aggressive subscription conversion. The vendor base clusters around three strategic archetypes: scale-driven tunnel networks with multi-state footprints, regional operators consolidating fragmented single-site assets, and technology-forward specialists emphasizing water reclamation compliance. Competitive dynamics center on real estate acquisition velocity and fleet contract centralization rather than product differentiation.
Among Sun Belt-focused operators, Mister Car Wash, Quick Quack Car Wash Holdings LLC, and Driven Brands Holdings Inc. exemplify distinct strategic positions. Mister Car Wash represents the scale-driven archetype with metropolitan corridor density. Quick Quack Car Wash Holdings LLC occupies the rapid-expansion tier through subscription-first site economics. Driven Brands Holdings Inc. anchors the diversified automotive services model with car wash adjacencies. These three entities collectively illustrate how capital access, real estate velocity, and payment model innovation separate market tiers.
| Leading Market Players |
|---|
| Mister Car Wash |
| Driven Brands Holdings Inc. |
| Quick Quack Car Wash Holdings LLC |
| Zips Car Wash |
| Tommy's Express |
| Autobell Car Wash Inc. |
| Splash Car Wash |
| Wash Depot Holdings Inc. |
| GO Car Wash |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up tunnel networks now dominate the North American car wash landscape, concentrating equipment procurement power among fewer buyers while enforcing disciplined subscription pricing across metropolitan corridors. This ownership consolidation directly shapes both supply chain leverage and margin structures as operators negotiate volume discounts on filtration systems and tunnel components.
Pricing Analysis
Water input costs pass through to subscription tiers unevenly across southwestern states where municipal pricing volatility compresses margins. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coating bundles from basic exterior washes, with fleet contracts anchoring the lowest per-unit economics. Pricing pressure stems from California drought ordinances mandating 85 percent reuse thresholds that force capital upgrades. Individual car owners show highest price sensitivity, while fleet procurement departments prioritize service consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Ohio, and Illinois anchor equipment manufacturer networks serving tunnel operators across the Sun Belt. Tunnel wash systems draw from specialized fabricators in Germany, Italy, and domestic Midwest production hubs for conveyor components and high-pressure pumps. Supply chain risk centers on single-source vulnerability for membrane bioreactor filtration units subject to EPA discharge certification delays. Distribution runs through manufacturer-direct installation teams rather than third-party logistics, ensuring compliance documentation transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American car wash market reads as a late-cycle quality story where fleet procurement centralization and water recycling mandates favor operators with capital reserves to meet premium specifications.
For Market Incumbents: Acquire underperforming single-site assets in secondary Arizona and Nevada metros before branded competitors consolidate local market share. Consolidation of fragmented self-service bays in Albuquerque and Tucson corridors defends position against Quick Quack-style rapid buildout specialists. Vertical integration into water reclamation system maintenance crews addresses technician skill gaps that constrain expansion velocity. For New Entrants and Emerging Players: Mobile app-based subscription onboarding offers the lowest customer acquisition friction in mid-sized Texas cities where express tunnel density lags Dallas-Fort Worth saturation. White-space opportunity concentrates in fleet contract servicing for last-mile delivery operators across Oklahoma and Kansas where incumbent tunnel networks lack multi-state coverage. License plate recognition integration with existing payment platforms provides fastest path to operational parity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional operators with 5-15 site clusters lacking subscription billing infrastructure or water recycling compliance. Long-term viability hinges on recurring revenue conversion rates and fleet contract renewal terms rather than greenfield expansion velocity. Watch California municipal water pricing referendum outcomes as inflection signal for capital intensity requirements across southwestern markets.| Strategic Initiative | Industry Significance |
|---|---|
| Water Recycling Technology Deployment | EPA discharge standards and California drought mandates force 85 percent reuse thresholds, differentiating compliant operators. |
| Subscription Platform Integration | License plate recognition and mobile billing reduce friction for fleet operators centralizing vendor relationships across multi-state footprints. |
| Secondary Metro Expansion | Mid-sized Sun Belt cities lack express tunnel density relative to vehicle registrations, offering first-mover real estate advantages. |
| Fleet Contract Centralization | Logistics and rental companies consolidate procurement, favoring tunnel networks with standardized service level agreements. |
| Technician Training Pipeline Development | Water reclamation system maintenance requires specialized skills that outpace regional vocational output, constraining expansion. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with tunnel operators, fleet procurement managers, equipment manufacturer sales directors, and municipal water authority regulators. Secondary validation draws from EPA discharge filings, state-level drought emergency ordinances, SEC 10-K disclosures from publicly traded operators, and municipal water pricing databases. Bottom-up site-level economics triangulate against top-down market sizing across service type, end user, and technology segments.
Granularity-level modeling applies service type distinctions at the metropolitan corridor level, with subscription conversion rates and fleet contract penetration tracked separately for Texas, Florida, California, and secondary southwestern markets. Water recycling technology adoption curves and equipment replacement cycles inform capital expenditure projections across the analysis window. CAGRs derive from regression analysis of historical site-level throughput data against vehicle registration growth and subscription pricing trends.
The model assumes a particular technology adoption path; alternative pathways for closed-loop membrane bioreactor systems would alter the outlook if EPA certifies lower-cost filtration alternatives. Forecasts reflect documented assumptions regarding municipal water pricing trajectories and fleet outsourcing propensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Vehicle Analytics Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Car Rental Business Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
US Car Wash Services Market
Automotive Services
Automotive Register Market
Automotive Services
France Car Rental Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Tow Truck Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Americas MAP Market
Automotive Services
United States Automotive Service Market
Automotive Services
Luxury Car Rental Market