
 Parasailing Equipment Market | 2026-2036
Parasailing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Parasailing Equipment Market Analytics
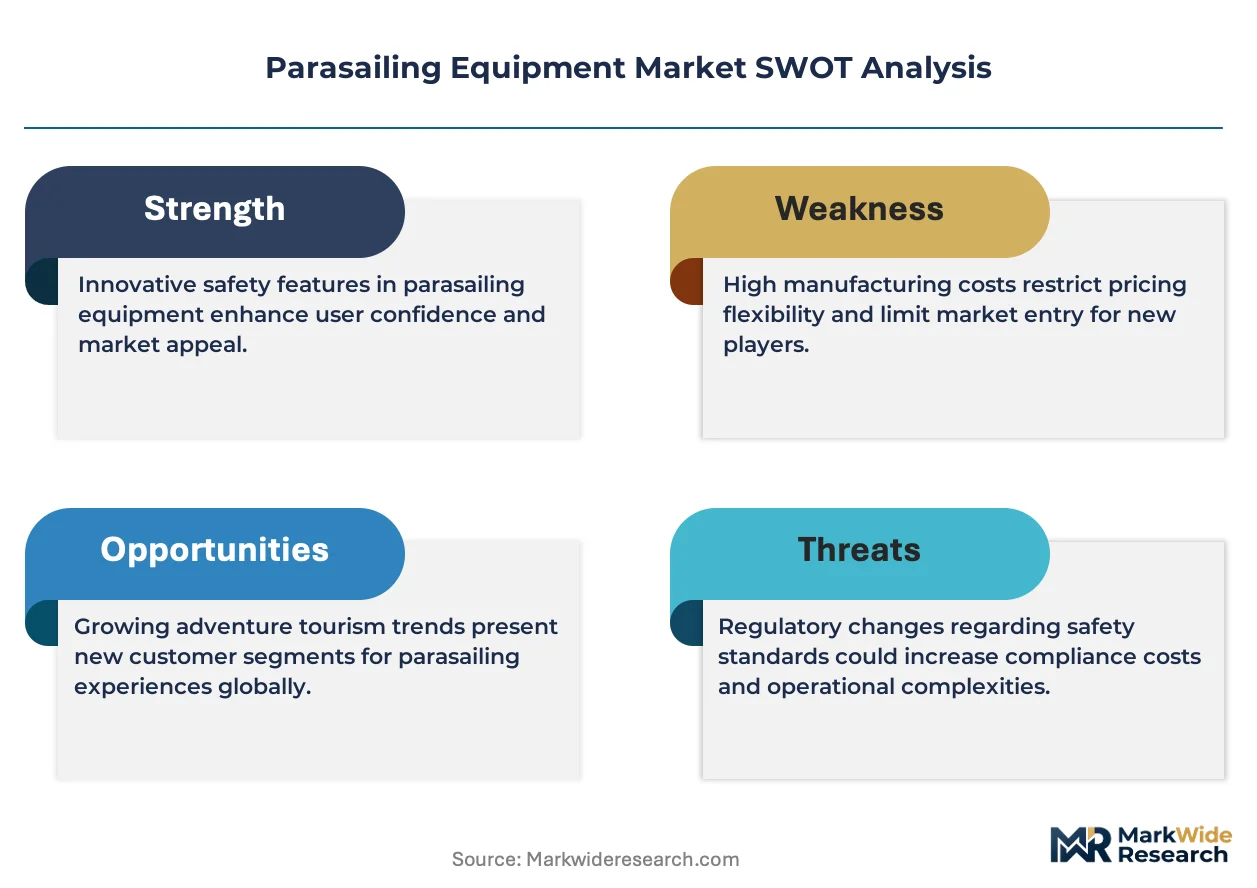
ASTM F1749-20 is bifurcating the competitive landscape into certified suppliers and uncertified regional vendors. Waterbird Parasails leverages its long-standing certification pedigree to anchor premium contracts with Caribbean resort operators. Qingdao Grandsea Boat Co., Ltd. sustains manufacturing scale across canopy and towline assemblies from its Shandong facility. Custom Chutes differentiates through specialized harness configurations for high-wind coastal environments.
Parasailing equipment encompasses the integrated canopy, harness, towline, and accessory systems designed to lift human riders aloft behind marine vessels, with canopies typically constructed from ripstop nylon rated at 30-70 square meters of surface area depending on rider capacity and wind conditions. The equipment serves commercial tour operators and adventure sports providers requiring reliable aerodynamic performance under variable marine wind loads. Canopy systems capture the dominant share of product value due to material complexity and replacement cycles driven by UV degradation and salt exposure. Towline assemblies represent the fastest-growing product category as operators upgrade from standard polyester to spectra-core lines rated for higher dynamic loads. The application split heavily favors commercial tourism over individual recreational purchase, concentrating margin pools with volume procurement contracts from integrated resort chains.
FAA oversight governs parasailing operations in U.S. airspace near airports, while ASTM International maintains the primary equipment safety standard referenced by insurance underwriters and coastal permitting authorities. The EU's CE marking framework and the General Product Safety Directive shape market access for European tour operators sourcing imported equipment. Stakeholders must monitor evolving liability insurance requirements tied to third-party certification status, as underwriters increasingly mandate documented inspection protocols beyond baseline manufacturer warranties.
Market Dynamics
ASTM F1749-20 compliance mandates are compressing the supplier base as uncertified regional vendors exit, while spectra-core towline adoption accelerates replacement cycles across commercial fleets.
Growth Catalysts
- ASTM F1749-20 Certification Mandates:U.S. coastal permitting authorities now require documented third-party inspection protocols, pushing rental operators toward certified equipment upgrades and expanding the addressable market for compliant suppliers.
- Marine Adventure Tourism Rebound:Government tourism boards in Thailand and the Dominican Republic are channeling infrastructure investment into water sports zones, directly stimulating fleet expansion by coastal operators.
- Spectra-Core Towline Technology:Commercial tour operators are replacing standard polyester lines with high-tensile spectra-core assemblies rated for elevated dynamic loads, opening premium replacement revenue streams.
Market Restraints
- Ripstop Nylon Input Volatility:UV-resistant canopy fabric costs fluctuate with petrochemical feedstock prices, squeezing margin pools for manufacturers without backward integration into textile supply.
- Shandong Manufacturing Concentration:Canopy and towline assembly production clusters heavily in eastern China's industrial corridor, creating geopolitical and logistics risk exposure for global procurement chains.
- Liability Insurance Escalation:Underwriters increasingly mandate documented inspection protocols beyond baseline warranties, raising operational compliance costs for smaller rental outfits.
Strategic Opportunities
- Vietnam Coastal Tourism Development:Phu Quoc and Da Nang are emerging as underpenetrated parasailing destinations where government-backed marina construction is creating first-mover equipment deployment opportunities.
- CE Marking Alignment:European tour operators sourcing under the General Product Safety Directive present a regulatory tailwind for suppliers achieving dual ASTM-CE certification, unlocking EU market access.
- Integrated Resort Chain Consolidation:Volume procurement contracts from Caribbean and Southeast Asian hospitality conglomerates are consolidating buyer power, favoring suppliers with certified scale and service networks.
Industry Challenges
- Certified Rigger Skill Scarcity:FAA oversight of U.S. airspace operations and ASTM inspection protocols require specialized rigging expertise that outpaces training pipeline output, creating operational bottlenecks.
- Harness Configuration Complexity:High-wind coastal environments demand specialized harness geometries that complicate inventory management and increase technical support burdens for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parasailing Equipment Market |
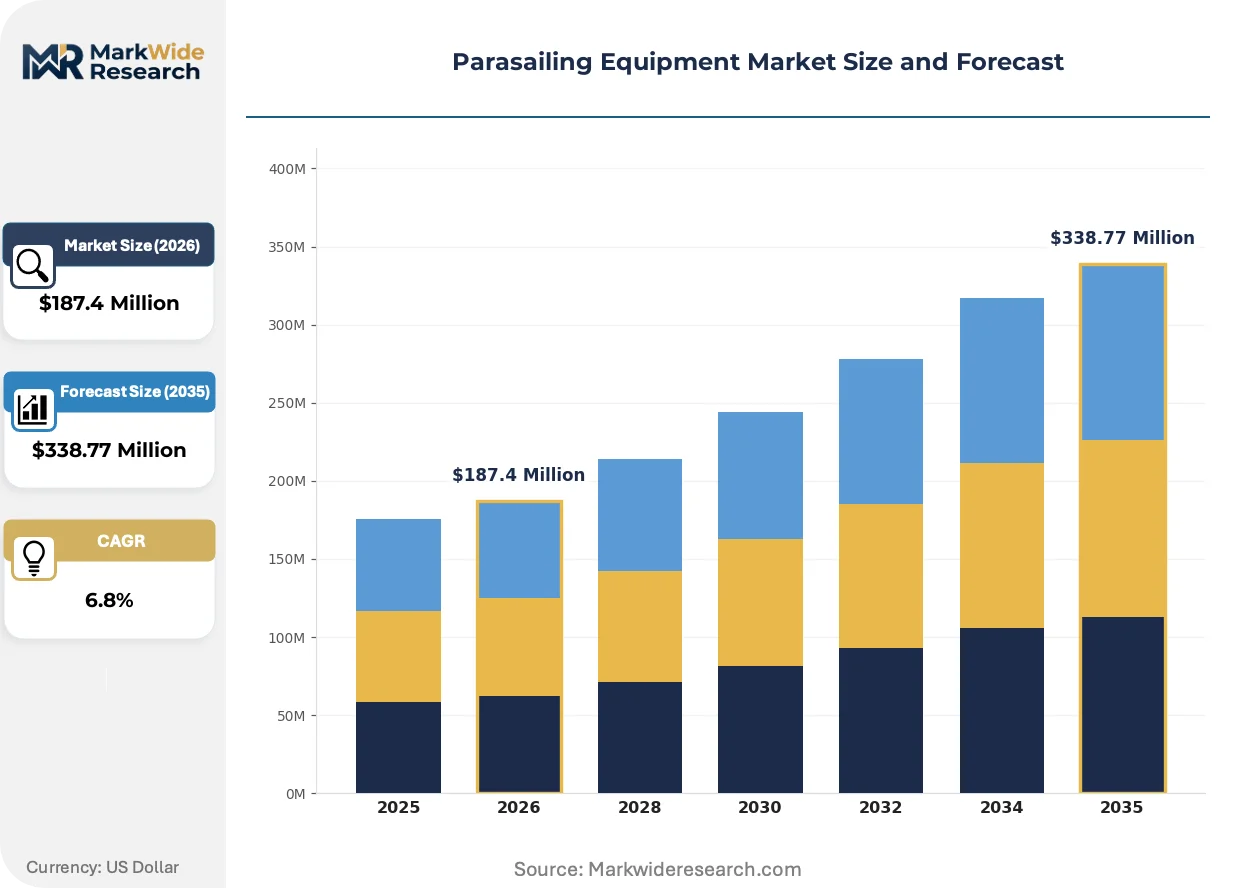
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canopy, Harness, Towline, Accessories Application: Recreational, Commercial, Adventure Sports, Tourism End User: Tour Operators, Individual Users, Water Sports Centers, Event Organizers Deployment: Onshore, Offshore, Coastal, Inland |
| Companies Covered | Waterbird Parasails, Paradise Mount, Custom Chutes, Hovel International Parasail, Ascending Parachutes International, Sport Chutes Over Texas, Sportlite, Qingdao Grandsea Boat Co., Ltd., Commercial Water Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parasailing Equipment Market Evolving Landscape
Equipment miniaturization and materials science advances are compressing replacement cycles while regulatory convergence reshapes competitive positioning across certification tiers.
Smart load-monitoring sensors embedded in towline assemblies are miniaturizing from bulky external modules to integrated fiber-optic strain gauges. Caribbean resort operators are piloting these systems for real-time tension telemetry. The technology is miniaturizing equipment form factors while enabling predictive maintenance contracts that displace traditional break-fix service models.
ASTM International is harmonizing inspection protocol language with the EU's CE marking framework under the General Product Safety Directive. European tour operators now face dual recognition pathways that reduce redundant certification costs. Coastal permitting authorities in Spain and Portugal are referencing this convergence to streamline equipment import approvals.
Buyer consolidation among integrated resort chains is compressing procurement decision cycles from seasonal to annual contracting. Volume procurement teams are displacing fragmented rental operator purchases across the Caribbean basin. This concentration is most visible in Dominican Republic and Mexican coastal zones where hospitality conglomerates centralize adventure sports equipment sourcing.
Parasailing Equipment Market Segmentation
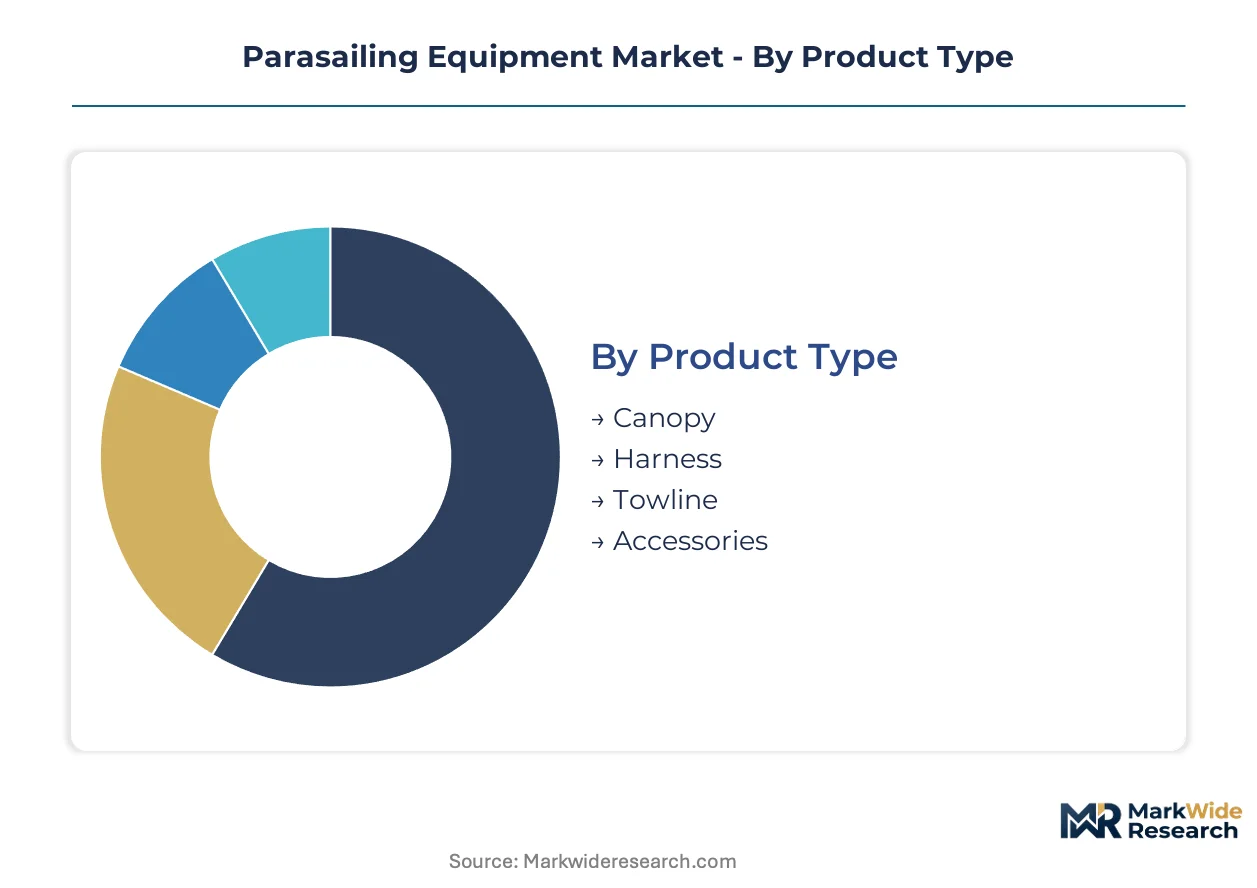
Parasailing equipment flows through distinct procurement channels shaped by certification requirements and fleet scale. Segment boundaries determine margin capture, replacement velocity, and supplier relationship intensity across marine tourism value chains.
Product Type:
Channel mix varies sharply by product complexity — canopies move through certified rigging specialists while accessories flow through general marine distributors.
- Canopy:Ripstop nylon assemblies rated at 30-70 square meters dominate product value due to UV degradation cycles and salt exposure replacement schedules. Caribbean resort operators concentrate procurement with ASTM F1749-20 certified suppliers to satisfy underwriter requirements.
- Towline:Spectra-core lines rated for elevated dynamic loads are displacing polyester assemblies across commercial fleets. Thai coastal operators drive replacement demand as government tourism boards expand water sports infrastructure quotas.
- Harness:Specialized geometries for high-wind environments complicate inventory management for regional distributors serving fragmented rental outfits.
- Accessories:Quick-release hardware and deployment bags flow through marine supply wholesalers without certification friction.
Canopy dominates installed base. Towline is where expansion concentrates.
Application:
Cost tier stratification separates premium commercial deployments from economy recreational purchases.
- Commercial:Integrated resort chains centralize volume procurement across Caribbean and Southeast Asian basins. Dominican Republic hospitality conglomerates negotiate annual contracting cycles that displace seasonal rental operator purchases.
- Tourism:Government-backed marina construction in Vietnam's Phu Quoc and Da Nang corridors creates first-mover equipment deployment opportunities for certified suppliers.
- Adventure Sports:High-wind coastal configurations demand technical support burdens that favor suppliers with regional service networks.
- Recreational:Individual purchase volumes remain marginal as liability insurance escalation prices smaller operators out of self-procurement.
Commercial commands procurement volume. Tourism is climbing the fastest.
End User:
Customer type determines contract structure — tour operators demand predictive maintenance agreements while individual users transact on spot replacement.
- Tour Operators:Volume buyers in Thailand and the Dominican Republic anchor fleet expansion as marine adventure activities rebound from pandemic contraction.
- Water Sports Centers:Specialized facilities require certified rigger expertise that outpaces training pipeline output, creating operational bottlenecks for ASTM inspection protocols.
- Event Organizers:Temporary deployment models favor rental channels over capital equipment purchase.
- Individual Users:Marginal segment constrained by liability insurance mandates and certified equipment cost barriers.
Tour Operators dominate procurement scale. Water Sports Centers face capability scarcity.
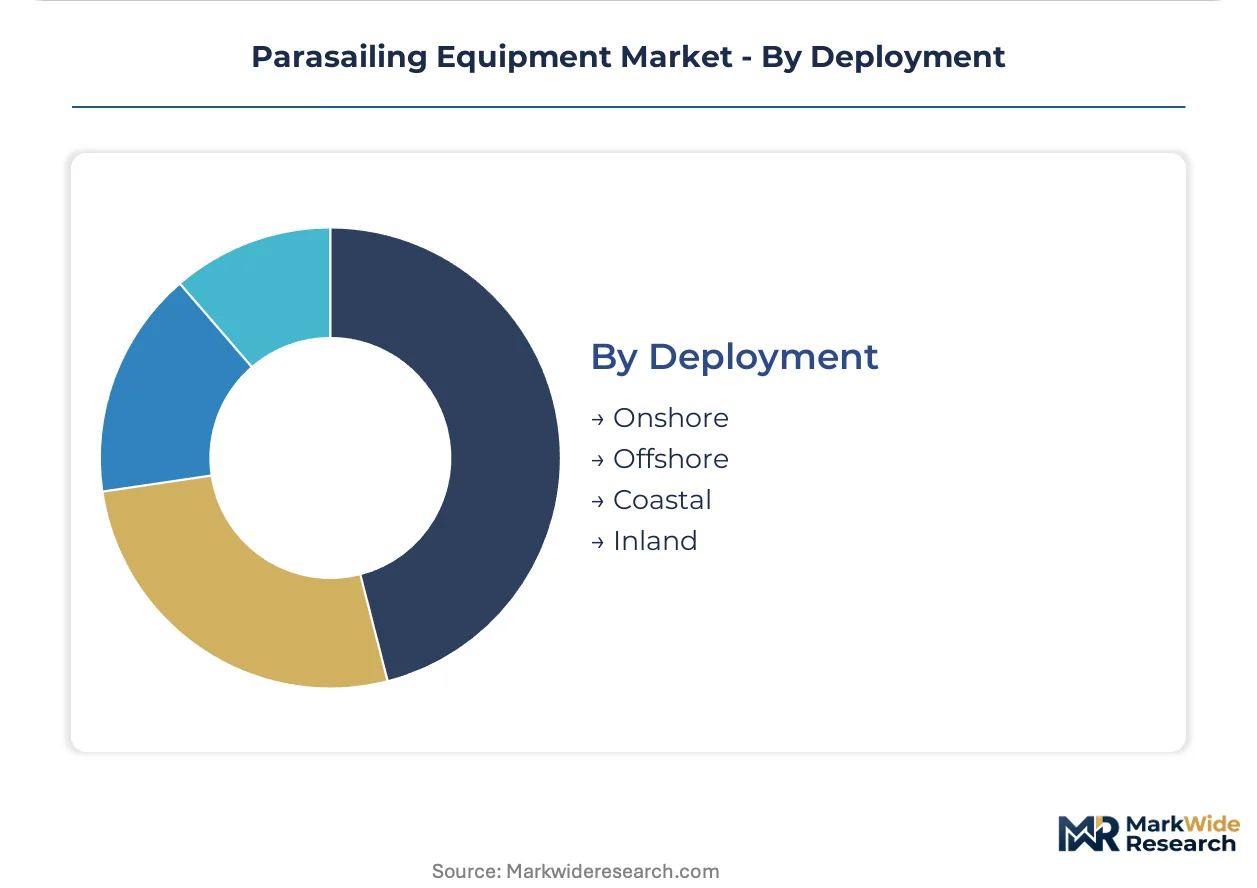
Deployment:
Geography dictates equipment specification — offshore environments demand higher load ratings than protected coastal zones.
- Coastal:Primary deployment mode across Southeast Asian island destinations where government tourism boards actively promote water sports infrastructure development.
- Offshore:Open-water operations require spectra-core towline ratings and specialized harness geometries that compress supplier margins through technical support burdens.
- Onshore:Beach-launched operations in Caribbean resort zones concentrate with integrated hospitality procurement teams.
- Inland:Lake-based operations remain marginal due to wind variability constraints and limited commercial operator density.
Coastal anchors deployment volume. Offshore is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated resort chains concentrate procurement volume in the Caribbean basin and Southeast Asian archipelagos, with commercial tour operators in Thailand and the Dominican Republic anchoring fleet expansion programs.
United States
Caribbean-facing coastal operators in Florida drive certified equipment demand as FAA oversight governs airspace near airports. ASTM F1749-20 compliance mandates push rental outfits toward documented third-party inspection protocols. Miami-Dade and Fort Lauderdale marine districts concentrate hospitality procurement teams centralizing adventure sports sourcing.
Dominican Republic
Punta Cana hospitality conglomerates negotiate annual volume contracts displacing seasonal rental purchases. Government tourism boards channel infrastructure investment into water sports zones along the eastern seaboard. Bavaro Beach resort clusters anchor fleet modernization programs for marine adventure activities.
Thailand
Phuket and Koh Samui coastal operators expand canopy and towline inventories as marine tourism rebounds from pandemic contraction. The country's national tourism authority promotes water sports infrastructure development through targeted zone designation. Chonburi Province manufacturing corridors supply regional distributors with ripstop nylon assemblies.
Vietnam
Phu Quoc and Da Nang emerge as underpenetrated destinations where government-backed marina construction creates first-mover deployment opportunities. Provincial tourism boards fast-track permitting for commercial parasailing operations in designated coastal zones. Da Nang's Han River port district clusters equipment import and rigging service providers.
China
Shandong Province manufacturing concentration supplies canopy and towline assemblies to export markets across Southeast Asia. GB standards and SAMR oversight shape domestic production quality frameworks for marine recreation equipment. Qingdao industrial corridors host fabricators serving international tour operator procurement chains.
Parasailing Equipment Market Competitive Landscape
Player mix skews toward certified specialists and regional fabricators serving distinct procurement tiers. ASTM F1749-20 compliance requirements bifurcate the supplier base into certified and uncertified segments, compressing the addressable vendor pool. Three archetypes dominate: long-standing certification pedigrees anchoring premium resort contracts, Shandong-based manufacturing scale players, and specialized harness configurators for high-wind environments. Competitive moves concentrate on dual certification alignment for EU market access and predictive maintenance service bundling displacing break-fix models.
Among certification-pedigreed specialists, Waterbird Parasails and Custom Chutes exemplify archetypes differentiated by compliance depth and technical specialization. Qingdao Grandsea Boat Co., Ltd. occupies a position representing Shandong manufacturing scale across canopy and towline assemblies. These three anchors illustrate how geographic origin and structural suffixes map to distinct competitive positioning within the bifurcated supplier landscape.
| Leading Market Players |
|---|
| Waterbird Parasails |
| Paradise Mount |
| Custom Chutes |
| Hovel International Parasail |
| Ascending Parachutes International |
| Sport Chutes Over Texas |
| Sportlite |
| Qingdao Grandsea Boat Co., Ltd. |
| Commercial Water Sports |
| Others |
Value Network & Pricing Analysis
Long-term volume procurement contracts from Caribbean and Southeast Asian resort chains lock in canopy and towline supply access while anchoring price visibility across replacement cycles. These arrangements insulate certified suppliers from spot-market volatility in ripstop nylon feedstocks while compressing margins for uncertified regional vendors excluded from hospitality procurement pipelines.
Pricing Analysis
Cost-plus contracts indexed to petrochemical feedstock benchmarks dominate canopy procurement between Shandong fabricators and integrated resort buyers. Price differentiation hinges on ASTM F1749-20 certification tier and after-sales service bundling, with certified suppliers capturing premium positioning. Pricing pressure stems from spectra-core towline commoditization as manufacturing scale expands in eastern China. Individual recreational buyers exhibit highest price sensitivity, while hospitality conglomerates prioritize reliability over unit cost.
Supply Chain Analysis
Inventory cycles for specialized harness configurations stretch lead times beyond standard canopy assemblies, complicating fleet expansion timing for Vietnamese coastal operators. Supply concentrates in China's Shandong Province, Thailand's Chonburi manufacturing corridors, and Vietnam's emerging Da Nang port clusters. The chain draws from ripstop nylon textile mills, spectra fiber extrusion facilities, and marine-grade hardware forgers. Single-source vulnerability in Shandong canopy assembly creates geopolitical risk exposure. Distribution runs through certified rigging specialists for canopies and general marine wholesalers for accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified rigger expertise gaps constrain fleet expansion timelines across Southeast Asian marine tourism zones, creating bottlenecks that favor suppliers with established training pipelines. This capability scarcity compresses operational readiness for new market entrants while rewarding incumbents with in-house technical service networks.
For Market Incumbents: Secure dual ASTM-CE certification alignment to capture European procurement flows under the General Product Safety Directive. Deepen backward integration into ripstop nylon textile supply to defend margin position against petrochemical feedstock volatility. Lock in multi-year service contracts with Caribbean hospitality conglomerates before competitive pressure intensifies in Vietnamese coastal zones. For New Entrants and Emerging Players: ASTM F1749-20 fast-track certification through third-party inspection partnerships offers the most viable entry path. Vietnam's Phu Quoc and Da Nang corridors present underpenetrated white-space where government-backed marina construction outpaces certified supplier presence. Target beach-launched coastal operations with predictive maintenance service bundles that displace break-fix incumbent relationships. For Investors and Strategic Acquirers: Capital is best deployed toward certified specialists with established Caribbean resort contracts and scalable Shandong manufacturing footprints. Long-term viability rests on regulatory convergence between ASTM and CE frameworks consolidating procurement preferences. Watch for spectra-core towline technology maturation as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Alignment | ASTM-CE convergence unlocks European procurement flows under General Product Safety Directive requirements. |
| Predictive Maintenance Service Bundling | Smart towline sensors enable telemetry contracts that displace break-fix models with Caribbean operators. |
| Backward Integration into Textile Supply | In-house ripstop nylon production defends margins against petrochemical feedstock volatility in canopy assemblies. |
| Certified Rigger Training Pipeline Investment | Technical service networks alleviate operational bottlenecks constraining Southeast Asian fleet expansion. |
| Vietnam Coastal Zone First-Mover Deployment | Government-backed marina construction in Phu Quoc and Da Nang creates equipment deployment precedents. |
Research Methodology
Operator-level perspectives from marine tour procurement directors, certified rigging specialists, hospitality conglomerate adventure sports managers, and Shandong manufacturing facility heads anchored the qualitative base. These primary insights combined with secondary validation from ASTM International technical committee records, FAA airspace operation filings, EU CE marking databases, and Southeast Asian tourism board infrastructure disclosures. Bottom-up equipment procurement flow analysis triangulated against top-down marine tourism expenditure estimates.
Sensitivity analysis around certification adoption timelines and spectra-core towline replacement velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity, application cost tier, end-user contract structure, and deployment geography load requirements. CAGRs derived from equipment replacement cycle analysis and tourism infrastructure investment trajectories. Industry-specific inputs incorporated UV degradation rates for canopy materials and marine wind load variability patterns.
Decision-makers should treat outputs as directional under assumptions of sustained ASTM F1749-20 compliance enforcement and Southeast Asian tourism board water sports promotion; material deviation in regulatory stringency or infrastructure funding would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
North America Climbing Gears Market