
 Hunting Rangefinder Market | 2026-2036
Hunting Rangefinder Market Size, Share, and Industry Trends Forecast 2026-2036
Hunting Rangefinder Market Analytics
Modular bundling of ballistic calculators with rangefinder hardware is shifting buyer choice toward integrated field solutions rather than standalone devices. Leupold & Stevens leverages its American manufacturing base to sustain premium positioning in long-range hunting optics. Bushnell competes aggressively through mass-market channel control across big-box outdoor retailers. Vortex Optics anchors its growth on unconditional warranty policies and direct-to-consumer engagement.
A hunting rangefinder is an electro-optical instrument that calculates distance to a target by emitting a laser pulse and measuring time-of-flight reflection, typically operating at 905 nanometer wavelength with effective ranges from 400 to 3,000 yards depending on target reflectivity. Its primary commercial purpose is to eliminate range-estimation error in ballistic trajectory calculation, thereby improving first-shot accuracy for hunters and precision shooters. Laser rangefinders dominate product type revenue due to superior accuracy and established hunter familiarity, while GPS rangefinders represent the fastest-growing category as topographic mapping integration expands utility beyond flat-terrain hunting. Amateur hunters constitute the largest end user segment by volume, though professional hunters command higher per-unit spending and earlier adoption of multi-sensor platforms.
The United States Food and Drug Administration regulates laser emission classifications for rangefinder devices, constraining power output and mandating eye-safety labeling that shapes product engineering trade-offs. The European Union REACH framework and RoHS directives restrict hazardous substance content in electronic components, affecting supply chain qualification for brands distributing across member states. Stakeholders must monitor evolving state-level hunting equipment regulations and battery transportation standards that could alter product design requirements and distribution logistics.
Market Dynamics
Bluetooth-enabled connectivity and ballistic calculation software are compressing the standalone rangefinder category as hunters demand integrated field solutions that eliminate manual data entry between devices.
Growth Catalysts
- Laser-based distance measurement:Professional hunters in North America are replacing optical estimation with 905 nanometer wavelength devices, driving hardware refresh cycles across flat-terrain and mountainous hunting grounds.
- REACH framework compliance:The European Union's hazardous substance restrictions are accelerating supply chain qualification programs that favor established manufacturers with pre-certified component libraries.
- Ballistic software integration:Modular bundling of trajectory calculators with rangefinder hardware is shifting buyer preference toward single-device solutions that reduce field equipment weight.
Market Restraints
- 905 nanometer wavelength power limits:FDA laser emission classifications constrain effective range extension, capping commercial devices below military-grade performance thresholds and compressing premium pricing headroom.
- Battery transportation standards:Evolving state-level regulations on lithium-cell shipping are fragmenting distribution logistics and raising compliance costs for direct-to-consumer channels.
- Optical estimation persistence:Amateur hunters in price-sensitive segments continue relying on reticle-based ranging, delaying category penetration in entry-level equipment tiers.
Strategic Opportunities
- GPS rangefinder convergence:Topographic mapping integration is expanding utility beyond flat-terrain hunting into backcountry navigation, opening adjacent demand from wilderness survival enthusiasts.
- Unconditional warranty policies:Direct-to-consumer engagement models that eliminate retailer markups are capturing margin previously allocated to big-box outdoor retail channels.
- Multi-sensor platforms:Professional hunters are adopting devices combining laser ranging with environmental sensors, creating upgrade pathways from single-function hardware.
Industry Challenges
- Eye-safety labeling compliance:FDA-mandated classification markings require engineering trade-offs between power output and product form factor, extending design validation timelines.
- RoHS directive adaptation:Restricted substance content in electronic components necessitates supplier audits and material substitutions that disrupt established procurement relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunting Rangefinder Market |
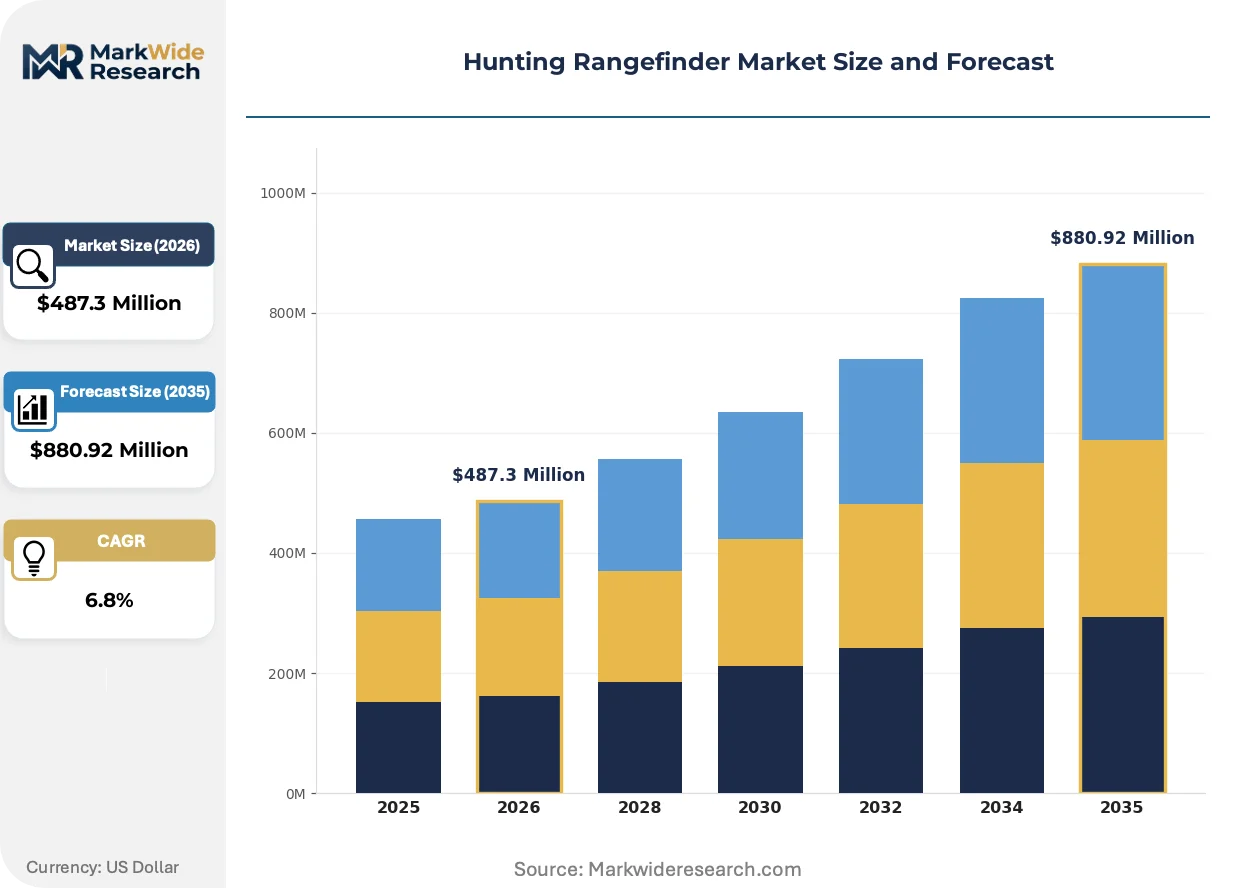
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Rangefinder, GPS Rangefinder, Smartphone App, Optical Rangefinder Technology: Infrared, Ultraviolet, Bluetooth, RFID End User: Amateur Hunters, Professional Hunters, Wildlife Researchers, Law Enforcement Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Leupold & Stevens, Bushnell, Vortex Optics, Nikon Corporation, Sig Sauer, Swarovski Optik, Leica, Trijicon, Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunting Rangefinder Market Evolving Landscape
Software-defined functionality is displacing fixed-feature hardware as the primary basis of product differentiation, with firmware updates extending device lifecycles and compressing replacement purchase frequency.
Laser rangefinder architecture is modularizing around swappable ballistic profiles and connectivity protocols. Professional hunters are adopting open-standard Bluetooth stacks that synchronize with third-party wind meters and ballistic apps. This modularization is compressing the addressable market for standalone environmental sensors by embedding their functions into core ranging hardware.
RoHS directives and REACH framework enforcement are reshaping component sourcing across the European Union. Manufacturers are qualifying lead-free solder alternatives and restricted-substance-free optical coatings to maintain market access. GPS rangefinder categories face heightened scrutiny due to embedded battery and circuit board complexity, slowing product registration timelines in member states with strict hazardous substance documentation requirements.
Direct-to-consumer engagement is displacing traditional outdoor retail distribution in premium equipment tiers. Unconditional warranty policies and online technical support are capturing buyer preference among precision shooters who prioritize post-purchase service over in-store handling. This channel shift is most visible in the United States, where hunting license frameworks support stable equipment investment cycles and e-commerce penetration in sporting goods exceeds other developed markets.
Hunting Rangefinder Market Segmentation
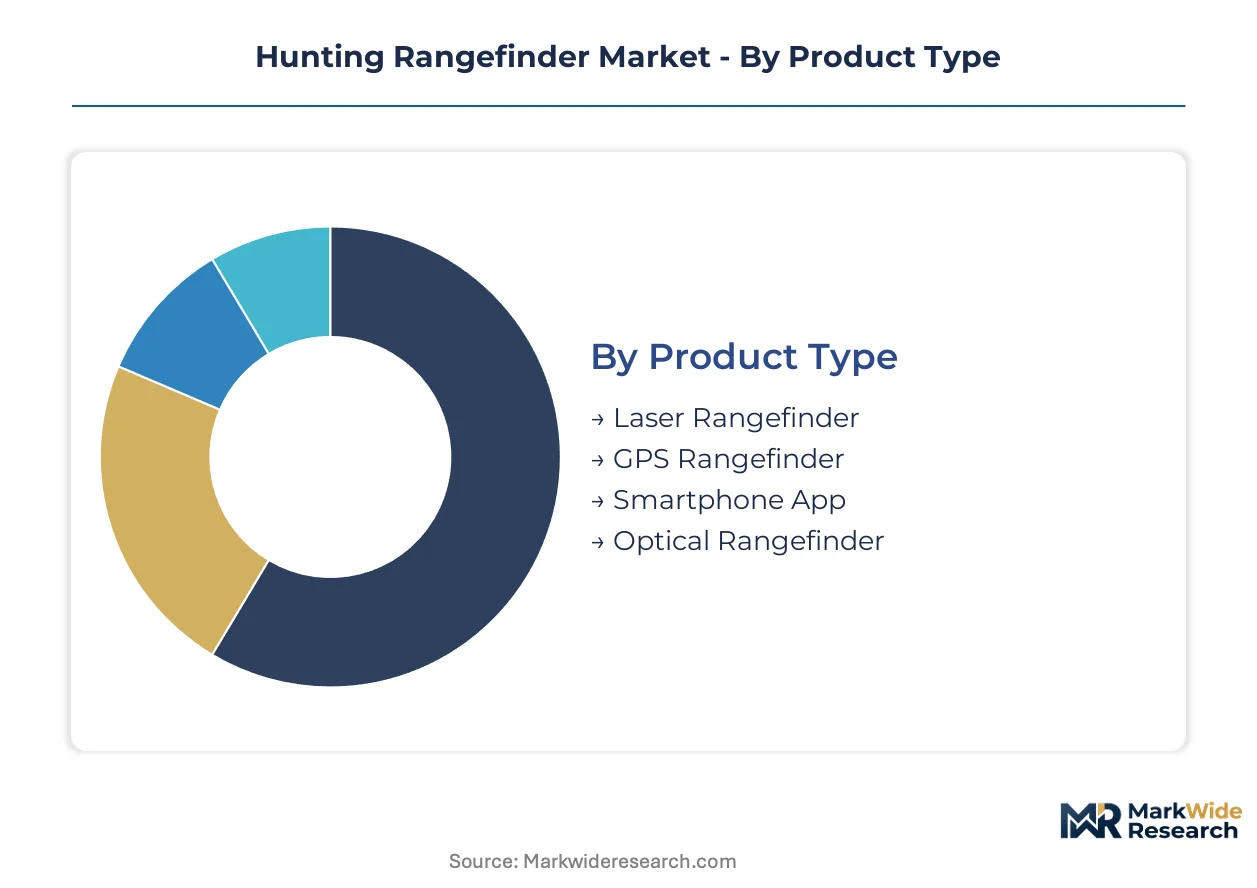
Segmentation in the hunting rangefinder market reveals how hardware specifications, connectivity protocols, and buyer sophistication create distinct commercial pockets. Manufacturers configure product portfolios across these axes to capture volume in amateur tiers while extracting premium from professional applications.
Product Type:
Laser emission architecture and positioning sensor integration define the core hardware differentiation axis.
- Laser Rangefinder:These devices emit 905 nanometer wavelength pulses and measure time-of-flight reflection to calculate distance with accuracy within one yard at 1,000 yards. Professional hunters in the United States drive replacement demand as ballistic software integration becomes standard. FDA laser emission classifications constrain power output and mandate eye-safety labeling that shapes engineering trade-offs between range extension and form factor.
- GPS Rangefinder:Embedded satellite receivers combine ranging with topographic mapping for backcountry navigation beyond flat-terrain hunting. Wilderness survival enthusiasts in Australia and Germany are expanding the addressable market through adjacent demand. REACH framework compliance requirements for hazardous substance documentation slow product registration timelines in European Union member states.
- Smartphone App:Camera-based distance estimation using device sensors and computational photography. Amateur hunters in price-sensitive tiers adopt these as entry-level alternatives before hardware upgrades.
- Optical Rangefinder:Reticle-based ranging through manual mil-dot or MOA calculations without electronic components. Traditionalists and budget-constrained buyers sustain residual demand despite accuracy limitations.
Mature deployment sits with laser rangefinders. Newer deployment is concentrated in GPS rangefinders.
Technology:
Signal processing protocols determine connectivity scope and environmental adaptability.
- Infrared:Near-infrared emitters at 905 nanometers dominate laser-based distance measurement for their balance of atmospheric penetration and eye safety. Professional hunters across North American flat-terrain and mountainous grounds favor infrared for consistent performance in varying light conditions.
- Bluetooth:Open-standard wireless stacks synchronize rangefinders with third-party wind meters and ballistic calculation apps. This protocol is expanding most quickly as modular bundling eliminates manual data entry between devices.
- Ultraviolet:Shorter wavelength emission for specialized applications requiring reduced atmospheric scatter. Niche demand concentrates in law enforcement and military-adjacent civilian markets.
- RFID:Proximity-based identification for asset tracking and inventory management in commercial hunting operations. Limited consumer adoption due to range constraints versus laser alternatives.
Volume concentration favors infrared. Margin extraction concentrates in Bluetooth-enabled configurations.
End User:
Skill level and equipment investment cycles separate recreational from commercial buyers.
- Amateur Hunters:Recreational participants seeking entry-level accuracy without premium pricing. This segment commands largest volume through big-box outdoor retail channels in the United States.
- Professional Hunters:Commercial operators and competitive precision shooters requiring sub-yard accuracy and multi-sensor integration. Higher per-unit spending and earlier adoption of environmental sensor platforms characterize this tier.
- Wildlife Researchers:Academic and conservation scientists using non-invasive distance measurement for population monitoring. Specialized calibration requirements create vendor stickiness.
- Law Enforcement:Tactical teams requiring MIL-SPEC durability and extended range performance. Procurement runs through government contracting vehicles with extended validation timelines.
Replacement frequency peaks with professional hunters. First-time buyer concentration sits with amateurs.
Distribution Channel:
Channel selection reflects buyer service expectations and price sensitivity trade-offs.
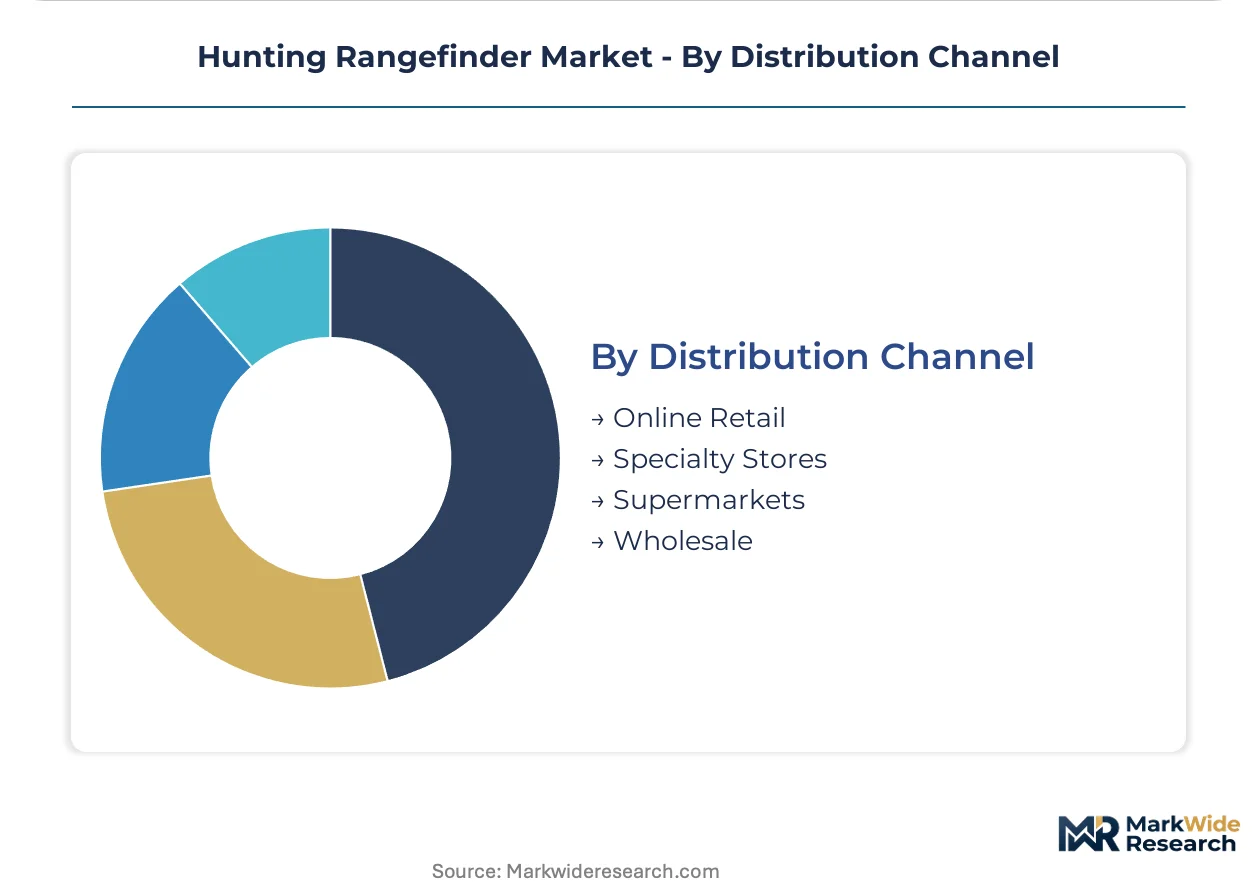
- Online Retail:Direct-to-consumer platforms capture margin through unconditional warranty policies and technical support. E-commerce penetration in United States sporting goods exceeds other developed markets.
- Specialty Stores:Independent outdoor retailers provide hands-on handling and staff expertise for premium equipment tiers. Germany and Australia maintain robust specialty networks.
- Supermarkets:Mass-market big-box retailers drive volume for entry-level laser rangefinders. Channel control competition concentrates among Bushnell and similar brands.
- Wholesale:Distributor networks serve international markets with localized compliance adaptation. Battery transportation standards fragment logistics for lithium-cell devices.
Service-intensive sales concentrate in specialty stores. Price-driven procurement dominates supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of hunting rangefinders concentrates in precision optics clusters across Germany, Japan, and the United States, while consumption patterns diverge between established hunting license frameworks and emerging outdoor recreation markets.
United States
Professional hunters and competitive precision shooters drive hardware refresh cycles as ballistic software integration becomes standard equipment. FDA laser emission classifications constrain power output and mandate eye-safety labeling that shapes engineering trade-offs. Wisconsin and Oregon host established optics manufacturing corridors where domestic assembly supports premium positioning.
Germany
REACH framework compliance and RoHS directives accelerate supply chain qualification programs favoring manufacturers with pre-certified component libraries. Bavaria and Baden-Württemberg anchor precision glass and electro-optics production for European distribution. German hunters exhibit strong preference for multi-sensor platforms combining laser ranging with environmental measurement.
Australia
Wilderness survival enthusiasts expand addressable demand beyond traditional hunting applications into backcountry navigation. TGA regulations govern medical device classifications for laser-emitting equipment with overlapping technical standards. Queensland and New South Wales concentrate specialty outdoor retail networks serving both recreational and professional segments.
Japan
METI industrial standards and JIS certification requirements shape product specifications for domestic and export markets. Kansai region optics manufacturers supply high-precision laser components to global rangefinder assemblers. Japanese consumers demonstrate early adoption of GPS-integrated rangefinders for mountainous terrain hunting.
Canada
Stable provincial hunting license frameworks in Alberta and British Columbia sustain equipment investment cycles comparable to United States patterns. Health Canada regulates laser product safety classifications parallel to FDA frameworks. Ontario and Quebec distribute both mass-market and premium-tier products through integrated outdoor retail and direct-to-consumer channels.
Hunting Rangefinder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three concentration levels: premium optical houses with century-long hunting heritage, mid-market brands leveraging warranty policies and channel control, and mass-market players competing on retail footprint. Strategic archetypes include vertically integrated precision manufacturers, direct-to-consumer disrupters, and big-box channel dominators. Competitive moves center on unconditional warranty differentiation and modular ballistic software bundling.
Within the premium heritage tier, Leupold & Stevens and Swarovski Optik exemplify American and Austrian precision manufacturing traditions. Bushnell occupies a position as the mass-market channel anchor. Vortex Optics represents the direct-to-consumer warranty-driven disrupter archetype.
| Leading Market Players |
|---|
| Leupold & Stevens |
| Bushnell |
| Vortex Optics |
| Nikon Corporation |
| Sig Sauer |
| Swarovski Optik |
| Leica |
| Trijicon |
| Zeiss |
| Others |
Value Network & Pricing Analysis
Professional hunter demand for FDA-compliant 905 nanometer wavelength devices with embedded ballistic software is forcing suppliers to qualify lead-free solder alternatives and restricted-substance-free optical coatings, compressing margins across component tiers while concentrating pricing power with pre-certified precision optics houses in Germany, Japan, and the United States.
Pricing Analysis
Margin tightening in the mass-market tier reflects channel control competition between big-box outdoor retailers and direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels separates Leupold's American manufacturing positioning from Bushnell's retail footprint dominance and Vortex's warranty-driven online engagement. Price differentiation hinges on after-sales service bundling and ballistic software integration depth. Amateur hunters exhibit highest price sensitivity, while professional hunters prioritize sub-yard accuracy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese Kansai region suppliers of high-precision laser emitters and German Bavarian clusters for electro-optics assembly. Component sourcing draws from Taiwan for circuit boards, China for lithium cells, and domestic United States facilities for final integration. Tariff exposure on optical glass and semiconductor content threatens cost structures. Distribution runs through wholesale networks for international markets with localized REACH and RoHS compliance adaptation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over precision laser emitter supply and ballistic software development determines margin capture across professional and amateur tiers.
For Market Incumbents: Anchor defensive positioning through captive supply of 905 nanometer wavelength components and pre-emptive FDA eye-safety certification investments. Threat substitution from smartphone camera-based estimation apps demands faster firmware update cycles. Backward integration into precision glass sourcing insulates against German and Japanese supplier concentration. For New Entrants and Emerging Players: Direct-to-consumer warranty specialists represent the most penetrable channel gap, particularly among precision shooters dissatisfied with big-box retail service. White-space concentrates in GPS rangefinder categories for Australian wilderness navigation and German multi-sensor platform demand. Go-to-market should leverage unconditional replacement policies and online technical support to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier brands possessing pre-certified REACH component libraries given accelerating European Union enforcement timelines. Long-term viability favors targets with software-defined functionality architectures extending device lifecycles through firmware rather than hardware refresh. Signal to monitor: FDA laser emission classification revisions that would obsolete non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Ballistic Software Integration | Embedded trajectory calculators eliminate manual data entry between rangefinders and wind meters. |
| REACH Compliance Certification | Pre-certified lead-free solder libraries accelerate European Union market access timelines. |
| Direct-to-Consumer Channel Expansion | Unconditional warranty policies capture margin previously allocated to outdoor retail markups. |
| Multi-Sensor Platform Development | Environmental sensor fusion creates upgrade pathways from single-function laser hardware. |
| Precision Optics Manufacturing Footprint | Domestic assembly in Wisconsin and Oregon supports premium positioning against import competition. |
Research Methodology
Independent corroboration across rangefinder product managers, precision optics procurement leads, ballistic software engineers, and big-box outdoor retail buyers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA laser product classification databases, European Chemicals Agency REACH registration records, United States hunting license issuance statistics, and customs trade data on electro-optical instrument imports. Bottom-up demand modeling and top-down supply capacity assessments were cross-referenced for triangulation.
Historical reference periods spanning pre-pandemic through post-supply-disruption intervals anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type architecture, connectivity protocol adoption, end-user skill tier, and distribution channel penetration. CAGRs were derived from installed base replacement cycles and first-time buyer conversion rates in amateur segments, with inputs from lithium-cell shipping regulation evolution and state-level hunting equipment law changes.
Caveats apply where FDA laser emission reclassification, REACH substance restriction expansion, or lithium battery transportation standard fragmentation could materially shift the outlook. Forecasts reflect documented assumptions regarding professional hunter equipment refresh frequency and amateur price sensitivity thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Spain Sports Tourism Market