
 Global Water Bikes Market | 2026-2036
Global Water Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Bikes Market Outlook
Asian composite manufacturers is realigning supply chains toward marine-grade carbon fiber output for water bike hull production. Manta5 leverages its hydrofoil engineering heritage to sustain premium positioning in pedal-assisted segments. Schiller Bikes anchors North American distribution through specialty retailers with exclusive territory arrangements. Yamaha Motor Corporation, USA competes in electric water bikes by extending its marine propulsion intellectual property into leisure applications.
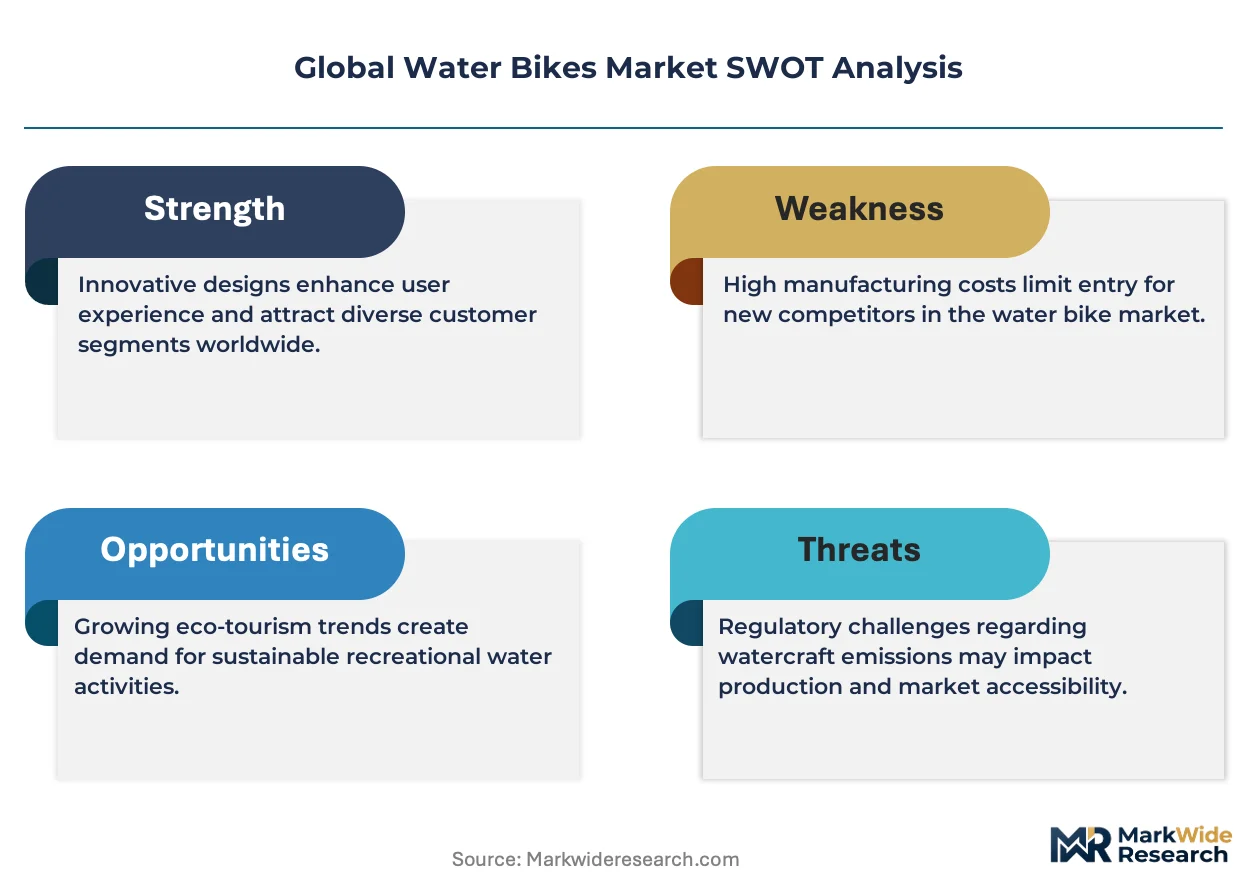
Water bikes are human-powered or motor-assisted watercraft utilizing pedal-driven propellers or hydrofoil lift systems, typically constructed from marine aluminum or carbon fiber composites with sealed bearing assemblies rated for saltwater immersion; their primary function is to provide stable, low-impact aquatic mobility for recreation, fitness, and guided tourism. Pedal water bikes occupy the largest installed base due to lower unit costs and minimal maintenance requirements, while electric water bikes capture expanding margin pools as lithium-ion energy density improves and harbor municipalities restrict combustion engines. Carbon fiber hulls command premium positioning among water sports enthusiasts, whereas aluminum variants dominate rental services where operators prioritize dent resistance and field repairability.
The US Coast Guard and EPA jointly influence water bike classification and environmental compliance, with the former governing personal flotation and navigation lighting standards and the latter restricting anti-fouling coatings under the Clean Water Act. The EU's F-Gas Regulation and REACH framework constrain refrigerant choices in electric water bike battery thermal management systems and mandate substance disclosure for composite resins. Japan's METI maritime leisure standards and JIS corrosion testing protocols shape export eligibility for hull manufacturers targeting East Asian resort markets. Stakeholders must monitor evolving harbor access permits and emission zone expansions as coastal cities rewrite waterfront commercial activity rules.
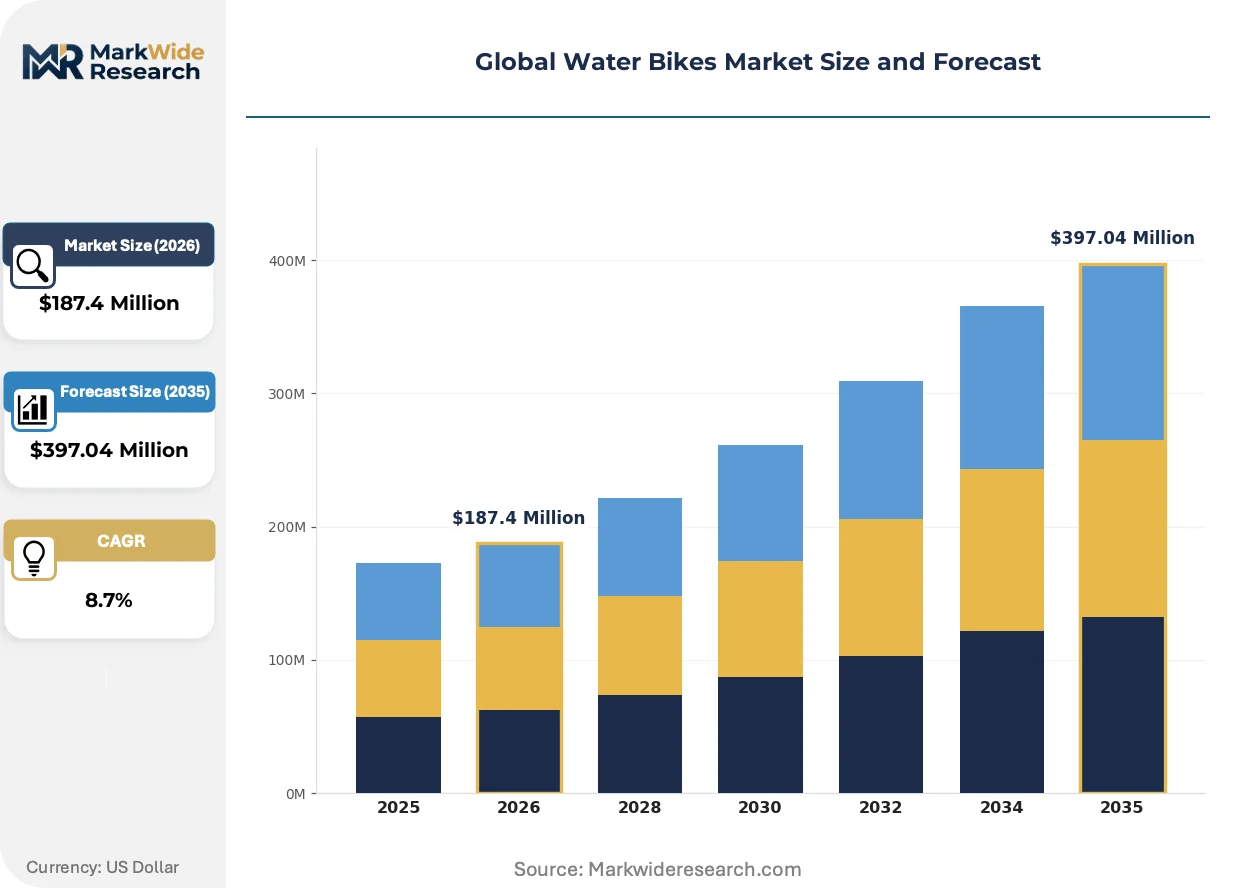
Market Dynamics
Harbor municipalities across coastal Australia, Spain, and Greece are rewriting waterfront commercial permits to exclude combustion-engine rentals, forcing fleet operators toward pedal and electric alternatives with immediate procurement timelines.
Growth Catalysts
- EU Green Deal zero-emission mandates:Coastal cities in Italy and France now require carbon-neutral water recreation equipment for new harbor concessions, eliminating permit renewals for gasoline-powered alternatives.
- Marine-grade carbon fiber supply expansion:Asian composite manufacturers are redirecting aerospace capacity toward hull production, reducing lead times for lightweight water bike frames by half.
- Tourism infrastructure investment:Australian state governments are funding aquatic mobility hubs in Sydney, Melbourne, and Brisbane harbor districts with dedicated water bike docking stations.
Market Restraints
- Lithium-ion battery thermal management costs:The EU's F-Gas Regulation restricts refrigerant choices in electric water bike battery cooling systems, adding engineering complexity and unit cost.
- Carbon fiber supply concentration:Three Asian manufacturers control marine-grade prepreg output, creating vulnerability for hull producers dependent on specific resin formulations.
- Seasonal revenue compression:Mediterranean and Australian operators face six-month utilization gaps, forcing asset-heavy business models to absorb idle capacity costs.
Strategic Opportunities
- Japanese resort market penetration:METI maritime leisure standards and JIS corrosion testing protocols create export eligibility barriers that compliant manufacturers can leverage for premium positioning in East Asian resort clusters.
- Fitness application expansion:Health clubs and hotel wellness programs are piloting water bike installations as low-impact aquatic exercise alternatives to pool-based equipment.
- Direct-to-operator distribution:Manufacturers are bypassing marine retail intermediaries to sell fleet packages directly to harbor concession holders with maintenance bundling.
Industry Challenges
- Marine corrosion engineering talent scarcity:Saltwater-rated sealed bearing design and galvanic isolation expertise concentrates among a small pool of naval architects with recreational watercraft experience.
- Multi-jurisdiction certification timelines:Obtaining US Coast Guard flotation compliance, EPA anti-fouling coating approvals, and EU CE marking simultaneously extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Bikes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal Water Bikes, Electric Water Bikes, Hybrid Water Bikes, Inflatable Water Bikes End User: Recreation Centers, Water Sports Enthusiasts, Tour Operators, Private Consumers Material: Aluminum, Fiberglass, Plastic, Carbon Fiber Distribution Channel: Online Stores, Specialty Retailers, Direct Sales, Rental Services |
| Companies Covered | Hydrobikes Inc., Manta5, Schiller Bikes, Redsharkbikes, SBK Engineering, Yamaha Motor Corporation, USA, Aurea Bike, Waterbike Italia S.R.L, Pioner Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Bikes Market Strategic Shifts
Water bike architecture is fragmenting into interchangeable subsystems as operators demand field-replaceable components and manufacturers seek production flexibility across hull materials and propulsion types.
Hydrofoil lift systems are modularizing water bike design by separating hull buoyancy from propulsion efficiency. Harbor rental fleets in Barcelona and Marseille are adopting foil-retrofit kits to reduce drag and extend pedal range for tourist circuits. This modularity is compressing R&D cycles as manufacturers test foil geometries without redesigning entire hull molds.
The EU's REACH framework now mandates substance disclosure for composite resins used in hull lamination, forcing manufacturers to reformulate epoxy systems or document supply chain chemistry. Electric water bike producers face additional F-Gas Regulation constraints on battery thermal management refrigerants. Producers targeting German and Dutch markets are prioritizing bio-based resin alternatives to preempt regulatory rejection.
Harbor concession procurement is consolidating around multi-year fleet service contracts rather than unit sales. Australian operators in Sydney and Perth now specify uptime guarantees and predictive maintenance inclusion, displacing traditional marine retail purchase models. This shift is most visible in Mediterranean markets where municipal tender documents explicitly exclude pure equipment vendors without service infrastructure.
Global Water Bikes Market Segmentation
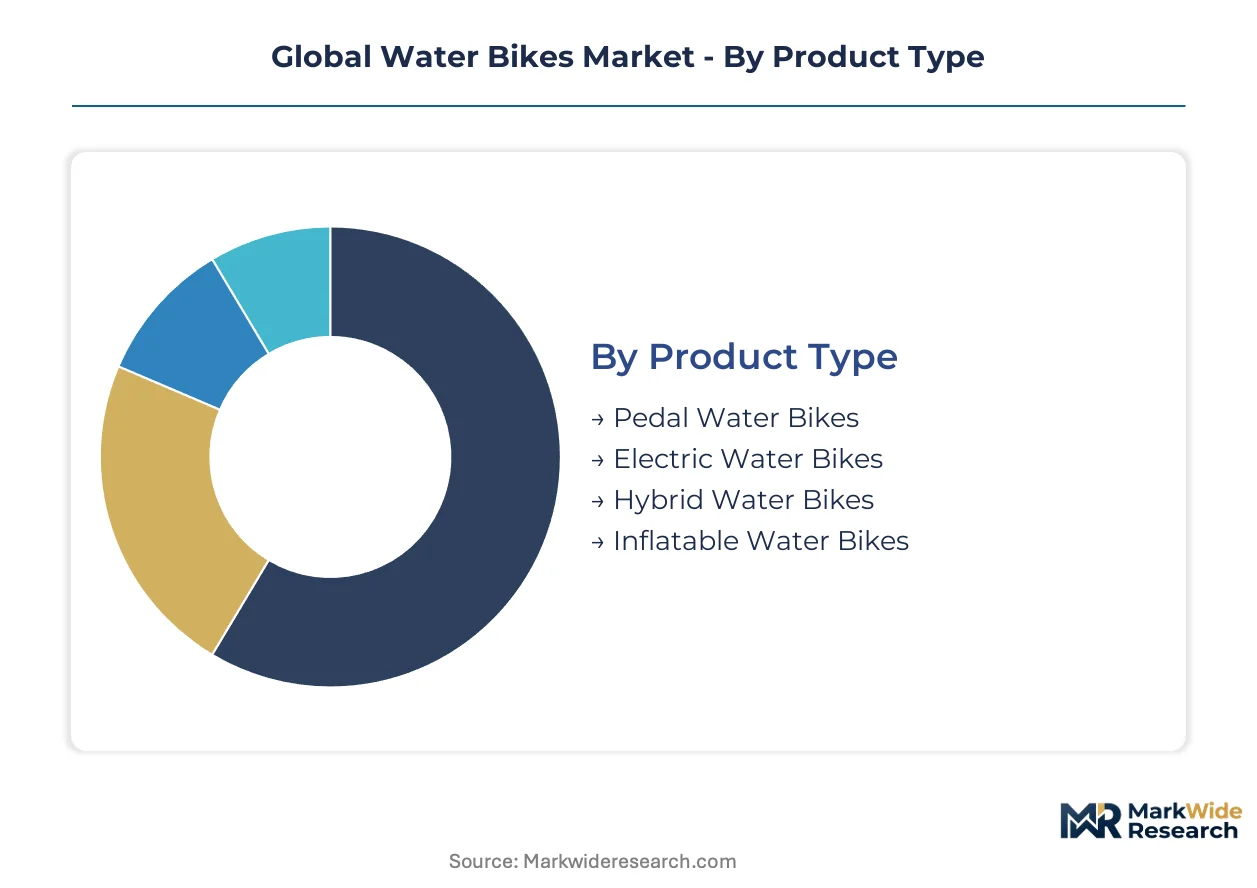
Water bike segmentation reveals divergent capital requirements across product architectures, with electric propulsion systems demanding battery thermal management investment while pedal variants minimize upfront fleet expenditure. Material choices and distribution channels further stratify working capital needs, shaping manufacturer portfolio priorities and operator procurement patterns.
Product Type:
Pedal water bikes demand the lowest capital intensity with minimal electronic componentry, while electric variants require substantial upfront engineering for battery integration and cooling systems.
- Pedal Water Bikes:Human-powered propulsion via sealed bearing pedal drives and marine-grade aluminum or composite hulls. Harbor rental fleets in Barcelona and Sydney concentrate procurement here, driven by zero-emission harbor permit mandates that exclude combustion alternatives. Most installed capacity flows through Pedal Water Bikes. Expansion is steepest in Electric Water Bikes.
- Electric Water Bikes:Lithium-ion battery systems powering submersible propulsion units with integrated thermal management. Australian aquatic tourism hubs and Mediterranean tour operators lead adoption as lithium energy density improvements extend operational range for commercial circuits.
- Hybrid Water Bikes:Dual-mode architecture combining pedal backup with electric assist for extended tourist routes.
- Inflatable Water Bikes:Drop-stitch PVC construction with modular pedal drives for recreational portability and seasonal storage.
Commercial fleet procurement concentrates in pedal and electric architectures, with hybrid systems capturing niche demand from operators serving extended coastal circuits.
End User:
Application context determines maintenance infrastructure requirements, with tour operators needing predictive service contracts while private consumers prioritize purchase price over operational support.
- Tour Operators:Fleet-scale procurement with uptime guarantees and harbor concession compliance requirements. Mediterranean municipalities in Greece and Italy mandate carbon-neutral equipment for waterfront permits, accelerating replacement cycles.
- Recreation Centers:Institutional procurement for aquatic fitness programming with standardized equipment pools and staff training protocols.
- Water Sports Enthusiasts:Premium carbon fiber hull demand with hydrofoil upgrade paths and customization tolerance.
- Private Consumers:Price-sensitive recreational purchase with seasonal storage constraints and minimal service infrastructure expectations.
Tour operators deploy the largest fleet volumes. Recreation centers are expanding most quickly as hotel wellness programs pilot aquatic fitness installations.
Material:
Raw material selection governs manufacturing asset intensity, with carbon fiber prepreg autoclaves requiring seven-figure capital deployment versus aluminum extrusion and welding stations.
- Carbon Fiber:Marine-grade prepreg construction with epoxy resin systems meeting EU REACH substance disclosure mandates. Water sports enthusiasts in Australia and Japanese resort markets drive premium positioning as hull weight reduction improves pedal efficiency and transportability.
- Aluminum:Marine alloy extrusion and welded hull assemblies with field-repairable dent resistance. Harbor rental services across Spanish and Greek islands standardize here, prioritizing damage tolerance and local welding repair over weight optimization.
- Fiberglass:Chopped strand mat and woven roving lamination for mid-tier recreational pricing.
- Plastic:Rotomolded polyethylene hulls for entry-level consumer segments and inflatable rigid-hull combinations.
Aluminum dominates rental fleet installed base. Carbon fiber commands the steepest expansion trajectory among premium consumer segments.
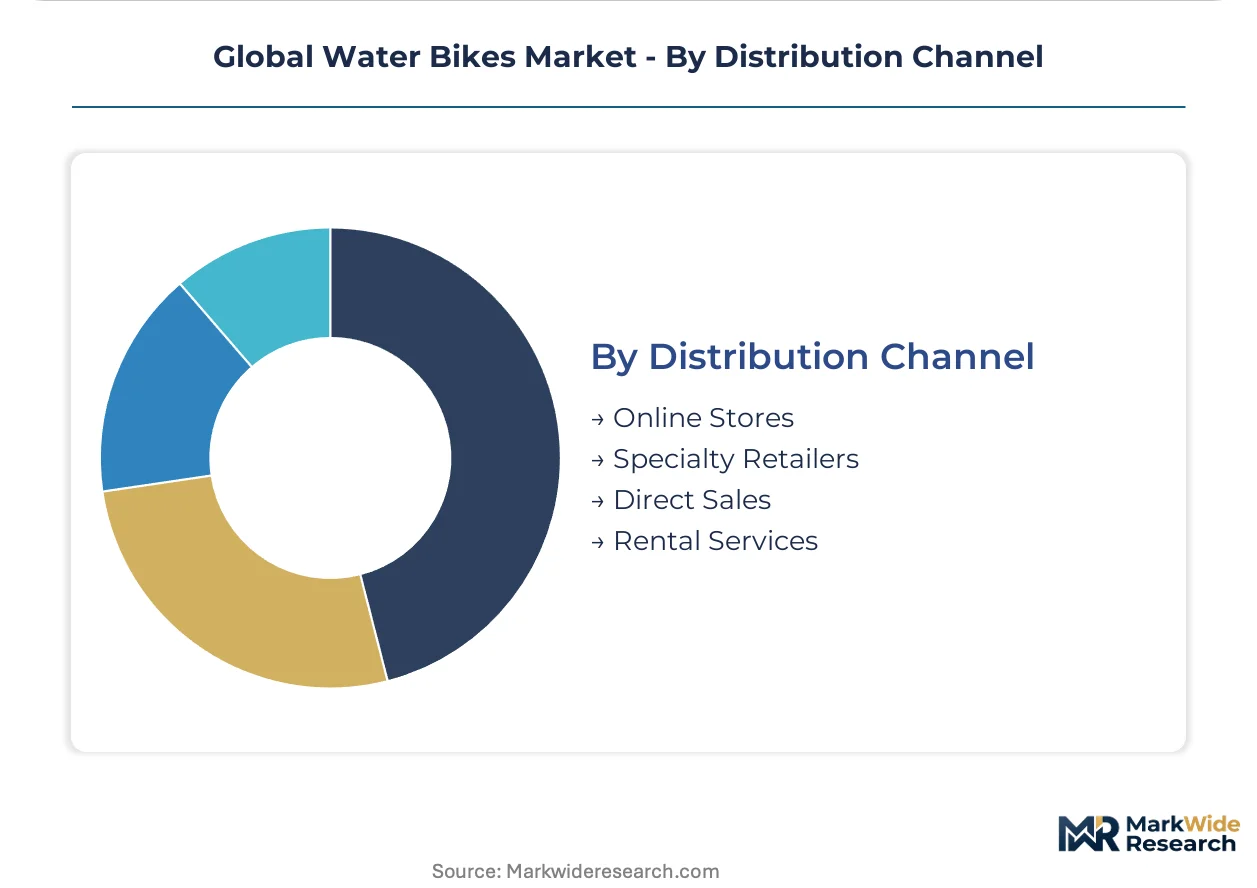
Distribution Channel:
Channel selection reflects customer scale and service complexity, with direct fleet contracting requiring dedicated account infrastructure versus transactional online retail.
- Direct Sales:Manufacturer-to-operator fleet packages with maintenance bundling and uptime guarantees. Australian harbor municipalities in Sydney and Perth now specify predictive maintenance inclusion in tender documents, displacing traditional marine retail.
- Rental Services:Asset-heavy operating lessors providing equipment-plus-service to concession holders with seasonal utilization risk transfer.
- Specialty Retailers:Territory-exclusive arrangements with technical demonstration capacity and local service partnerships.
- Online Stores:Direct-to-consumer fulfillment for inflatable and entry-level pedal variants with minimal pre-purchase inspection requirements.
Direct sales capture the largest fleet transaction value. Rental services are expanding most quickly as municipal tender structures favor operational expenditure over capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping water bike manufacturing geography, with production gravitating toward jurisdictions offering streamlined harbor equipment certification and lower carbon-fiber import duties. Manufacturers now site assembly operations where EU Green Deal compliance costs diverge most sharply from domestic market access advantages.
United States
Harbor municipalities in Florida and California are mandating zero-emission watercraft for new concession leases, displacing gasoline-powered rental fleets. The US Coast Guard governs personal flotation and navigation lighting standards under recreational vessel classifications. Miami and San Diego harbor districts host the densest operator clusters, with aquatic tourism infrastructure expanding into hotel wellness programming.
Australia
State governments in New South Wales and Victoria are funding dedicated water bike docking stations across Sydney, Melbourne, and Brisbane harbor districts. The TGA influences product safety expectations through consumer goods frameworks that extend to recreational marine equipment. Perth operators are pioneering fleet service contracts with uptime guarantees, displacing traditional equipment purchase models.
Spain
Coastal municipalities in Catalonia and Andalusia now require carbon-neutral equipment for waterfront permit renewals, eliminating gasoline-powered alternatives. EU REACH mandates substance disclosure for composite resins used in hull lamination, forcing reformulation of epoxy systems. Barcelona and Marseille harbor rental fleets are adopting hydrofoil retrofit kits to reduce drag and extend tourist circuit range.
Italy
Mediterranean island operators in Sicily and Sardinia are replacing traditional kayak fleets with pedal-powered alternatives to meet harbor concession environmental requirements. The EU Green Deal's zero-emission mandates shape manufacturer compliance priorities for equipment sold into Italian resort markets. Greek island clusters are following Italian regulatory precedents for carbon-neutral water recreation equipment.
Japan
Resort developers in Okinawa and Shizuoka are importing water bikes to diversify aquatic tourism offerings beyond traditional marine activities. METI maritime leisure standards and JIS corrosion testing protocols create export eligibility barriers that compliant manufacturers leverage for premium positioning. East Asian resort clusters are standardizing around Japanese certification requirements as a regional quality benchmark.
Global Water Bikes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hydrofoil-assisted and electric-assist architectures to differentiate beyond basic pedal propulsion. The vendor base stratifies across three tiers: marine-grade aluminum fabricators serving rental fleets, carbon fiber composite specialists targeting water sports enthusiasts, and diversified marine propulsion companies extending leisure applications. Two strategic archetypes dominate: harbor concession fleet suppliers optimizing for field repairability and dent resistance, and premium positioning specialists emphasizing hull weight reduction and hydrofoil lift efficiency. Competitive moves concentrate on direct-to-operator distribution bypassing marine retail intermediaries, and predictive maintenance bundling to capture municipal tender specifications.
Among North American specialists, Hydrobikes Inc. and Schiller Bikes exemplify contrasting archetypes within the rental fleet and premium consumer segments respectively. Manta5 occupies a position representing hydrofoil engineering heritage applied to pedal-assisted watercraft. Yamaha Motor Corporation, USA anchors the diversified marine propulsion tier, extending intellectual property from powerboat engines into electric leisure applications. These three entities collectively illustrate the competitive spectrum from pure-play water bike fabricators to conglomerate-backed leisure divisions.
| Leading Market Players |
|---|
| Hydrobikes Inc. |
| Manta5 |
| Schiller Bikes |
| Redsharkbikes |
| SBK Engineering |
| Yamaha Motor Corporation, USA |
| Aurea Bike |
| Waterbike Italia S.R.L |
| Pioner Boats |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's zero-emission harbor equipment mandates gate both qualified supply and premium-tier pricing access, restricting fleet procurement to certified manufacturers while carbon-neutral compliance costs stratify pricing tiers across Mediterranean and Australian markets.
Pricing Analysis
Distributor margins compress as direct-to-operator fleet contracting displaces marine retail intermediaries in harbor concession procurement. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy rotomolded plastic hulls reflects material certification grade and after-sales service bundling. Pricing pressure stems from lithium-ion battery thermal management engineering costs under EU F-Gas Regulation constraints. Tour operators exhibit highest price sensitivity due to seasonal utilization gaps, while water sports enthusiasts tolerate premium positioning for hydrofoil-equipped architectures.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and Japanese marine-grade carbon fiber prepreg manufacturers controlling resin formulation output for lightweight hull production. Raw material dependencies center on aerospace-grade carbon fiber, marine aluminum alloys, and lithium-ion battery cells from South Korean and Chinese cell producers. Supply chain risk concentrates in tariff exposure on composite resin imports under evolving EU-Asia trade frameworks. Distribution runs through direct fleet contracting with predictive maintenance bundling, displacing traditional specialty retailer channels in municipal harbor tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Italy and France diverge sharply from certification-light harbor procurement in Florida and California, creating margin capture opportunities for dual-registered manufacturers.
For Market Incumbents: Deepen backward integration into marine-grade carbon fiber prepreg sourcing to offset Asian supply concentration risk. Lock harbor concession fleet service contracts with uptime guarantees before municipal tender structures exclude pure equipment vendors. Defend against emerging hydrofoil specialists by accelerating foil-retrofit kit development for installed aluminum hull bases. For New Entrants and Emerging Players: Launch via direct-to-operator distribution targeting Australian state-funded aquatic mobility hubs in Sydney and Perth harbor districts. Penetrate the fitness application white space by supplying health clubs and hotel wellness programs with standardized aquatic exercise installations. Exploit Japanese resort market entry barriers by securing METI maritime leisure certification ahead of regional competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional harbor fleet operators because municipal tender consolidation favors asset-heavy service providers with predictive maintenance infrastructure. Five-to-ten year viability hinges on electric propulsion cost curves and lithium energy density improvements. Target acquisition candidates with established uptime guarantee contracts and JIS corrosion testing compliance. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for electric water bike margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrofoil Retrofit Kit Development | Barcelona and Marseille rental fleets adopt foil systems to extend tourist circuit range and reduce pedal drag. |
| Direct-to-Operator Fleet Contracting | Sydney and Perth municipal tenders now specify predictive maintenance inclusion, displacing marine retail channels. |
| Bio-Based Resin Formulation | German and Dutch market entry requires REACH-compliant epoxy alternatives to preempt regulatory rejection. |
| Japanese Certification Investment | METI maritime leisure standards and JIS corrosion protocols create premium positioning in Okinawa resort clusters. |
| Battery Thermal Management Partnership | EU F-Gas Regulation constraints on refrigerant choices drive engineering collaboration with marine HVAC specialists. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with harbor concession operators, marine composite procurement leads, naval architects specializing in saltwater corrosion engineering, and municipal waterfront planning officers with secondary validation against EU harbor permit databases, Australian state infrastructure budget disclosures, US Coast Guard recreational vessel classification records, and Asian carbon fiber trade flow customs data. Bottom-up fleet installation counts and top-down tourism expenditure estimates were cross-referenced for triangulation.
Segment-weighting approaches modeled product type splits between pedal, electric, hybrid, and inflatable architectures alongside material tier differentiation across carbon fiber, aluminum, fiberglass, and plastic hull constructions. End-user segmentation incorporated tour operator fleet procurement patterns, recreation center institutional purchasing, and private consumer seasonal demand cycles. CAGRs were derived from harbor concession replacement timelines and lithium-ion energy density improvement curves. Industry-specific forecast inputs included EU Green Deal permit mandate rollout schedules and METI maritime leisure standard adoption trajectories across East Asian resort markets.
Several conditions sit outside the modeled scope, including potential combustion-engine rental fleet grandfathering clauses in Mediterranean municipalities, abrupt lithium supply chain disruptions, and unilateral tariff impositions on marine-grade composite imports. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and tourism infrastructure funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Outdoor Backpack Market