
 Outdoor Backpack Market | 2026-2036
Outdoor Backpack Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Backpack Market Intelligence
A shift from single-source Asian supply to multi-source regional manufacturing is broadening the vendor map for frame and fabric components. VF Corporation leverages its vertical manufacturing network to control nylon supply chains from polymer to finished pack. Deuter Sport GmbH anchors its production in Alpine Europe, sustaining premium positioning through proximity to core hiking markets. Osprey Packs specializes in ergonomic suspension systems, differentiating on fit technology rather than material cost.
An outdoor backpack is a load-bearing carrying system constructed with internal or external frames, engineered fabrics such as ripstop nylon or Cordura, and adjustable harnesses designed to distribute weight across the hips and shoulders for sustained mobility. Primary applications span multi-day trekking, urban commuting, and technical climbing where payload stability and weather resistance determine functional value. Trekking bags dominate value contribution due to complex suspension engineering and higher retail price points, while hydration packs represent the fastest-expanding category as trail runners and mountain bikers prioritize fluid access over cargo volume. Nylon retains volume leadership for strength-to-weight performance, though recycled polyester is capturing margin pools as sustainability certifications become procurement gatekeepers.
REACH restricts chemical inputs in European-sourced textiles, pushing manufacturers toward bluesign-approved dye houses and PFAS-free water repellency. The US Consumer Product Safety Commission monitors load-bearing hardware for mechanical failure risk, particularly on child carrier packs. ISO 9001 quality management and OEKO-TEX Standard 100 certifications increasingly appear in retail buyer requirements across North American and Asian distribution channels. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and California that will reshape end-of-life collection obligations and material circularity investments.
Market Dynamics
REACH compliance and bluesign certification requirements are forcing manufacturers to reconfigure dye house partnerships and water-repellency chemistry, compressing margins for non-compliant suppliers while rewarding early adopters with preferred retail placement.
Growth Catalysts
- Adventure tourism procurement programs:Tour operators in Germany and New Zealand are bundling technical packs with guided expedition packages, creating institutional demand channels distinct from retail.
- PFAS-free chemistry innovation:ECHA restrictions on fluorinated compounds are accelerating silicone and paraffin-based DWR adoption, opening patent positions for European chemical suppliers.
- Mountain bike trail infrastructure:Purpose-built bike parks in Colorado and British Columbia are normalizing dedicated hydration pack use among recreational riders previously using general-purpose bags.
Market Restraints
- Nylon 6,6 supply concentration:Polymer production clusters in China and the US Gulf Coast create input vulnerability for ripstop fabric mills during petrochemical volatility cycles.
- Frame hardware forging capacity:Aluminum and Delrin component stamping relies on a limited vendor base in Vietnam's northern industrial zones, constraining rapid scaling.
- Extended producer responsibility timelines:EU and California frameworks mandate end-of-life collection infrastructure investments that smaller brands cannot amortize across low volumes.
Strategic Opportunities
- Modular repair ecosystems:Component-level replacement programs for buckles, straps, and back panels create recurring revenue streams and brand loyalty loops.
- Corporate wellness procurement:Urban employers subsidizing commuter packs for cycling employees represent an untapped B2B channel with volume pricing potential.
- Recycled ocean plastic certification:Ocean-bound polyester traceability systems from SEAQUAL and Parley open premium positioning for sustainability-verified product lines.
Industry Challenges
- Pattern engineering talent scarcity:Specialized knowledge in load distribution geometry and 3D harness modeling concentrates among aging specialists in Alpine Europe and Japan.
- Multi-certification compliance stacking:Simultaneous pursuit of bluesign, OEKO-TEX, and ISO 9001 creates documentation burdens that delay product launch windows by 8-14 months.
- Legacy ERP integration with traceability platforms:Blockchain-enabled material provenance systems require middleware development that mid-tier manufacturers lack technical staff to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Backpack Market |
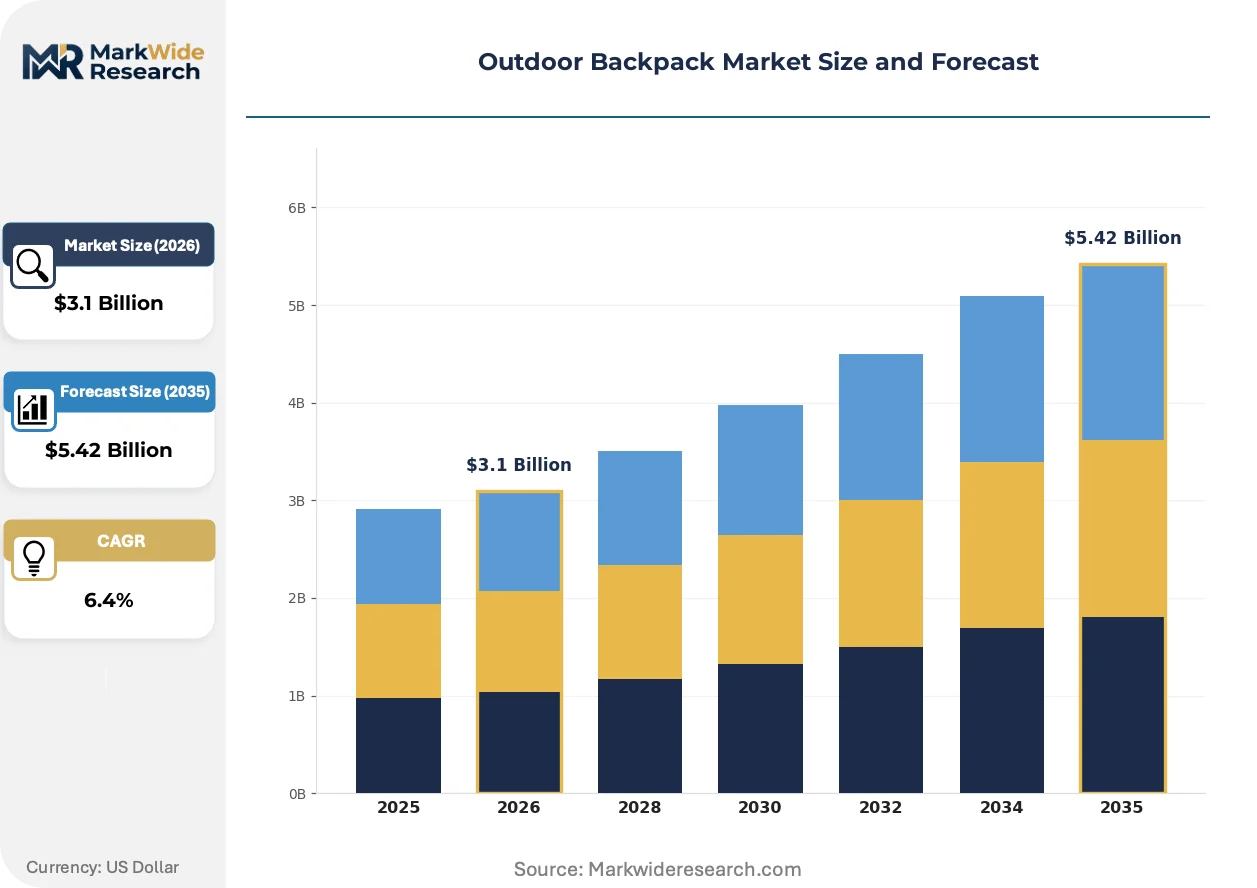
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trekking Bags, Daypacks, Hydration Packs, Travel Backpacks Application: Hiking, Camping, Travel, School Material: Nylon, Polyester, Canvas, Leather End User: Outdoor Enthusiasts, Students, Travelers, Professionals |
| Companies Covered | VF Corporation, Osprey Packs, Deuter Sport GmbH, The North Face, Patagonia, Columbia Sportswear, Samsonite International, Amer Sports Corp., Thule Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Backpack Market Strategic Shifts & Innovations
Material traceability systems and adaptive suspension geometries are compressing the traditional two-year product development cycle, while regulatory chemistry bans are eliminating incumbent supply relationships faster than alternatives can scale.
Recycled polyester with verified post-consumer content is integrating into main body fabrics and lining materials previously reserved for virgin nylon. Trail running and fastpacking segments are adopting these materials at parity pricing as retail buyers mandate sustainability documentation. This shift is integrating circular material flows into standard procurement specifications, displacing virgin polymer dependence among tier-one suppliers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain C8 fluorocarbon water repellents from European-sourced textiles. Manufacturers must qualify alternative chemistries through accelerated abrasion and wash-cycle testing before seasonal production windows. Technical climbing packs face the steepest reformulation timelines, with German and Austrian brands leading compliance migration to maintain alpine retail access.
Direct-to-consumer configuration tools are fragmenting the traditional wholesale model. Buyers now specify torso length, hip belt size, and accessory compatibility through web interfaces, with production batches as small as fifty units. This pattern concentrates in North American markets where REI and specialty retailers have ceded assortment control to brand-owned channels, while European consumers retain higher expectations for physical fitting services.
Outdoor Backpack Market Segmentation
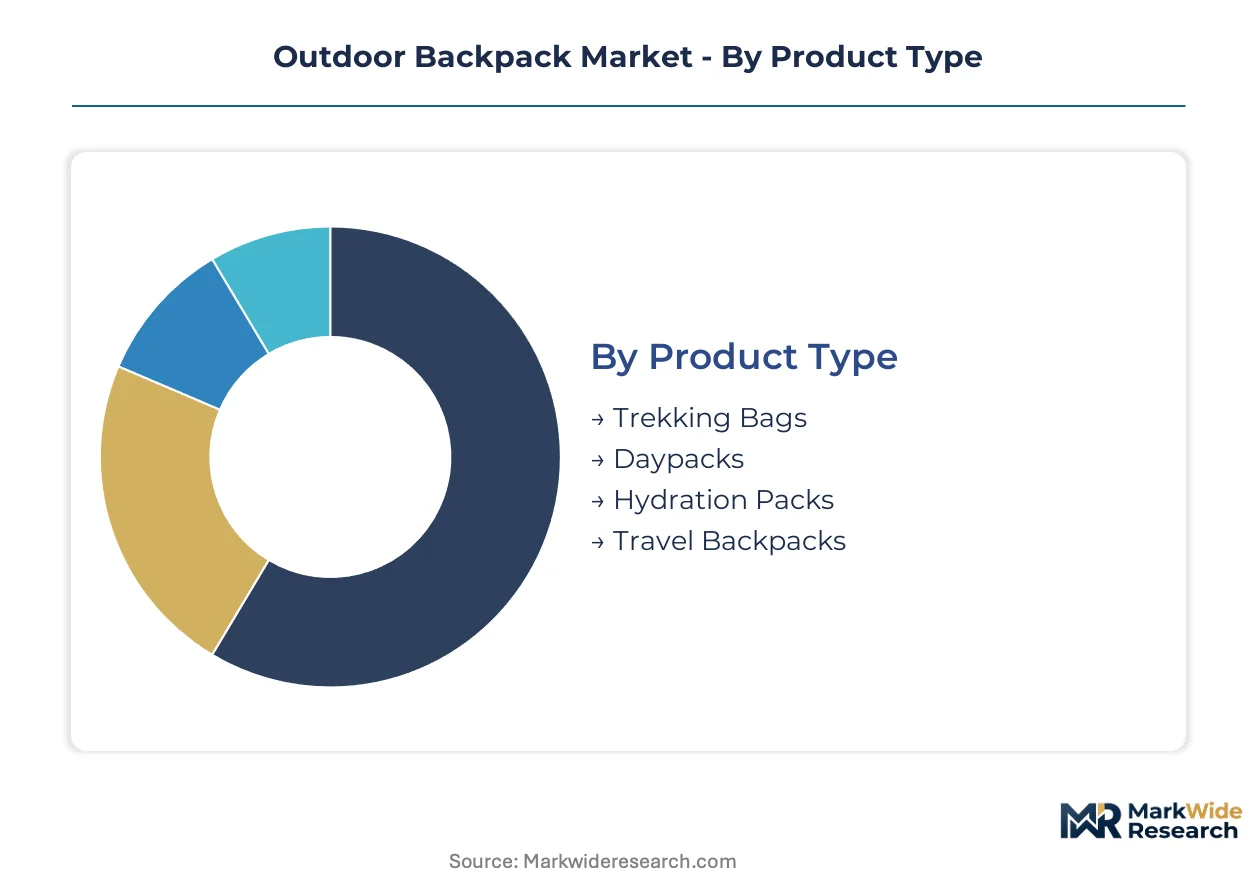
Outdoor backpack segmentation reveals how suspension engineering, trip duration, and user mobility requirements create distinct procurement specifications across retail and institutional channels. Buyers prioritize load distribution geometry for multi-day treks versus weatherproofing for daily commuting, driving divergent material and hardware investments.
Product Type:
Cost tier differentiation separates technical expedition buyers from casual day hikers and urban commuters with distinct durability and feature expectations.
- Trekking Bags:Internal frame systems with adjustable torso lengths and load-lifter straps distribute 20-40kg across hips and shoulders for alpine terrain. German and Austrian alpine clubs specify these for guided expeditions, with suspension engineering commanding premium retail placement.
- Daypacks:Frameless or minimal-frame designs under 25 liters prioritize lightweight fabrics for summit pushes and trail running. Colorado trail runners and British Columbia mountain bikers are normalizing dedicated use where fluid access and minimal bulk outweigh cargo capacity.
- Hydration Packs:Integrated reservoir sleeves and tube routing for on-the-move drinking dominate fastpacking segments.
- Travel Backpacks:Panel-loading access and lockable zippers suit airport security and hostel storage requirements.
Trekking bags lead volumes today; hydration packs are gaining share fastest.
Application:
Volume concentration tracks seasonal expedition calendars and institutional procurement cycles rather than individual purchase patterns.
- Hiking:Multi-day trail networks in Germany's Alpine regions and New Zealand's Department of Conservation tracks sustain replacement demand for abrasion-resistant fabrics and reinforced bottom panels. REACH-compliant water repellency has become a non-negotiable specification for European retail placement.
- Camping:Base camp configurations require expanded cargo volumes with external lash points for tents and sleeping pads. Family camping growth in US national parks is driving child carrier pack demand monitored by the Consumer Product Safety Commission for mechanical failure risk.
- Travel:Carry-on dimension compliance and theft-deterrent features dominate urban mobility use cases.
- School:Ergonomic load distribution for adolescent spine protection shapes regional procurement in Japan and South Korea.
Hiking leads volumes today; camping is expanding most quickly.
Material:
Margin pools are shifting toward certified sustainable inputs as bluesign and OEKO-TEX documentation becomes mandatory for tier-one supplier qualification.
- Nylon:Ripstop weaves and Cordura face fabrics deliver strength-to-weight ratios essential for technical climbing packs. Vietnam's cut-and-sew zones rely on polymer supply clusters in China and the US Gulf Coast, creating vulnerability during petrochemical volatility cycles.
- Polyester:Recycled post-consumer content with SEAQUAL and Parley traceability is displacing virgin polymer in main body fabrics. Trail running and fastpacking segments adopt these at parity pricing as retail buyers mandate sustainability documentation.
- Canvas:Waxed cotton heritage constructions appeal to heritage positioning in urban commuter lines.
- Leather:Full-grain and top-grain applications concentrate in premium positioning where aesthetic durability outweighs weight penalties.
Nylon leads volumes today; recycled polyester is climbing the fastest.
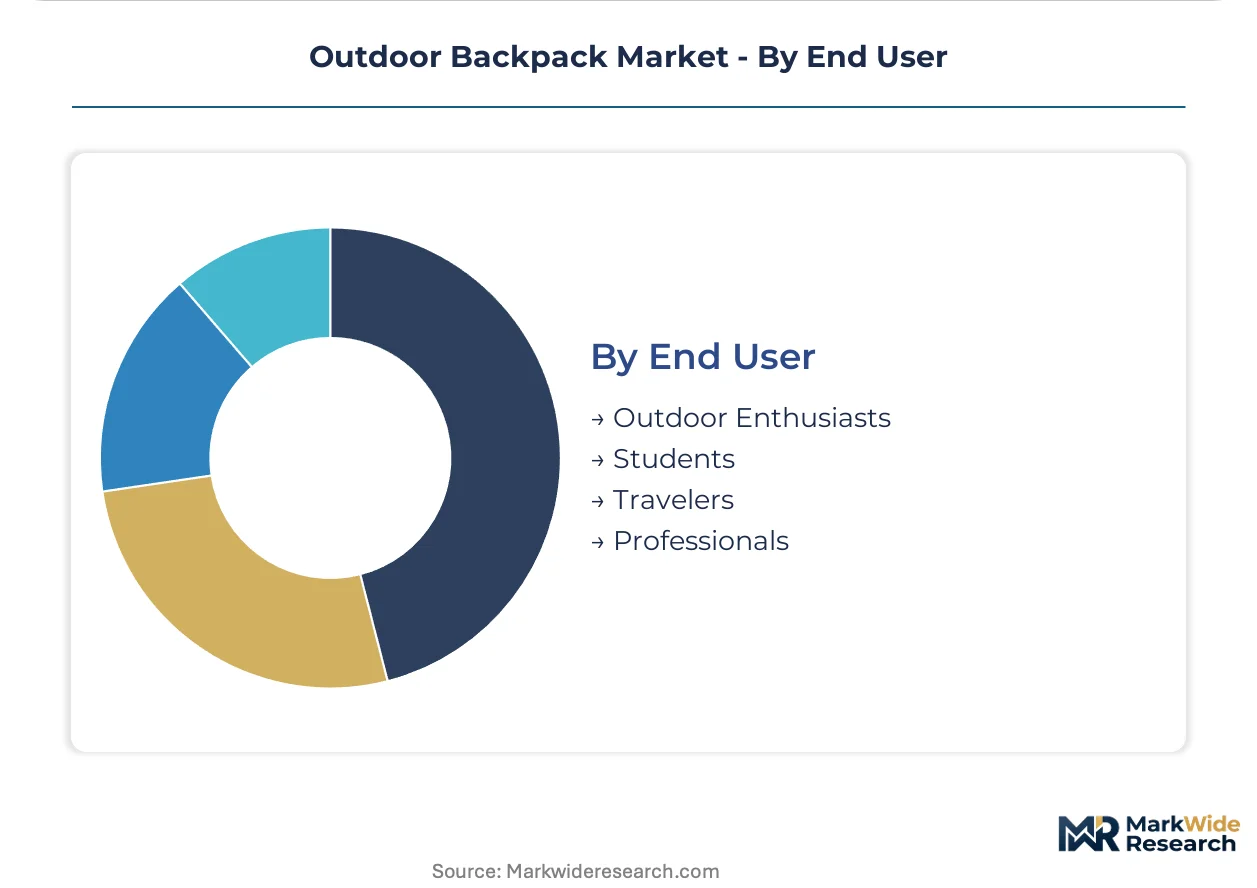
End User:
Customer type determines channel strategy, with institutional procurement bypassing traditional retail markup structures.
- Outdoor Enthusiasts:Technical specifications around suspension adjustability and weather sealing drive repeat purchase loyalty. Adventure tourism operators in Germany and New Zealand bundle guided expedition packages with technical pack procurement, creating volume channels distinct from consumer retail.
- Students:Price-sensitive volume purchasing with ergonomic requirements for daily load carrying. Japanese school districts specify JIS-standard spine protection features in annual procurement tenders.
- Travelers:Carry-on compliance and anti-theft hardware prioritize airport and urban mobility functionality.
- Professionals:Corporate wellness programs subsidizing commuter cycling packs represent an untapped B2B channel with volume pricing potential in North American urban employment clusters.
Outdoor enthusiasts lead volumes today; professionals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's alpine manufacturing clusters anchor production for technical trekking equipment, while Vietnam's cut-and-sew zones handle volume assembly. Demand concentrates where adventure tourism operators bundle expedition packages with gear procurement.
Germany
Alpine clubs and guided expedition operators sustain institutional procurement of internal-frame trekking systems. REACH Annex XVII restrictions on PFAS compounds force reformulation of water-repellent chemistries ahead of seasonal production windows. Manufacturing concentrates in Bavaria's Alpine foothills where Deuter Sport GmbH maintains captive production for premium positioning.
United States
Colorado trail runners and British Columbia-bound mountain bikers normalize dedicated hydration pack use through purpose-built bike park infrastructure. The Consumer Product Safety Commission monitors load-bearing hardware on child carrier packs for mechanical failure risk. Frame hardware forging relies on limited vendor capacity in Vietnam's northern industrial zones, creating scaling constraints during demand surges.
Vietnam
Cut-and-sew production zones in northern industrial provinces process ripstop nylon from China and US Gulf Coast polymer clusters. Petrochemical volatility cycles create input vulnerability for fabric mills serving export orders. Ho Chi Minh City-area facilities specialize in aluminum and Delrin component assembly for mid-tier brands.
China
Nylon 6,6 polymer production clusters supply ripstop fabric mills across Asia-Pacific cut-and-sew networks. MIIT standards for textile chemical inputs intersect with bluesign certification requirements for European export orders. Yangtze River Delta manufacturing bases balance domestic outdoor retail growth against compliance costs for REACH-aligned dye house partnerships.
Japan
JIS-standard spine protection specifications govern school backpack procurement tenders in Tokyo and Osaka metropolitan districts. METI guidelines on product safety shape ergonomic load distribution requirements for adolescent daily carry. Pattern engineering talent concentrates among aging specialists in Nagoya-area technical textile development centers.
Outdoor Backpack Market Key Industry Players
Global majors compete with regional champions across certification compliance and suspension engineering capabilities. Market structure tiers into vertically integrated polymer-to-pack operators, Alpine-proximity premium specialists, and Asia-based volume assemblers. Three archetypes dominate: chemical compliance leaders capturing preferred retail placement, ergonomic technology differentiators commanding fit-based premiums, and scale-driven manufacturers optimizing cut-and-sew economics. Competitive moves concentrate on dye house partnership reconfigurations and modular repair ecosystem development.
Among Alpine Europe-based specialists, Deuter Sport GmbH exemplifies proximity-to-market positioning through German manufacturing retention. VF Corporation represents backward integration from polymer supply through finished pack distribution. Osprey Packs occupies a position within the ergonomic technology tier, differentiating through suspension system specialization rather than material cost optimization.
| Leading Market Players |
|---|
| VF Corporation |
| Osprey Packs |
| Deuter Sport GmbH |
| The North Face |
| Patagonia |
| Columbia Sportswear |
| Samsonite International |
| Amer Sports Corp. |
| Thule Group |
| Others |
Cost & Logistics Intelligence
Nylon 6,6 polymer costs ripple from China and US Gulf Coast petrochemical clusters through ripstop fabric mills to finished pack pricing tiers. REACH-compliant dye house partnerships and bluesign certification requirements compress margins for non-compliant suppliers while rewarding early adopters with preferred retail placement in European alpine retail channels.
Pricing Analysis
Input-cost pass-through from petrochemical volatility drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on suspension engineering complexity and certification grade, with ergonomic technology commanding fit-based premiums over material-cost-optimized alternatives. Pricing pressure stems from PFAS-free chemistry reformulation timelines compressing seasonal production windows. Students and price-sensitive volume purchasers exhibit highest price sensitivity; alpine club institutional procurement and corporate wellness channels demonstrate lowest sensitivity due to bundled service value.
Supply Chain Analysis
Ripstop nylon supply rests on polymer production clusters in China and the US Gulf Coast, with cut-and-sew assembly concentrating in Vietnam's northern industrial zones and Germany's Alpine manufacturing foothills. Raw material dependencies span nylon 6,6 polymer, aluminum frame hardware, and Delrin component stamping. Single-source vulnerability in Vietnam's aluminum and Delrin forging capacity constrains rapid scaling during demand surges. Distribution runs through adventure tourism operator procurement programs, specialty retail channels, and direct-to-consumer configuration platforms with production batches as small as fifty units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA PFAS restrictions under REACH Annex XVII force chemistry reformulation ahead of each seasonal production window, accelerating compliance investment returns for prepared suppliers.
For Market Incumbents: Cement preferred retail placement through early bluesign and OEKO-TEX certification completion before competitor qualification timelines. Capture institutional procurement channels by aligning suspension engineering specifications with German and Austrian alpine club expedition calendars. Defend against modular repair ecosystem entrants by launching component-level replacement programs for buckles, straps, and back panels that create recurring revenue streams.
For New Entrants and Emerging Players: Begin with corporate wellness procurement channels in North American urban employment clusters where cycling commuter pack subsidies represent untapped B2B volume potential. Target fastpacking and trail running segments where recycled polyester adoption at parity pricing enables sustainability-verified positioning without premium cost barriers. Pursue direct-to-consumer configuration tools allowing torso length and hip belt specification through web interfaces.
For Investors and Strategic Acquirers: Consolidation pressure builds where extended producer responsibility frameworks in the European Union and California mandate end-of-life collection infrastructure investments that smaller brands cannot amortize across low volumes. Pattern engineering talent scarcity among aging specialists in Alpine Europe and Japan creates acquisition value for technical capabilities. Watch SEAQUAL and Parley ocean-bound polyester traceability adoption rates as inflection indicators for premium sustainability positioning viability.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Migration | ECHA restrictions eliminate C8 fluorocarbon water repellents, forcing silicone and paraffin-based DWR qualification through accelerated testing protocols. |
| Modular Repair Ecosystem Launch | Component-level replacement programs for buckles and back panels create recurring revenue streams and brand loyalty loops distinct from one-time retail transactions. |
| Corporate Wellness Channel Development | Urban employers subsidizing commuter cycling packs unlock B2B volume pricing potential in North American employment clusters previously bypassed by outdoor retail. |
| Recycled Ocean Plastic Certification | SEAQUAL and Parley traceability systems enable premium positioning for sustainability-verified product lines in trail running and fastpacking segments. |
| Direct-to-Consumer Configuration Platform | Web-based torso length and hip belt specification fragments traditional wholesale models with production batches as small as fifty units. |
Research Approach
Multiple input streams — primary interviews with brand product managers, supply chain directors at cut-and-sew facilities, and adventure tourism procurement officers; secondary validation through customs and trade data, bluesign certification registries, and alpine club expedition specifications — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed technical textile developers, frame hardware forging specialists, and retail category buyers across German, Vietnamese, and US distribution channels. Secondary sources included REACH Annex XVII regulatory filings, OEKO-TEX Standard 100 certification databases, and Consumer Product Safety Commission mechanical failure incident reports.
Data-stream reconciliation across product type, application, material grade, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled volume and value trajectories incorporating adventure tourism procurement cycle timing, petrochemical input volatility patterns, and regulatory compliance deadline clustering. Industry-specific forecast inputs encompassed seasonal production window constraints and pattern engineering talent pipeline demographics.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to extended producer responsibility frameworks and breakthrough suspension geometry patents that could compress development cycles. Forecasts reflect documented assumptions about bluesign certification adoption rates and PFAS-free chemistry scale-up timelines. Supply chain disruption from geopolitical tension in polymer production regions and logistics chokepoint congestion represent specific risk factors that could revise projections. A small set of named triggers — ECHA enforcement intensity, ocean plastic traceability system adoption, and corporate wellness program expansion rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Hiking Accessories Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market