
 Hiking Backpacks Market | 2026-2036
Hiking Backpacks Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Backpacks Market Foresight
Ultralight specification tiers is redrawing competitive boundaries in hiking backpacks. Hyperlite Mountain Gear leverages Dyneema composite expertise to dominate sub-one-pound load haulers. Osprey sustains broad market presence through anatomical suspension R&D and deep REI channel partnerships. Gregory Packs anchors the premium expedition segment with reinforced frame-sheet architectures for 60L-plus payloads.
Hiking backpacks are load-bearing systems constructed from ripstop nylon, laminated Cordura, or woven Dyneema with internal or external frame structures, designed to distribute weight across the hips and shoulders during multi-hour or multi-day terrain traversal. Overnight packs in the 51L to 70L capacity band command the largest revenue pool as three-to-five-day trekkers prioritize volume-to-weight optimization. Daypacks below 20L represent the fastest-expanding segment, driven by trail running and fastpacking crossovers from the casual hiker end-user category. Nylon retains material dominance though recycled-content variants are displacing virgin polymer lines as mountaineers and serious trekkers scrutinize supply chain credentials.
REACH chemical restrictions and the EU Green Deal textile strategy are tightening acceptable thresholds for DWR coatings and fluorocarbon treatments across European supply chains. The EPA's emerging PFAS regulations in the United States will extend similar compliance burdens to brands distributing in North America. Stakeholders must monitor how quickly Bluesign and OEKO-TEX certification migrate from premium positioning to baseline market access requirements.
Market Dynamics
The EU Green Deal's textile sustainability requirements are decomposing virgin nylon supply chains and forcing manufacturers toward recycled-content laminates and PFC-free waterproofing across European distribution networks.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening DWR coating thresholds are accelerating Bluesign certification adoption among Alpine outfitters seeking market access.
- Thru-hiker community expansion:Long-distance trail completion rates in Germany's hut-to-hut networks are sustaining premium pack replacement cycles.
- Dyneema composite weaving:Ultralight material advances are compressing sub-one-pound load hauler specifications across weekend warrior segments.
Market Restraints
- Recycled nylon input cost volatility:Post-consumer polymer feedstock prices fluctuate with municipal collection infrastructure gaps in Southeast Asian processing hubs.
- Fluorocarbon treatment substitution:PFC-free DWR alternatives demonstrate 30-40% durability degradation versus legacy C8 chemistry in independent abrasion testing.
- Frame-sheet aluminum supply concentration:Extruded 7075-T6 sourcing clusters in Chinese smelting regions create single-point vulnerability for expedition-grade manufacturers.
Strategic Opportunities
- Fastpacking crossover demand:Trail running communities in Colorado's Front Range and Chamonix valley are adopting sub-20L technical daypacks for single-push alpine objectives.
- EU Green Deal textile strategy:Extended producer responsibility mandates create first-mover advantage for brands with closed-loop take-back infrastructure.
- REI channel partnership depth:Co-development agreements with cooperative retail networks enable exclusive volume-tier distribution for 51L-70L overnight segments.
Industry Challenges
- Bluesign certification timeline compression:Chemical inventory auditing requirements extend new product development cycles by 8-14 months for laminates and coatings.
- Load-lifter strap integration complexity:Anatomical suspension R&D demands specialized biomechanical testing facilities scarce outside Bavarian and Colorado manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Backpacks Market |
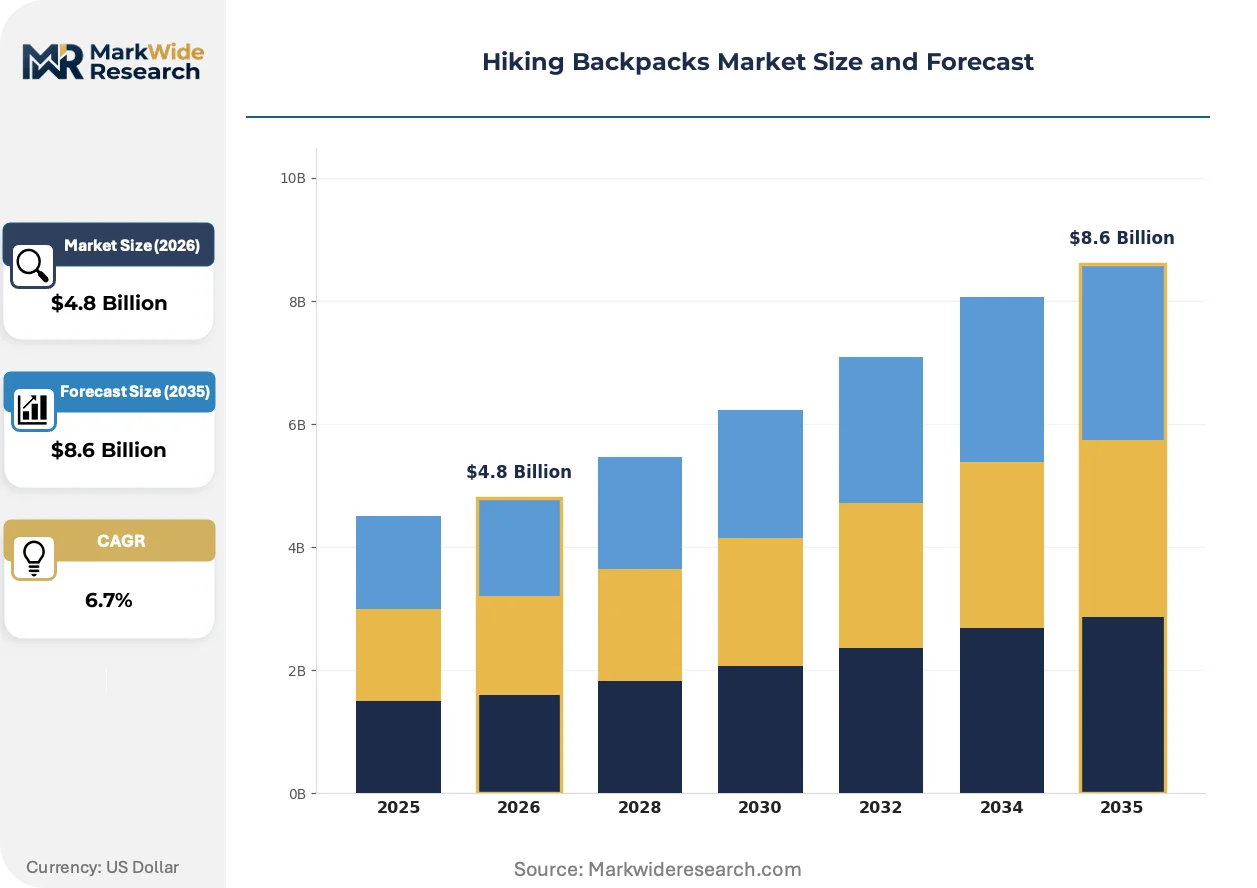
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daypacks, Hydration Packs, Overnight Packs, Expedition Packs Material: Nylon, Polyester, Canvas, Synthetic Leather Capacity: Less than 20L, 20L to 50L, 51L to 70L, Above 70L End User: Casual Hikers, Serious Trekkers, Campers, Mountaineers |
| Companies Covered | Arcteryx, ULA Equipment, Osprey, Granite Gear, REI Co-op, Gregory Packs, Hyperlite Mountain Gear, Rab, Deuter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Backpacks Market Shifts & Advancements
Material science advances and regulatory chemistry bans are simultaneously compressing product lifecycles and opening premium positioning for certified-sustainable alternatives across load-bearing equipment categories.
Dyneema Composite Fabric is decomposing traditional Cordura-nylon laminate hierarchies in technical backpacking. Thru-hikers and alpine climbers now specify woven polyethylene for tear strength-to-weight ratios exceeding 30:1 versus ballistic nylon. This material shift is decomposing established price-performance tiers and forcing legacy manufacturers to license composite weaving patents or surrender ultralight market segments.
EPA's emerging PFAS regulations are extending REACH-equivalent compliance burdens to North American distribution networks. Stateside brands must reformulate DWR treatments and waterproof membranes ahead of federal enforcement timelines. The 51L-70L overnight pack segment faces the steepest retooling costs given membrane surface area requirements for multi-day weather protection.
Certification-driven preference shifts are restructuring wholesale procurement criteria. REI and specialty retailers now require OEKO-TEX Standard 100 documentation for new pack introductions, displacing uncertified competitors from prime shelf positioning. This behavioral change concentrates most visibly in Germany's Alpine regions and Pacific Northwest outdoor retail clusters where consumer scrutiny of supply chain credentials runs highest.
Hiking Backpacks Market Segmentation
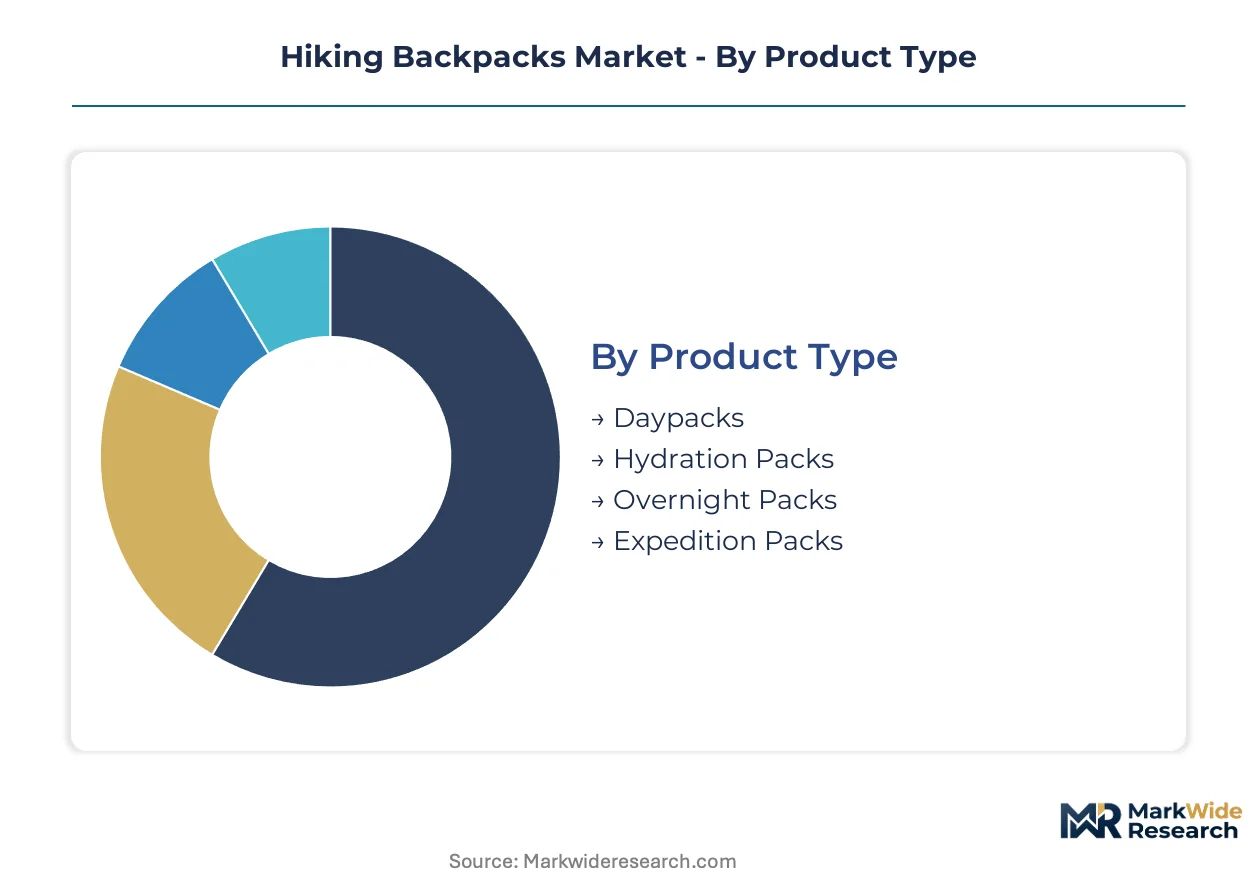
Segmentation in hiking backpacks reveals how load-bearing specifications, material credentials, and user intensity tiers fragment manufacturing priorities and channel strategies. Margin pools concentrate where technical performance intersects with regulatory compliance requirements.
Product Type:
Margin pools sit deepest in technical overnight and expedition categories where frame-sheet engineering and weatherproofing command price premiums.
- Overnight Packs:Three-to-five-day trekking configurations in the 51L to 70L band dominate revenue concentration. Germany's Alpine hut-to-hut networks and Colorado's dispersed camping zones sustain replacement cycles for load-distributing suspension systems.
- Daypacks:Sub-20L technical configurations are expanding most quickly as trail running communities in Chamonix and Colorado's Front Range adopt fastpacking hybrids. Crossover demand from casual hikers compresses development cycles for ultralight frameless designs.
- Hydration Packs:Integrated reservoir systems target single-day endurance athletes with lumbar-centered weight distribution and quick-access drinking tubes.
- Expedition Packs:Reinforced frame-sheet architectures for 60L-plus payloads anchor the premium segment with 7075-T6 aluminum stays and laminated Cordura abrasion panels.
Overnight packs hold installed capacity. Daypacks are rotating up the share rankings.
Material:
Cost tier differentiation separates virgin polymer laminates from certified-recycled alternatives facing EU Green Deal compliance thresholds.
- Nylon:Ripstop weaves and laminated Cordura variants retain material dominance. REACH chemical restrictions and ECHA's tightening DWR coating thresholds are accelerating Bluesign certification adoption among Alpine outfitters seeking European market access.
- Polyester:Lower-cost alternative for entry-level packs with reduced tear strength specifications. Southeast Asian processing hubs dominate feedstock supply, creating volatility in post-consumer polymer pricing.
- Canvas:Heritage aesthetic configurations target urban-outdoor crossover segments with waxed cotton durability and repairable construction.
- Synthetic Leather:Accent material for base reinforcement and aesthetic differentiation in fashion-oriented daypack lines.
Nylon commands legacy volume. Recycled-content variants are climbing the fastest.
Capacity:
Volume bands align directly with trip duration and gear-intensive activity requirements across user intensity tiers.
- 51L to 70L:The overnight trekking standard balances volume-to-weight optimization for multi-day self-supported travel. EPA's emerging PFAS regulations and membrane surface area requirements for weather protection create the steepest retooling costs in this band.
- Less than 20L:Frameless ultralight configurations for summit pushes and trail running crossovers. Dyneema composite weaving expertise compresses specifications below one-pound thresholds for weekend warrior segments.
- 20L to 50L:Day-hiking and technical cragging range with panel-loading access and rope-carry straps.
- Above 70L:Expedition-grade haulers for unsupported wilderness travel with external frame options and detachable lid packs.
51L to 70L maintains category leadership. Sub-20L configurations are gaining share fastest.
End User:
Customer type stratification separates price-sensitive casual participants from credential-scrutinizing technical users driving sustainability certification demands.
- Serious Trekkers:Thru-hiker and long-distance trail communities prioritize tear strength-to-weight ratios and supply chain transparency. OEKO-TEX Standard 100 documentation now functions as baseline market access for REI and specialty retail procurement in Germany's Alpine regions and Pacific Northwest clusters.
- Mountaineers:Alpine climbing specialists demand ice axe loops, crampon patches, and reinforced haul points. PFC-free DWR alternatives demonstrate 30-40% durability degradation versus legacy C8 chemistry in independent abrasion testing, creating performance trade-offs.
- Casual Hikers:Weekend recreationists drive volume in sub-50L categories with lower suspension sophistication requirements.
- Campers:Basecamp-oriented users prioritize gear-hauling capacity over technical climbing features.
Serious trekkers anchor premium positioning. Mountaineers are rotating up the share rankings.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in technical outdoor equipment tilt toward manufacturing concentration in Southeast Asian processing hubs, while demand gravity pulls toward Alpine trekking corridors and dispersed camping regions in North America. Currency volatility in polymer feedstock sourcing is compressing margin buffers for brands without captive recycling infrastructure.
Germany
The Bavarian hut-to-hut trekking network sustains premium pack replacement cycles among thru-hiker communities. ECHA's REACH chemical restrictions tighten DWR coating thresholds, accelerating Bluesign certification adoption among Alpine outfitters. Manufacturing clusters around Munich and Nuremberg specialize in anatomical suspension R&D for load-distributing frame systems.
United States
Colorado's Front Range and Pacific Northwest trail running communities drive fastpacking crossover demand for sub-20L technical daypacks. EPA's emerging PFAS regulations extend compliance burdens to waterproof membrane formulations ahead of federal enforcement timelines. Seattle and Boulder host concentrated biomechanical testing facilities for load-lifter strap integration.
China
Extruded 7075-T6 aluminum frame-sheet sourcing clusters in Guangdong and Zhejiang provinces create supply concentration for expedition-grade manufacturers. The country's national environmental regulator advances dual carbon goals that pressure textile processors toward energy-intensive recycling lines. Shenzhen and Dongguan dominate laminated Cordura and ripstop nylon contract manufacturing.
France
Chamonix valley alpine climbing specialists prioritize ice axe loops and reinforced haul points in technical pack specifications. EU Green Deal textile strategy mandates reshape procurement criteria for PFC-free waterproofing across European distribution networks. Annecy and Grenoble anchor design centers for mountaineering-specific suspension architectures.
Japan
Kansai region outdoor retailers demand OEKO-TEX Standard 100 documentation as baseline shelf-access requirements for new pack introductions. METI standards influence durability testing protocols for Dyneema composite weaving applications. Osaka and Nagoya concentrate specialty retail networks scrutinizing supply chain credentials.
Hiking Backpacks Market Competitive Landscape
Listed leaders compete with private specialists across material science and channel access dimensions. The vendor base stratifies into three tiers: ultralight composite innovators, full-range suspension generalists, and cooperative retail captive brands. Strategic archetypes include Dyneema weaving patent-holders, anatomical R&D houses, and extended producer responsibility first-movers. Competitive moves concentrate on Bluesign certification acceleration and REI co-development exclusivity.
Within the ultralight composite tier, Hyperlite Mountain Gear and ULA Equipment exemplify sub-one-pound specification leadership. Osprey occupies a position bridging technical performance with mass-channel penetration. Gregory Packs and Deuter anchor the premium expedition segment through reinforced frame-sheet architectures. Arc'teryx and Rab represent the technical alpine specialization vector. Granite Gear sits within the heritage American manufacturing archetype, while REI Co-op exemplifies cooperative retail vertical integration into private-label technical equipment.
| Leading Market Players |
|---|
| Arcteryx |
| ULA Equipment |
| Osprey |
| Granite Gear |
| REI Co-op |
| Gregory Packs |
| Hyperlite Mountain Gear |
| Rab |
| Deuter |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day laminated fabric lead times from Southeast Asian processors compress margin buffers for brands without captive recycling infrastructure, concentrating pricing power among vertically integrated manufacturers with polymer feedstock control.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with Dyneema composite weaving expertise and Bluesign certification status driving price differentiation. Cost compression in the sub-20L daypack segment intensifies because trail running crossover demand attracts fashion-oriented entrants with lower suspension R&D overhead. Weekend warriors exhibit highest price sensitivity, while thru-hiker communities prioritize tear strength-to-weight ratios over unit cost.
Supply Chain Analysis
China and Vietnam anchor laminated Cordura and ripstop nylon contract manufacturing, with Guangdong and Zhejiang provinces hosting extruded 7075-T6 aluminum frame-sheet sourcing clusters. Post-consumer nylon feedstock supply rests on municipal collection infrastructure gaps in Southeast Asian processing hubs. Single-source vulnerability concentrates in Chinese smelting regions for expedition-grade manufacturers. Distribution runs through cooperative retail networks and specialty outdoor channels with OEKO-TEX documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hiking backpacks market tracks a cyclical recovery as thru-hiker community expansion in Alpine corridors sustains premium pack replacement cycles following pandemic-era inventory destocking.
For Market Incumbents: Consolidate frame-sheet aluminum supply through backward integration into Southeast Asian extrusion partnerships or long-term offtake agreements with Guangdong smelters. Accelerate Bluesign certification timelines to preempt ECHA's tightening DWR coating thresholds and defend shelf positioning against uncertified competitors. Prioritize anatomical suspension R&D investment in Bavarian and Colorado biomechanical testing clusters.
For New Entrants and Emerging Players: Differentiate on fastpacking crossover specifications for Colorado Front Range and Chamonix valley trail running communities, where sub-20L technical daypack demand outpaces incumbent development cycles. Target the casual hiker segment with recycled-content laminates and direct-to-consumer channels bypassing cooperative retail gatekeeping. Leverage PFC-free waterproofing as a sustainability positioning wedge against legacy C8 chemistry incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from heritage American manufacturing archetypes with established REI channel relationships but lagging Dyneema composite weaving capabilities. Long-term viability hinges on extended producer responsibility infrastructure readiness as EU Green Deal mandates mature. Watch for inflection signals in post-consumer polymer feedstock price stabilization across Southeast Asian collection hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluesign Certification Acceleration | ECHA's REACH restrictions position certified laminates for Alpine market access. |
| Backward Integration into Recycling | Captive post-consumer nylon processing hedges feedstock volatility in Vietnam. |
| Fastpacking Product Line Extension | Chamonix trail running communities drive sub-20L technical daypack specifications. |
| REI Co-Development Exclusivity | Cooperative retail partnerships secure volume-tier distribution for overnight segments. |
| PFC-Free DWR Reformulation | EPA emerging regulations extend compliance burdens to North American membrane formulations. |
Research Methodology
The analysis maps overnight packs, daypacks, expedition haulers, and hydration systems, each validated through product development directors at laminate manufacturers, procurement leads at cooperative retailers, biomechanical testing facility managers, and sustainability compliance officers. Primary interviews combined with secondary validation from ECHA regulatory filings, EPA docket records, customs trade data for polymer feedstocks, and OEKO-TEX certification databases. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment outputs.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled capacity bands, material credential tiers, user intensity segments, and regional regulatory clusters. CAGRs derived from segment-level growth rate synthesis and input-cost trajectory modeling. Industry-specific forecast inputs incorporated Dyneema composite adoption curves and REACH compliance timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained thru-hiker community expansion or abrupt ECHA enforcement acceleration would require recalibration. Forecasts reflect documented assumptions regarding polymer feedstock availability and cooperative retail procurement criteria stability. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and EPA PFAS regulatory finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Spain Sports Tourism Market