
 Outdoor Living Product Market | 2026-2036
Outdoor Living Product Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Living Product Market Insights
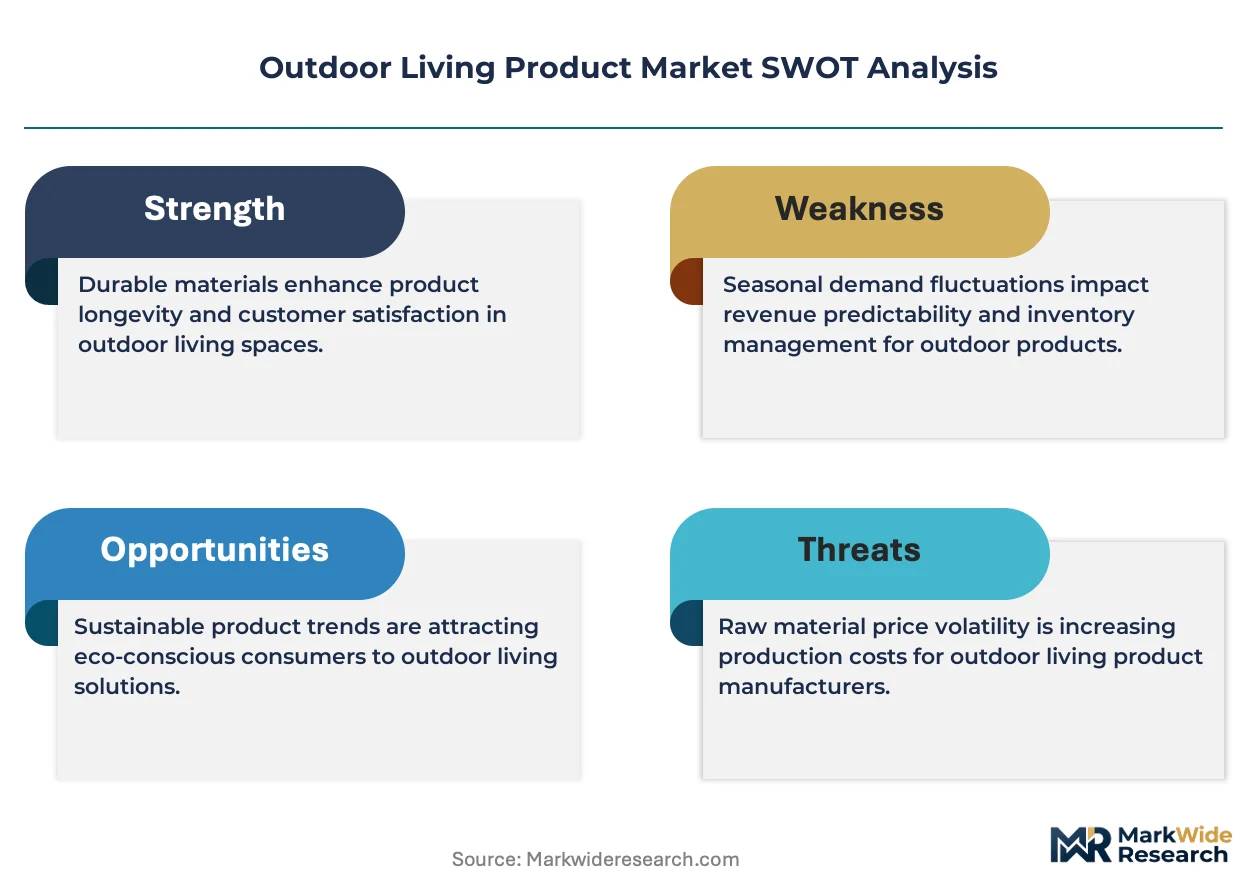
REACH compliance is consolidating the cost-of-entry calculus for European-sourced outdoor furniture, forcing smaller importers to absorb expensive third-party testing or exit the market entirely. Brown Jordan Inc. leverages its domestic manufacturing footprint to sidestep cross-border certification delays. Polywood LLC specializes in marine-grade recycled HD lumber formulations that bypass traditional wood treatment requirements. Renson Inc. anchors its position through integrated shading and ventilation systems that meet stringent Belgian building codes.
Outdoor living products encompass weather-resistant furnishings, cooking equipment, ambient illumination, and decorative accessories engineered for sustained exterior exposure, typically utilizing UV-stabilized polymers, powder-coated aluminum, or thermally modified timber rated for decay resistance. The primary commercial purpose centers on extending habitable square footage beyond structural walls while withstanding cyclic moisture, thermal expansion, and solar degradation. Furniture and grills command the largest revenue pools due to replacement cycles tied to housing turnover and entertainment-driven upgrades, while lighting is accelerating fastest as LED retrofit demand intersects with smart-home integration. The material split reveals plastic gaining ground against traditional wood as supply chains prioritize dimensional stability and lower maintenance profiles.
EPA oversees treated wood preservative registrations under FIFRA, while the EU F-Gas Regulation constrains refrigerant choices in outdoor kitchen appliances, and California's Proposition 65 mandates explicit labeling on metal finishes with detectable lead content. These frameworks collectively elevate compliance spending but also reward transparent supply chain documentation. Stakeholders must monitor evolving state-level chemical disclosure rules and decide whether to front-load certification costs or narrow geographic exposure.
Market Dynamics
Residential homeowners are expanding outdoor kitchens and entertainment zones, while EPA regulations on treated wood emissions push manufacturers toward alternative materials like marine-grade recycled HD lumber and thermally modified timber.
Growth Catalysts
- Sun Belt Housing Expansion:Extended outdoor seasons in the United States Sun Belt states drive replacement cycles for weather-resistant furnishings and cooking equipment. Residential turnover accelerates demand for upgraded outdoor entertainment infrastructure.
- REACH Compliance Barriers:European chemical testing mandates consolidate import channels, rewarding domestic manufacturers with established certification documentation. Smaller competitors absorb exit pressure from third-party laboratory costs.
- LED-Smart Home Convergence:Ambient illumination products integrate with connected home ecosystems, compressing replacement timelines and expanding addressable square footage beyond structural walls.
Market Restraints
- Treated Wood Preservative Restrictions:EPA FIFRA registrations constrain traditional lumber supply chains, forcing capital reallocation toward powder-coated aluminum and UV-stabilized polymer formulations.
- Refrigerant Chemistry Constraints:EU F-Gas Regulation limits compressor coolant options for outdoor kitchen appliances, complicating cross-border appliance sourcing and inventory planning.
- California Proposition 65 Labeling:Metal finish disclosure mandates create friction for distributors serving the United States West Coast, requiring segregated supply chains or universal compliance investments.
Strategic Opportunities
- Belgian Building Code Integration:Renson Inc. demonstrates pathway through combined shading and ventilation systems meeting stringent thermal performance standards, opening adjacent product categories.
- Marine-Grade Material Substitution:Recycled HD lumber formulations bypass wood treatment requirements entirely, capturing share from traditional timber in coastal and high-humidity installations.
- Smart-Home Channel Expansion:Lighting manufacturers bypass traditional retail through direct electrician and contractor relationships, capturing specification authority earlier in project timelines.
Industry Challenges
- Cross-Border Certification Delays:REACH documentation timelines extend European product launch cycles, requiring advance inventory positioning or domestic manufacturing investments.
- Dimensional Stability Expertise Gap:Polymer formulation chemistry and thermally modified timber processing demand specialized technical talent scarce in traditional furniture manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Living Product Market |
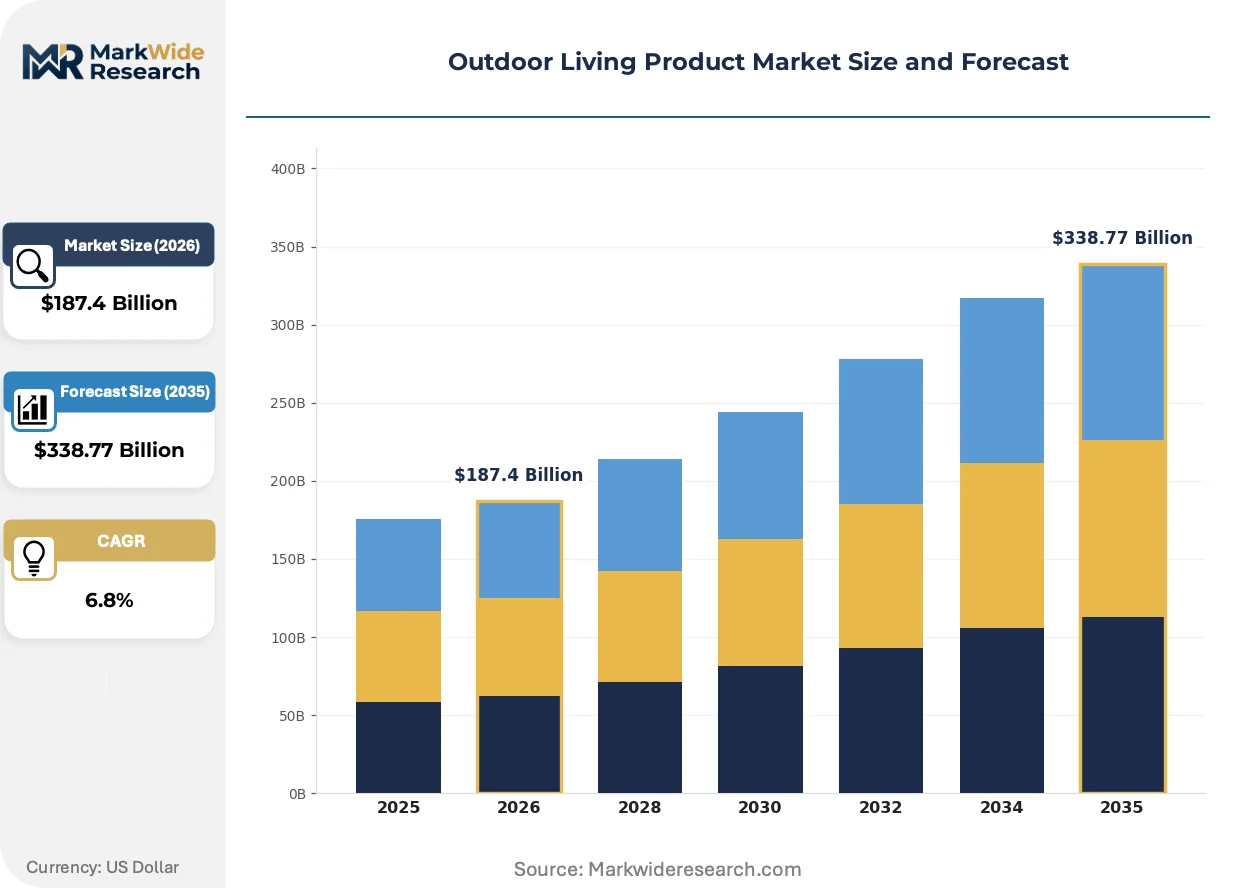
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Decor, Grills, Lighting Material: Wood, Metal, Plastic, Fabric End User: Homeowners, Businesses, Hotels, Resorts Distribution Channel: Retail Stores, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Absolute Outdoor Living, Renson Inc, Brown Jordan Inc., Barbeques Galore, Corradi, Scandia Canada Ltd., Luxos, Sunesta, Polywood LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Living Product Market Trends and Innovations
Material science advances and regulatory chemistry constraints are compressing traditional wood dominance while elevating engineered alternatives with lower maintenance profiles and explicit compliance documentation.
Marine-grade recycled HD lumber is integrating into structural outdoor furniture applications previously reserved for pressure-treated timber. Sun Belt residential contractors specify these formulations for dimensional stability in cyclic moisture environments. The technology is integrating specification authority away from traditional lumber distributors toward specialized polymer compounders.
EU F-Gas Regulation constrains hydrofluorocarbon refrigerant choices in outdoor kitchen appliance compressors. Manufacturers redesign cooling systems around approved alternatives or exit European distribution entirely. United States producers with domestic cooling circuit production capture share from importers facing re-engineering cost burdens.
Homeowner specification behavior now prioritizes connected lighting ecosystems over standalone fixture replacement. Electricians and smart-home integrators displace big-box retail as primary influence points in project planning. This channel rotation concentrates most visibly in United States metropolitan markets with high renovation activity and established contractor networks.
Outdoor Living Product Market Segmentation
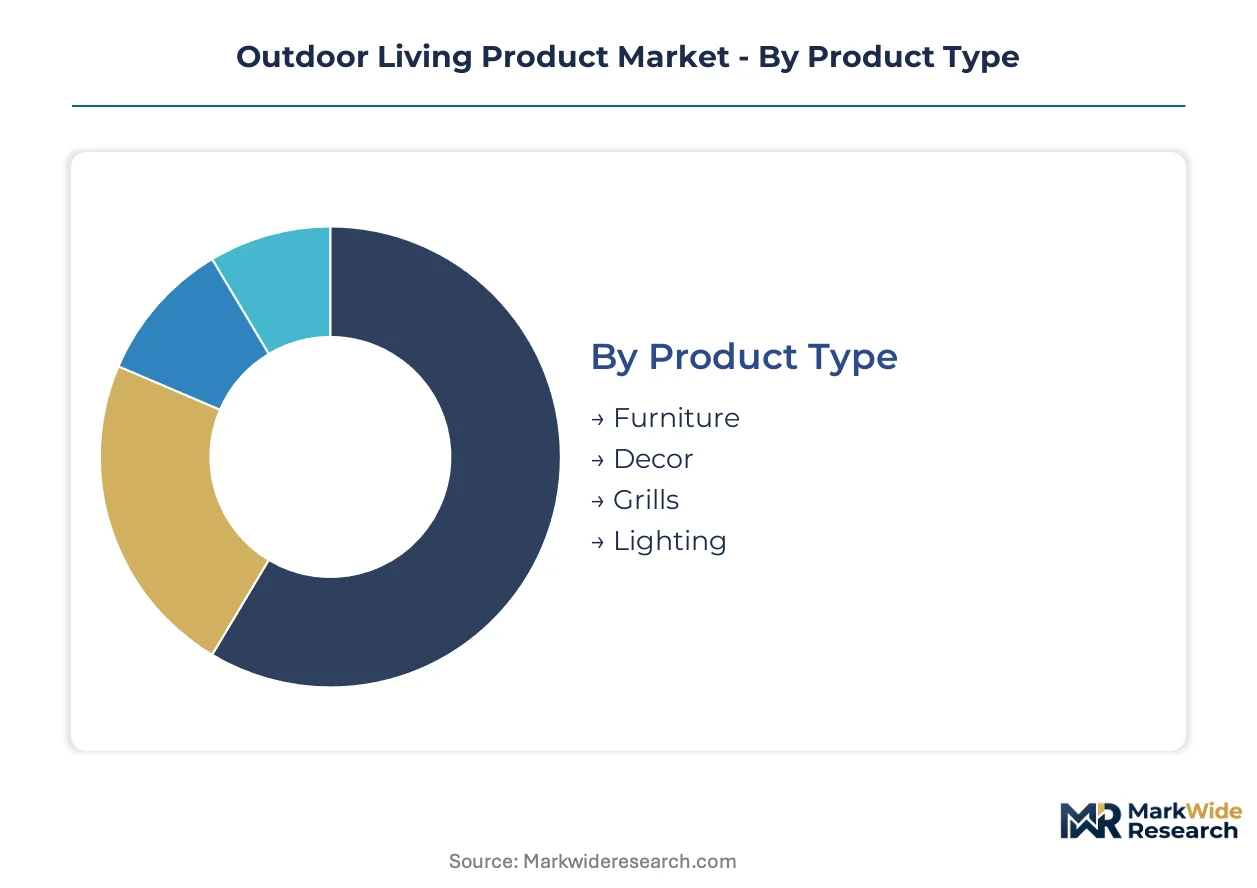
Segmentation in outdoor living products reveals how material substitution and channel rotation reshape competitive boundaries. Understanding where specification authority concentrates—whether through contractor networks, hospitality procurement, or direct-to-consumer platforms—determines which product configurations capture margin.
Product Type:
Furniture and grills anchor volume throughput, while lighting commands premium expansion as smart-home integration redefines replacement cycles.
- Furniture:Weather-resistant seating and dining configurations utilizing powder-coated aluminum frames, marine-grade recycled HD lumber, or thermally modified timber. Demand concentrates in United States Sun Belt states where extended outdoor seasons justify substantial entertainment infrastructure investments.
- Grills:Combustion and electric cooking equipment with stainless steel construction and integrated refrigeration modules. Hotels and resorts in Florida, Arizona, and Texas drive specification upgrades tied to guest experience differentiation and outdoor event programming.
- Decor:Accent pieces, planters, and ornamental accessories engineered for UV stability. Coastal installations favor synthetic wicker and resin formulations over organic materials.
- Lighting:Ambient illumination systems with LED retrofit compatibility and smart-home ecosystem integration. Electricians and contractors in high-renovation metropolitan markets displace retail as primary influence points.
Today's leader: Furniture. Tomorrow's challenger: Lighting.
Material:
Plastic compounds are gaining specification authority as EPA FIFRA constraints on traditional wood preservatives force reformulation across supply chains.
- Wood:Pressure-treated lumber faces regulatory headwinds from EPA preservative registrations under FIFRA. Thermally modified timber offers a compliant alternative for structural applications in high-humidity environments.
- Metal:Powder-coated aluminum dominates furniture frames and grill enclosures. California Proposition 65 labeling mandates on detectable lead content create supply chain friction for West Coast distributors.
- Plastic:Marine-grade recycled HD lumber formulations bypass wood treatment requirements entirely. Sun Belt residential contractors specify these compounds for dimensional stability in cyclic moisture conditions.
- Fabric:Solution-dyed acrylics and vinyl-coated polyester for upholstery and shade applications. Hospitality procurement in resort markets prioritizes fade resistance and rapid-dry properties.
Wood retains installed base dominance. Plastic climbs the fastest on specification momentum.
End User:
Homeowners drive replacement cycles through housing turnover, while hospitality procurement concentrates volume in seasonal destination markets.
- Homeowners:Residential property owners expanding outdoor kitchens and entertainment zones. United States Sun Belt housing expansion accelerates demand for upgraded weather-resistant infrastructure.
- Businesses:Corporate campus and restaurant patio installations. Procurement prioritizes durability warranties and maintenance cost minimization over initial acquisition price.
- Hotels:Mid-scale and luxury properties refreshing poolside and terrace amenities. Brand standards increasingly mandate sustainable material documentation.
- Resorts:Destination properties in coastal and desert climates. Specification authority resides with hospitality design firms rather than individual property managers.
Homeowners generate transaction velocity. Resorts concentrate average order value.
Distribution Channel:
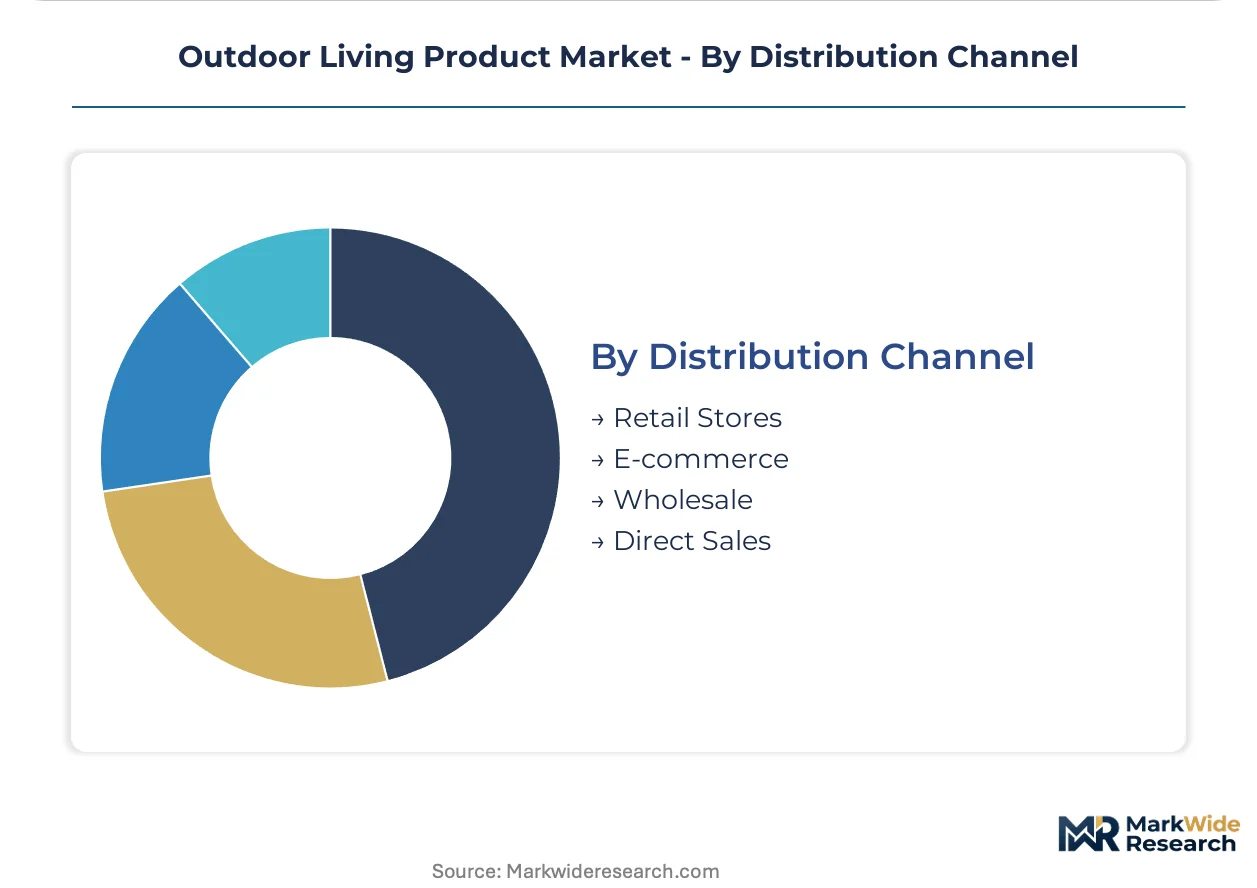
Channel influence is rotating toward specification professionals as project complexity and smart-home integration elevate technical consultation requirements.
- Retail Stores:Big-box and specialty outdoor retailers serving replacement and upgrade demand. Foot traffic depends on seasonal merchandising and localized climate patterns.
- E-commerce:Direct-to-consumer platforms capturing research-intensive purchases. Product content requirements include detailed material specifications and compliance documentation.
- Wholesale:Distributor networks supplying contractors and hospitality procurement. Inventory positioning must account for extended REACH documentation timelines for European-sourced products.
- Direct Sales:Manufacturer relationships with design-build firms and smart-home integrators. This channel captures specification authority earliest in residential renovation project timelines.
Retail holds transaction volume. Direct sales gain share fastest on project influence depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer compounders and thermally modified timber specialists anchor regional production clusters, with regulatory chemistry constraints reshaping where specification authority concentrates across manufacturing footprints.
United States
Residential contractors in Florida, Arizona, and Texas specify marine-grade recycled HD lumber for outdoor kitchens facing cyclic moisture exposure. EPA FIFRA registrations constrain pressure-treated wood supply chains, elevating alternative material demand. The Dallas-Fort Worth metroplex hosts concentrated fabrication capacity serving Sun Belt housing expansion.
Germany
Engineering-intensive manufacturers supply powder-coated aluminum framing systems to hospitality procurement across the European Union. ECHA REACH compliance documentation extends product launch cycles, rewarding domestic producers with established certification pathways. The North Rhine-Westphalia industrial corridor concentrates metal finishing and coating expertise.
Belgium
Integrated shading and ventilation specialists serve stringent building code requirements for thermal performance and energy efficiency. Belgian regional regulations mandate explicit documentation for exterior building envelope components. The Flanders region anchors research and development for climate-responsive outdoor living systems.
Canada
Timber-rich provinces face cross-border certification friction for treated wood exports to California markets. Health Canada PMRA oversight of wood preservatives parallels EPA constraints, accelerating domestic adoption of thermally modified alternatives. British Columbia's coastal fabrication clusters pivot toward marine-grade polymer formulations.
United Kingdom
Post-Brexit regulatory divergence complicates REACH-aligned supply chains for imported outdoor furnishings. Domestic manufacturers leverage UKCA marking requirements to consolidate specification authority in residential renovation markets. The Southeast England corridor concentrates design-build firms influencing early-stage project decisions.
Outdoor Living Product Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material science and distribution channel vectors. The vendor base stratifies into three tiers: domestic manufacturers with certification documentation advantages, specialized polymer compounders bypassing wood treatment requirements, and integrated system providers combining shading with ventilation. Consolidation pressure concentrates among smaller importers absorbing REACH testing costs. Dominant competitive moves include backward integration into polymer formulation and direct channel expansion toward electricians and contractors.
Within the domestic manufacturing tier, Brown Jordan Inc. and Polywood LLC exemplify divergent specialization strategies. Renson Inc. anchors the integrated systems archetype through Belgian regulatory alignment. These three occupy positions across the competitive spectrum without overlapping material or channel focus.
| Leading Market Players |
|---|
| Absolute Outdoor Living |
| Renson Inc |
| Brown Jordan Inc. |
| Barbeques Galore |
| Corradi |
| Scandia Canada Ltd. |
| Luxos |
| Sunesta |
| Polywood LLC |
| Others |
Pricing and Supply Chain Analysis
Specialized polymer compounders in the United States Sun Belt command wage premiums that compress pricing spreads between premium marine-grade recycled HD lumber and standard thermally modified timber tiers. Labor-cost differentials between domestic formulation specialists and imported European metal finishers create tiered entry points for residential contractors versus hospitality procurement.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based contractor specifications from retail replacement purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification documentation depth and after-sales installation support. Pricing pressure stems from REACH compliance cost absorption among smaller European importers. Residential homeowners exhibit highest price sensitivity, while resort hospitality procurement prioritizes total cost of ownership over initial acquisition.
Supply Chain Analysis
Direct-to-contractor channels handle specification-intensive demand from Sun Belt residential developers and hospitality design firms. Raw material sourcing concentrates on United States polymer compounders, Belgian integrated systems specialists, and German powder-coated aluminum fabricators. Formulation chemistry for marine-grade recycled HD lumber, thermally modified timber processing, and UV-stabilized polymer additives constitute critical input dependencies. Single-source vulnerability sits with specialized polymer compounders serving coastal moisture applications. Distribution runs through wholesale distributor networks, direct manufacturer relationships with design-build firms, and e-commerce platforms for research-intensive consumer purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Outdoor Living Product Market functions as a stable compounder. Sun Belt housing turnover generates predictable replacement cycles for weather-resistant infrastructure across residential and hospitality segments.
For Market Incumbents: Lock in specification authority through backward integration into polymer formulation chemistry and captive supply of marine-grade recycled HD lumber. Threats from REACH-compliant European competitors necessitate domestic certification documentation investments. Channel control through direct electrician and contractor relationships secures early-stage project influence. For New Entrants and Emerging Players: The price-point gap between premium smart-home-integrated lighting and economy standalone fixtures offers entry leverage. Mid-scale hospitality properties in secondary Sun Belt markets present the most penetrable segment. A go-to-market angle through smart-home integrator partnerships bypasses established retail shelf competition. For Investors and Strategic Acquirers: Building materials conglomerates with outdoor living divisions are the most active acquirer in this space. The five-to-ten year viability window favors targets with established EPA FIFRA documentation and domestic manufacturing footprints. Acquisition target archetype: specialized polymer compounders with marine-grade formulation patents. The signal to watch is consolidation pressure among REACH-burdened European importers exiting United States distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive supply of marine-grade recycled HD lumber bypasses EPA FIFRA wood treatment constraints entirely. |
| Direct Contractor Channel Expansion | Electrician and smart-home integrator relationships displace big-box retail in specification authority. |
| REACH Compliance Documentation Investment | Third-party laboratory certification creates cost-of-entry barriers protecting domestic manufacturers from European import competition. |
| Belgian Building Code Alignment | Integrated shading and ventilation systems open adjacent product categories in stringent thermal performance markets. |
| Marine-Grade Material Substitution Program | Recycled HD lumber formulations capture share from pressure-treated timber in coastal high-humidity installations. |
Research Methodology
Coverage spans the United States Sun Belt, Germany, Belgium, Canada, and the United Kingdom, with primary inputs from each regional cluster. The analysis combines primary interviews with residential contractors, hospitality procurement managers, polymer formulation chemists, smart-home integrators, and regulatory compliance officers with secondary validation. Secondary sources include EPA FIFRA registration databases, ECHA REACH compliance documentation, customs trade records, and SEC filings from publicly traded building materials conglomerates. Bottom-up demand modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product type, material composition, end-user category, and distribution channel complexity. CAGRs derive from housing turnover velocity, replacement cycle compression from smart-home integration, and regulatory-driven material substitution rates. Industry-specific forecast inputs include Sun Belt residential construction permits and hospitality capital expenditure intentions.
Caveats apply where EPA FIFRA registration delays, REACH documentation timeline extensions, or California Proposition 65 enforcement shifts could materially shift the outlook. Forecasts reflect assumptions about housing turnover stability and regulatory chemistry constraint continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Spain Artificial Turf Market