
 North America Spectator Sports Market | 2026-2036
North America Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spectator Sports Market Insights
Private equity and sovereign wealth fund participation is fragmenting capital access across North American spectator sports, allowing non-traditional owners to acquire franchise stakes previously reserved for ultra-high-net-worth individuals. The National Football League sustains the largest broadcast rights revenue base through its centralized media strategy. Major League Baseball competes through regional sports network partnerships that preserve local market leverage. The National Basketball Association differentiates via international digital streaming expansion that extends brand reach beyond arena footprints.
North America spectator sports encompass organized athletic competitions designed for live and remote viewership, incorporating venue infrastructure, media distribution systems, and commercial licensing frameworks that monetize audience attention through multiple consumption channels. The sector operates through professional leagues, collegiate athletic conferences, and amateur federations that coordinate scheduling, competitive rules, and revenue allocation across participating entities. Broadcast rights command the dominant revenue share within professional team structures, while college athletics increasingly monetize name-image-likeness frameworks alongside traditional ticket sales. Fantasy leagues and membership programs represent the fastest-expanding fan engagement segment, driven by real-time data integration and personalized content delivery platforms.
The Federal Communications Commission shapes media access through broadcast licensing and anti-siphoning rules that protect free-to-air distribution of marquee events, while state gaming commissions across multiple jurisdictions regulate the sports betting expansion that now funds stadium development and team marketing budgets. Canada's Competition Bureau and the US Federal Trade Commission both scrutinize league media consolidation and ticketing platform integration for anti-competitive effects. Stakeholders must monitor how emerging state gambling tax structures and potential federal privacy legislation reshape fan data monetization strategies.
Market Dynamics
Sports betting legalization is fragmenting revenue concentration across state jurisdictions, forcing leagues to rebuild media and data licensing frameworks around gambling-integrated fan experiences rather than traditional broadcast exclusivity.
Growth Catalysts
- State Gaming Commission Expansion:Post-PASPA regulatory openings across multiple US states create new stadium financing mechanisms through dedicated sports wagering tax revenue streams.
- Collegiate NIL Frameworks:Name-image-likeness monetization at NCAA member institutions transforms amateur athletics into talent development pipelines with direct commercial value extraction.
- Texas and California Metropolitan Corridors:Population density in Dallas-Fort Worth, Houston, Los Angeles, and San Francisco Bay Area concentrates disposable entertainment expenditure and corporate hospitality demand.
Market Restraints
- Regional Sports Network Collapse:Diamond Sports Group bankruptcy proceedings expose professional baseball and hockey franchises to local media revenue volatility and carriage negotiation fragility.
- FCC Anti-Siphoning Rules:Federal Communications Commission broadcast licensing protections limit paywall penetration for marquee events, constraining direct-to-consumer subscription pricing power.
- Franchise Valuation Concentration:Private equity and sovereign wealth fund capital accumulation in NFL and NBA team acquisitions reduces ownership liquidity and raises entry barriers for local investor groups.
Strategic Opportunities
- Canadian Sports Betting Harmonization:Provincial lottery corporations in Ontario, Quebec, and British Columbia present integrated single-game wagering platforms with established regulatory infrastructure.
- Immersive Venue Technology Convergence:Augmented reality overlays combined with real-time biometric player data create premium in-arena experiences that justify ticket price elevation.
- International Digital Streaming:National Basketball Association direct-to-consumer international expansion bypasses traditional broadcast intermediaries in European and Asian growth markets.
Industry Challenges
- Data Rights Fragmentation:League-level official data licensing conflicts with team-level direct partnerships complicate sportsbook and fantasy platform integration timelines.
- Ticketing Platform Monopolization:Department of Justice and Federal Trade Commission antitrust scrutiny of vertical integration between primary and secondary ticket marketplaces creates operational uncertainty for venue operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spectator Sports Market |
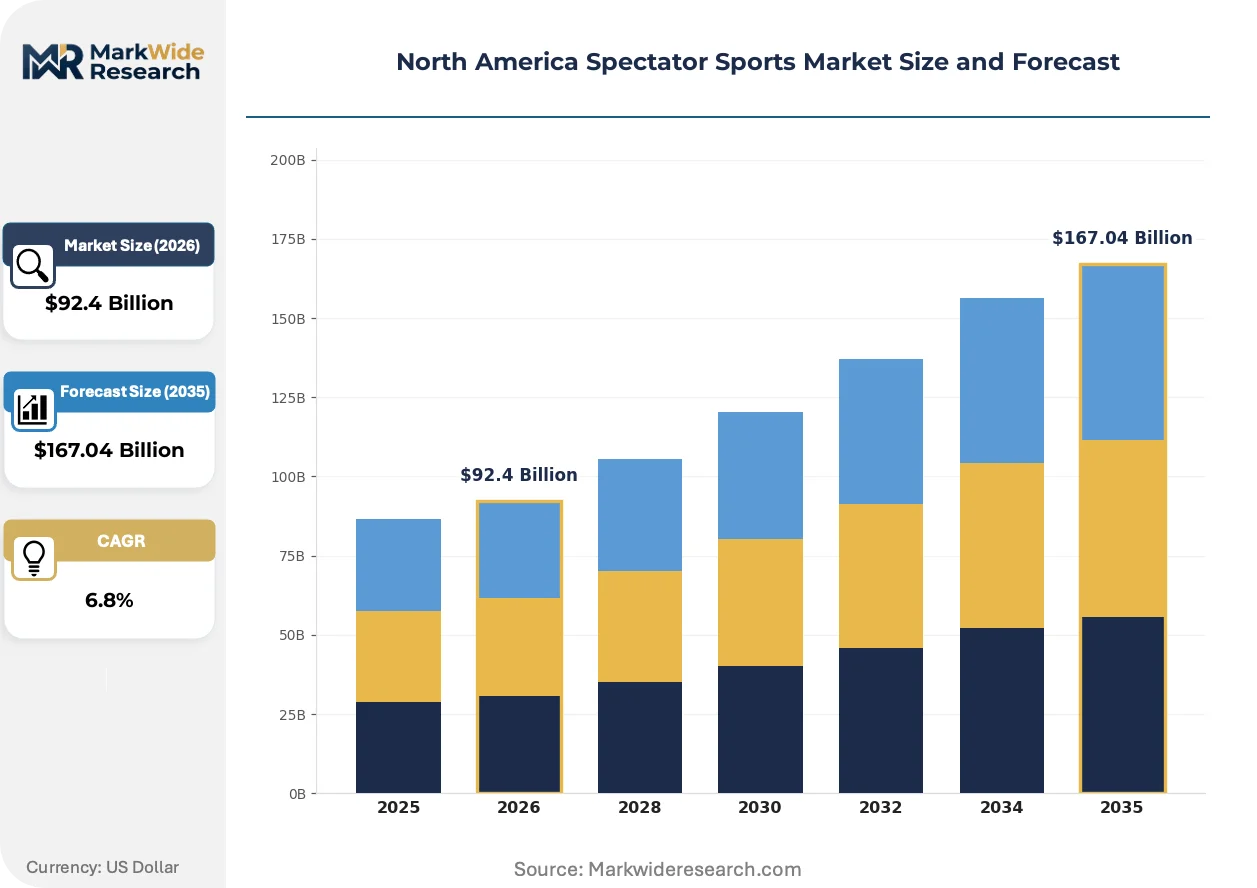
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Football, Basketball, Baseball, Hockey Team Structure: Professional, College, Amateur, Semi-Professional Revenue Stream: Ticket Sales, Sponsorship, Merchandise, Broadcast Rights Fan Engagement: Membership Programs, Fantasy Leagues, Social Media Interaction, Events |
| Companies Covered | National Football League (NFL), National Basketball Association (NBA), Major League Baseball (MLB), National Hockey League (NHL), Major League Soccer (MLS), Cleveland Browns, Austin FC, BC Lions, CF Montreal, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spectator Sports Market Trends and Innovations
Real-time wagering integration is compressing the gap between live athletic competition and transactional fan engagement, requiring infrastructure investment in latency-sensitive data distribution and in-venue mobile connectivity.
Edge computing deployment for instant replay and officiating review is hybridizing broadcast production with gambling-grade data verification, reducing decision latency from seconds to milliseconds. Sportsbook operators and league technology partners are co-investing in sub-second data transmission infrastructure. This compression is enabling in-play micro-betting markets that were technically impossible under previous satellite-reliant distribution architectures.
The US Federal Trade Commission and state attorneys general are intensifying merger review of regional sports network consolidation, examining how Sinclair Broadcast Group and other holders of local team rights extract carriage fees from competing streaming distributors. Cable television subscriber attrition is accelerating the shift to direct-to-consumer league applications. Franchises in smaller designated market areas face disproportionate revenue exposure from this structural transition.
Fan membership programs are displacing season-ticket hierarchies as the primary loyalty mechanism, with personalized content feeds and exclusive digital access replacing traditional seat-based tenure systems. National Football League clubs and Major League Soccer franchises are piloting subscription models that decouple game attendance from premium status recognition. This behavioral shift is most pronounced in Pacific Coast markets where technology sector employment patterns favor flexible consumption over fixed-schedule commitment.
North America Spectator Sports Market Segmentation
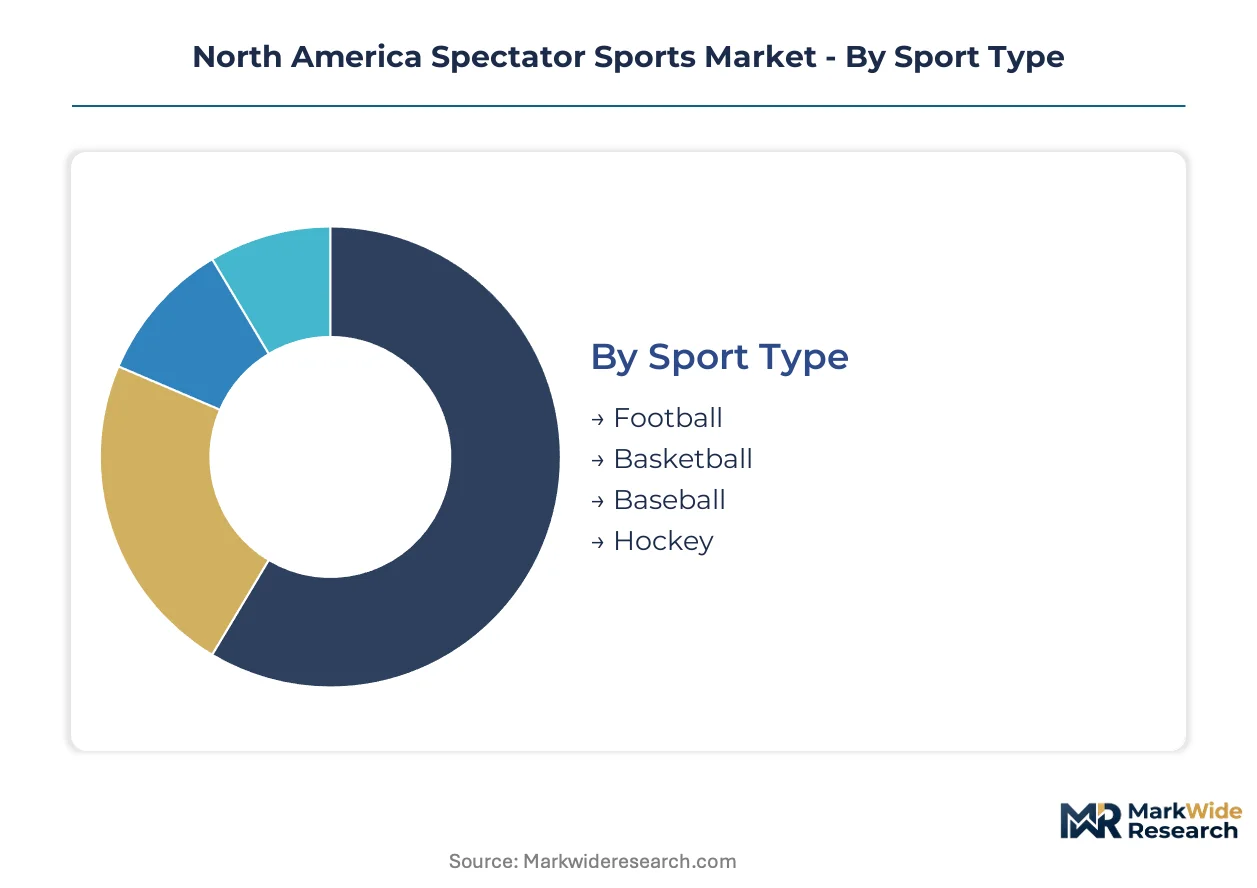
Spectator sports monetization varies dramatically across consumption formats, with each segment demanding distinct infrastructure investment and partnership structures. Revenue allocation patterns differ between live venue experiences and distributed media consumption, requiring tailored operational frameworks for each category.
Sport Type:
After-sales service intensity peaks in football and basketball, where stadium infrastructure requires continuous technology upgrades and fan experience optimization to maintain premium pricing power.
- Football:Gridiron competitions operate through centralized league structures that negotiate collective broadcast agreements and revenue-sharing mechanisms. NFL franchises in Dallas-Fort Worth and Houston metropolitan corridors extract maximum corporate hospitality expenditure through luxury suite inventories and founding partner programs.
- Basketball:Indoor arena formats enable year-round venue utilization through concert and event scheduling that subsidizes basketball-specific capital costs. NBA organizations leverage international digital streaming expansion to bypass traditional broadcast intermediaries in European and Asian growth markets.
- Baseball:162-game schedules create inventory abundance that pressures per-game pricing through regional sports network dependency.
- Hockey:Cold-weather geographic concentration in Northeast and Upper Midwest markets limits national media appeal despite strong local season-ticket loyalty.
Football holds the largest share; momentum sits with basketball.
Team Structure:
Cost tier differentiation separates professional operations with nine-figure payrolls from amateur federations surviving on volunteer labor and municipal subsidies.
- Professional:Labor market structures feature collective bargaining agreements that cap player compensation while guaranteeing revenue splits. Private equity and sovereign wealth fund accumulation in NFL and NBA franchise acquisitions has reduced ownership liquidity and raised entry barriers for local investor groups.
- College:NCAA member institutions now monetize name-image-likeness frameworks that transform amateur athletics into talent development pipelines with direct commercial value extraction. Texas and California universities lead NIL deal volume through alumni network density and media market exposure.
- Amateur:Youth and recreational leagues depend on municipal field allocations and volunteer coaching infrastructure with minimal commercial revenue generation.
- Semi-Professional:Minor league baseball and independent football leagues operate on thin margins requiring stadium subsidies and broadcast revenue sharing from affiliated major league organizations.
Professional operations dominate revenue concentration; college athletics are expanding most quickly through NIL monetization.
Revenue Stream:
Application-specific monetization models range from per-transaction ticket sales to long-term broadcast rights contracts with decade-long durations.
- Broadcast Rights:NFL centralized media strategy sustains the largest revenue base through exclusive network agreements that limit direct-to-consumer fragmentation. FCC anti-siphoning rules constrain paywall penetration for marquee events, limiting subscription pricing power despite cable subscriber attrition.
- Sponsorship:Naming rights and jersey patch inventory command premium valuations in Texas and California metropolitan corridors where technology sector marketing budgets concentrate. Real-time wagering integration is compressing the gap between live competition and transactional fan engagement.
- Ticket Sales:Dynamic pricing algorithms optimize yield per seat across variable demand schedules.
- Merchandise:E-commerce fulfillment and licensed apparel distribution extend brand reach beyond geographic market boundaries.
Broadcast rights hold the largest share; momentum sits with sponsorship as sports betting legalization creates new inventory categories.
Fan Engagement:
Customer type stratification separates committed season-ticket holders from casual digital participants with vastly different lifetime value profiles.
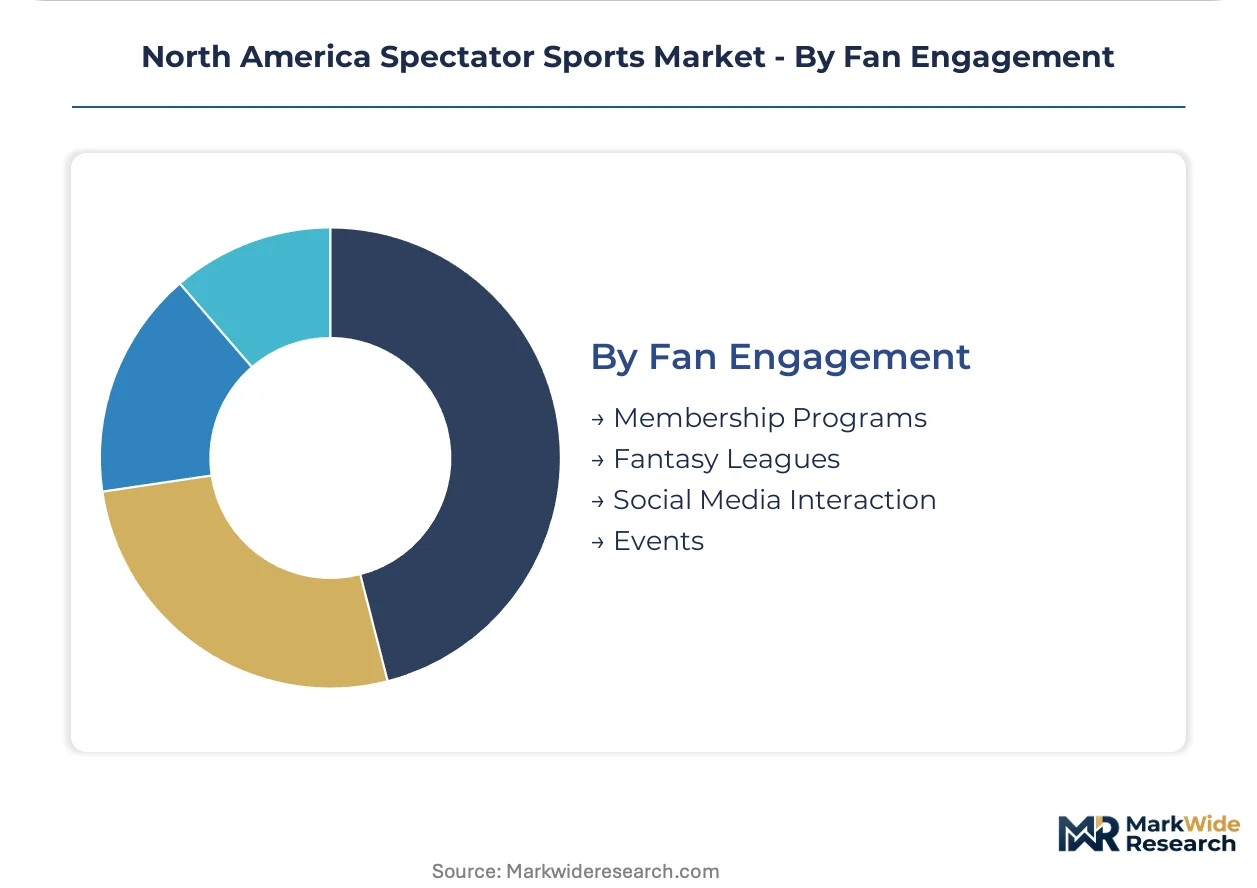
- Membership Programs:Subscription models decouple game attendance from premium status recognition, replacing traditional seat-based tenure systems with personalized content feeds and exclusive digital access. NFL clubs and Major League Soccer franchises pilot these structures most aggressively in Pacific Coast technology employment markets.
- Fantasy Leagues:Real-time data integration and personalized content delivery platforms represent the fastest-expanding engagement segment. Data rights fragmentation between league-level official licensing and team-level direct partnerships complicates sportsbook integration timelines.
- Social Media Interaction:Short-form content distribution builds brand awareness among demographics unlikely to purchase traditional media packages.
- Events:Pre-game festivals and alumni gatherings monetize non-ticketed fan gatherings through concession and merchandise capture.
Membership programs hold the largest share; fantasy leagues are gaining share fastest through wagering integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and California metropolitan corridors while Canadian markets operate under provincial lottery frameworks that constrain revenue velocity. The United States sustains the dominant valuation premiums through franchise scarcity and media rights inflation. Mexico's emerging professional infrastructure captures cross-border fan engagement and sponsorship arbitrage.
United States
Texas and California metropolitan corridors generate the highest per-capita entertainment expenditure through corporate hospitality demand and technology sector marketing budgets. The Federal Communications Commission enforces anti-siphoning rules that protect free-to-air broadcast access for marquee events. Dallas-Fort Worth and Houston NFL franchises maximize luxury suite yields through founding partner programs and real estate-integrated stadium developments.
Canada
Ontario, Quebec, and British Columbia present harmonized single-game wagering platforms through provincial lottery corporations with established regulatory infrastructure. The Competition Bureau scrutinizes league media consolidation and ticketing platform integration for anti-competitive effects. Toronto and Vancouver anchor the national broadcast rights valuation through hockey-centric viewership concentration and multicultural soccer expansion.
Mexico
Mexico City metropolitan area and northern border states capture US cross-border fan travel and sponsorship arbitrage from multinational brand activation. The federal gaming regulator oversees emerging sports betting frameworks that remain less developed than US state-level openings. Monterrey and Guadalajara host Liga MX franchises with stadium infrastructure capable of hosting international exhibition matches and CONCACAF tournament fixtures.
North America Spectator Sports Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in venue technology and data infrastructure. The North America spectator sports market consolidates around five major league organizations that control collective bargaining, media rights, and franchise expansion protocols. Three strategic archetypes dominate: centralized league platforms, regional franchise operators, and technology-enabled venue managers. Competitive intensity manifests through media rights auction escalation and sports betting partnership exclusivity contests.
Among centralized league platforms, the National Football League and National Basketball Association exemplify the media rights maximization archetype through centralized negotiation strategies. The National Football League sustains the largest broadcast revenue base through exclusive network agreements that limit direct-to-consumer fragmentation. The National Basketball Association occupies a position emphasizing international digital streaming expansion that bypasses traditional broadcast intermediaries in European and Asian growth markets.
| Leading Market Players |
|---|
| National Football League (NFL) |
| National Basketball Association (NBA) |
| Major League Baseball (MLB) |
| National Hockey League (NHL) |
| Major League Soccer (MLS) |
| Cleveland Browns |
| Austin FC |
| BC Lions |
| CF Montreal |
| Others |
Pricing and Supply Chain Analysis
Broadcast rights concentration in the United States determines where margin pools accumulate across North American spectator sports, with NFL centralized media negotiations extracting maximum value from network exclusivity while regional sports network fragility erodes pricing power in baseball and hockey markets.
Pricing Analysis
Configured-to-order premium experiences command substantial markups over standard ticket inventory, with NFL luxury suites and NBA courtside seats pricing at multiples of upper-bowl general admission. Three-tier pricing structure across premium, standard, and economy levels stratifies fan segments by disposable entertainment expenditure and corporate hospitality budgets. Cost compression in mid-tier seating is intensifying because dynamic pricing algorithms optimize yield per seat across variable demand schedules. Casual digital participants exhibit highest price sensitivity, while committed season-ticket holders and corporate founding partners demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from venue technology integrators and sportsbook operators now stretch 90-120 days, compressing working capital for regional franchise operators and mid-tier suppliers. Manufacturing concentrates in the United States, Mexico, and Canada for stadium infrastructure components, with specialty display systems and biometric sensors drawing from Asian component suppliers. Raw material dependencies span aluminum extrusions for seating systems, LED display substrates, and fiber-optic transmission hardware. Single-source vulnerability in real-time data distribution networks creates operational exposure for in-play wagering integration. Distribution runs through league-sanctioned technology partners and primary ticketing platforms with exclusive venue contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in latency-sensitive data infrastructure and gambling-grade verification systems constrains competitive entry, privileging organizations with captive technology development or exclusive league partnerships.
For Market Incumbents: Harden data rights positioning through exclusive league-level official data licensing that preempts team-level fragmentation threatening sportsbook integration timelines. Deepen backward integration into edge computing infrastructure for instant replay and officiating verification, reducing dependency on third-party transmission vendors. Capacity addition in Texas and California metropolitan corridors captures maximum corporate hospitality yield through real estate-integrated stadium developments. For New Entrants and Emerging Players: Pursue Canadian provincial lottery harmonization opportunities where Ontario, Quebec, and British Columbia present integrated single-game wagering platforms with established regulatory infrastructure. White-space exists in immersive venue technology convergence, specifically augmented reality overlays combined with real-time biometric player data for premium in-arena experiences. Technology sector employment markets on the Pacific Coast favor flexible membership programs over fixed-schedule season tickets, enabling subscription-based go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional sports network operators and distressed stadium infrastructure funds seeking liquidity from Diamond Sports Group bankruptcy exposure. Long-term viability across the projection horizon hinges on gambling revenue integration and direct-to-consumer streaming transition completion. Monitor FCC anti-siphoning rule enforcement intensity and state gaming commission tax structure evolution as inflection indicators for media rights valuation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Venue Technology Deployment | Augmented reality overlays with biometric data create premium experiences justifying ticket price elevation in Dallas-Fort Worth and Houston markets. |
| International Digital Streaming Expansion | NBA direct-to-consumer platforms bypass traditional broadcast intermediaries in European and Asian growth markets. |
| Canadian Sports Betting Harmonization | Provincial lottery corporations in Ontario and British Columbia offer integrated wagering with established regulatory infrastructure. |
| Data Rights Consolidation | League-level official data licensing prevents team-level fragmentation that complicates sportsbook integration timelines. |
| Membership Program Piloting | NFL clubs and Major League Soccer franchises test subscription models decoupling attendance from premium status in Pacific Coast technology markets. |
Research Methodology
Desk research of league financial disclosures, FCC regulatory filings, and state gaming commission proceedings preceded structured interviews with league revenue officers, stadium operations directors, sportsbook platform engineers, regional sports network executives, and collegiate athletic administrators. Secondary validation drew from SEC 10-K filings of publicly traded venue technology providers, Canadian Competition Bureau merger review documents, and US Federal Trade Commission antitrust scrutiny records. Bottom-up franchise-level revenue modeling triangulated against top-down league aggregate disclosures.
Assumption sets held fixed the current state-level sports betting regulatory patchwork and existing FCC anti-siphoning enforcement posture while varying international digital streaming adoption rates and regional sports network restructuring outcomes. Segmentation dimensions modeled across the analysis window encompassed sport type, team structure, revenue stream category, and fan engagement format alongside metropolitan corridor population density and corporate hospitality demand concentration. CAGRs were derived from revenue trajectory analysis incorporating broadcast rights inflation, NIL monetization expansion, and wagering tax revenue allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in disposable entertainment expenditure, technology sector employment patterns, or interest rate environments affecting private equity acquisition capacity would shift the trajectory. Forecasts incorporate documented assumptions regarding regulatory stability and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market