
 Global Personal Watercraft Market | 2026-2036
Global Personal Watercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Watercraft Market Foresight
The EU Green Deal is broadening compliance obligations for combustion-engine watercraft across European marinas and leisure ports. Yamaha Motor Co., Ltd. anchors its position through four-stroke engine leadership and extensive coastal dealer networks. BRP Inc. leverages vertical integration from powertrain to hull manufacturing. Taiga Motors differentiates through dedicated electric watercraft R&D and battery system specialization.
Personal watercraft are motorized vessels typically under four meters in length, powered by inboard jet drives generating thrust through water impellers rather than external propellers, designed for one to three riders across recreational, sporting, and utility functions. Sit-down configurations dominate volume sales due to family accessibility and stability, while electric engine types represent the fastest-growing segment as lithium-ion energy density improves and marina charging infrastructure spreads. Rental companies constitute the most concentrated customer type for fleet procurement, though individual consumers sustain the highest per-unit margin pools through premium sport and utility specifications.
The EPA enforces marine emissions standards under the Clean Air Act that constrain two-stroke engine sales and push manufacturers toward four-stroke and electric alternatives. The EU's F-Gas Regulation and REACH framework impose additional material and refrigerant restrictions on European-sold units. The International Organization for Standardization (ISO) 13590 standard governs personal watercraft construction and stability testing for type certification. Stakeholders must monitor battery safety certification progress and marina electrification timelines to calibrate product portfolio transitions.
Market Dynamics
EPA marine emissions enforcement under the Clean Air Act is compressing two-stroke engine viability while accelerating four-stroke and electric powertrain transitions across manufacturer portfolios.
Growth Catalysts
- EU Green Deal marina electrification mandates:European leisure ports face expanding compliance obligations that favor zero-emission watercraft procurement.
- Lithium-ion energy density improvements:Battery chemistry advances are extending electric personal watercraft range toward practical recreational thresholds.
- Coastal tourism corridor rental concentration:Fleet operators across Florida, California, and Mediterranean destinations are consolidating procurement volumes.
Market Restraints
- Marina charging infrastructure gaps:Electrification timelines lag electric watercraft availability, constraining adoption in secondary coastal markets.
- Four-stroke engine cost premiums:Compliance-driven powertrain shifts elevate unit economics versus legacy two-stroke alternatives.
- Jet drive impeller manufacturing concentration:Precision casting capabilities cluster with specialized marine component suppliers.
Strategic Opportunities
- Battery system specialization:Dedicated marine battery pack engineering offers differentiation as automotive-derived solutions prove inadequate.
- Utility function expansion:Search-and-rescue and patrol applications present fleet procurement channels beyond recreational buyers.
- ISO 13590 certification acceleration:Streamlined type certification processes enable faster product cycles for compliant manufacturers.
Industry Challenges
- Marine electric propulsion engineering talent scarcity:Specialized skill sets spanning hydrodynamics and battery thermal management command premium compensation.
- Dual powertrain platform development costs:Simultaneous four-stroke refinement and electric architecture investment strains R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Watercraft Market |
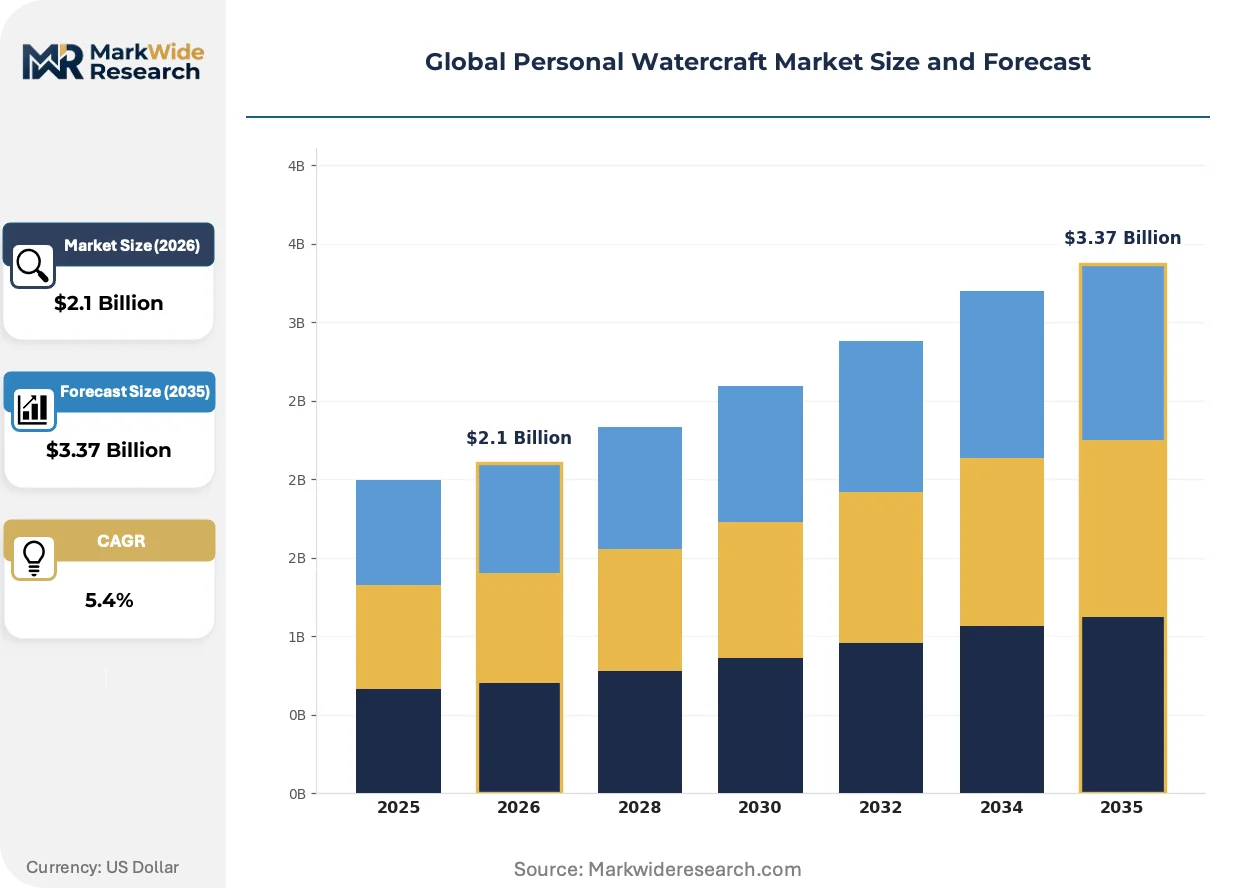
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up, Sit-down, Recreational, Sport, Utility Engine Type: Two-Stroke, Four-Stroke, Electric, Hybrid Application: Leisure, Racing, Rescue Operations, Rental Services, Training Customer Type: Individual Consumers, Rental Companies, Sports Clubs, Training Academies |
| Companies Covered | BRP Inc., Yamaha Motor Co., Ltd., Kawasaki Heavy Industries, Ltd., Polaris Inc., Honda Motor Co., Ltd., Taiga Motors, Belassi GmbH, Krash Industries, Gibbs Sports Amphibians Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Watercraft Market Shifts & Advancements
Powertrain electrification and regulatory emissions compression are restructuring competitive capabilities across hull design, battery integration, and marina ecosystem alignment.
High-density lithium-ion battery packs with marine-grade thermal management are rewriting range and performance expectations for electric personal watercraft. Rental fleet operators in Florida and California are piloting these systems for daily commercial duty cycles. The technology is compressing the performance gap between electric and combustion alternatives in recreational applications.
REACH framework substance restrictions and EU F-Gas Regulation refrigerant constraints are reshaping material selection and cooling system design for European-market units. Manufacturers must reformulate hull composites and sealing compounds to maintain compliance. Sit-down family configurations face the tightest reformulation timelines due to higher sales volumes in regulated markets.
Outcome-based fleet management contracts are displacing traditional unit sales for rental operators along coastal tourism corridors. Procurement now bundles watercraft, maintenance, and charging infrastructure as integrated service agreements. This pattern concentrates most visibly across Mediterranean marina networks and Great Lakes recreational clusters.
Global Personal Watercraft Market Segmentation
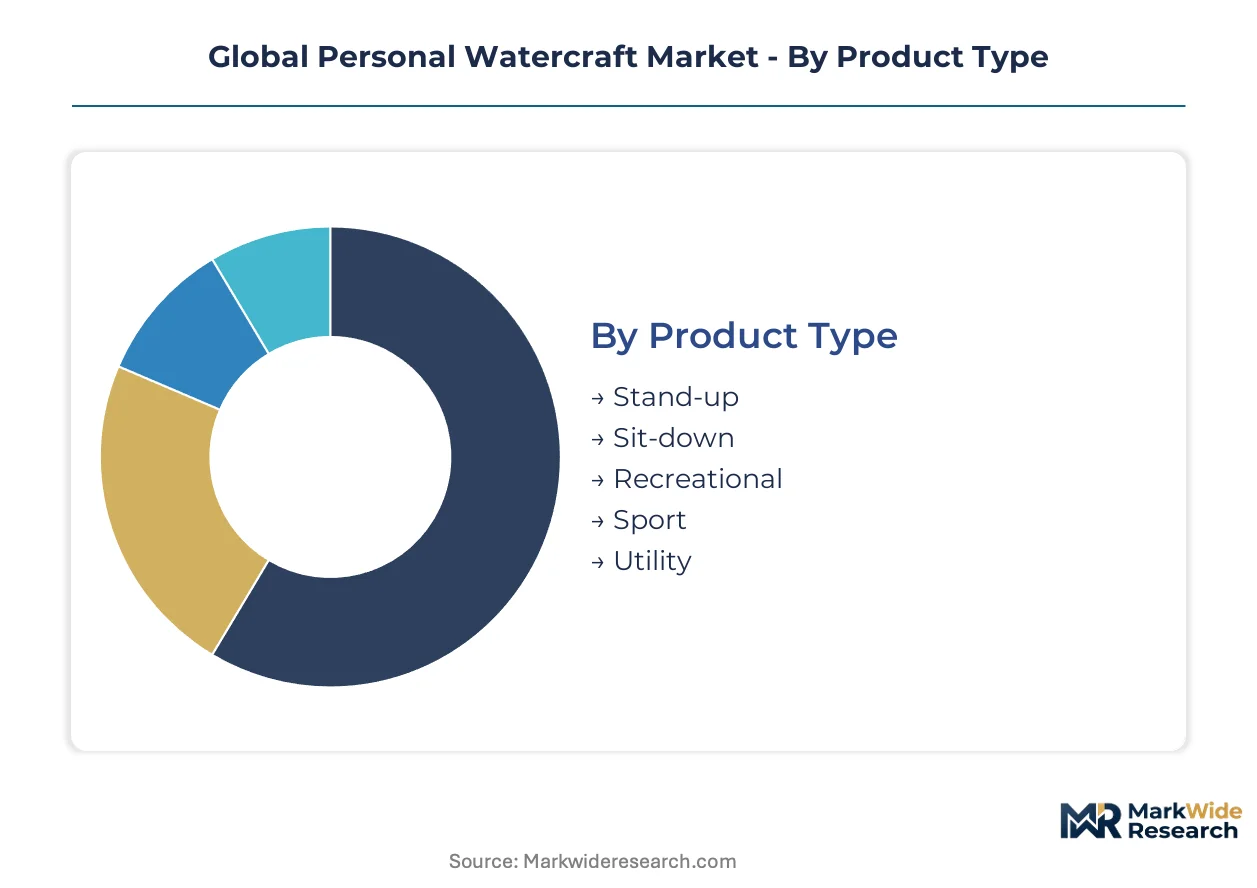
Personal watercraft segmentation reveals distinct procurement patterns across recreational, commercial, and institutional buyers. Product configuration and powertrain selection vary sharply by end-use intensity and regulatory exposure.
Product Type:
Hull geometry specialization concentrates manufacturing capabilities among suppliers with dedicated mold tooling and composite engineering expertise.
- Sit-down:Family-oriented configurations with three-rider capacity dominate fleet procurement volumes across Florida and California rental corridors. Stability-focused hull designs attract first-time buyers and coastal tourism operators seeking lower liability exposure.
- Stand-up:Athletic single-rider platforms command premium pricing in sport segments. Demand clusters with competitive racing circuits and advanced rider training programs in Australia and Japan.
- Recreational:Entry-level specifications with moderate horsepower ratings serve casual lake and coastal users.
- Sport:High-performance variants with reinforced hulls and enhanced suspension systems target enthusiast buyers.
- Utility:Patrol and rescue configurations with expanded storage and towing capabilities serve municipal and commercial fleets.
Today's leader: Sit-down. Tomorrow's challenger: Utility.
Engine Type:
Powertrain selection directly determines regulatory compliance pathways and marina access permissions across EPA, EU, and Japanese jurisdictions.
- Four-Stroke:Emissions-compliant engines with direct fuel injection and catalytic aftertreatment anchor manufacturer portfolios. Yamaha and BRP production lines prioritize these configurations for US and European markets facing Clean Air Act and EU Green Deal enforcement.
- Electric:Lithium-ion battery systems with marine-grade thermal management are expanding most quickly. Taiga Motors and emerging specialists target rental fleet electrification pilots in Mediterranean marinas and California coastal zones.
- Two-Stroke:Legacy carbureted designs face phased elimination under tightening EPA marine emissions standards.
- Hybrid:Range-extending architectures combining electric propulsion with compact combustion generators remain developmental.
Four-stroke engines sustain current revenue concentration. Electric architectures are gaining share fastest among new product introductions.
Application:
Use-case intensity shapes durability specifications and maintenance interval requirements across buyer segments.
- Rental Services:High-utilization commercial duty cycles with 8-12 hour daily operation demand reinforced hulls and simplified maintenance access. Fleet operators across Florida, Spain, and Australia consolidate procurement through outcome-based service contracts.
- Rescue Operations:Search-and-recovery specifications with GPS integration, towing points, and emergency lighting serve coast guard and municipal agencies. Procurement concentrates through government tender processes in the United States, Italy, and Japan.
- Leisure:Weekend recreational use with seasonal storage patterns dominates individual consumer transactions.
- Racing:Competition-tuned configurations with modified impellers and reduced weight targets sanctioned circuit participation.
- Training:Dual-control layouts and speed-limiting systems serve instructional academies.
Rental services anchor commercial volume. Rescue operations present the steepest expansion trajectory for specialized manufacturers.
Customer Type:
Buyer sophistication and procurement scale fragment pricing power and service model requirements across the value chain.
- Rental Companies:Fleet operators with 50-500 unit deployments negotiate integrated service agreements bundling watercraft, maintenance, and charging infrastructure. Procurement concentrates among coastal tourism corridor specialists in Florida, California, and Queensland.
- Individual Consumers:Discretionary purchases with high customization preference sustain premium margin pools for sport and utility specifications. Financing penetration varies by regional credit availability.
- Sports Clubs:Organized racing and freestyle associations with standardized equipment requirements.
- Training Academies:Instructional institutions with certification obligations and insurance-driven safety specifications.
Rental companies command procurement volume concentration. Individual consumers retain pricing premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The personal watercraft industry traces its commercial origins to the United States, where jet-propelled recreational vessels first achieved mass production scale during the 1970s before spreading to Japanese and European manufacturing centers.
United States
Florida and California coastal corridors concentrate rental fleet procurement volumes, with Lake Havasu and Lake Tahoe serving as year-round recreational hubs. EPA marine emissions enforcement under the Clean Air Act constrains two-stroke engine sales and accelerates four-stroke and electric powertrain transitions. Miami-Dade and Orange County municipalities are expanding rescue watercraft procurement through federal harbor security grants.
Japan
Osaka and Shizuoka prefectures host precision casting suppliers for jet drive impeller manufacturing, with Kawasaki and Yamaha anchoring domestic production networks. METI industrial standards govern marine engine efficiency benchmarks and noise emission thresholds. Tokyo Bay and Osaka Bay recreational zones are piloting electric watercraft rental concessions ahead of regulatory mandates.
Germany
Bavarian lakes and Baltic Sea coastal zones sustain leisure demand for sit-down family configurations, with Munich-based distributors serving Alpine recreational clusters. EU F-Gas Regulation refrigerant constraints and REACH substance restrictions reshape hull composite formulations for European-market units. Lake Constance and Chiemsee marinas are deploying charging infrastructure for electric rental pilots.
Australia
Queensland and New South Wales coastal tourism corridors drive commercial fleet procurement, with Gold Coast operators consolidating 50-500 unit deployments. TGA-equivalent state maritime safety regulations govern personal watercraft operator licensing and equipment standards. Sydney Harbor and Whitsunday Islands rental networks are transitioning toward outcome-based service contracts bundling watercraft and maintenance.
Spain
Mediterranean marina networks from Barcelona to Málaga concentrate seasonal rental demand, with Balearic Islands operators extending fleet utilization windows through winter tourism packages. EU Green Deal marina electrification mandates expand compliance obligations for zero-emission watercraft procurement. Valencia and Alicante port authorities are tendering integrated charging infrastructure for electric fleet transitions.
Global Personal Watercraft Market Competitive Landscape
Premium-margin players sit above commodity-margin players across powertrain sophistication and dealer network density, with four-stroke and electric specialists commanding pricing leverage over two-stroke legacy portfolios. The vendor base organizes into three tiers: integrated powertrain-hull manufacturers, dedicated hull fabricators sourcing engines, and electric-only entrants with battery system specialization. Dominant competitive moves include backward integration into precision casting capabilities and strategic partnerships with marina charging infrastructure providers.
Within the integrated manufacturing tier, BRP Inc. and Yamaha Motor Co., Ltd. exemplify scale-driven positions spanning combustion and emerging electric architectures. Taiga Motors occupies a specialist position dedicated to lithium-ion battery system development for marine applications. These three anchors represent distinct strategic postures: diversified powertrain portfolios, combustion-engine manufacturing depth, and pure-electric vertical focus respectively.
| Leading Market Players |
|---|
| BRP Inc. |
| Yamaha Motor Co., Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| Polaris Inc. |
| Honda Motor Co., Ltd. |
| Taiga Motors |
| Belassi GmbH |
| Krash Industries |
| Gibbs Sports Amphibians Inc. |
| Others |
Supply & Pricing Matrix
Four-stroke powertrain transitions and lithium-ion battery pack integration are simultaneously elevating unit production costs and concentrating manufacturing capabilities among suppliers with captive precision casting and thermal management engineering. This dual technology shift compresses margin structures for legacy two-stroke portfolios while rewarding vertically integrated hull-engine manufacturers with pricing leverage across EPA-compliant and EU Green Deal-aligned product lines.
Pricing Analysis
Three-tier pricing structure across premium sport, standard recreational, and economy rental specifications governs transactional dynamics, with ISO 13590 certification grade and fleet volume scale serving as primary price differentiation drivers. Cost compression in the economy rental tier is intensifying because marina electrification mandates accelerate electric powertrain adoption before charging infrastructure achieves parity coverage. Individual consumers purchasing premium sport configurations exhibit lowest price sensitivity, while fleet procurement officers negotiating 50-500 unit deployments command steepest discounts through bundled service contracts.
Supply Chain Analysis
Workforce availability for marine-grade composite fabrication and precision impeller casting concentrates manufacturing gravity in Japan, the United States, and Germany, where specialized hydrodynamics engineering talent commands premium compensation. Raw material dependencies center on carbon fiber hull reinforcements, lithium nickel manganese cobalt oxide cathode materials, and marine-grade aluminum alloys for jet drive housings. Single-source vulnerability in precision casting capabilities for impeller assemblies presents structural supply chain risk. Distribution runs through coastal dealer networks and direct fleet sales channels serving Mediterranean marina clusters and Florida rental corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal watercraft market functions as a regulatory compounder where EPA marine emissions enforcement and EU Green Deal marina electrification mandates are systematically eliminating non-compliant powertrains while generating replacement demand for certified alternatives.
For Market Incumbents: Cement four-stroke and electric powertrain leadership through backward integration into precision impeller casting capabilities and accelerated ISO 13590 certification pipelines. Battery thermal management engineering talent scarcity threatens product development timelines, making captive R&D investment in marine-specific lithium-ion pack design the critical defensive lever against pure-electric specialists. For New Entrants and Emerging Players: Lithium-ion battery system specialization offers the most penetrable wedge for capturing share in Mediterranean and California rental fleet electrification pilots. Utility function expansion into search-and-rescue and harbor patrol applications presents underserved institutional procurement channels beyond saturated recreational segments. Direct marina charging infrastructure partnerships enable integrated service positioning against established combustion-engine incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier hull fabricators lacking captive powertrain capabilities but possessing established coastal dealer networks. Long-term viability over the next decade hinges on successful electric architecture transition timing relative to marina infrastructure buildout cycles. Battery safety certification progress and EU F-Gas Regulation compliance timelines signal inflection points for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Battery Pack Specialization | Dedicated thermal management engineering addresses automotive-derived solution inadequacies for saltwater environments. |
| Precision Impeller Casting Integration | Captive supply of jet drive components insulates against single-source supplier concentration risks. |
| Marina Charging Infrastructure Partnership | Integrated service bundling aligns procurement patterns with EU Green Deal electrification mandates. |
| ISO 13590 Certification Acceleration | Streamlined type certification enables faster product cycles for compliant manufacturers entering European markets. |
| Utility Function Portfolio Expansion | Search-and-rescue specifications open government tender channels beyond recreational buyer concentration. |
Research Methodology
Multiple input streams — structured interviews with watercraft manufacturer product planners, marina fleet procurement directors, and marine battery system engineers; secondary validation against EPA enforcement disclosures, EU F-Gas Regulation compliance filings, and customs trade data; plus bottom-up and top-down triangulation across hull production volumes and powertrain shipment records — were reconciled to construct market estimates.
Historical shipment trajectories were cross-referenced against expert panel assessments of electrification adoption curves across the projection horizon. Segmentation dimensions modeled include hull configuration type, powertrain architecture, end-use intensity, and regional regulatory cluster. CAGRs were derived from slope-consensus methodology incorporating lithium-ion energy density improvement curves and marina infrastructure deployment schedules.
The model holds under stable EPA enforcement timelines and linear battery cost decline assumptions; deviation in EU Green Deal implementation pace or breakthrough solid-state battery commercialization would shift adoption trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Climbing Harness Market