
 US Spectator Sports Market | 2026-2036
US Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
US Spectator Sports Market Insights
Single-source media rights deals are decoupling from long-term league-federation partnerships as franchises and conferences explore direct-to-consumer streaming alternatives. The NFL sustains the largest national broadcast footprint through legacy network agreements. ESPN Inc. navigates a hybrid cable-digital strategy that preserves affiliate fees while building streaming subscription volume. The Dallas Cowboys leverage unmatched local market revenue to fund stadium infrastructure independently.
US Spectator Sports encompasses live professional and amateur athletic competitions designed for in-venue and remote viewership, delivered through broadcast, cable, satellite, and over-the-top streaming platforms with production specifications ranging from 4K HDR video to immersive audio and real-time data overlays. The primary commercial purpose centers on aggregating mass audiences for monetization through ticket sales, media rights, sponsorship inventory, and licensed merchandise. Football commands the largest monetization model revenue pool across broadcasting rights and sponsorships, while basketball and soccer segments show faster growth in digital-native audience engagement. Adult demographics anchor per-capita spending on premium experiences, though family-oriented event programming drives higher total attendance volume across regular season schedules.
FCC broadcast ownership rules and the NFL's media rights framework shape content distribution access, while NCAA governance structures and state-level sports betting regulations alter fan engagement economics and secondary revenue streams. OSHA standards influence venue safety protocols and crowd management capacity calculations. Stakeholders must monitor how fragmented streaming rights and evolving state gambling frameworks reshape fan spending patterns and partnership valuations.
Market Dynamics
Media rights fragmentation is dismantling the NFL's centralized broadcast monopoly as conferences and franchises build direct-to-consumer streaming infrastructure, forcing a fundamental restructuring of how sports content reaches audiences and generates revenue.
Growth Catalysts
- State Sports Betting Frameworks:Legalized wagering in jurisdictions like New York and Illinois is expanding fan engagement economics and creating new sponsorship inventory categories for venues and broadcasters.
- 4K HDR Production Pipelines:Advanced broadcast specifications are enabling premium tier pricing for remote viewership and reducing the quality gap between in-venue and at-home experiences.
- Metropolitan Venue Density:Corporate sponsorship bases in Dallas, Los Angeles, and Atlanta are underwriting luxury hospitality construction and sustaining premium seating demand through economic cycles.
Market Restraints
- FCC Broadcast Ownership Caps:Local market television station consolidation limits create friction for regional sports network economics and reduce leverage in carriage fee negotiations.
- Collegiate Conference Realignment Costs:NCAA governance instability forces media rights contract renegotiation cycles that compress valuation certainty for content distributors.
- Legacy Cable Bundle Dependency:ESPN's hybrid strategy remains tethered to declining affiliate fee revenue pools that fund collegiate athletic program subsidies.
Strategic Opportunities
- Texas Secondary Market Expansion:Austin and San Antonio metro areas present underpenetrated demand for professional franchise relocation or expansion with corporate sponsorship depth.
- Immersive Audio-Data Convergence:Real-time betting overlays and spatial audio are creating new premium subscription tiers for digital-native demographics.
- OSHA Venue Safety Modernization:Updated crowd management standards enable capacity optimization and premium standing-room product development in renovated stadium infrastructure.
Industry Challenges
- Streaming Rights Fragmentation:Disaggregated league, conference, and team-level digital distribution creates consumer confusion and subscription fatigue that suppresses aggregate conversion rates.
- Production Talent Pipeline Constraints:Specialized broadcast technicians for 4K HDR and real-time data integration face acute supply shortages in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Spectator Sports Market |
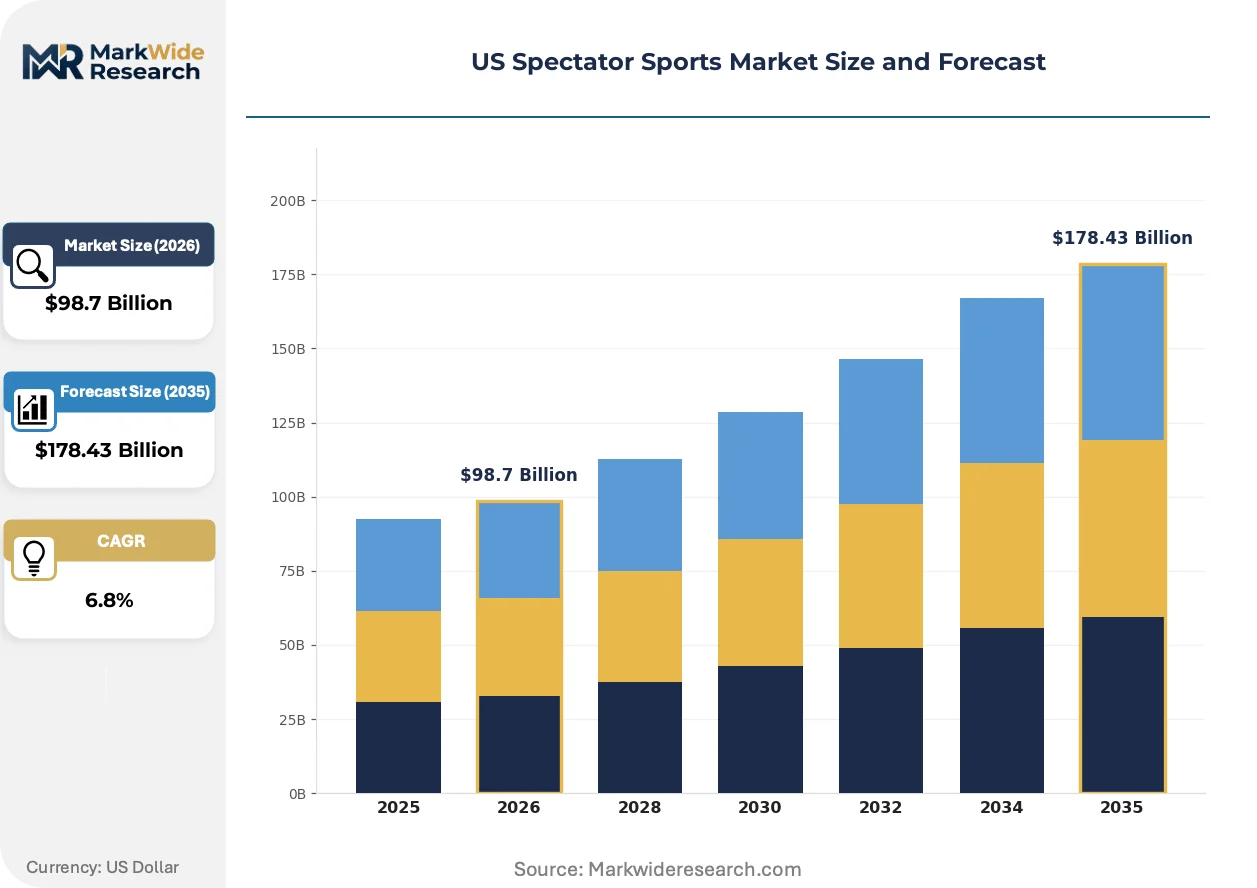
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Football, Basketball, Baseball, Hockey Audience Demographic: Adults, Teenagers, Families, Seniors Event Type: Regular Season, Playoffs, Championships, All-Star Games Monetization Model: Ticket Sales, Broadcasting Rights, Sponsorships, Merchandise |
| Companies Covered | National Hockey League (NHL), Dallas Cowboys, National Football League (NFL), Los Angeles Lakers, New York Yankees, Major League Baseball (MLB), Major League Soccer (MLS), ESPN Inc., National Basketball Association (NBA), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Spectator Sports Market Trends and Innovations
Distribution architecture is pivoting from centralized league-federation control toward fragmented direct-to-consumer models, with technology and regulation accelerating the unbundling of traditional broadcast economics.
Cloud-based production workflows are modularizing sports broadcast infrastructure. Regional sports networks and collegiate conferences are adopting software-defined production stacks that reduce capital intensity for mid-tier properties. This technology compression is modularizing what previously required dedicated hardware investments, enabling smaller market teams to compete on production quality.
FCC broadcast ownership rule modernization is reshaping local station consolidation economics. Relaxation of duopoly restrictions in designated market areas is permitting broadcast groups to achieve scale efficiencies in sports programming acquisition. The regulatory shift most affects mid-sized metropolitan markets where standalone station economics previously constrained sports rights bidding capacity.
Secondary ticket market unbundling is disrupting traditional season ticket holder retention models. Digital-native fans in Los Angeles and New York are purchasing single-event premium experiences through mobile-first platforms rather than committing to annual seat licenses. This behavioral rotation is most visible in NFL markets where variable pricing algorithms now dominate inventory release strategies.
US Spectator Sports Market Segmentation
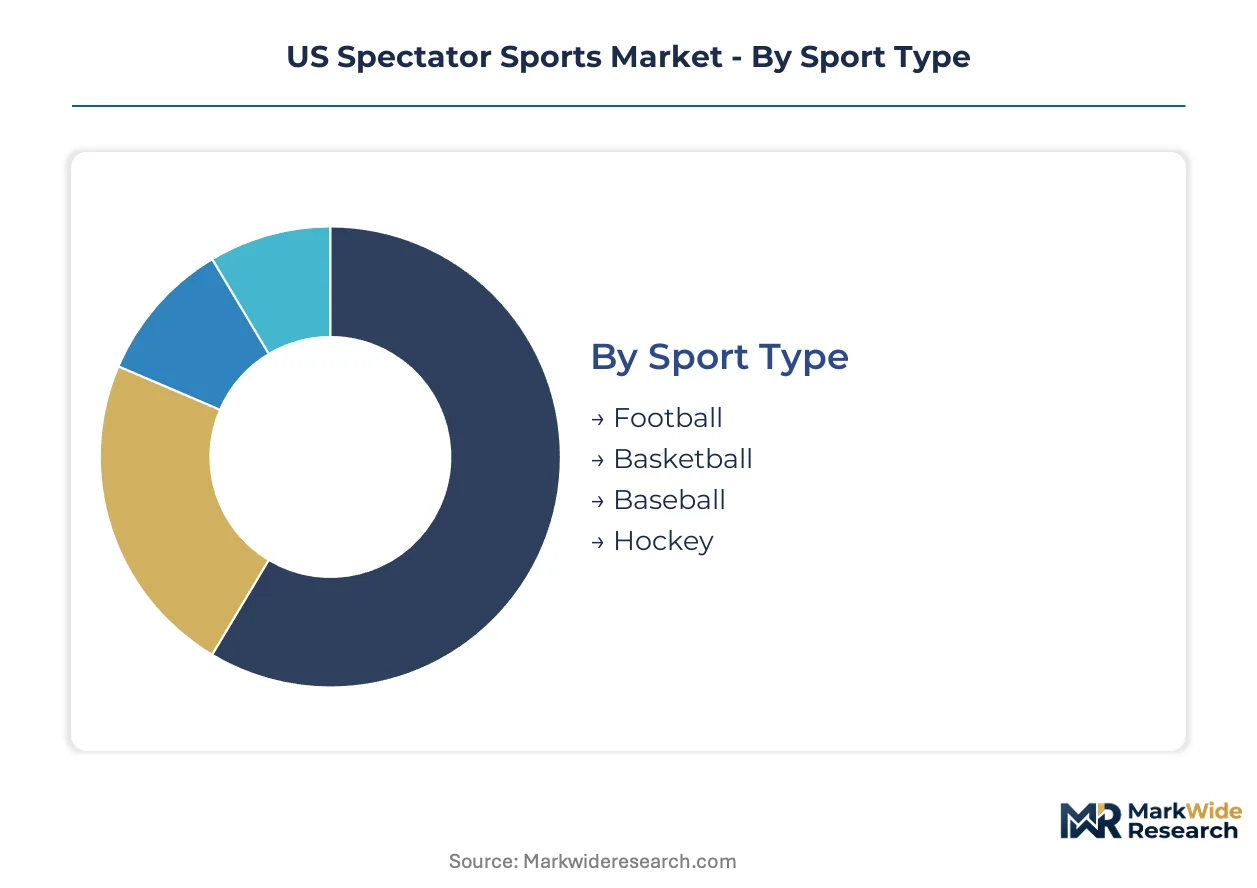
Segmentation in US spectator sports reveals how revenue pools concentrate across distinct consumption patterns and commercial architectures. Each dimension exposes different pressure points for pricing power, media rights valuation, and venue infrastructure investment.
Sport Type:
Football commands disproportionate production infrastructure and stadium capital deployment across the Dallas, Los Angeles, and New York metro clusters.
- Football:NFL properties dominate national broadcast economics through 4K HDR production specifications and exclusive media rights windows. Dallas Cowboys local market revenue funds independent stadium infrastructure without league subsidy.
- Basketball:NBA franchises leverage faster game pacing to capture digital-native engagement through real-time betting overlays and immersive audio subscriptions. Atlanta and Los Angeles corporate sponsorship bases sustain premium hospitality construction.
- Baseball:MLB's elongated season schedule creates inventory depth for regional sports network carriage fee negotiations.
- Hockey:NHL properties concentrate in northern metropolitan markets with established winter sports venue infrastructure.
Football absorbs the bulk of installed capacity; basketball is expanding most quickly.
Audience Demographic:
Spending concentration varies sharply by age cohort and household composition, reshaping how venues package hospitality and broadcasters tier subscription products.
- Adults:Per-capita expenditure peaks among 25-54 demographics purchasing premium seating and corporate hospitality inventory. FCC broadcast regulations and NFL media rights frameworks target this cohort through legacy network agreements.
- Families:Higher total attendance volume across regular season schedules drives concession and merchandise economics through child-oriented programming.
- Teenagers:Mobile-first consumption patterns concentrate on short-form highlights and fantasy sports engagement.
- Seniors:Traditional broadcast loyalty sustains cable bundle economics and daytime programming slots.
Adult demographics anchor per-capita revenue extraction; family segments drive aggregate attendance throughput.
Event Type:
Inventory scarcity and production intensity escalate through the competitive calendar, creating tiered pricing architectures that venues exploit for yield optimization.
- Championships:Single-elimination or best-of-series finales command 10-20x regular season ticket multiples and exclusive broadcast windows. Super Bowl media rights and NCAA Final Four rotation agreements concentrate production talent and sponsorship activation.
- Playoffs:Tournament structures in basketball and hockey generate incremental inventory with variable pricing algorithms dominating release strategies in Los Angeles and New York markets.
- Regular Season:Volume-based scheduling sustains regional sports network economics and season ticket holder retention programs.
- All-Star Games:Exhibition formats leverage destination city rotation for tourism and hospitality revenue capture.
Championships absorb the bulk of premium pricing infrastructure; playoffs are climbing the fastest in per-event revenue yield.
Monetization Model:
Revenue architecture is decoupling from centralized league control as franchises and conferences build direct-to-consumer streaming infrastructure independent of legacy broadcast partnerships.
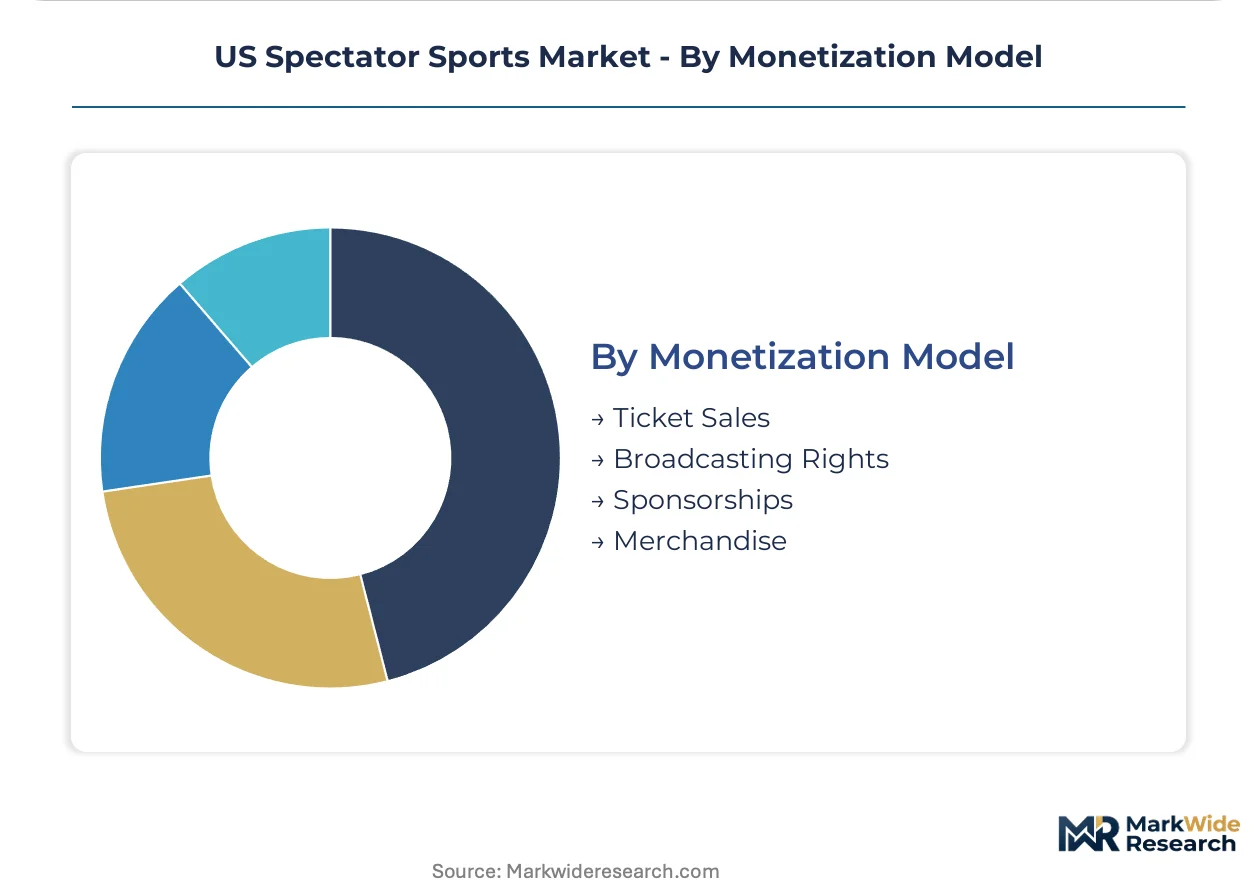
- Broadcasting Rights:NFL national agreements sustain the largest footprint, while ESPN's hybrid cable-digital strategy preserves affiliate fees alongside streaming subscription volume. FCC ownership rule modernization enables broadcast group scale efficiencies in mid-sized designated market areas.
- Ticket Sales:Secondary market unbundling disrupts season ticket retention through mobile-first single-event purchases in metropolitan venue density clusters.
- Sponsorships:State sports betting frameworks in New York and Illinois expand inventory categories for venues and broadcasters.
- Merchandise:Licensed product economics tie to championship cycles and star player mobility.
Broadcasting rights absorb the bulk of contracted revenue; sponsorships are gaining share fastest through wagering integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan venue density in Dallas, Los Angeles, and New York anchors the US Spectator Sports Market's geographic concentration. Corporate sponsorship bases in these clusters sustain premium hospitality construction and media rights valuation. FCC broadcast regulations and state-level sports betting frameworks reshape revenue extraction across sub-regional markets.
Texas
The Dallas Cowboys generate unmatched local market revenue that funds independent stadium infrastructure without league subsidy. State sports betting legalization creates new sponsorship inventory categories for venues and broadcasters. Austin and San Antonio metro areas present underpenetrated demand for professional franchise expansion with corporate sponsorship depth.
California
Los Angeles Lakers and multiple NFL franchises leverage entertainment industry adjacency for premium media production partnerships. FCC broadcast ownership caps create friction for regional sports network economics in the state's fragmented designated market areas. Silicon Valley technology clusters accelerate cloud-based production workflow adoption across collegiate and professional properties.
New York
New York Yankees and multiple professional franchises command the deepest corporate hospitality demand and variable pricing algorithm deployment. State sports betting frameworks in New York expand fan engagement economics and secondary revenue streams. The metropolitan venue density sustains premium seating demand through economic cycles with unmatched sponsorship activation scale.
Illinois
Chicago's collegiate and professional athletic programs navigate NCAA governance instability and media rights contract renegotiation cycles. State-level sports betting regulations alter fan engagement economics and create new inventory categories for broadcasters. The metropolitan market's corporate sponsorship base underwrites luxury hospitality construction across renovated stadium infrastructure.
Georgia
Atlanta's corporate sponsorship concentration sustains premium hospitality construction and championship event rotation hosting. OSHA venue safety standards influence crowd management capacity calculations in renovated stadium infrastructure. The metropolitan market's collegiate athletic programs adopt software-defined production stacks that reduce capital intensity for mid-tier broadcast properties.
US Spectator Sports Market Competitive Landscape
Media rights fragmentation dominates the current landscape as conferences and franchises build direct-to-consumer streaming infrastructure. The market structures around three tiers: centralized league federations controlling national broadcast windows, individual franchises extracting local market revenue, and technology platforms disintermediating traditional distribution. Two strategic archetypes predominate: vertically integrated venue-media conglomerates and streaming-native content distributors. Competitive moves concentrate on exclusive media rights acquisition and proprietary streaming platform development.
Among league-based entities, the National Football League and National Basketball Association occupy positions as centralized rights aggregators. ESPN Inc. sits within the hybrid distribution tier, navigating cable affiliate fees alongside streaming subscription volume. The Dallas Cowboys exemplify the franchise-level archetype, leveraging unmatched local market revenue to fund independent infrastructure development.
| Leading Market Players |
|---|
| National Hockey League (NHL) |
| Dallas Cowboys |
| National Football League (NFL) |
| Los Angeles Lakers |
| New York Yankees |
| Major League Baseball (MLB) |
| Major League Soccer (MLS) |
| ESPN Inc. |
| National Basketball Association (NBA) |
| Others |
Pricing and Supply Chain Analysis
Cloud-based production workflows are compressing broadcast infrastructure costs while simultaneously redistributing supply concentration toward technology hubs and away from legacy hardware manufacturers. This dual shift enables mid-tier collegiate conferences to achieve parity production quality at reduced capital intensity, fundamentally altering how pricing power accrues across the content distribution value chain.
Pricing Analysis
Service bundling separates premium tier offerings that include immersive audio, real-time betting overlays, and 4K HDR streams from unbundled basic access. Three-tier pricing structure across premium, standard, and economy levels reflects production quality differentiation and geographic market density. Pricing pressure stems from subscription fatigue as fragmented streaming rights force consumers toward multiple platform commitments. Family-oriented event programming demonstrates highest price sensitivity, while corporate hospitality buyers in Dallas and New York metros exhibit lowest elasticity.
Supply Chain Analysis
Direct-to-consumer streaming channels handle hyperscale fan demand, bypassing traditional cable bundle intermediaries. Production technology concentrates in California's Silicon Valley clusters, Texas metro areas, and Georgia's Atlanta hub. Raw material dependencies include specialized broadcast hardware, cloud computing infrastructure, and proprietary data overlay software. Supply chain risk centers on single-source vulnerability for 4K HDR production talent in secondary markets. Distribution runs through hybrid cable-digital platforms alongside franchise-controlled streaming applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Spectator Sports Market sits at a technology-transition inflection as cloud-based production workflows displace legacy hardware-dependent broadcast infrastructure, forcing stakeholders to recalibrate investment priorities around software-defined content delivery.
For Market Incumbents: Anchor defensive positioning through exclusive media rights acquisition in Texas and California growth corridors while accelerating proprietary streaming platform development. Threats from direct-to-consumer fragmentation by individual franchises demand countermeasures through league-level technology standardization. Vertical integration into cloud production infrastructure offers cost control leverage against technology vendor consolidation. For New Entrants and Emerging Players: Enter via Austin and San Antonio metro areas where corporate sponsorship depth exceeds professional franchise penetration. White-space targets include immersive audio-data convergence products for digital-native demographics and secondary market ticketing platforms optimized for mobile-first single-event purchases. Go-to-market positioning should emphasize software-defined production stacks that reduce capital barriers for mid-tier collegiate properties. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated venue-media conglomerates given state sports betting framework expansion as a valuation catalyst. Long-term viability favors franchises controlling both physical infrastructure and direct-to-consumer distribution channels. Signal to watch is FCC broadcast ownership rule modernization enabling consolidation scale efficiencies in mid-sized designated market areas.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Streaming Platform Development | ESPN's hybrid cable-digital strategy preserves affiliate fees while building subscription volume against fragmentation. |
| Cloud-Based Production Stack Adoption | Georgia's collegiate programs reduce capital intensity through software-defined infrastructure in Atlanta clusters. |
| State Sports Betting Partnership Expansion | New York and Illinois frameworks create new sponsorship inventory categories for venues and broadcasters. |
| Exclusive Media Rights Acquisition | NFL national agreements sustain the largest broadcast footprint through legacy network window control. |
| Premium Hospitality Infrastructure Buildout | Dallas Cowboys leverage unmatched local market revenue to fund independent stadium development without league subsidy. |
Research Methodology
Document review covered SEC filings from publicly traded media companies, FCC regulatory dockets, and NCAA governance records, complemented by interviews with broadcast technology executives, collegiate athletic directors, regional sports network operators, and corporate sponsorship managers. Secondary sources included ESPN subscriber disclosure data, NFL media rights agreements, state sports betting regulatory filings, and venue construction permits. Bottom-up revenue modeling triangulated against top-down market sizing from media rights valuation benchmarks.
Historical consumption patterns cross-referenced against panel input from streaming platform operators and ticket marketplace data providers informed projection assumptions. Segmentation dimensions modeled include sport type, audience demographic, event type, and monetization model across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating FCC regulatory trajectory and state wagering legalization pace. Forecast inputs included collegiate conference realignment probability and cloud production cost compression curves.
Revisions become necessary when FCC ownership rule changes accelerate, state sports betting frameworks shift, or streaming rights fragmentation triggers consumer subscription behavior changes. Forecasts reflect assumptions regarding technology adoption rates and regulatory enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Motorized Pool Tube Market