
 Ski Vacation Market | 2026-2036
Ski Vacation Market Size, Share, and Industry Trends Forecast 2026-2036
Ski Vacation Market Analytics
Market Context
Synthetic insulation materials are displacing traditional down in ski apparel and lodging amenities, and this shift is recalibrating procurement economics across the vacation supply chain. Ski.com leverages its digital platform control to aggregate inventory from fragmented mountain suppliers across North America and Europe. Intrepid Travel differentiates through carbon-neutral itinerary certification, attracting environmentally conscious travelers to its backcountry programs. G Adventures anchors its model in small-group expedition formats, sustaining premium pricing in destinations like Patagonia and the Japanese Alps.
Technical Definition and Segment Structure
A ski vacation constitutes a multi-day travel product centered on alpine or nordic skiing, incorporating lift-accessed terrain, equipment rental, instruction services, and slope-side lodging with operational parameters spanning vertical drop, snow reliability indices, and bed-base capacity per resort. Package type segmentation reveals all-inclusive bundles capturing the dominant margin pool by bundling lift tickets, meals, and equipment into single-price contracts, while accommodation-only bookings serve price-sensitive travelers who self-source terrain access. Destination type segmentation shows resorts commanding the highest revenue per available room through captive village economies, whereas backcountry segments attract specialized operators like Bindlestiff Tours that compete on guide expertise and safety infrastructure rather than fixed-asset scale.
Regulatory Framework
France's Mountain Law and Switzerland's Federal Act on the Protection of the Environment shape terrain development permissions, mandating environmental impact assessments that extend approval timelines and elevate capital requirements for new lift installations. The EU Green Deal's tourism sustainability criteria and ISO 14001 environmental management standards increasingly condition access to institutional financing for resort expansion projects across the European Alps. Stakeholders must monitor how alpine jurisdictions integrate climate adaptation requirements into operating licenses, as snowmaking restrictions and energy-transition mandates redefine viable season lengths and infrastructure depreciation schedules.
Market Dynamics
Climate adaptation mandates are compressing viable season lengths across alpine destinations, forcing operators to diversify revenue streams beyond lift-dependent skiing toward year-round mountain experiences.
Growth Catalysts
- EU Green Deal tourism criteria:Institutional financing increasingly favors resorts demonstrating carbon-neutral operations, accelerating capital flows toward sustainable infrastructure upgrades.
- Synthetic insulation materials:These advanced textiles reduce supply chain volatility from down sourcing while meeting performance benchmarks for extreme-cold applications.
- Swiss Alps terrain consolidation:Integrated operators capturing village economies through bundled lodging, dining, and lift access generate superior revenue per available room.
Market Restraints
- France's Mountain Law ecological compensation:Mandatory environmental offsets for lift expansion extend approval timelines and elevate upfront capital requirements.
- Snowmaking energy intensity:Restrictions on water withdrawal and electricity consumption during peak demand periods constrain artificial snow production capacity.
- Vertical drop scarcity:Limited undeveloped terrain with sufficient elevation differential restricts greenfield resort development in premium alpine zones.
Strategic Opportunities
- Japanese Alps backcountry segments:Powder tourism demand from North American and European travelers outpaces guided-service supply, creating pricing power for certified operators.
- Carbon-neutral itinerary certification:Third-party validation of emission offsets attracts environmentally conscious travelers willing to pay premium rates.
- Digital platform aggregation:Inventory consolidation across fragmented mountain suppliers reduces booking friction and captures commission revenue.
Industry Challenges
- Guide certification bottlenecks:Backcountry safety expertise requirements limit qualified personnel supply for expanding expedition programs.
- Legacy lift infrastructure depreciation:Accelerated replacement cycles for energy-inefficient systems strain operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ski Vacation Market |
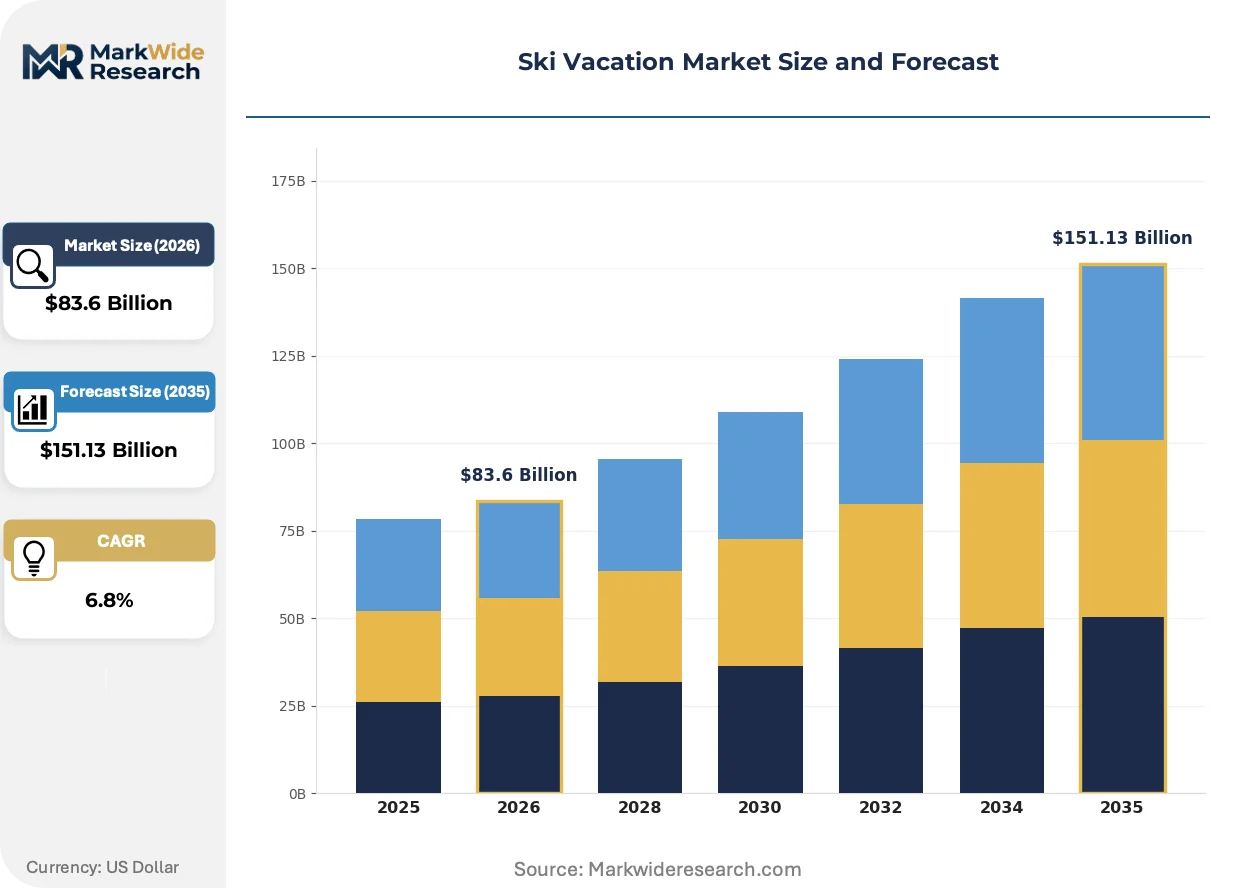
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $151.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: All-Inclusive, Ski Pass, Accommodation Only, Group Packages Customer Demographic: Families, Couples, Solo Travelers, Corporate Groups Destination Type: Resorts, Backcountry, Urban Areas, Mountain Villages Experience Level: Beginner, Intermediate, Advanced, Expert |
| Companies Covered | On The Go Tours, Ski Independence, G Adventures, Bindlestiff Tours, One Life Adventures, Intrepid Travel, Ski.com, Ski Solutions, Contiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ski Vacation Market Evolving Landscape
Alpine operators are reconfiguring fixed-asset portfolios around climate resilience, with technology and regulatory pressure converging to redefine what constitutes a viable ski product.
AI-powered snow depth prediction systems combine satellite imagery with ground sensor networks to optimize grooming schedules and snowmaking activation. Mid-sized resorts in Austria and Italy are deploying these platforms to reduce energy waste. This precision resource management is overtaking intuition-based operational decision-making.
Switzerland's Federal Act on the Protection of the Environment mandates environmental impact assessments that extend lift installation approvals by multiple seasons. Capital deployment timelines stretch accordingly, favoring incumbent operators with patient balance sheets. New entrant developers face structural disadvantages in terrain access competitions.
Travelers increasingly self-source terrain access through multi-resort pass products rather than booking packaged bundles. Accommodation-only bookings rise as price-sensitive segments bypass traditional operators. This unbundling concentrates most visibly in Colorado and Utah, where Ikon and Epic pass penetration exceeds packaged vacation sales.
Ski Vacation Market Segmentation
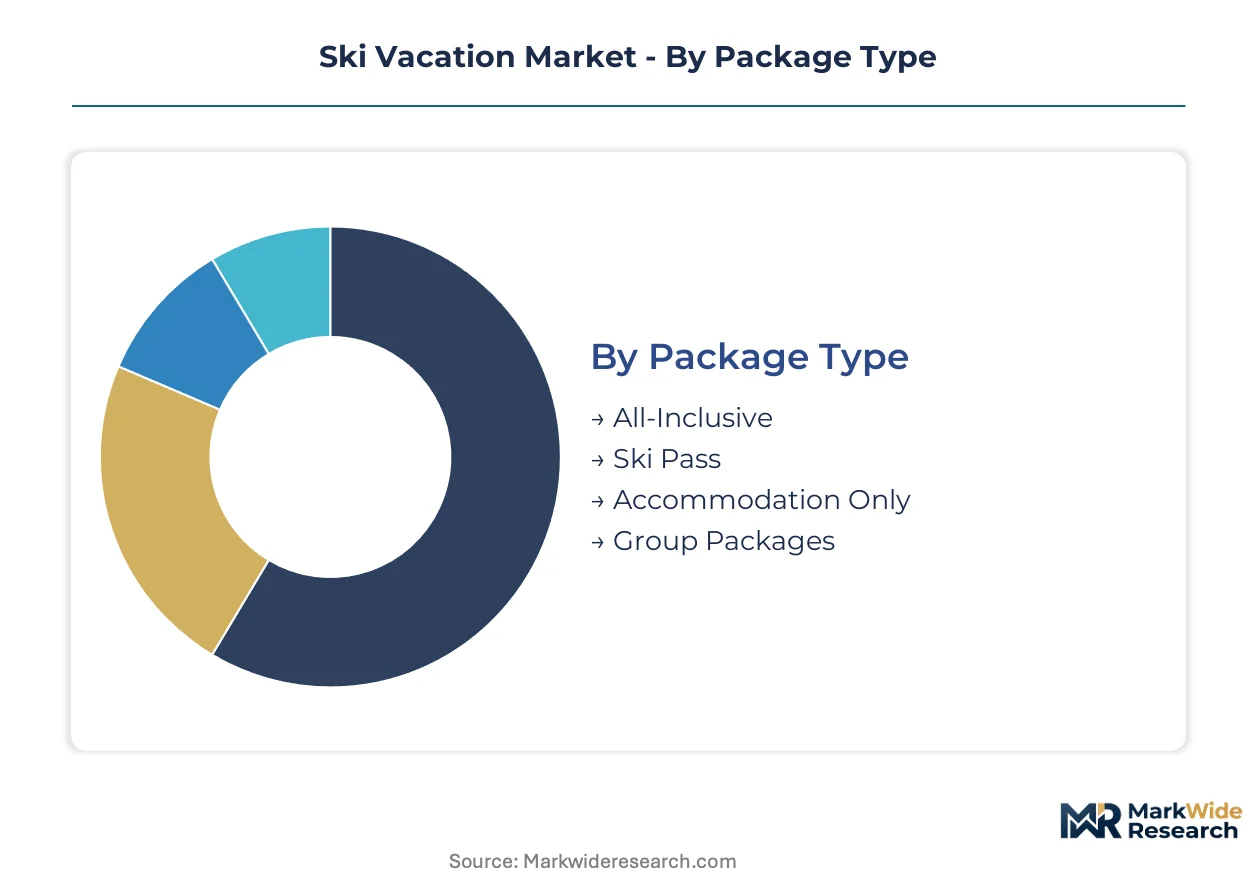
Ski vacation segmentation reveals how bundling depth, customer composition, and terrain access shape revenue capture. Operators calibrate inventory allocation across these dimensions to defend margin pools against climate compression and unbundling pressures.
Package Type:
Standalone purchase decisions versus embedded system integration distinguishes how travelers access mountain infrastructure and where operators extract value.
- All-Inclusive:Single-price contracts bundle lift tickets, meals, equipment, and instruction into unified procurement. French and Swiss integrated resort operators dominate this segment through captive village economies with lodging-dining-terrain lock-in. Climate adaptation investments concentrate here as bundled pricing absorbs snowmaking cost volatility.
- Ski Pass:Terrain-access-only products separate lift tickets from lodging procurement. North American multi-resort passes like Ikon and Epic accelerate unbundling in Colorado and Utah, forcing traditional packagers toward commission-based aggregation models.
- Accommodation Only:Lodging bookings without bundled mountain services serve price-sensitive travelers who self-source terrain access. Digital platforms capture this demand through inventory aggregation.
- Group Packages:Coordinated bookings for affinity clusters leverage volume discounts and dedicated instruction allocation. Corporate retreat demand and family reunion travel concentrate in this segment.
All-Inclusive leads volumes today; Ski Pass is gaining share fastest.
Customer Demographic:
Group size and decision-making unit composition determine booking channel preference and ancillary revenue potential across the vacation cycle.
- Families:Multi-generational units prioritize instruction services, childcare infrastructure, and slope-side lodging proximity. Safety certification and beginner terrain quality drive destination selection.
- Couples:Smaller booking units favor premium lodging and dining experiences over terrain volume. Spa and après-ski amenities command disproportionate share of wallet.
- Solo Travelers:Individual bookings concentrate in backcountry segments and guided expedition formats where safety infrastructure substitutes for group dynamics. Intrepid Travel and G Adventures target this demographic.
- Corporate Groups:Incentive travel and team-building retreats generate midweek demand during low-occupancy periods. Conference facilities and group instruction packages structure these bookings.
Families anchor revenue concentration; Solo Travelers show steepest expansion trajectory.
Destination Type:
Fixed-asset intensity and operational control vary dramatically across terrain access models, reshaping capital deployment requirements.
- Resorts:Lift-served terrain with captive village economies generates superior revenue per available room through bundled service control. Swiss integrated operators exemplify this model.
- Backcountry:Guide-dependent terrain access competes on safety expertise rather than fixed-asset scale. Japanese Alps powder tourism outpaces certified guide supply.
- Urban Areas:Artificial slope facilities and indoor skiing centers decouple terrain access from alpine geography. These installations extend seasonality and democratize entry.
- Mountain Villages:Distributed lodging stock without unified lift infrastructure requires traveler self-organization. Price-sensitive segments dominate.
Resorts command margin pools; Backcountry climbs the fastest.
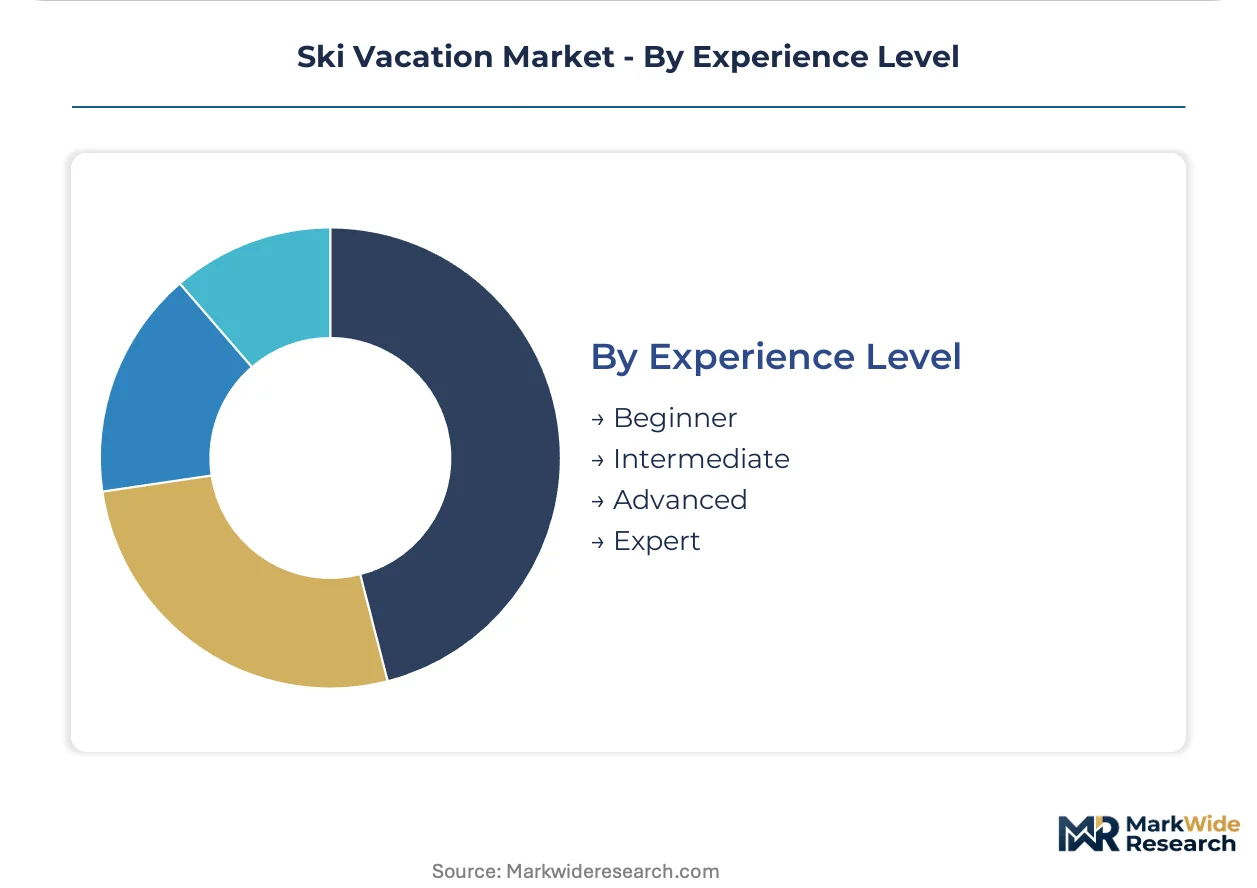
Experience Level:
Skill-based segmentation aligns instruction service design, terrain allocation, and risk management protocols with traveler capability profiles.
- Beginner:First-time skiers require dedicated learning terrain, rental equipment optimization, and progressive instruction curricula. Conversion to repeat visitation hinges on initial experience quality.
- Intermediate:Developing skiers seek varied terrain progression and social skiing environments. This segment represents the largest addressable population for destination marketing.
- Advanced:Confident skiers prioritize challenging groomed terrain and off-piste access within resort boundaries. Speed and vertical throughput shape satisfaction.
- Expert:Technical proficiency enables backcountry expedition participation and steep skiing objectives. Guide certification and avalanche safety infrastructure become decisive factors.
Intermediate anchors participation volumes; Expert shows strongest pricing power expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Swiss Alps anchor destination concentration through integrated resort operators controlling captive village economies with bundled lodging, dining, and lift infrastructure.
United States
Colorado and Utah drive North American demand through multi-resort pass penetration exceeding traditional packaged vacation sales. The EPA regulates snowmaking water withdrawal under Clean Water Act provisions, constraining artificial production capacity. Aspen and Vail anchor the Ikon and Epic pass ecosystems, consolidating terrain access under platform-based inventory control.
France
High-net-worth millennial travelers expand premium package bookings through integrated resort operators in the French Alps. The Mountain Law mandates ecological compensation for lift infrastructure expansion, redirecting capital toward sustainable systems. Chamonix and Val d'Isère concentrate terrain development approvals extended by environmental impact assessment timelines.
Switzerland
Integrated operators generate superior revenue per available room through unified control of lodging, dining, and lift assets across alpine villages. The Federal Act on the Protection of the Environment shapes terrain development permissions through extended approval seasons. Zermatt and St. Moritz exemplify consolidated village economies with patient capital deployment for climate-resilient infrastructure.
Japan
Powder tourism demand from North American and European travelers outpaces certified guide supply in the Japanese Alps. METI oversees tourism sustainability standards conditioning access to development financing. Niseko and Hakuba concentrate backcountry expedition growth where safety expertise substitutes for fixed-asset scale.
Austria
Mid-sized resorts deploy AI-powered snow depth prediction systems combining satellite imagery with ground sensor networks to optimize grooming schedules. The EU Green Deal tourism criteria accelerate capital flows toward carbon-neutral operations. Innsbruck and Kitzbühel anchor precision resource management adoption overtaking intuition-based operational decision-making.
Ski Vacation Market Competitive Landscape
Global majors compete with regional champions across digital platform control and guide-dependent expedition formats. The vendor base separates between inventory aggregators capturing commission revenue and specialized operators competing on safety certification. Three archetypes dominate: integrated resort operators with captive village economies, digital aggregators consolidating fragmented mountain supplier inventory, and backcountry specialists leveraging guide expertise. Competitive moves concentrate on M&A for terrain access consolidation and carbon-neutral itinerary certification to attract environmentally conscious travelers.
Within the expedition-specialist tier, G Adventures and Intrepid Travel exemplify small-group format operators sustaining premium pricing through carbon-neutral certification, while Ski.com anchors the digital aggregation archetype consolidating North American and European inventory. Bindlestiff Tours occupies a position among guide-dependent backcountry operators where safety infrastructure substitutes for fixed-asset scale in Japanese Alps powder tourism.
| Leading Market Players |
|---|
| On The Go Tours |
| Ski Independence |
| G Adventures |
| Bindlestiff Tours |
| One Life Adventures |
| Intrepid Travel |
| Ski.com |
| Ski Solutions |
| Contiki |
| Others |
Value Network & Pricing Analysis
High-net-worth millennial travelers demanding carbon-neutral itinerary certification are forcing operators to absorb sustainability compliance costs into bundled pricing structures, compressing margins on standard packages while amplifying premium-tier pricing power.
Pricing Analysis
Input-cost pass-through from synthetic insulation material procurement and snowmaking energy tariffs shapes pricing stratification across premium, standard, and economy tiers. All-inclusive bundles at French and Swiss integrated resorts absorb climate adaptation investments into single-price contracts, while accommodation-only bookings in North American markets face sharper price sensitivity from self-sourcing terrain access through multi-resort passes. Pricing pressure intensifies in mid-tier segments as unbundling accelerates in Colorado and Utah.
Supply Chain Analysis
Regional distribution centers in Grenoble, Innsbruck, and Denver anchor hub-and-spoke patterns for equipment and apparel fulfillment. Manufacturing concentrates in China, Vietnam, and Bangladesh for synthetic textiles, while lift system components source from Austria, Switzerland, and Germany. Supply chain risk centers on single-source vulnerability for specialized avalanche safety equipment. Distribution runs through resort-affiliated rental hubs and third-party logistics partners serving fragmented mountain suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
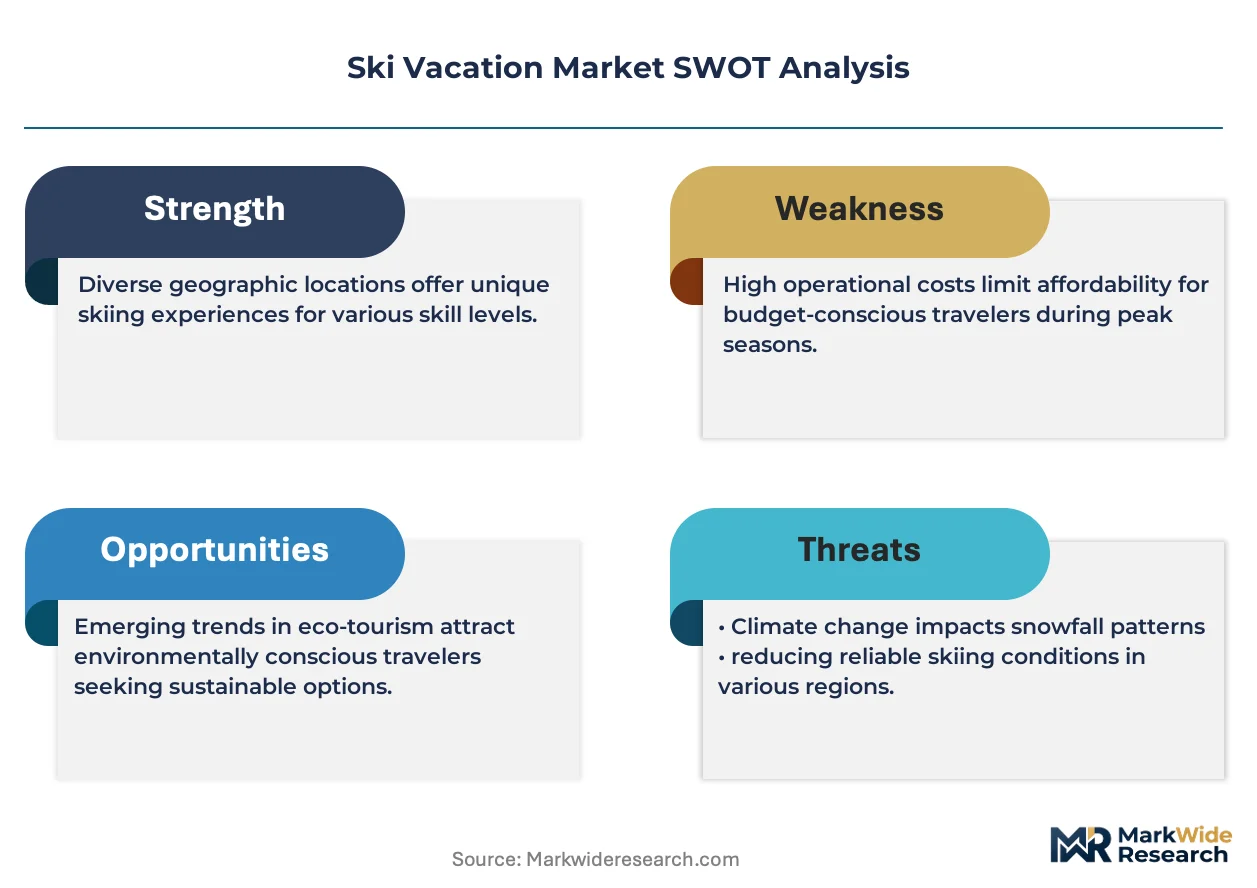
This market operates as a regulatory compounder where France's Mountain Law and the EU Green Deal tourism criteria accelerate capital flows toward operators with pre-certified sustainability infrastructure.
For Market Incumbents: Anticipate compressed season lengths by diversifying revenue streams toward year-round mountain experiences beyond lift-dependent skiing. Swiss and French integrated operators should consolidate terrain access through patient capital deployment while accelerating AI-powered snow depth prediction adoption to reduce energy waste. Guide certification bottlenecks threaten backcountry expansion timelines.
For New Entrants and Emerging Players: The price-point gap between premium carbon-certified packages and economy self-sourced bookings creates white-space opportunity in mid-tier guided expedition formats. Japanese Alps backcountry segments show the most penetrable demand-supply imbalance, with certified guide scarcity enabling pricing power for qualified entrants. Target solo traveler demographics through digital platform aggregation partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized backcountry operators holding certified guide networks in undersupplied powder tourism destinations. Long-term viability favors assets with diversified revenue streams decoupled from snow reliability. Monitor EU Green Deal financing access as the inflection indicator for operator tier separation.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Certification Investment | EU Green Deal criteria condition institutional financing access for resort expansion projects. |
| AI-Powered Resource Management Deployment | Austrian mid-sized resorts reduce snowmaking energy waste through satellite-sensor integration. |
| Guide Network Capacity Buildout | Japanese Alps powder tourism demand outpaces certified safety expertise supply. |
| Digital Platform Integration | Ski.com's inventory aggregation model captures commission revenue from fragmented suppliers. |
| Year-Round Experience Diversification | Climate adaptation mandates compress viable ski seasons, forcing revenue stream expansion. |
Research Methodology
Direct dialogue with resort operations directors, backcountry guide service managers, sustainable tourism certification officers, and alpine destination marketing executives grounded qualitative findings. Secondary validation drew from EU Green Deal implementation reports, France's Mountain Law regulatory filings, Swiss Federal Act on environmental impact assessments, and METI tourism sustainability standards. Bottom-up segmentation modeling triangulated with top-down macroeconomic indicators across the analysis window.
Market sizing outputs reflect demand-side aggregation across package type, customer demographic, destination type, and experience level dimensions. CAGRs derived from slope-side lodging capacity expansion, lift infrastructure investment cycles, and backcountry guide supply growth trajectories. Snow reliability indices and energy transition mandates informed scenario-weighted projections throughout the forecast period.
Caveats apply where regulatory timeline extensions, snowmaking restriction tightening, or synthetic material supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Wakeboard Market