
 Fat Bike Market | 2026-2036
Fat Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Bike Market Foresight
CE marking under the EU Machinery Directive is rebalancing the cost-of-entry calculus for European fat bike imports, forcing smaller assemblers to certify frame integrity and electrical systems before market access. Surly Bikes leverages its Minnesota-based manufacturing heritage to sustain domestic credibility among cold-climate riders. Rad Power Bikes anchors its position through direct-to-consumer channel control that bypasses traditional bike shop markups. Velotric differentiates by competing aggressively on e-fat bike price positioning against legacy pedal-only brands.
A fat bike is a bicycle built around oversized tires typically measuring four to five inches in width, mounted on rims ranging from 65 to 100 millimeters, designed to distribute rider weight across snow, sand, and loose terrain surfaces where standard mountain bike tires would sink. The frame geometry accommodates these tire dimensions through widened bottom brackets and extended chainstays while maintaining pedal clearance. Hardtail configurations dominate volume sales due to simpler maintenance requirements and lower price points that appeal to entry-level recreational cyclists. Full suspension fat bikes command premium positioning among adventure enthusiasts tackling technical trail riding terrain where rear shock absorption improves traction and control. Carbon fiber frame material adoption is accelerating among professional athletes seeking reduced rotational mass for competitive snow racing events.
FDA oversight applies to wearable biometric sensors increasingly integrated into handlebar-mounted displays on e-fat bikes, while FCC regulations govern the radio frequency emissions of Bluetooth-connected pedal-assist controllers. The Consumer Product Safety Commission enforces mechanical safety standards that manufacturers must satisfy before interstate commerce. Stakeholders must monitor how state-level e-bike classification laws in the US fragment throttle-assist legality and determine where Class 3 speed limitations constrain product specification for commuter-oriented builds.
Market Dynamics
The fat bike market pivots on the collision between CE marking compliance costs under the EU Machinery Directive and the rapid integration of pedal-assist electric drivetrains into formerly mechanical product lines.
Growth Catalysts
- Adventure tourism fleet expansion:Nordic operators in Finland and Norway are doubling seasonal rental inventories as public investment flows into groomed winter trail infrastructure.
- E-bike classification harmonization:State-level Class 1-3 frameworks in the United States are clarifying throttle-assist legality and unlocking commuter-oriented specification for urban builds.
- ISO 4210 frame safety adoption:Standardized structural testing protocols are reducing liability exposure and accelerating insurance underwriting for commercial rental deployments.
Market Restraints
- Aluminum rim supply concentration:Southeast Asian forging capacity bottlenecks are transmitting volatility into component pricing for entry-level hardtail assemblies.
- CE marking cost barrier:European Union Machinery Directive certification expenses disproportionately burden sub-scale assemblers seeking market access.
- Full suspension complexity:Rear shock tuning requirements and maintenance intervals limit adoption among recreational cyclists lacking technical aptitude.
Strategic Opportunities
- Alaska backcountry access expansion:Federal land management agencies are permitting mechanized winter travel on previously restricted Bureau of Land Management terrain.
- Biometric sensor convergence:Wearable heart-rate and power-meter integration with handlebar displays is creating premium specification tiers for athletic training segments.
- Direct-to-consumer channel maturation:Bypassing traditional bike shop markups through controlled digital distribution is compressing price points for e-fat bike entry models.
Industry Challenges
- FCC certification timelines:Radio frequency emissions testing for Bluetooth-connected pedal-assist controllers is extending product launch cycles by four to six months.
- Cold-climate battery engineering:Lithium-ion cell performance degradation below negative twenty degrees Celsius requires thermal management systems that add weight and cost.
- Frame welding skill scarcity:Fat bike-specific bottom bracket and chainstay geometries demand specialized aluminum and carbon fiber fabrication expertise concentrated in Minnesota and Taiwan manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Bike Market |
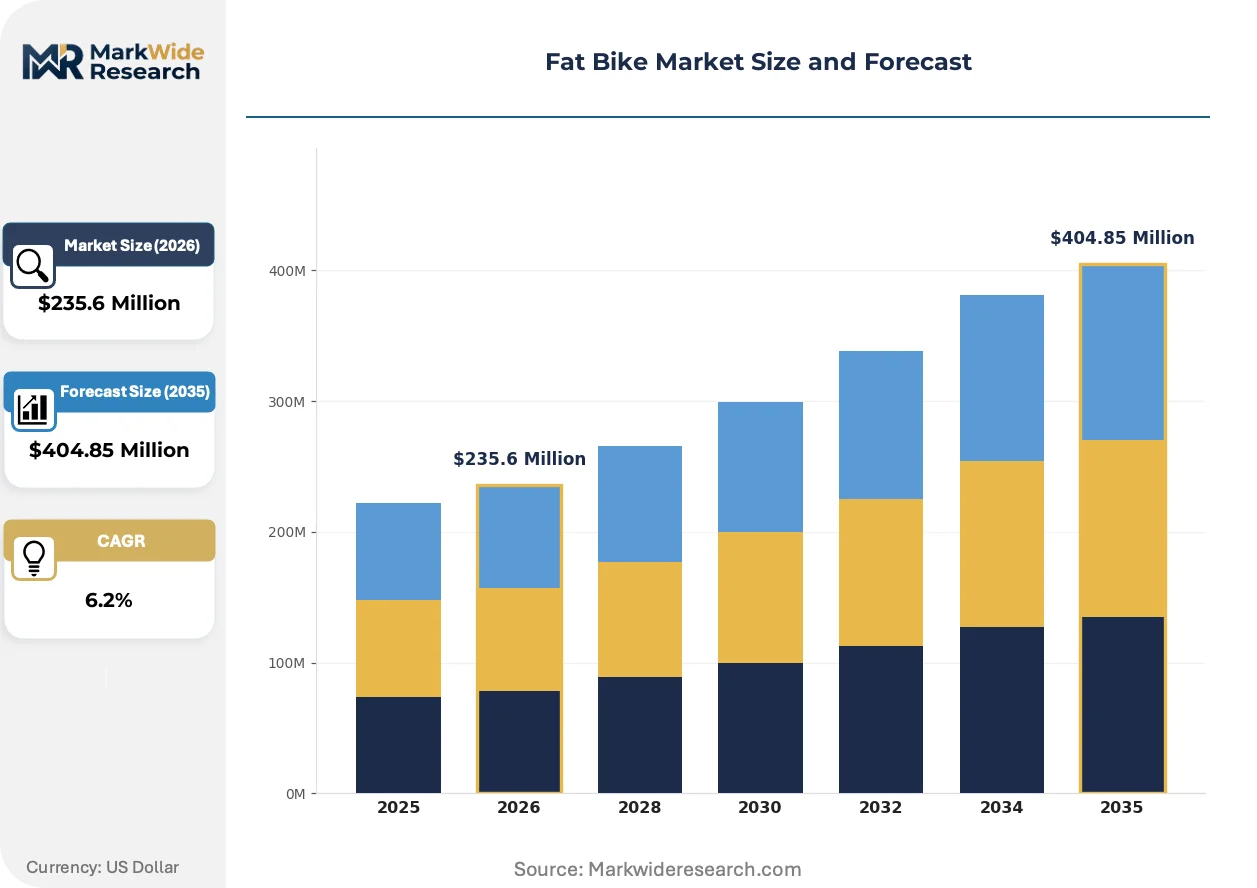
| Market Size in 2026 | $235.6 Million |
| Market Size in 2035 | $404.85 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Full Suspension, Hardtail, Folding Frame Material: Aluminum, Carbon Fiber, Steel, Titanium Use Case: Snow Riding, Sand Terrain, Urban Commuting, Trail Riding End User: Recreational Cyclists, Adventure Enthusiasts, Commuters, Professional Athletes |
| Companies Covered | 9:Zero:7, Aventon, Surly Bikes, Lectric eBikes, Rad Power Bikes, Borealis Fat Bikes, Velotric, Mokwheel, Salsa Cycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Bike Market Shifts & Advancements
Electrification is compressing the traditional segmentation between pedal-only recreational products and powered commuter builds, while regulatory fragmentation across jurisdictions is forcing modular platform architectures.
Mid-drive torque sensor technology is automating power delivery mapping to terrain gradient and rider cadence. Adventure tourism operators in Alaska and Colorado are specifying these systems for rental fleets to reduce mechanical support burdens. The technology is automating the elimination of throttle-dependent rider education and reducing incident liability exposure.
CE marking enforcement under the EU Machinery Directive is mandating third-party frame integrity and electrical system certification before customs clearance. European assemblers are absorbing compliance costs into premium pricing tiers while smaller importers exit the market. E-fat bike categories face the steepest compliance burden due to dual mechanical and electrical testing requirements.
Seasonal rental procurement is consolidating around multi-year fleet agreements with integrated maintenance and mid-season component refresh clauses. Nordic tourism cooperatives in Finland are negotiating volume commitments that displace single-unit retail purchases. This pattern concentrates most visibly in Rovaniemi and Tromsø where winter sports infrastructure investment has matured.
Fat Bike Market Segmentation
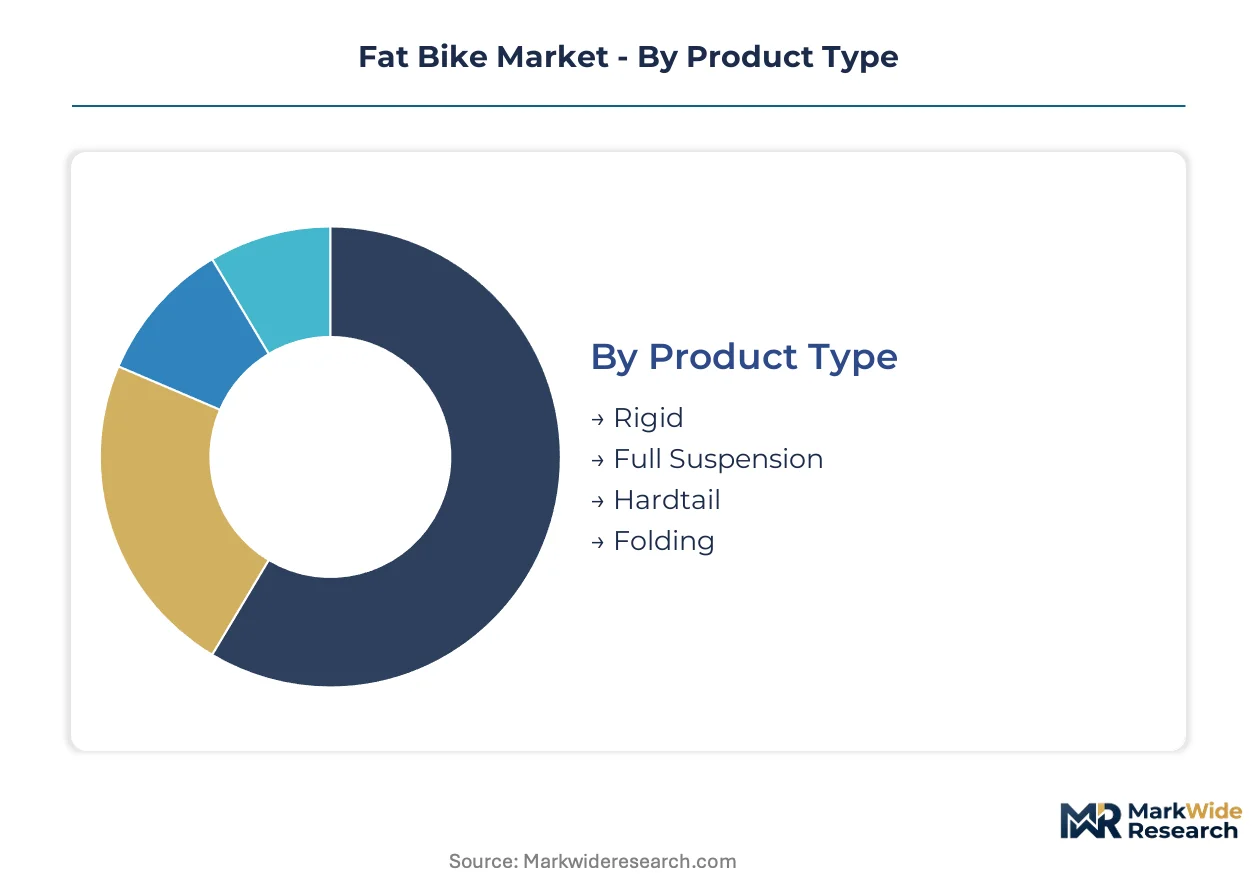
Segmentation in the fat bike market reveals how tire width, frame geometry, and powertrain configuration map to distinct terrain demands and rider skill levels. Manufacturers configure product lines around these boundaries to optimize inventory turns and margin capture across seasonal purchase windows.
Product Type:
Standardization dominates at the entry tier while customization concentrates in premium builds where suspension travel and foldability command price premiums.
- Hardtail:Combines a rigid front fork with rear frame flexibility, using widened bottom bracket shells to accommodate 4-5 inch tires. Fleet procurement by Nordic tourism operators in Finland and Norway concentrates here due to simplified field maintenance protocols and lower per-unit capital outlay for seasonal rental rotations.
- Full Suspension:Integrates front and rear shock absorption with linkage-driven rear triangle movement to maintain tire contact across technical snow and rock terrain. Colorado and Alaska backcountry tour operators specify these for guided technical descents where traction consistency reduces incident liability and guest skill requirements.
- Rigid:Eliminates suspension components entirely, reducing weight and mechanical failure points for groomed trail cruising. Popular among Minnesota-based winter commuters on plowed lake paths.
- Folding:Incorporates frame hinges and quick-release couplers to collapse the wheelbase for vehicle trunk transport or seasonal storage. Gains traction among Anchorage residents with limited apartment storage.
Most installed capacity flows through Hardtail. Expansion is steepest in Full Suspension.
Frame Material:
Cost tier stratification separates commodity aluminum from performance-oriented carbon fiber and exotic metals.
- Aluminum:6061-T6 alloy tubing dominates volume production through hydroformed tube shaping that accommodates fat bike-specific chainstay clearances. Southeast Asian forging clusters supply rim and frame extrusions, though capacity constraints are transmitting volatility into entry-level assembly pricing.
- Carbon Fiber:Pre-preg layup and monocoque molding reduce frame weight below 1,200 grams for competitive snow racing where rotational mass reduction improves acceleration out of corners. Professional athletes in International Snow Bike Association events drive specification here.
- Steel:Chromoly tubing persists in custom frame builder niches and cargo-oriented builds where fatigue resistance outweighs weight penalties.
- Titanium:Cold-worked seamless tubing commands artisan pricing for corrosion resistance in coastal sand riding environments.
Volume production centers on Aluminum. Value capture concentrates in Carbon Fiber.
Use Case:
Application context determines tire pressure ranges, tread patterns, and accessory integration requirements.
- Snow Riding:Requires tire pressures below 8 PSI to maximize flotation on unconsolidated powder, with studded tire options for ice crust conditions. Alaska Bureau of Land Management trail expansions are mechanizing previously restricted winter terrain access.
- Trail Riding:Demands intermediate tire pressures and aggressive knob patterns for mixed dirt-snow conditions. Colorado Front Range municipalities are grooming multi-use paths that bridge seasonal usage.
- Sand Terrain:Prioritizes maximum tire volume and smooth center treads for beach and desert dune traversal. Concentrated in coastal tourism markets and Dubai desert safari operations.
- Urban Commuting:Favors lighter builds with fender and rack mounts, integrating e-bike drivetrains where Class 1-3 state frameworks permit throttle-assist legality.
Seasonal rental revenue concentrates in Snow Riding. Equipment refresh cycles run shortest in Urban Commuting.
End User:
Customer type segmentation aligns purchase frequency, service expectations, and upgrade pathways.
- Recreational Cyclists:Entry-level hardtail purchasers seeking winter fitness alternatives with minimal maintenance overhead. Price sensitivity drives direct-to-consumer channel preference.
- Adventure Enthusiasts:Full suspension and carbon fiber specification for backcountry multi-day trips requiring load-carrying capacity and technical descending confidence. Alaska and Colorado guide services target this cohort.
- Commuters:E-fat bike adoption for year-round urban transportation where snow removal infrastructure remains inconsistent. State-level classification laws in the US determine throttle-assist legality and speed limitation compliance.
- Professional Athletes:Custom geometry and component specification for International Snow Bike Association racing circuits. Sponsorship-dependent purchase cycles concentrate in Minnesota and Wisconsin training clusters.
Transaction volume flows through Recreational Cyclists. Margin concentration sits with Adventure Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frame welding specialists cluster in Minnesota and Taiwan manufacturing hubs, anchoring production capacity for fat bike-specific geometries. These workforce concentrations supply global assembly operations while regional demand patterns diverge around trail infrastructure investment and e-bike regulatory frameworks.
United States
Federal land management agencies in Alaska are permitting mechanized winter travel on previously restricted Bureau of Land Management terrain, expanding backcountry access for adventure tourism operators. State-level Class 1-3 e-bike classification laws in Colorado and Minnesota clarify throttle-assist legality for commuter builds. The Minneapolis-St. Paul metro anchors domestic manufacturing heritage and cold-climate rider communities.
Finland
Tourism cooperatives in Rovaniemi are negotiating multi-year fleet agreements with integrated maintenance clauses, displacing single-unit retail purchases. CE marking under the EU Machinery Directive rebalances import cost structures for European market access. Public investment flows into groomed winter trail infrastructure across Lapland.
Norway
Adventure operators in Tromsø are doubling seasonal rental inventories as Nordic winter sports infrastructure matures. ECHA chemical regulations govern frame coating and tire compound formulations for environmental compliance. The northern fjord regions concentrate tourism-dependent procurement volume.
Canada
Health Canada oversees wearable biometric sensor safety for handlebar-integrated displays on e-fat bikes. Provincial trail networks in British Columbia and Alberta expand groomed winter access for recreational ridership. The Pacific Northwest manufacturing corridor supplies aluminum forging capacity to North American assemblers.
Germany
KBA vehicle classification frameworks influence e-bike speed limitation compliance for commuter-oriented product specifications. REACH chemical regulations constrain tire compound and frame coating formulations for EU market entry. The Bavarian and Baden-Württemberg industrial clusters host precision component suppliers for drivetrain systems.
Fat Bike Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between heritage bicycle manufacturers, direct-to-consumer digital natives, and component-integrated assemblers. Three archetypes dominate: cold-climate heritage brands leveraging geographic credibility, digitally native disrupters compressing price points through channel control, and e-bike specialists converging biometric and electric drivetrain technologies. Competitive moves center on direct-to-consumer channel maturation and CE marking compliance absorption into premium pricing tiers.
Among heritage-positioned manufacturers, Surly Bikes and Salsa Cycles exemplify cold-climate credibility anchored in Midwestern manufacturing heritage. Rad Power Bikes and Velotric occupy positions within the direct-to-consumer vector, representing channel-control strategies that bypass traditional retail markups. Lectric eBikes and Aventon sit within the value-tier e-bike specialization archetype, competing aggressively on price positioning against legacy pedal-only alternatives. Mokwheel and Borealis Fat Bikes represent regional fabrication specialists with concentrated geographic identities. The 9:Zero:7 designation indicates a specialized technical positioning within premium performance segments.
| Leading Market Players |
|---|
| 9:Zero:7 |
| Aventon |
| Surly Bikes |
| Lectric eBikes |
| Rad Power Bikes |
| Borealis Fat Bikes |
| Velotric |
| Mokwheel |
| Salsa Cycles |
| Others |
Supply & Pricing Matrix
Captive aluminum forging capacity in Southeast Asian manufacturing clusters anchors both component availability and tiered pricing power for hardtail assemblies. This backward integration into rim and frame extrusions allows scaled assemblers to buffer entry-level price erosion while smaller competitors absorb volatile spot-market premiums.
Pricing Analysis
Bundled fleet-maintenance contracts versus unbundled retail transactions split pricing architectures across buyer segments. Three-tier pricing structure across premium, standard, and economy levels maps to frame material grades and e-bike drivetrain integration depth. CE marking certification costs for EU market entry concentrate pricing pressure on sub-scale European importers. Recreational cyclists exhibit highest price sensitivity, while adventure tourism operators prioritize total-cost-of-ownership calculations over per-unit acquisition costs.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale demand from price-sensitive recreational buyers, while traditional bike shop networks retain premium full-suspension specification. Taiwan, Vietnam, and China concentrate aluminum forging and carbon fiber layup capacity for frame and rim production. Supply chains draw from lithium-ion cell manufacturers in South Korea and Japan for e-fat bike battery packs. Single-source vulnerability around mid-drive torque sensor suppliers extends product launch timelines. Distribution runs through digital-native platforms for entry-tier hardtails and specialty retailers for performance builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Minnesota-based manufacturing heritage and Southeast Asian component sourcing exploits labor cost differentials and tariff exposure gaps. CE marking compliance burdens in Europe versus streamlined state-level e-bike classifications in the US create divergent market entry economics.
For Market Incumbents: Hedge against direct-to-consumer price compression by deepening captive supply of aluminum rim extrusions through Taiwan manufacturing partnerships. Absorb CE marking certification costs into premium e-fat bike pricing tiers to filter out sub-scale competitors. Channel control investments in digital distribution infrastructure defend margin position against Rad Power Bikes and Velotric.
For New Entrants and Emerging Players: Launch via direct-to-consumer platforms targeting Alaska and Colorado recreational cyclists with unbundled hardtail offerings below legacy retail markups. White-space concentration sits in folding fat bikes for urban storage-constrained buyers in Anchorage and Minneapolis-St. Paul. Biometric sensor integration with handlebar displays offers specification differentiation against pedal-only incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication specialists with concentrated cold-climate credibility because frame welding skill scarcity limits replication speed. Five-to-ten-year viability hinges on e-bike drivetrain convergence penetration rates. Signal to monitor: Bureau of Land Management permitting velocity for mechanized winter trail access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Compliance Investment | EU Machinery Directive certification unlocks customs clearance for e-fat bike categories. |
| Direct-to-Consumer Channel Expansion | Digital distribution bypasses bike shop markups and compresses entry-model price points. |
| Mid-Drive Torque Sensor Integration | Automated power delivery reduces rental fleet mechanical support burdens in Alaska. |
| Aluminum Forging Capacity Lock-in | Taiwan and Vietnam extrusion commitments buffer rim supply volatility for hardtail production. |
| Biometric Sensor Platform Development | FDA-regulated wearable integration creates premium specification tiers for athletic training segments. |
Research Methodology
Bottom-up tourism operator and commuter demand modeling reconciled against top-down frame manufacturing and component supply tracking forms the analytical core. Primary interviews with fleet procurement managers at Nordic adventure cooperatives, product directors at Minnesota-based assemblers, and regulatory affairs leads navigating CE marking pathways combined with secondary validation. Secondary sources include customs trade databases for aluminum rim imports, Bureau of Land Management permitting records, and state-level e-bike classification statutes. Triangulation across these vectors ensures demand-side and supply-side estimates converge.
Historical trendline analysis of hardtail versus full suspension shipment patterns informed segmentation-level growth trajectories across the projection horizon. Modeled dimensions span product type, frame material grade, use case application, and end user archetype. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and infrastructure investment cycles. Industry-specific forecast inputs include groomed trail network expansion timelines and lithium-ion cell thermal management cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Bureau of Land Management access policy reversals or ECHA chemical restriction escalations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Hunting Rangefinder Market