
 Hammocks Market | 2026-2036
Hammocks Market Size, Share, and Industry Trends Forecast 2026-2036
Hammocks Market Outlook
Asset-light direct-to-consumer leasing models is narrowing the capital barrier for new entrants in the hammocks sector. Kammok leverages its B Corp certification to anchor premium positioning among sustainability-focused buyers. REI Co-op sustains channel dominance through its member-owned cooperative structure and controlled retail footprint. Hennessy Hammock specializes in integrated shelter systems that command technical loyalty among backcountry users.
A hammock is a suspended fabric or netting sling suspended between two anchor points, typically woven from cotton, nylon, or canvas in densities ranging from lightweight 70D ripstop to heavy 12-ounce duck cloth, engineered to distribute occupant weight across lateral suspension lines for reclining or sleeping applications. Camping hammocks lead volume due to ultralight portability demands, while lounger hammocks capture margin pools through higher unit economics in residential settings. Nylon dominates technical segments for its strength-to-weight ratio, though cotton retains structural importance in artisanal and premium decorative channels where breathability and natural texture drive selection.
FDA textile contact standards, EPA chemical treatment regulations for flame-resistant coatings, and ISO 9001 quality management frameworks collectively shape product safety benchmarks and market access thresholds for hammock manufacturers. The EU Green Deal's textile sustainability requirements are forcing supply chain documentation upgrades across European import channels. Stakeholders must monitor evolving chemical disclosure mandates and decide whether to front-load compliance investment or redirect volume toward less regulated regional markets.
Market Dynamics
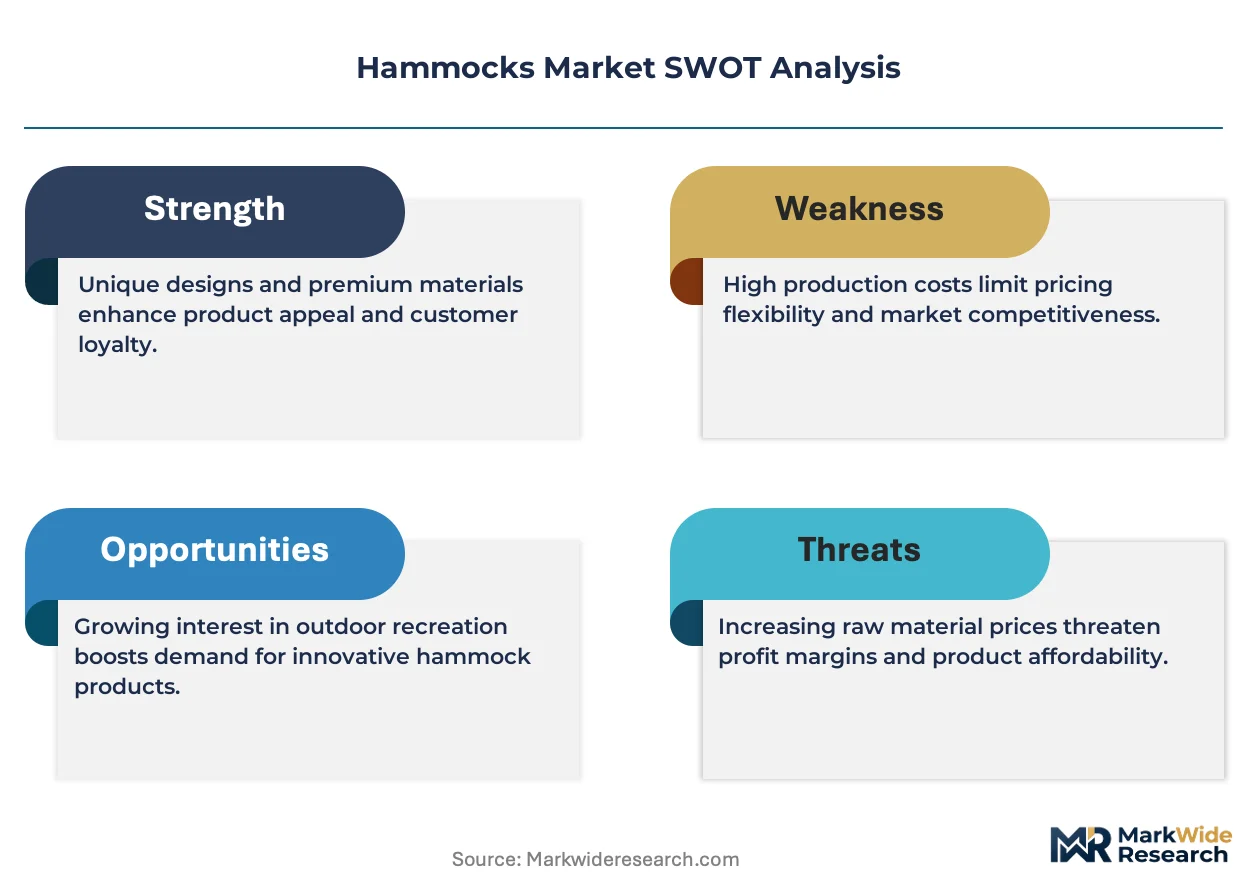
REACH chemical standards in Europe are forcing synthetic fabric substitution toward certified organic cotton supply chains, compressing margins for non-compliant producers while rewarding certified organic cotton suppliers with preferential channel access.
Growth Catalysts
- Backyard leisure installations:Residential outdoor space investment is pulling demand upward as homeowners prioritize permanent relaxation infrastructure over temporary recreational equipment.
- REACH compliance migration:European chemical disclosure mandates are accelerating certified organic cotton adoption, creating differentiation premiums for compliant supply chains.
- Artisanal weaving clusters:Ceará state production concentration in Brazil anchors export volume and sustains handcrafted positioning in premium decorative channels.
Market Restraints
- Organic cotton input cost volatility:Certified fiber premiums fluctuate with climate-driven yield uncertainty, compressing margin stability for brands committed to natural materials.
- Synthetic fabric supply concentration:Nylon technical yarn production clusters in East Asian petrochemical corridors create geopolitical exposure for ultralight camping segment suppliers.
- Flame-resistant coating technical limitations:EPA chemical treatment regulations constrain durable water-repellent chemistry options, limiting weatherproofing performance in technical applications.
Strategic Opportunities
- Asset-light direct-to-consumer leasing:Subscription rental models reduce capital barriers for new entrants while capturing recurring revenue from occasional-use residential buyers.
- EU Green Deal textile sustainability requirements:Supply chain documentation upgrades create first-mover advantage for brands with established organic certification and traceability systems.
- Integrated shelter system convergence:Hammock-tent hybrid designs with bug netting and rainfly integration are capturing technical loyalty among backcountry users seeking multi-functional equipment.
Industry Challenges
- ISO 9001 quality management certification timelines:Documentation and audit requirements delay market entry for new manufacturers, favoring incumbent suppliers with established frameworks.
- Legacy retail inventory integration:Cooperative member-owned structures resist rapid assortment shifts, slowing speed-to-market for innovative product configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hammocks Market |
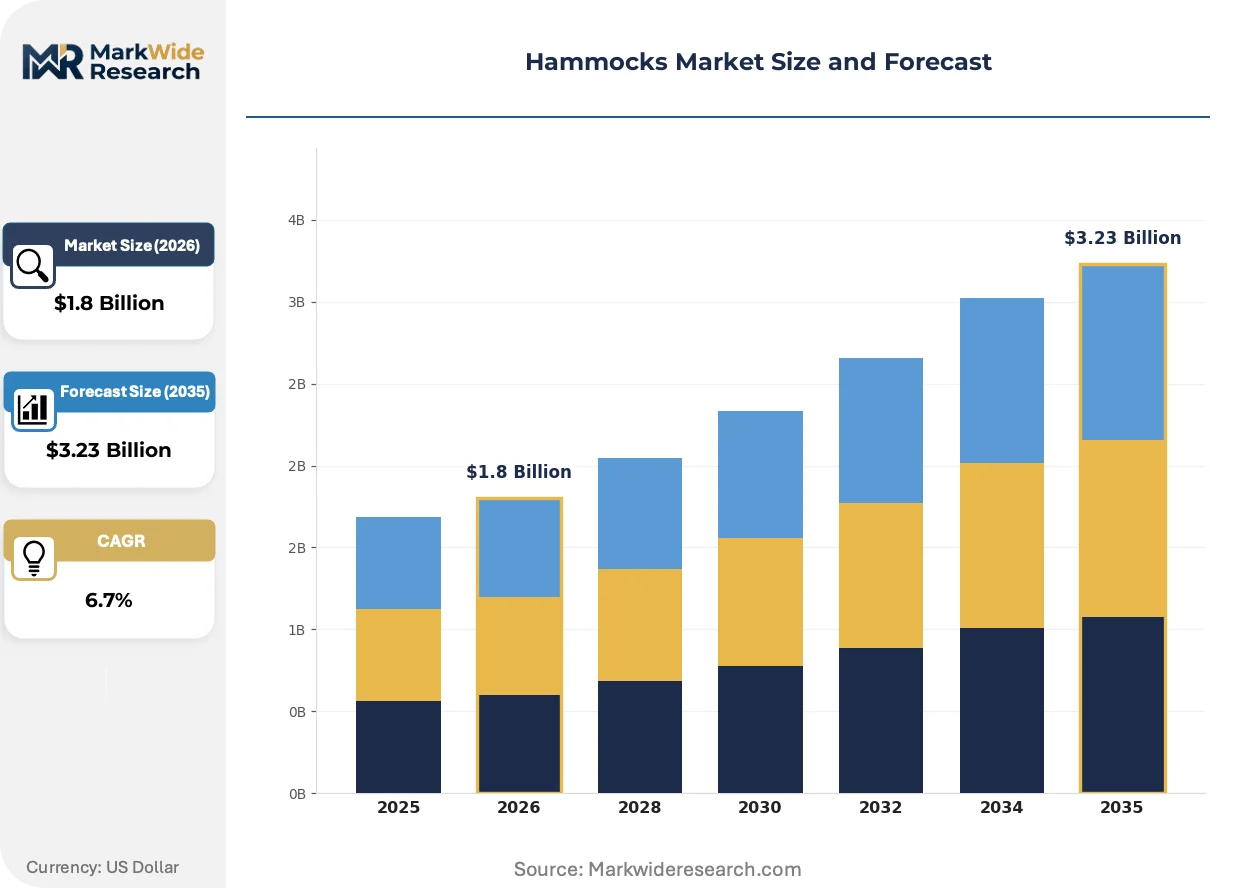
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camping Hammocks, Portable Hammocks, Double Hammocks, Lounger Hammocks Material: Nylon, Cotton, Polyester, Canvas Usage: Backyard, Camping, Outdoor Events, Travel Age Group: Adults, Kids, Teens, Seniors |
| Companies Covered | Eagles Nest Outfitters, Grand Trunk, REI Co-op, The Hammock Source, Wise Owl Outfitters, Kammok, La Siesta, Lawson Hammock, Hennessy Hammock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hammocks Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to reshape competitive positioning across technical and decorative segments simultaneously.
Ultralight ripstop nylon with 70D density ratings dominates technical camping applications for its strength-to-weight ratio and packability. Backcountry equipment buyers are migrating from traditional tent systems toward hammock-based shelter configurations that reduce ground impact and expand site selection flexibility. This shift is compressing demand for conventional backpacking tents while expanding the addressable market for integrated suspension and weather protection accessories.
The EU Green Deal's textile sustainability requirements are forcing supply chain documentation upgrades across European import channels. Manufacturers must now certify fiber origin, chemical treatment compliance, and carbon intensity metrics to maintain market access. Decorative and artisanal segments face the steepest compliance burden due to fragmented supplier bases and limited traceability infrastructure in traditional weaving clusters.
Rental and subscription models are displacing outright ownership among urban consumers with limited storage space and intermittent outdoor recreation patterns. Direct-to-consumer platforms with flexible return policies and seasonal rotation options are capturing residential buyers who prioritize experience access over asset accumulation. This behavioral shift is most visible in North American and Western European metropolitan markets where housing density constrains equipment storage capacity.
Hammocks Market Segmentation
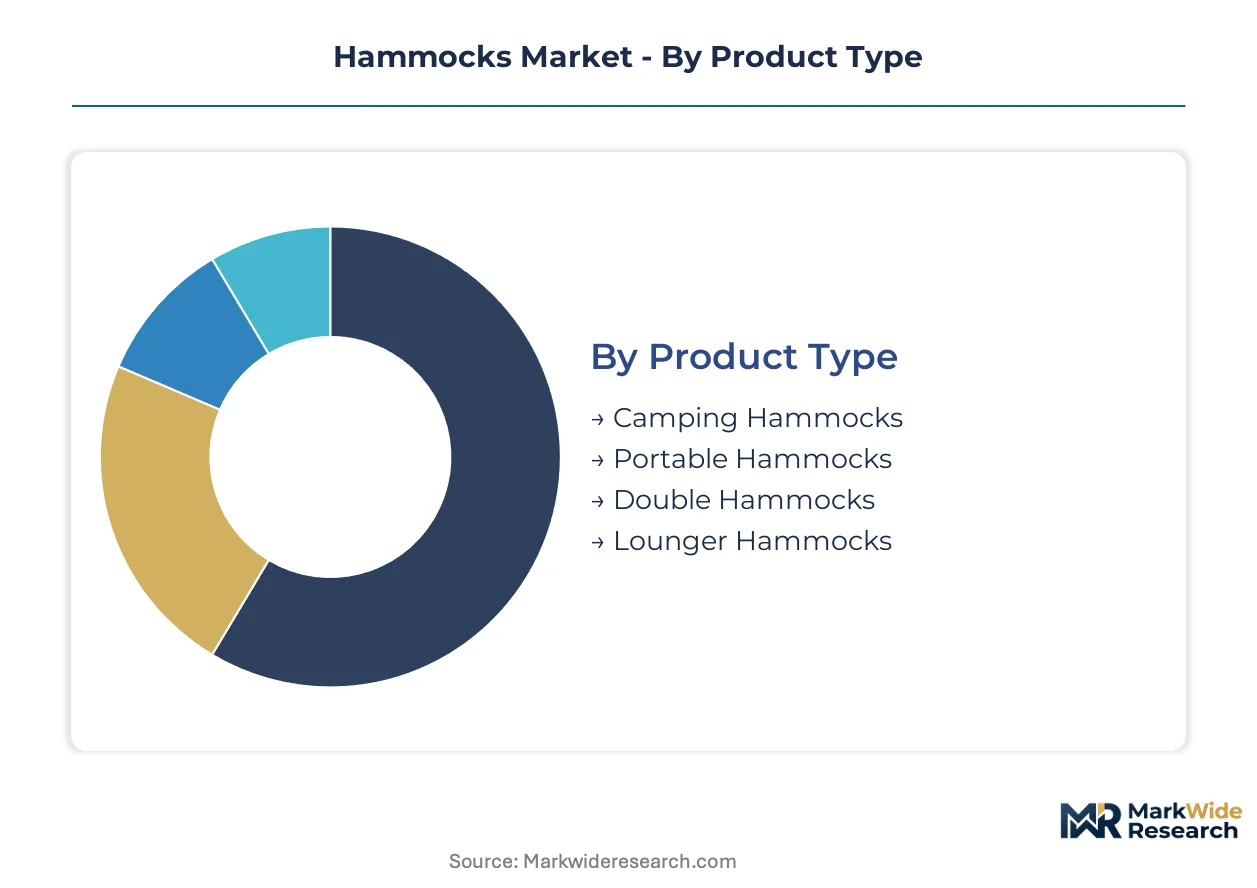
Segmentation in the hammocks market reveals distinct service and replacement cycles across product configurations. Material durability, suspension hardware wear rates, and seasonal usage patterns create divergent aftermarket revenue opportunities that shape manufacturer go-to-market economics.
Product Type:
After-sales-service intensity varies sharply across product architectures, with integrated shelter systems demanding technical support while simple fabric slings require minimal intervention.
- Camping Hammocks:Ultralight ripstop nylon construction with 70D density ratings delivers strength-to-weight ratios essential for backcountry load constraints. Demand concentrates among Appalachian Trail through-hikers and Pacific Crest Trail users where pack weight reduction drives equipment selection. Replacement intervals compress under heavy use, creating recurring revenue from suspension strap and carabiner refresh cycles.
- Lounger Hammocks:Spreader-bar designs with quilted fabric surfaces command premium positioning in residential outdoor furniture channels. Brazilian Ceará state weaving clusters supply handcrafted variants to North American patio retailers where permanent backyard installation trends sustain replacement demand. Aftermarket intensity peaks with seasonal cushion and canopy refresh purchases.
- Portable Hammocks:Collapsible aluminum frame systems with integrated carry cases target festival attendees and beach recreation users. Compact packed dimensions compete with traditional folding chairs for vehicle trunk space.
- Double Hammocks:Reinforced suspension lines and wider fabric spans accommodate dual occupancy in couple-oriented camping and glamping applications. Weight capacity ratings of 400+ pounds differentiate from single-occupancy alternatives.
By volume, Camping Hammocks leads. By growth pace, Lounger Hammocks is gaining share fastest.
Material:
Cost tier stratification separates commodity synthetics from certified organic supply chains, with compliance documentation burden concentrated in premium natural fiber segments.
- Nylon:Technical yarn with high tenacity-to-weight ratios dominates ultralight camping equipment where every ounce determines route feasibility. East Asian petrochemical corridors concentrate production, exposing brands to geopolitical supply disruption. REACH-compliant variants with reduced chemical treatment portfolios command price premiums in European import channels.
- Cotton:Breathable natural fiber with artisanal texture retention anchors decorative and premium residential positioning. Ceará state cooperative weaving networks in Brazil maintain handcrafted supply chains despite EU Green Deal documentation requirements. Climate-driven yield volatility in Texas and India creates input cost instability for certified organic grades.
- Polyester:UV-resistant synthetic with colorfast properties suits permanent outdoor installation where sun exposure degrades natural alternatives. Lower unit costs enable mass-market penetration.
- Canvas:Heavy duck cloth construction delivers durability for military surplus heritage positioning and hunting camp applications. Weight penalties exclude from portable segments.
By volume, Nylon leads. By growth pace, Cotton is expanding most quickly.
Usage:
Application context determines suspension hardware specifications, weatherproofing requirements, and replacement frequency patterns that differentiate margin profiles.
- Backyard:Permanent anchor installations with decorative stand systems capture residential outdoor living investment trends. Seasonal cushion and canopy refresh cycles sustain aftermarket revenue. Brazilian handcrafted imports compete with domestic mass-market alternatives on texture authenticity.
- Camping:Ultralight portable configurations with tree-strap suspension systems reduce ground impact and expand site selection flexibility. Integrated bug netting and rainfly accessories command technical loyalty among backcountry users.
- Outdoor Events:Rental fleet deployment at music festivals and corporate gatherings drives commercial procurement with high turnover and damage replacement rates.
- Travel:Compact packable designs with integrated carry systems target digital nomads and hostel accommodation markets where luggage constraints dominate equipment selection.
By volume, Backyard leads. By growth pace, Camping is climbing the fastest.
Age Group:
Customer type segmentation reveals divergent safety certification requirements and price sensitivity thresholds that shape product development priorities.
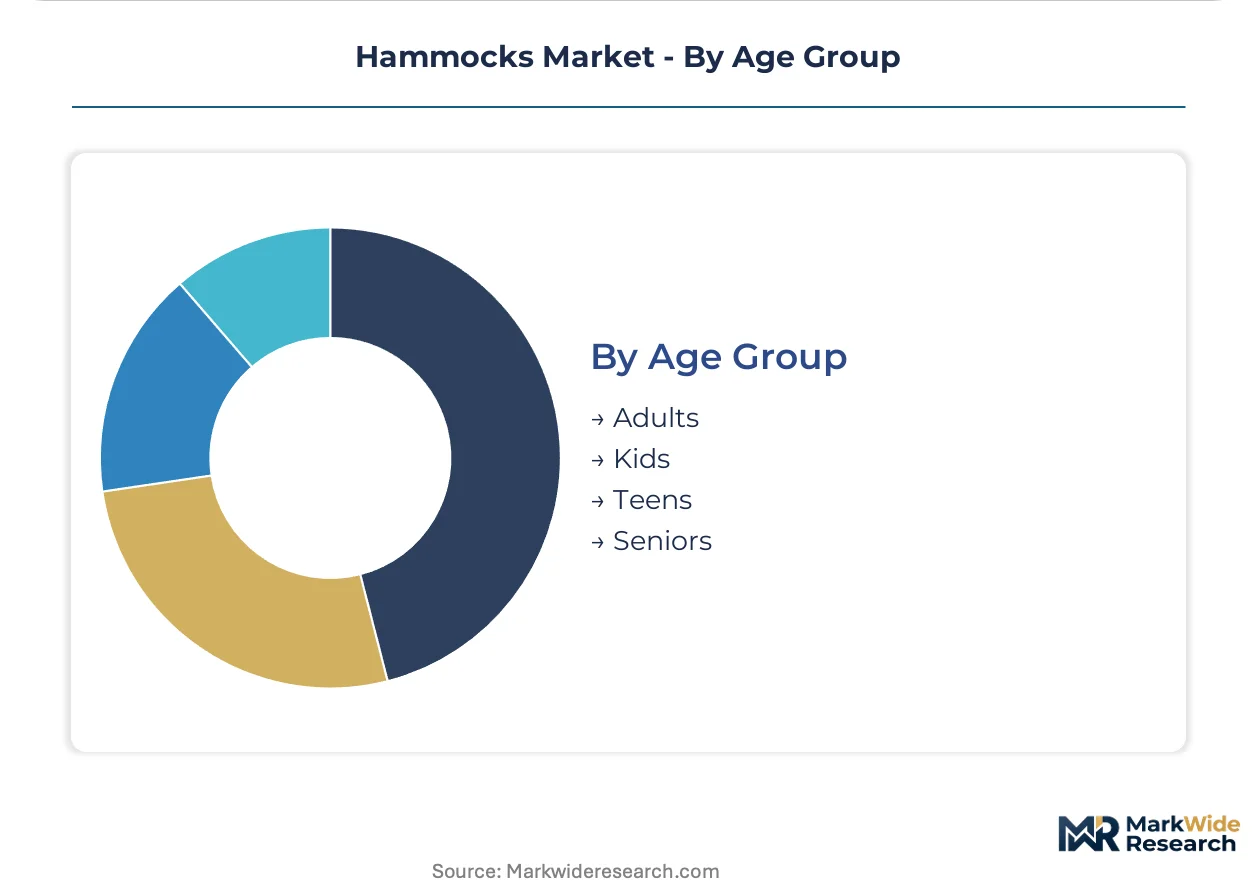
- Adults:Primary revenue concentration across all product categories with full weight capacity utilization and technical feature adoption. Occupational health considerations in workplace wellness programs drive institutional procurement.
- Kids:Elevated safety standards with enclosed designs and lower suspension heights dominate product specifications. CPSC compliance documentation requirements extend development timelines.
- Teens:Social media-driven aesthetic preferences influence colorway and pattern selection with peer endorsement effects on brand perception.
- Seniors:Accessibility-focused designs with higher seat heights and grab-bar integration address mobility limitations in aging populations.
By volume, Adults leads. By growth pace, Seniors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Brazil's Ceará state as the dominant net exporter of handcrafted hammocks, while the United States and Germany absorb premium volumes through direct-to-consumer channels and specialty retail cooperatives respectively.
Brazil
Artisanal weaving clusters in Ceará state anchor global handcrafted hammock supply, with Fortaleza metro exporters shipping certified organic cotton variants to North American patio retailers. ANVISA textile contact standards govern domestic safety certification, though REACH compliance documentation burdens European-bound shipments. Cooperatives in Jaguaribe Valley sustain traditional hand-knotting techniques despite EU Green Deal traceability mandates.
United States
Backyard leisure installations drive residential demand across suburban markets, with REI Co-op's member-owned cooperative structure dominating specialty retail distribution. EPA chemical treatment regulations constrain flame-resistant coating formulations for camping equipment. Appalachian Trail corridor communities in Virginia and North Carolina concentrate ultralight gear retail density and trail-testing culture.
Germany
EU Green Deal textile sustainability requirements force supply chain documentation upgrades for imported hammocks, favoring brands with established organic certification. ECHA REACH enforcement creates preferential channel access for compliant suppliers. Stuttgart region outdoor equipment distributors serve as European logistics hubs for premium camping hammock imports.
China
East Asian petrochemical corridors concentrate nylon technical yarn production for ultralight camping segments, exposing brands to geopolitical supply disruption risk. MIIT industrial standards govern synthetic fiber manufacturing quality. Yangtze River Delta fabric mills supply ripstop nylon to global camping equipment assemblers.
United Kingdom
Subscription rental models capture urban consumers with limited storage space in London and Southeast England metropolitan markets. Trading Standards Institute oversees product safety compliance for textile contact applications. Cotswolds-based glamping operators drive commercial procurement of double-occupancy lounger configurations.
Hammocks Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base spans cooperative retail structures, direct-to-consumer platforms, and artisanal weaving networks without dominant consolidation. Three archetypes prevail: member-owned cooperatives with controlled retail footprints, B Corp-certified sustainability premiums, and technical shelter system specialists. Competitive moves center on EU Green Deal compliance documentation and integrated shelter-tent hybrid development.
Within the cooperative retail tier, REI Co-op exemplifies member-owned channel dominance, while Kammok occupies a position among B Corp-certified sustainability premiums. Hennessy Hammock anchors the technical shelter system specialist archetype with integrated rainfly and bug netting configurations.
| Leading Market Players |
|---|
| Eagles Nest Outfitters |
| Grand Trunk |
| REI Co-op |
| The Hammock Source |
| Wise Owl Outfitters |
| Kammok |
| La Siesta |
| Lawson Hammock |
| Hennessy Hammock |
| Others |
Value Chain & Pricing Dynamics
Ceará state's artisanal weaving clusters in Brazil anchor handcrafted hammock supply capacity, with Fortaleza metro exporters translating limited organic cotton availability into premium pricing power over North American patio retailers. REACH-compliant certified organic cotton commands tiered premiums across European import channels, while East Asian petrochemical corridors compress synthetic fiber pricing through concentrated nylon technical yarn output.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for volume camping equipment procurement. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and geographic delivery cost, with EU Green Deal documentation burdens compressing margins for non-compliant producers. Cost compression in standard-grade synthetic segments is intensifying because of East Asian capacity expansion. Specialty retailers demonstrate least price sensitivity due to member-owned cooperative structures, while mass-market distributors exhibit highest sensitivity to freight cost fluctuations.
Supply Chain Analysis
Petrochemical feedstock from Yangtze River Delta mills draws from concentrated East Asian corridors for ripstop nylon technical yarn, while Ceará state cooperative networks source certified organic cotton from climate-vulnerable Texas and Indian growing regions. Geographic supply concentration spans Brazil, China, and Vietnam for finished assembly. Single-source vulnerability in 70D ripstop nylon production creates geopolitical exposure for ultralight camping segment suppliers. Distribution runs through member-owned cooperative retail structures and direct-to-consumer platforms with seasonal rotation logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated specialty retail cooperatives with controlled assortment authority, fragmenting pricing leverage among upstream suppliers. Cooperative member-owned structures now command slotting fee negotiations and exclusive product development access.
For Market Incumbents: Pre-empt emerging asset-light direct-to-consumer leasing platforms by securing exclusive supply agreements with Brazilian Ceará weaving cooperatives for certified organic cotton allocation. Invest in ISO 9001 quality management documentation ahead of EU Green Deal enforcement timelines to defend channel access against compliant competitors. Vertical integration into suspension hardware manufacturing mitigates carabiner and strap supplier concentration risk. For New Entrants and Emerging Players: Metropolitan UK subscription rental markets with limited residential storage penetration offer lowest competitive density for direct-to-consumer platform entry. Target senior-oriented accessibility designs with higher seat heights and grab-bar integration as fastest-expanding age demographic with unmet product configuration availability. Deploy asset-light leasing models with flexible seasonal rotation policies to capture occasional-use residential buyers without inventory carrying cost burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated shelter system specialists with technical loyalty and accessory refresh cycles. Long-term viability across the projection horizon favors manufacturers with established organic certification and traceability infrastructure capable of serving EU import channels. Monitor ECHA REACH enforcement intensity as inflection indicator for compliant supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Compliance Documentation | Establishes preferential channel access for certified organic cotton suppliers in ECHA-regulated markets. |
| Integrated Shelter System Development | Captures technical loyalty from Appalachian Trail and Pacific Crest Trail backcountry user segments. |
| Asset-Light Direct-to-Consumer Leasing | Reduces capital barriers while capturing recurring revenue from storage-constrained urban consumers. |
| Ceará Cooperative Supply Agreement | Secures handcrafted positioning and certified organic cotton allocation for premium decorative channels. |
| Senior Accessibility Design Extension | Addresses fastest-expanding age demographic with mobility-focused product configurations. |
Study Parameters
Desk research of customs trade records, SEC retailer filings, and ANVISA textile safety standards preceded structured interviews with brand managers at outdoor equipment manufacturers, category buyers at cooperative retail structures, supply planners at Brazilian weaving cooperatives, and aftermarket service heads at camping equipment distributors. Primary fieldwork with hammock suspension hardware suppliers and technical fabric mills validated secondary data on nylon ripstop density specifications and organic cotton yield volatility. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators across the analysis window.
Assumptions held fixed include REACH chemical disclosure enforcement timelines and EU Green Deal textile sustainability documentation requirements, while variables included climate-driven organic cotton yield fluctuations and East Asian petrochemical corridor capacity utilization. Segmentation dimensions modeled encompass product architecture, material certification grade, usage context, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and demand elasticity coefficients for residential outdoor furniture investment trends. Industry-specific forecast inputs incorporated Appalachian Trail through-hiker equipment replacement cycles and Brazilian cooperative export licensing velocity.
Practitioners should monitor ECHA enforcement intensity, climate-driven organic cotton yield reports, and cooperative retail inventory turnover rates for early signals requiring forecast revision. Cross-checking against REI Co-op member sales disclosures and Brazilian export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Fat Bike Market