
 North America Climbing Gears Market | 2026-2036
North America Climbing Gears Market Size, Share, and Industry Trends Forecast 2026-2036
North America Climbing Gears Market Insights
Indoor climbing gym chains is consolidating as the fastest-growing end-use vertical in North America, displacing traditional outdoor specialty retailers as the dominant procurement channel. Black Diamond Equipment leverages its Salt Lake City manufacturing base to anchor supply for Western US climbing destinations. Petzl Distribution competes through its vertical control over headlamp and ice tool technology, while Arc'teryx differentiates with premium apparel integration that extends brand loyalty into hardware categories.
North America climbing gears encompass ropes, harnesses, carabiners, and helmets engineered from high-tenacity nylon, Dyneema, and aircraft-grade aluminum alloys to arrest falls and protect against impact in vertical environments. The primary commercial purpose centers on life-safety functionality where UIAA fall ratings and CE certification gates determine market access. Ropes and harnesses command the deepest margin pools due to replacement cycles tied to fall history and UV degradation protocols, while helmets are accelerating fastest as gym mandates and guided-service liability requirements expand. Carabiners remain the most mature segment, with competition concentrating on gate-action refinement and weight reduction rather than fundamental design innovation.
ASTM International governs product testing protocols in the United States, while Canada's CSA Group maintains parallel standards that create dual-certification requirements for cross-border suppliers. The UIAA safety label functions as a de facto market-access filter, particularly for rope and helmet categories where gym operators and guide services mandate third-party validation. Stakeholders must monitor evolving state-level liability frameworks and insurance requirements that increasingly specify certified equipment for commercial operations.
Market Dynamics
Indoor climbing gym chains are consolidating procurement power as Olympic recognition drives facility expansion across the United States and Canada, shifting volume away from outdoor specialty retailers toward direct institutional contracts.
Growth Catalysts
- Sport climbing's Olympic inclusion:USA Climbing and Gymnastics Canada report membership surges that force gym chains to expand wall capacity and refresh hardware inventories on compressed timelines.
- ASTM F1772 harness standard updates:The revised fall-arrest testing protocol mandates replacement cycles for commercial operators, creating predictable refresh demand in the American West where gym density peaks.
- Dyneema fiber adoption:Ultra-high-molecular-weight polyethylene ropes and slashing slings cut weight by 30% versus nylon, compelling alpine guides and search-and-rescue units in the Canadian Rockies to upgrade kit.
Market Restraints
- Aluminum alloy supply concentration:Aircraft-grade 7075-T6 billet for carabiners concentrates with three North American mills, exposing hardware manufacturers to aerospace sector demand spikes and price volatility.
- Dual-certification burden:CSA Group and ASTM International maintain non-harmonized test protocols, forcing rope suppliers to run separate production batches for Canadian versus American gym contracts.
- Guided-service liability inflation:Commercial operators in California and Colorado face insurance premium escalations that compress equipment budgets and extend replacement intervals beyond manufacturer recommendations.
Strategic Opportunities
- Mexico's underpenetrated gym market:Guadalajara and Monterrey climbing facility counts lag per-capita penetration rates seen in Texas and Arizona, creating whitespace for equipment distributors with Spanish-language support infrastructure.
- Adaptive climbing hardware:Paraclimbing program expansion at national federations drives demand for seated harnesses, handle-style ascenders, and pulley systems engineered for amputee and wheelchair-using athletes.
- State-level physical education mandates:Colorado and Utah school districts now require climbing wall exposure in secondary curricula, opening institutional procurement channels distinct from commercial gym buyers.
Industry Challenges
- UIAA Safety Commission certification backlog:Rope and helmet manufacturers face 14-18 month approval queues that delay product launches and strand development capital in pre-revenue inventory.
- Technical rescue integration complexity:Fire departments and municipal SAR units demand hardware compatibility with existing rope systems, forcing suppliers to maintain legacy connector geometries alongside modern lightweight designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Climbing Gears Market |
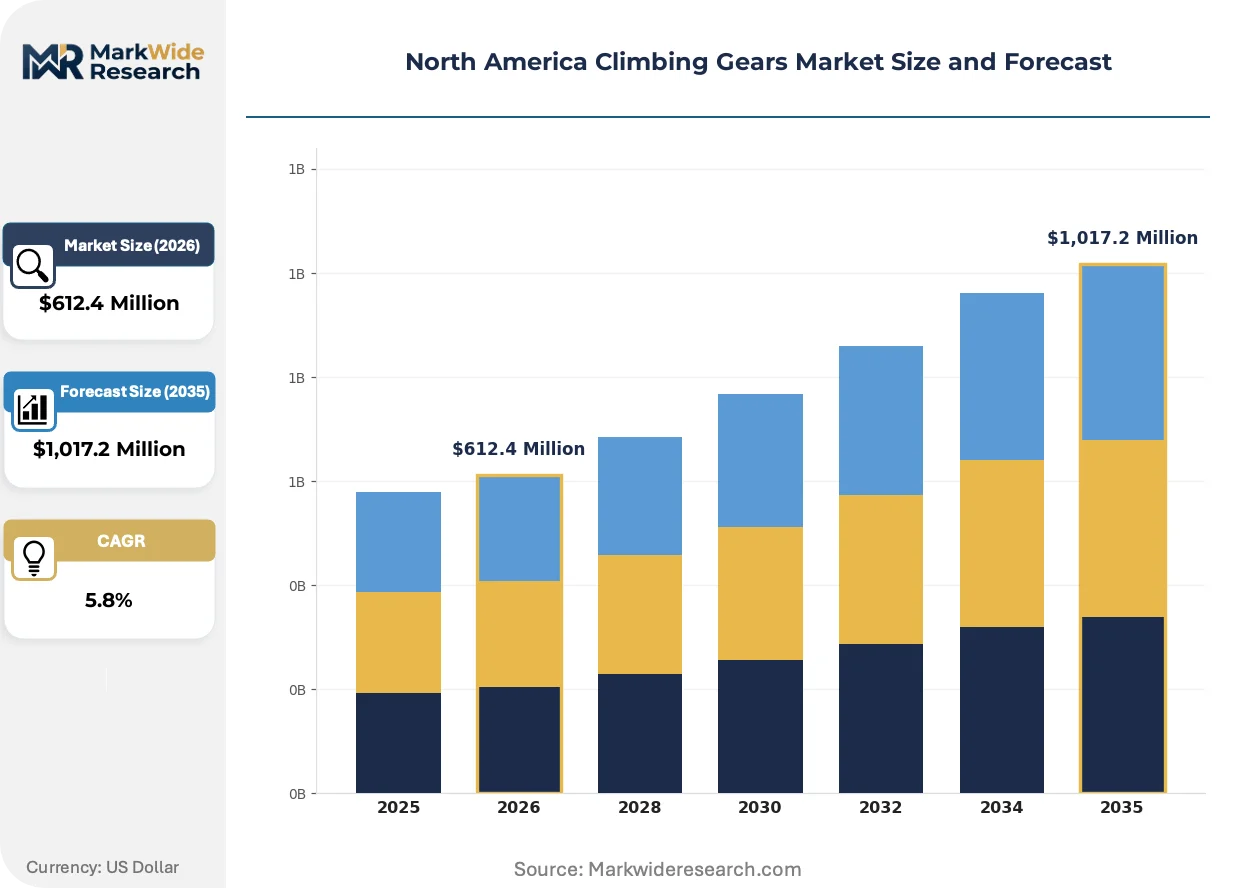
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ropes, Harnesses, Carabiners, Helmets Application: Mountaineering, Rock Climbing, Ice Climbing, Bouldering End User: Athletes, Hobbyists, Professionals, Instructors Distribution Channel: Online Retail, Specialty Stores, Sporting Goods, Distributors |
| Companies Covered | Petzl Distribution, Black Diamond Equipment, Arc'teryx, Mammut Sports Group, Camp USA, Metolius Climbing, Edelrid, Mad Rock Climbing, Trango, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Climbing Gears Market Trends and Innovations
Material science breakthroughs and certification protocol evolution are compressing product lifecycles while expanding the addressable user base beyond traditional outdoor enthusiasts into institutional and adaptive segments.
Recycled nylon yarn technology is electrifying rope manufacturing. Sterling Rope and BlueWater Ropes have shifted post-consumer fishing net and industrial textile waste into high-tenacity sheath fibers that match virgin nylon fall ratings. American gym chains now specify recycled-content minimums in RFPs, pressuring mid-tier Asian suppliers to certify traceability or lose bid eligibility.
ASTM International's pending update to F1163 helmet impact standards is tightening test velocity requirements from 5.0 to 5.5 meters per second. The revision responds to gym fall height increases as competition-style routes push 18-meter lead walls. Canadian operators anticipate parallel CSA Group alignment, forcing dual-stock helmet inventories through 2026 transition windows.
Buying committees at multi-location gym chains now bypass traditional outdoor retailers entirely. Vail Resorts' Epic Climb division and El Dorado Climbing Walls negotiate direct master service agreements with Black Diamond and Petzl, extracting volume discounts that specialty shops cannot match. This channel compression concentrates in Colorado's Front Range and California's Bay Area where chain consolidation runs deepest.
North America Climbing Gears Market Segmentation
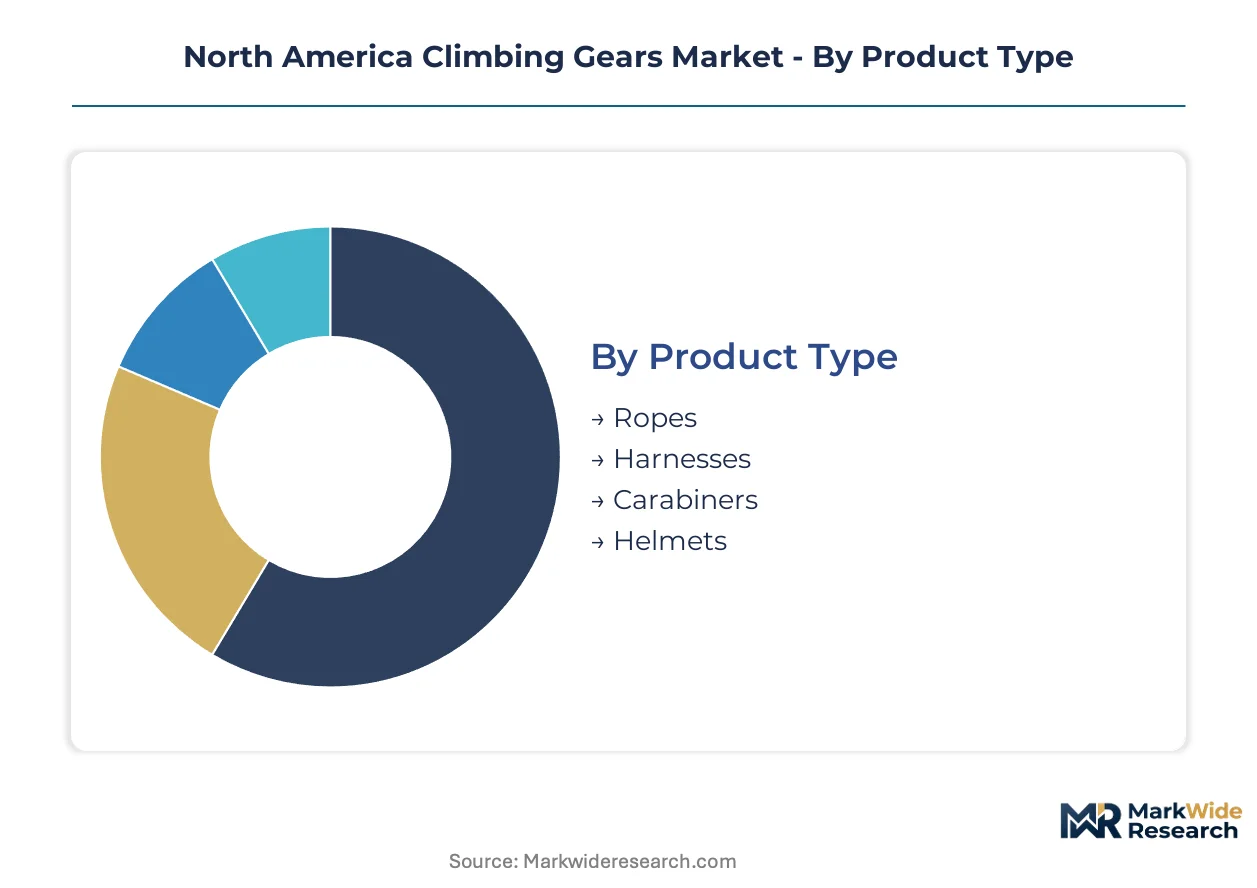
Replacement cycles and certification mandates create divergent demand profiles across product categories. Understanding segment-specific procurement patterns enables suppliers to align inventory with institutional refresh timelines and recreational upgrade behaviors.
Product Type:
Upgrade urgency varies sharply by fall-history protocols and UV degradation exposure, driving replacement premiums in gym-contracted categories versus extended lifecycles in personal-use hardware.
- Ropes:Dynamic kernmantle construction with nylon or Dyneema cores absorbs fall energy through controlled elongation. Colorado and Utah gym chains mandate retirement after five years regardless of visible wear, compressing replacement cycles for institutional buyers.
- Harnesses:Padded waist belts and leg loops distribute fall forces across the pelvis and upper thighs. ASTM F1772 harness standard updates force commercial operators in California to accelerate refresh schedules beyond manufacturer guidance.
- Carabiners:Aircraft-grade aluminum 7075-T6 or steel alloys form the load-bearing backbone of protection systems.
- Helmets:Expanded polystyrene or polypropylene liners absorb impact energy from falling rock or ground collisions.
Volume placements concentrate in Ropes; the faster expansion belongs to Helmets.
Application:
Cost tier stratification separates expedition-grade technical equipment from mass-market gym configurations, with pricing spreads reflecting certification depth and environmental exposure ratings.
- Mountaineering:High-altitude expeditions demand ice tools, crampons, and technical axes alongside core protection hardware. Canadian Rockies guide services in Alberta and British Columbia drive premium kit procurement with triple-redundancy requirements.
- Rock Climbing:Traditional and sport climbing rely on removable protection, fixed anchors, and rope systems for vertical rock faces. Arizona and Nevada crag communities sustain steady carabiner and quickdraw demand through weekend warrior traffic.
- Ice Climbing:Frozen waterfall ascents require specialized crampons, ice screws, and tubular belay devices.
- Bouldering:Low-altitude unroped climbing uses crash pads and chalk systems rather than life-safety hardware.
Revenue depth pools in Mountaineering; the steepest volume climb is occurring in Rock Climbing.
End User:
Customer type determines margin capture, with institutional procurement favoring multi-year service agreements and individual buyers showing higher accessory attachment rates.
- Athletes:Competition climbers and sponsored professionals demand weight-optimized equipment meeting IFSC specifications. USA Climbing cardholders in the American West drive concentrated demand for certified competition hardware.
- Hobbyists:Weekend recreational climbers balance cost sensitivity with safety certification requirements. Texas and Florida climbing gym memberships are expanding the hobbyist base fastest among Sun Belt states.
- Professionals:Certified guides and industrial rope access technicians require documented equipment histories.
- Instructors:Gym staff and outdoor education leaders need durable hardware withstands repetitive student use.
Unit economics favor Professionals; the broadest base expansion is happening among Hobbyists.
Distribution Channel:
Supply concentration in direct institutional contracts is displacing traditional retail intermediaries, particularly in markets where gym chain consolidation runs deepest.
- Online Retail:E-commerce platforms offer price transparency and breadth of technical specifications for informed buyers. REI and Backcountry serve remote climbers in Montana and Idaho lacking specialty store access.
- Specialty Stores:Staff expertise and fitting services justify premium pricing for technical footwear and harness selection. Colorado's Front Range cluster maintains the densest specialty store network per capita.
- Sporting Goods:Big-box retailers carry entry-level harnesses and shoes for trial participants.
- Distributors:Wholesale intermediaries stock commercial gym chains and municipal recreation departments.
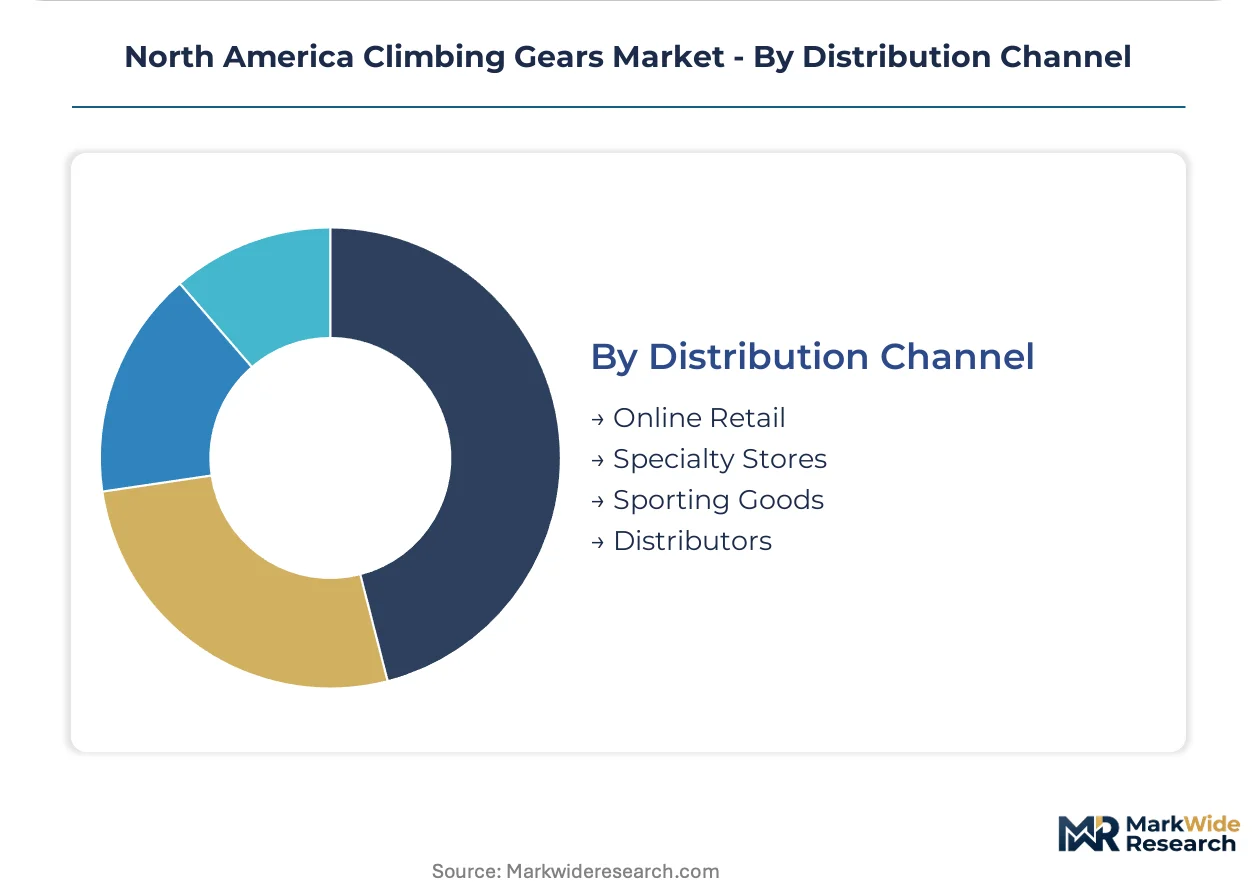
Transaction volume flows through Online Retail; the channel gaining share fastest is Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Colorado's Front Range and Utah's Wasatch Front concentrate climbing gear demand through tax-advantaged facility development. These zones anchor the densest gym chain expansion in North America.
United States
Colorado and California host the steepest gym construction pipelines as Olympic sport climbing medal counts drive youth program enrollment. ASTM International governs harness and helmet certification with F1772 and F1163 standards that mandate replacement cycles for commercial operators. Salt Lake City anchors Black Diamond Equipment's manufacturing base, supplying Western destinations from a single logistics hub.
Canada
Alberta and British Columbia guide services drive premium mountaineering kit procurement with triple-redundancy requirements for technical rescue operations. CSA Group maintains parallel certification standards to ASTM, creating dual-test burdens for rope suppliers serving cross-border gym chains. Canmore and Squamish clusters concentrate retail infrastructure for Canadian Rockies access.
Mexico
Guadalajara and Monterrey climbing facility counts lag per-capita penetration rates seen in Texas and Arizona border states. Mexico's national consumer protection agency enforces product safety labeling without harmonized climbing-specific protocols, creating import friction for certified hardware. Nuevo León's industrial corridor attracts distributors building Spanish-language support infrastructure for Latin American expansion.
North America Climbing Gears Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with life-safety hardware favoring in-house production while accessories tolerate outsourced fabrication. The market structures around three tiers: heritage alpine brands with vertical control over textile and metal production, gym-focused volume suppliers competing on replacement-cycle pricing, and regional assemblers serving municipal procurement channels. Consolidation pressure concentrates in the American West where direct institutional contracts displace retail intermediaries. Strategic moves center on Dyneema fiber integration and recycled-content certification to meet gym chain RFP requirements.
Among heritage alpine specialists, Petzl Distribution and Black Diamond Equipment exemplify divergent sourcing strategies—Petzl through French-controlled headlamp and ice tool technology, Black Diamond through Utah-based metal forging and textile finishing. Arc'teryx occupies a premium-tier position where apparel integration extends brand loyalty into hardware categories. These three represent distinct archetypes: European technology licensing, American manufacturing scale, and Canadian premium positioning.
| Leading Market Players |
|---|
| Petzl Distribution |
| Black Diamond Equipment |
| Arc'teryx |
| Mammut Sports Group |
| Camp USA |
| Metolius Climbing |
| Edelrid |
| Mad Rock Climbing |
| Trango |
| Others |
Pricing and Supply Chain Analysis
Dyneema fiber migration from niche alpine applications into mainstream gym rope production simultaneously compresses per-unit material costs and concentrates supply leverage with DSM's Dutch polymer facilities and their licensed North American textile finishers. This technology shift forces mid-tier manufacturers to absorb certification premiums or cede share to vertically integrated competitors with captive Dyneema access.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply for UIAA-certified rope batches delivered inside standard fourteen-month approval queues, while spot inventory of legacy nylon constructions trades at distressed levels. Three-tier pricing structure across premium Dyneema-core, standard nylon, and economy recycled-sheath tiers differentiates primarily by fall-rating certification depth and gym-mandated replacement protocols. Pricing pressure stems from aluminum alloy billet cost volatility driven by aerospace sector demand spikes, compressing margins for carabiner specialists without long-term mill contracts. Hobbyist buyers through online retail channels exhibit highest price elasticity, while institutional gym chains prioritize total-cost-of-ownership calculations incorporating replacement-cycle predictability.
Supply Chain Analysis
Freight cost absorption for cross-border Canadian shipments adds eight to twelve percent to landed rope costs, incentivizing Salt Lake City and Denver distribution hub investments. Aircraft-grade 7075-T6 aluminum billet concentrates with mills in Pennsylvania, Ohio, and Quebec, while Dyneema fiber draws exclusively from DSM's Greenville, North Carolina finishing plant and Dutch source polymer. Single-source vulnerability in UIAA Safety Commission certification testing creates fourteen-month product launch delays that strand working capital. Distribution runs through direct master service agreements with multi-location gym chains, bypassing traditional outdoor specialty retail intermediaries in Colorado's Front Range and California's Bay Area markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
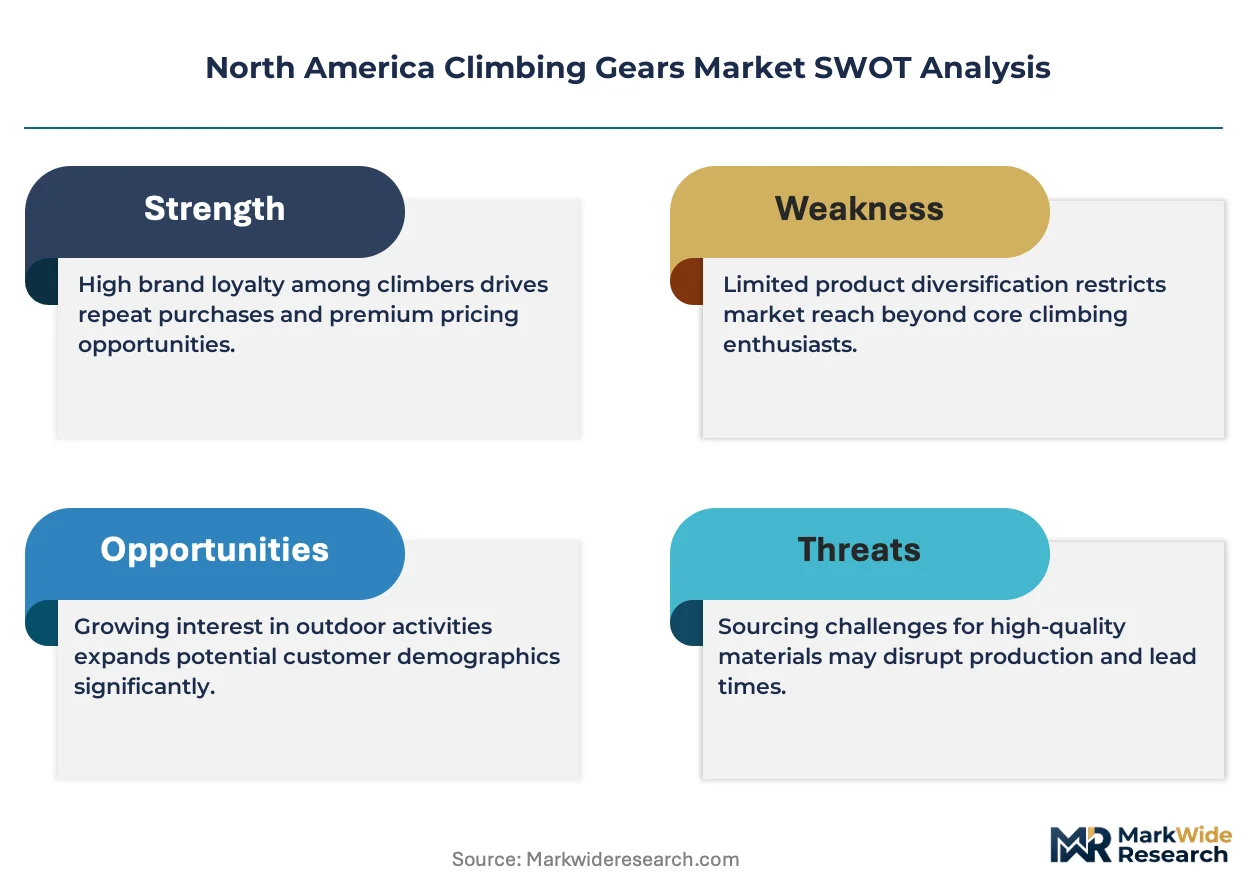
ASTM F1772 harness standard compliance functions as a structural barrier-to-entry moat, forcing capital-intensive testing infrastructure investments that exclude sub-scale competitors from institutional procurement channels.
For Market Incumbents: Lock in Dyneema fiber allocation through multi-year offtake agreements with DSM's North American operations before aerospace and maritime sectors absorb remaining polymer capacity. Defend position by accelerating recycled-nylon certification to preempt gym chain RFP sustainability mandates that threaten to disqualify virgin-material suppliers. Vertical integration into Salt Lake City-area textile finishing captures margin currently leaked to third-party sheath braiders. For New Entrants and Emerging Players: ASTM F1163 helmet standard updates in the United States open a window for specialized head protection suppliers to capture gym-mandated replacement demand before heritage brands retool production lines. Target Mexico's Guadalajara and Monterrey climbing facility whitespace with Spanish-language certification support and distributor partnerships that bypass California-focused incumbents. Lead with adaptive climbing hardware for paraclimbing programs as a beachhead into institutional procurement channels with lower competitive density. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by heritage alpine brands seeking Dyneema integration capabilities or gym-chain direct sales infrastructure. Long-term viability favors suppliers with demonstrated UIAA certification throughput and captive recycled-content traceability systems that match evolving institutional RFP requirements. Watch for inflection when Colorado and Utah school district physical education mandates trigger municipal procurement volume spikes distinct from commercial gym demand patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Nylon Certification Investment | Sterling Rope and BlueWater Ropes validate post-consumer waste traceability to meet gym chain RFP minimums. |
| Dyneema Fiber Integration Partnership | DSM's Greenville facility anchors North American supply for alpine guide and search-and-rescue unit upgrades. |
| Direct Institutional Contracting | Vail Resorts' Epic Climb division bypasses specialty retail to extract volume discounts from Black Diamond and Petzl. |
| Adaptive Hardware Product Line Launch | Seated harnesses and handle-style ascenders capture paraclimbing program expansion at USA Climbing and Gymnastics Canada. |
| Mexico Distribution Infrastructure Buildout | Nuevo León industrial corridor attracts Spanish-language support capabilities for Latin American facility expansion. |
Research Methodology
Document review covered UIAA Safety Commission certification protocols, ASTM International and CSA Group standard filings, and gym chain procurement RFP documentation, complemented by interviews with climbing gym operations directors, equipment buyers at multi-location chains, UIAA-accredited testing laboratory managers, and Canadian Rockies guide service operators. Secondary validation drew from customs trade data for aluminum alloy and synthetic fiber imports, SEC 10-K disclosures from publicly traded outdoor equipment parents, and municipal recreation department budget allocations. Bottom-up demand modeling from gym construction pipelines and replacement-cycle protocols triangulated against top-down market sizing from certification body shipment records.
Segment-level value outputs across the projection horizon reflect discrete modeling of rope, harness, carabiner, and helmet categories with separate replacement-cycle elasticity parameters for institutional versus individual buyers. CAGRs derive from gym membership growth trajectories reported by USA Climbing and Gymnastics Canada, overlaid with ASTM standard-mandated refresh schedules and Dyneema adoption curves from alpine guide equipment upgrade surveys. Industry-specific inputs include UIAA certification queue duration assumptions and state-level physical education mandate implementation timelines.
The model assumes a particular technology adoption path where recycled nylon achieves parity with virgin fiber fall ratings; alternative pathways for bio-based polymer development would alter the outlook for mid-tier suppliers betting on mechanical recycling infrastructure. Forecasts reflect assumptions regarding Olympic sport climbing medal performance sustaining youth program enrollment, aluminum alloy price volatility remaining within historical bands, and CSA Group-ASTM harmonization proceeding incrementally rather than abruptly. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Hiking Accessories Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Paragliding Equipment Market