
 Global Badminton Equipment and Facilities Market | 2026-2036
Global Badminton Equipment and Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Global Badminton Equipment and Facilities Market Analysis
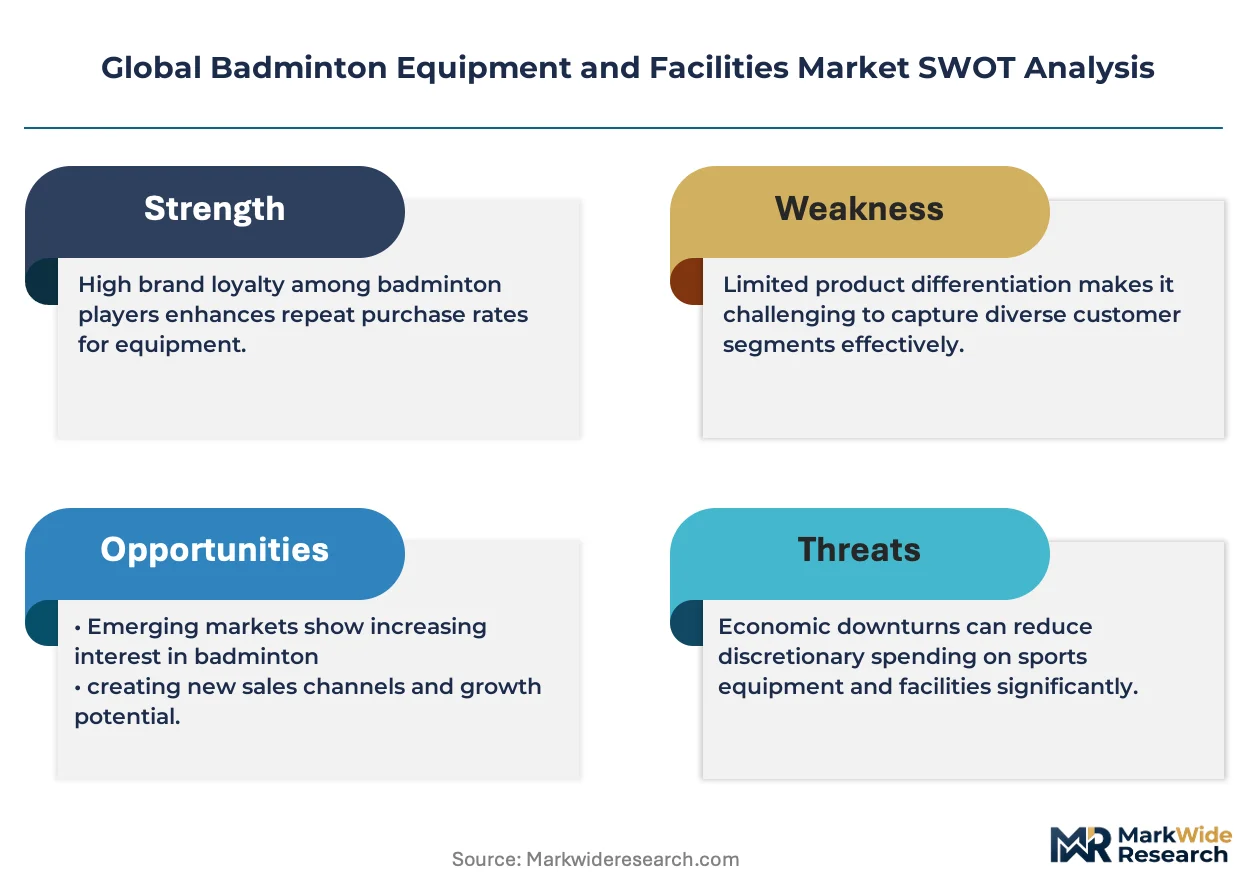
Premium carbon fiber racket specifications is unwinding the competitive landscape as manufacturers race to meet tournament-grade stiffness-to-weight ratios. YONEX leverages its integrated graphite sourcing and in-house molding operations to dominate professional tour supply chains. Li-Ning anchors its position through national team sponsorships across Asian federations. Babolat competes by extending its tennis string expertise into hybrid badminton stringbed technologies for European club players.
Badminton equipment and facilities encompass the full production and installation infrastructure for rackets, shuttlecocks, nets, court surfaces, and supporting accessories used in recreational and competitive play. Carbon fiber pre-preg layup with resin transfer molding achieves frame weights below 80 grams while maintaining 30-pound string tension tolerance, serving the dual purpose of reducing player fatigue and enabling explosive smash velocities. Rackets and shuttlecocks capture the deepest margin pools as material science differentiation commands price premiums at the elite tier. Facility type segmentation shows indoor courts with sprung wood flooring and climate control generating the highest per-court revenue, while multi-sport facilities represent the fastest-growing installation category as municipal budgets favor flexible-use infrastructure.
ISO 9001 quality management and GB standards from China's Standardization Administration govern racket durability testing and shuttlecock flight consistency, with BIS certification in India adding compliance layers for imported equipment. The EU's REACH regulation restricts volatile organic compounds in grip adhesives and court surface coatings, reshaping supplier qualification criteria for European distributors. Stakeholders must monitor carbon fiber supply concentration and evolving national federation procurement standards as the primary variables determining market access and pricing power.
Market Dynamics
Carbon fiber composite manufacturing is concentrating supply leverage among racket producers with captive pre-preg sourcing, while ISO 9001 certification mandates from China's Standardization Administration and India's BIS reshape procurement minimums for professional-grade equipment.
Growth Catalysts
- National federation procurement upgrades:Professional clubs in Indonesia and India are mandating tournament-grade stiffness specifications for competitive venues, accelerating replacement cycles for elite-tier rackets.
- REACH compliance adaptation:The EU's volatile organic compound restrictions on grip adhesives are forcing formulation innovations that transfer to premium product lines globally.
- Sprung wood flooring standardization:Climate-controlled indoor facilities with certified shock absorption are becoming mandatory for national championship hosting rights across Asian markets.
Market Restraints
- Carbon fiber supply concentration:Toray-grade pre-preg availability clusters with Japanese and Taiwanese suppliers, exposing racket manufacturers to input bottlenecks during aerospace demand surges.
- REACH certification friction:European distributors face 18-24 month requalification timelines for court surface coatings, delaying new product introductions.
- Multi-sport facility substitution:Municipal budgets favoring flexible-use gymnasiums over dedicated badminton halls compress per-court equipment attachment rates.
Strategic Opportunities
- Brazilian club infrastructure buildout:Underpenetrated competitive badminton development in São Paulo and Rio de Janeiro creates whitespace for facility installation and equipment distribution partnerships.
- Hybrid stringbed technology convergence:Tennis-derived monofilament-nylon hybrids are penetrating European amateur segments previously served by traditional multifilament.
- China's dual carbon goals:National manufacturing incentives for low-carbon production processes reward resin transfer molding investments with tax preferencing.
Industry Challenges
- Composite layup technician scarcity:Frame manufacturing requires skilled pre-preg cutters and mold operators with 3+ year training curves, constraining capacity expansion.
- Shuttlecock flight consistency certification:BIS and GB standard testing protocols demand specialized wind tunnel infrastructure that smaller producers cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Badminton Equipment and Facilities Market |
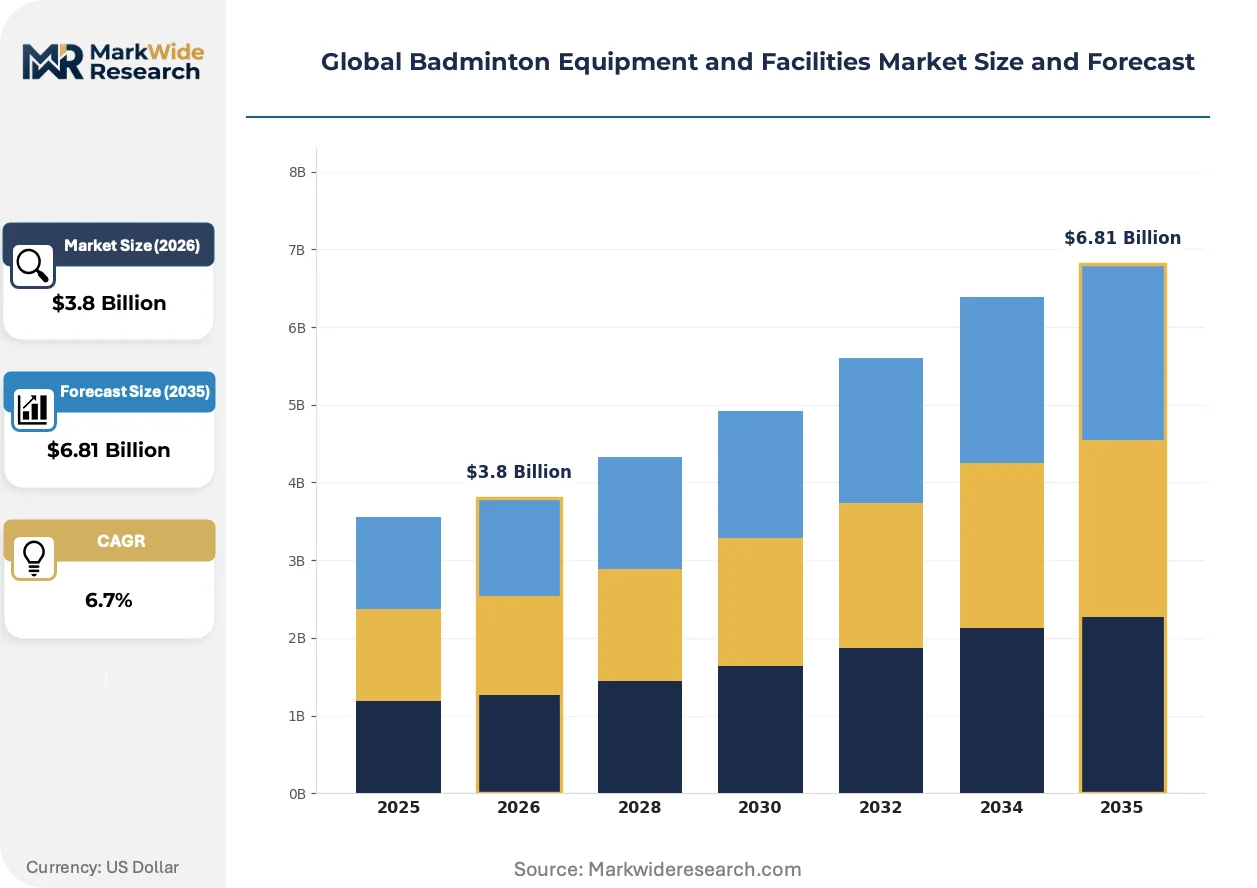
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rackets, Shuttlecocks, Nets, Accessories End User: Schools, Clubs, Individuals, Organizations Distribution Channel: Online Retail, Specialty Stores, Sports Equipment Chains, Direct Sales Facility Type: Indoor Courts, Outdoor Courts, Multi-Sport Facilities, Community Centers |
| Companies Covered | Babolat, Carlton Sports, YONEX, Wilson Sporting Goods, ASICS, Li-Ning, GOSEN, Ashaway, VICTOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Badminton Equipment and Facilities Market Emerging Trajectories
Material science differentiation and regulatory compliance automation are compressing product development timelines while fragmenting competitive advantage sources across manufacturing and distribution layers.
Aerodynamic frame geometries with truncated cone cross-sections are bifurcating the racket market between drag-minimized head shapes for defensive players and box-section stability frames for smash-oriented specialists. National team programs in China and Indonesia are adopting these variants at 18-month replacement cycles. The technology is bifurcating professional supply chains into separate molding tooling lines that smaller manufacturers cannot amortize.
REACH Annex XVII restrictions on phthalate plasticizers in grip compounds are forcing reformulation investments across European-bound product lines. Manufacturers serving Germany and France must now certify alternative polymer blends through ECHA notification procedures. Amateur club segments face 15-20% price premiums for compliant grips, compressing margin recovery timelines.
Direct-to-academy distribution models are displacing traditional wholesale channels for volume racket purchases. Municipal sports bureaus in India and Indonesia now negotiate frame-string-grip bundles through federation-coordinated tenders, bypassing regional distributors. This consolidation is most visible in Jakarta and Bangalore, where single-source contracts cover 200+ court facility networks.
Global Badminton Equipment and Facilities Market Segmentation
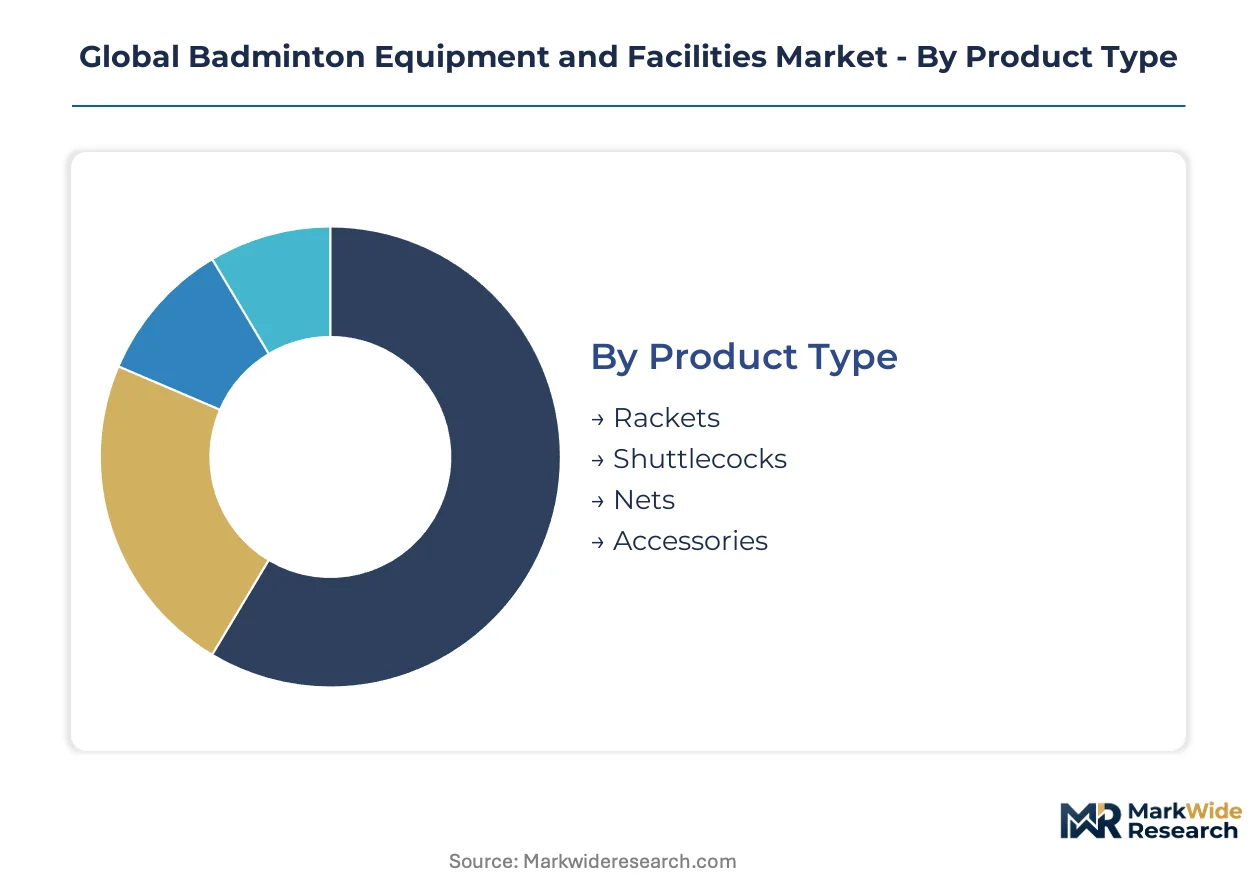
Badminton equipment segmentation tracks divergent margin structures across material-intensive rackets versus consumable shuttlecocks, while facility typology determines equipment attachment rates and replacement cycle velocity. Understanding substitution pressures across product and distribution layers exposes where pricing power concentrates.
Product Type:
Shuttlecocks face the strongest substitute threat as synthetic nylon variants displace feather shuttles in amateur training environments, compressing traditional supplier margins.
- Rackets:Carbon fiber pre-preg layup with resin transfer molding achieves sub-80 gram frames maintaining 30-pound string tension tolerance. Tournament-grade stiffness specifications from Indonesian and Indian professional clubs are accelerating replacement cycles to 18-month intervals.
- Shuttlecocks:Goose feather construction with standardized skirt diameter dominates competitive play, though cork-base durability varies by humidity exposure. China's national team programs and Jakarta's club networks consume volume through federation-coordinated tenders.
- Nets:Braided polyethylene mesh with vinyl-coated steel cable tensioning systems.
- Accessories:Grip tapes, racket bags, and court boundary markers.
Rackets anchor the volume base while shuttlecocks gain share at the steepest rate through synthetic material adoption.
End User:
Procurement concentration varies sharply by institutional scale, with municipal sports bureaus wielding tender leverage that individual purchasers cannot replicate.
- Clubs:Professional venues in Jakarta, Bangalore, and São Paulo drive equipment bundling through direct-to-academy distribution. Sprung wood flooring certification requirements and climate control mandates are reshaping capital expenditure priorities.
- Schools:Physical education programs across India and Indonesia represent high-volume, price-sensitive procurement through government tender mechanisms.
- Individuals:Amateur enthusiasts purchasing through specialty retail or online channels.
- Organizations:Corporate wellness programs and municipal recreation departments.
Schools dominate unit volume while clubs command the highest per-player equipment spend.
Distribution Channel:
Channel selection determines margin recovery timelines, with direct sales bypassing distributor markups but requiring dedicated account infrastructure.
- Direct Sales:Federation-coordinated tenders in India and Indonesia now cover 200-plus court facility networks, displacing regional wholesale layers. Municipal sports bureaus negotiate frame-string-grip bundles through single-source contracts.
- Specialty Stores:Professional stringing services and grip customization attract tournament players in European markets facing REACH compliance premiums.
- Online Retail:E-commerce platforms serving price-comparison shoppers.
- Sports Equipment Chains:Multi-sport retailers with standardized inventory.
Direct sales capture institutional volume while specialty stores defend premium positioning.
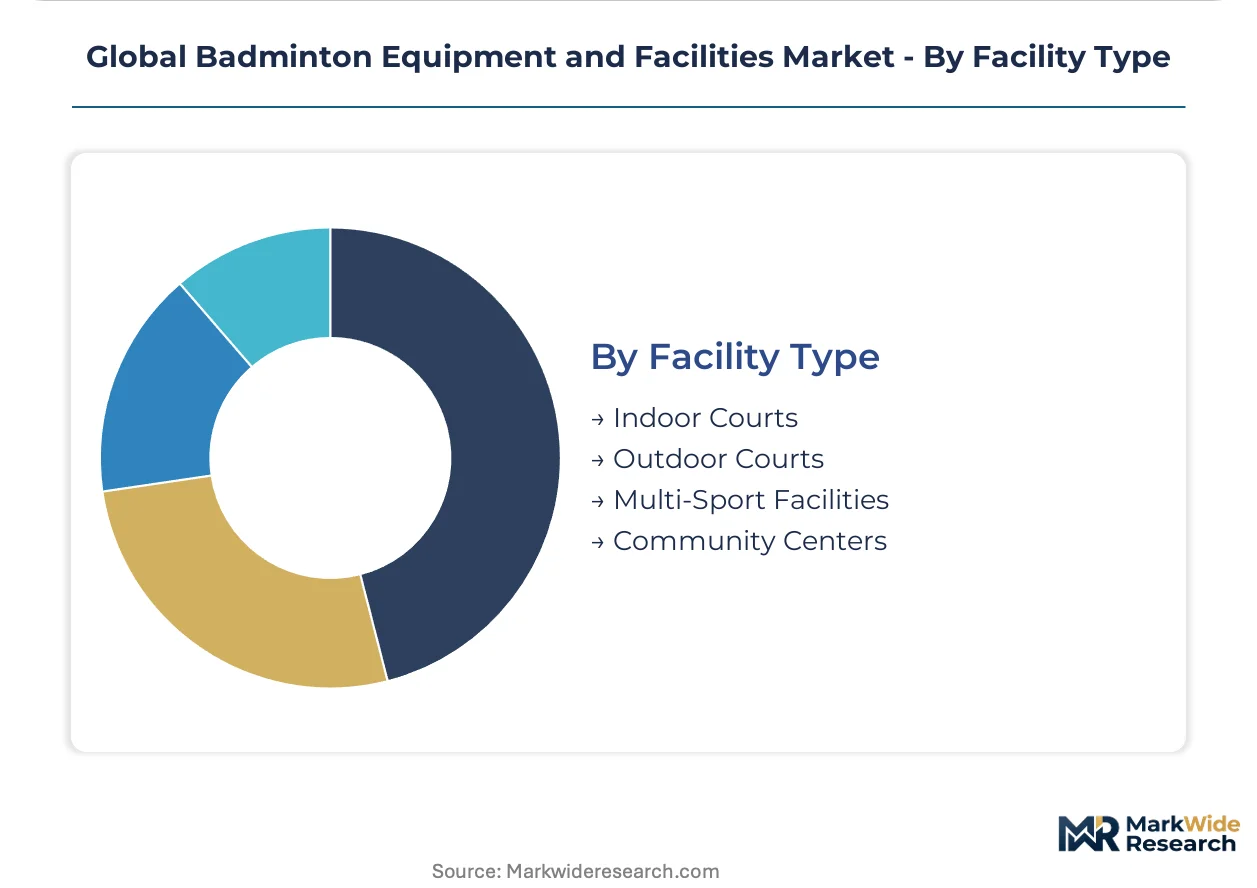
Facility Type:
Construction cost amortization periods differ dramatically by flooring specification and climate control requirements.
- Indoor Courts:Sprung wood flooring with certified shock absorption and climate control generates highest per-court revenue. Asian championship hosting rights now mandate these specifications, concentrating investment in Jakarta, Bangalore, and Chinese provincial capitals.
- Multi-Sport Facilities:Flexible-use gymnasiums favored by municipal budgets represent the fastest-expanding installation category, though per-court badminton equipment attachment rates compress accordingly.
- Outdoor Courts:Weather-exposed concrete or asphalt surfaces with portable net systems.
- Community Centers:Subsidized public access venues with basic equipment provisions.
Indoor courts anchor revenue per facility while multi-sport installations expand most quickly across municipal portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for Toray-grade carbon fiber pre-preg tilts trade balances toward Japan and Taiwan, while finished racket exports flow from Chinese manufacturing clusters to Southeast Asian federation procurement programs.
China
Domestic consumption absorbs the largest share of carbon fiber racket production, with provincial sports bureaus in Guangdong and Jiangsu issuing bulk tenders for school equipment programs. GB standards from the Standardization Administration mandate shuttlecock flight consistency testing that smaller producers cannot access. The Yangtze River Delta concentration of resin transfer molding facilities supplies both domestic clubs and export orders to Jakarta and Bangalore networks.
Indonesia
Persatuan Bulutangkis Seluruh Indonesia procurement upgrades have compressed elite racket replacement cycles to 18-month intervals. BIS certification requirements for imported equipment add compliance layers that favor established suppliers with testing infrastructure. Jakarta's club facility networks now negotiate frame-string-grip bundles through federation-coordinated single-source contracts covering 200-plus courts.
India
Badminton Association of India tenders for national championship venues mandate sprung wood flooring with certified shock absorption. BIS testing protocols for racket durability and shuttlecock flight consistency reshape import qualification criteria. Bangalore and Hyderabad municipal sports bureaus have displaced regional wholesale layers through direct-to-academy distribution models for volume purchases.
Japan
Toray Industries' domestic pre-preg production anchors the upstream carbon fiber supply chain for premium racket manufacturers. METI industrial policy supports advanced materials R&D that transfers to sporting goods applications. The Kanto region's integrated graphite sourcing and molding operations concentrate supply leverage among producers with captive raw material access.
Brazil
Underpenetrated competitive badminton development in São Paulo and Rio de Janeiro creates whitespace for facility installation partnerships. Confederação Brasileira de Badminton infrastructure grants remain limited, constraining equipment attachment rates relative to Asian benchmarks. Local distributors face 18-24 month timelines for REACH-compliant court surface coating requalification when sourcing from European suppliers.
Global Badminton Equipment and Facilities Market Vendor Landscape
Concentration sits with vertically integrated specialists controlling carbon fiber pre-preg sourcing and in-house molding operations. The vendor base stratifies across three tiers: multinational sporting goods conglomerates with multi-sport portfolios, Asian specialists with federation sponsorship anchoring, and regional fabricators serving price-sensitive amateur segments. Dominant competitive moves include backward integration into graphite supply chains and federation-coordinated tender participation that displaces wholesale distribution layers.
Among Japanese specialists, YONEX exemplifies the integrated archetype through captive pre-preg sourcing and professional tour supply chain dominance. Li-Ning occupies a position as a federation-anchored Chinese competitor with national team sponsorships across Asian markets. Babolat represents European diversification from tennis string expertise into hybrid badminton technologies for club segments. These three illustrate how geographic origin and core competency specialization determine competitive positioning within the carbon fiber racket tier.
| Leading Market Players |
|---|
| Babolat |
| Carlton Sports |
| YONEX |
| Wilson Sporting Goods |
| ASICS |
| Li-Ning |
| GOSEN |
| Ashaway |
| VICTOR |
| Others |
Supply Flow & Price Mechanics
Eighteen-month pre-preg inventory cycles at Taiwanese suppliers concentrate pricing leverage among racket manufacturers with captive graphite sourcing, while REACH-compliant grip compound reformulations feed 15-20% cost premiums into European-bound product lines.
Pricing Analysis
Federation procurement coordinators anchor tournament-grade racket pricing through volume bundling of frame-string-grip configurations. Three-tier pricing structure across premium carbon fiber, standard graphite composite, and economy aluminum tiers separates professional stiffness specifications from amateur training equipment. Cost compression in synthetic shuttlecock variants is intensifying because nylon skirt technologies displace goose feather construction in club training environments. Municipal sports bureaus in India and Indonesia exhibit highest price sensitivity through tender-driven procurement, while professional clubs in Jakarta and Bangalore demonstrate lowest sensitivity due to championship hosting mandates.
Supply Chain Analysis
Toray-grade carbon fiber pre-preg availability clusters with Japanese and Taiwanese suppliers, exposing racket manufacturers to input bottlenecks during aerospace demand surges. Finished racket assembly draws from Chinese resin transfer molding facilities, Indonesian federation procurement programs, and Indian municipal tender networks. Single-source vulnerability concentrates in aerospace-grade carbon fiber allocation priorities. Distribution runs through federation-coordinated direct sales displacing regional wholesale layers for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with synthetic shuttlecock adoption and Brazilian facility buildout creating distinct competitive arenas outside incumbent strongholds.
For Market Incumbents: Shield carbon fiber supply leverage through captive pre-preg sourcing agreements with Toray Industries and Formosa Plastics. Deepen molding capacity in Yangtze River Delta clusters to capture federation tender volumes in Jakarta and Bangalore. Certification investment in BIS and GB standard testing infrastructure raises barriers against regional fabricators threatening price-sensitive school procurement segments. For New Entrants and Emerging Players: Lead with hybrid stringbed technology convergence targeting European amateur clubs seeking tennis-derived monofilament-nylon alternatives. São Paulo and Rio de Janeiro facility installation partnerships represent the most penetrable whitespace given underpenetrated competitive badminton development. Direct-to-academy distribution models bypass entrenched wholesale relationships in Brazilian club networks. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because carbon fiber composite manufacturing expertise concentrates among specialists with 3+ year technician training curves. Acquisition target archetype: mid-tier racket fabricators with BIS certification access and federation relationships in India or Indonesia. Watch carbon fiber allocation priority shifts between aerospace and sporting goods as the inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Supply | Toray-grade pre-preg sourcing secures tournament-grade stiffness specification compliance for professional tour supply chains. |
| Federation Tender Participation | Single-source contracts covering 200-plus court networks in Jakarta and Bangalore displace regional distributor markups. |
| REACH-Compliant Grip Reformulation | ECHA notification procedures for phthalate-free polymer blends unlock German and French club market access. |
| Synthetic Shuttlecock Scale-Up | Nylon skirt production lines capture amateur training segment substitution away from goose feather construction. |
| Brazilian Facility Partnership | Confederação Brasileira de Badminton infrastructure grants in São Paulo and Rio de Janeiro establish first-mover court installation presence. |
Methodological Framework
A standing panel of racket manufacturing plant managers, federation procurement officers, carbon fiber composite R&D directors, and municipal sports bureau coordinators provided ongoing calibration against secondary validation from BIS certification databases, GB standard filings, customs trade records, and SEC 10-K sporting goods disclosures. Primary interviews with pre-preg suppliers and resin transfer molding operators combined with bottom-up facility installation tracking and top-down federation budget analysis to triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel, and facility typology alongside regional regulatory cluster variations. CAGRs were derived from equipment replacement cycle velocity and facility installation run rates, with carbon fiber input cost trajectories and REACH compliance timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in REACH Annex XVII enforcement and BIS certification protocols; material policy shifts would require re-modeling. Carbon fiber aerospace allocation priorities, federation procurement budget cycles, and synthetic shuttlecock performance parity thresholds constitute specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as dual carbon goal incentives and municipal infrastructure spending patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
US Fencing Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Golf Ball Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Diving Board Market
Sports Equipment
Sports Equipment Market