
 Skiing Equipment Market | 2026-2036
Skiing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Skiing Equipment Market Intelligence
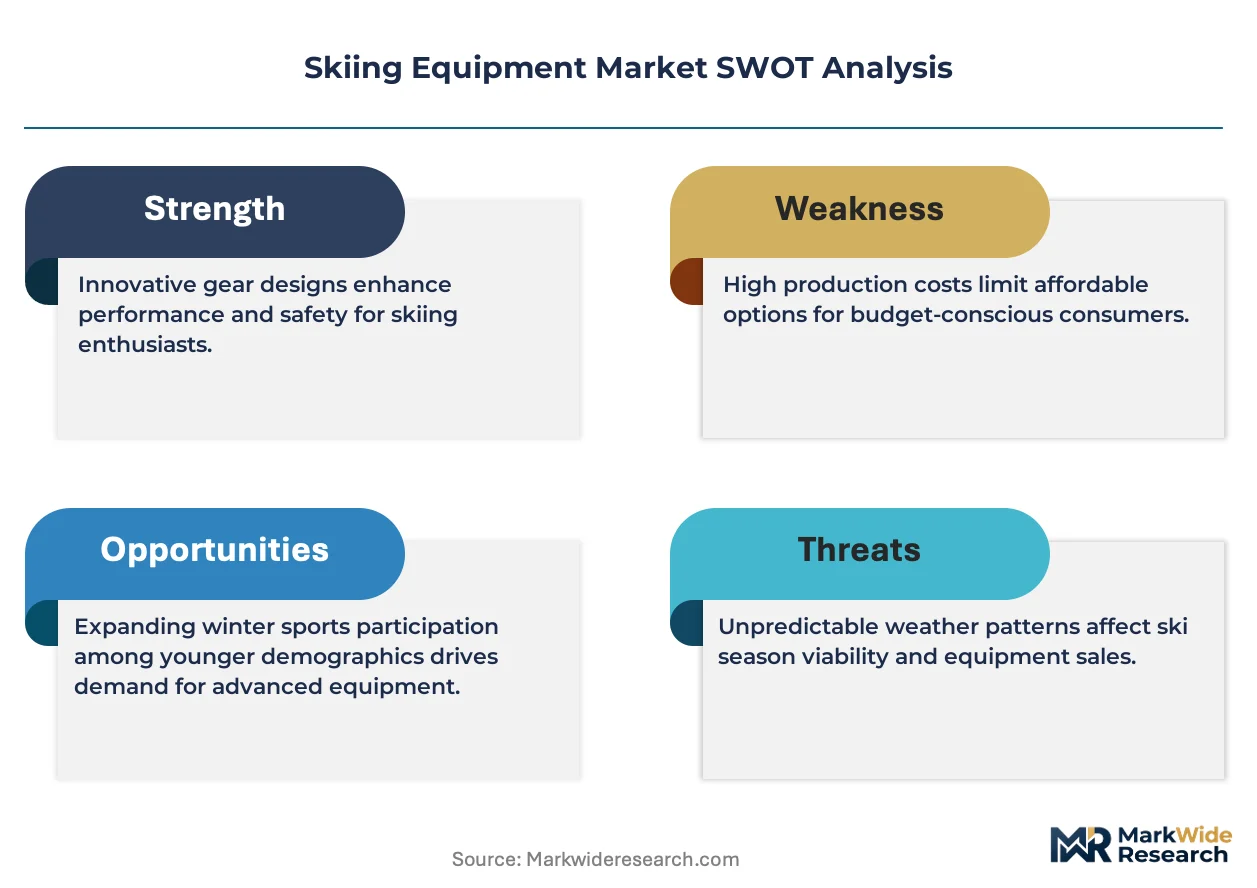
Alpine boot-fitting technician shortages across European manufacturing hubs is unwinding production capacity for custom-molded ski boots. Amer Sports Oyj leverages its multi-brand architecture to sustain year-round R&D pipelines across Nordic and alpine disciplines. Fischer Beteiligungsverwaltungs GmbH anchors its competitive stance through captive Austrian manufacturing of race-grade skis and bindings.
Skiing equipment encompasses purpose-built apparatus for downhill, Nordic, and freestyle snow sports, including laminated wood-core skis with titanal reinforcement layers, thermoplastic polyurethane ski boots with DIN-standard release bindings, and carbon fiber composite poles engineered for flexural rigidity at sub-zero temperatures. The primary commercial purpose centers on enhancing athlete safety, control, and propulsion across groomed, powder, and terrain park conditions. Ski gear and snowboard categories dominate value pools due to material intensity and replacement frequency, while carbon fiber technology commands premium positioning as manufacturers substitute fiberglass layups for reduced swing weight. Digital interfaces embedded in smart goggles and wearable trackers represent the fastest-growing technology segment, though thermal insulation retains volume leadership across mass-market price tiers.
ISO 9462 and ISO 9465 binding release standards, enforced by national safety regulators in Austria, France, and the United States, mandate periodic recalibration of rental fleet equipment and shape manufacturer warranty obligations. The EU's F-Gas Regulation constrains fluorinated wax formulations used in competitive ski preparation, redirecting R&D investment toward hydrocarbon and plant-based glide treatments. Stakeholders must monitor binding standard harmonization talks between CEN and ASTM committees, as divergent test protocols threaten cross-Atlantic product certification costs.
Market Dynamics
Compressed three-year replacement cycles for French Alps rental fleets are pulling production capacity toward high-volume standardized models, squeezing lead times for custom-molded alpine boots and redistributing margin pools across the value chain.
Growth Catalysts
- ISO 9462/9465 binding calibration mandates:Austria, France, and the United States now enforce periodic recertification of rental fleet equipment. This regulatory pressure accelerates equipment turnover and sustains replacement demand across resort operators.
- Digital interface integration:Smart goggles and wearable trackers embed sensor arrays for real-time slope analytics. Recreational skiers in North American resorts adopt these systems fastest, creating attach-rate expansion for hardware-software bundles.
- Carbon fiber substitution:Manufacturers displace fiberglass layups with carbon fiber composites to reduce swing weight. Race-grade and premium recreational segments absorb this material shift despite processing complexity.
Market Restraints
- Titanal and petroleum-derived TPU input costs:Laminated wood-core skis and thermoplastic polyurethane boots face margin compression from commodity volatility. European manufacturers lack price pass-through leverage in mass-market tiers.
- Austrian manufacturing concentration:Captive production of race-grade equipment anchors in specific Alpine valleys. Geographic clustering exposes output to regional labor shortages and logistics bottlenecks.
- Fluorinated wax prohibition:The EU's F-Gas Regulation eliminates competitive ski preparation formulations. Hydrocarbon and plant-based substitutes currently underperform on glide metrics, forcing R&D redirection without immediate performance parity.
Strategic Opportunities
- Plant-based glide treatment R&D:F-Gas Regulation constraints redirect investment toward bio-derived wax formulations. First-movers capturing performance benchmarks gain regulatory shelter and sustainability positioning.
- Direct-to-consumer boot fitting:3D scanning and remote thermoforming technology collapses the retail fitting bottleneck. North American specialty retailers pilot hybrid models combining digital measurement with local finishing.
- Seasonal rental fleet digitization:Embedded binding sensors enable usage-based maintenance scheduling. French Alps operators testing predictive recalibration reduce downtime and extend certified equipment life.
Industry Challenges
- Alpine boot-fitting technician scarcity:Custom-molded production capacity unwinds across European hubs as skilled labor pools contract. Training pipeline gaps exceed five years for certification proficiency.
- CEN-ASTM test protocol divergence:Binding standard harmonization talks stall between European and American technical committees. Manufacturers face duplicated certification costs for cross-Atlantic product lines.
- Smart hardware-software integration complexity:Goggle and tracker ecosystems require ongoing firmware support. Legacy equipment obsolescence risks fragment customer loyalty across upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skiing Equipment Market |
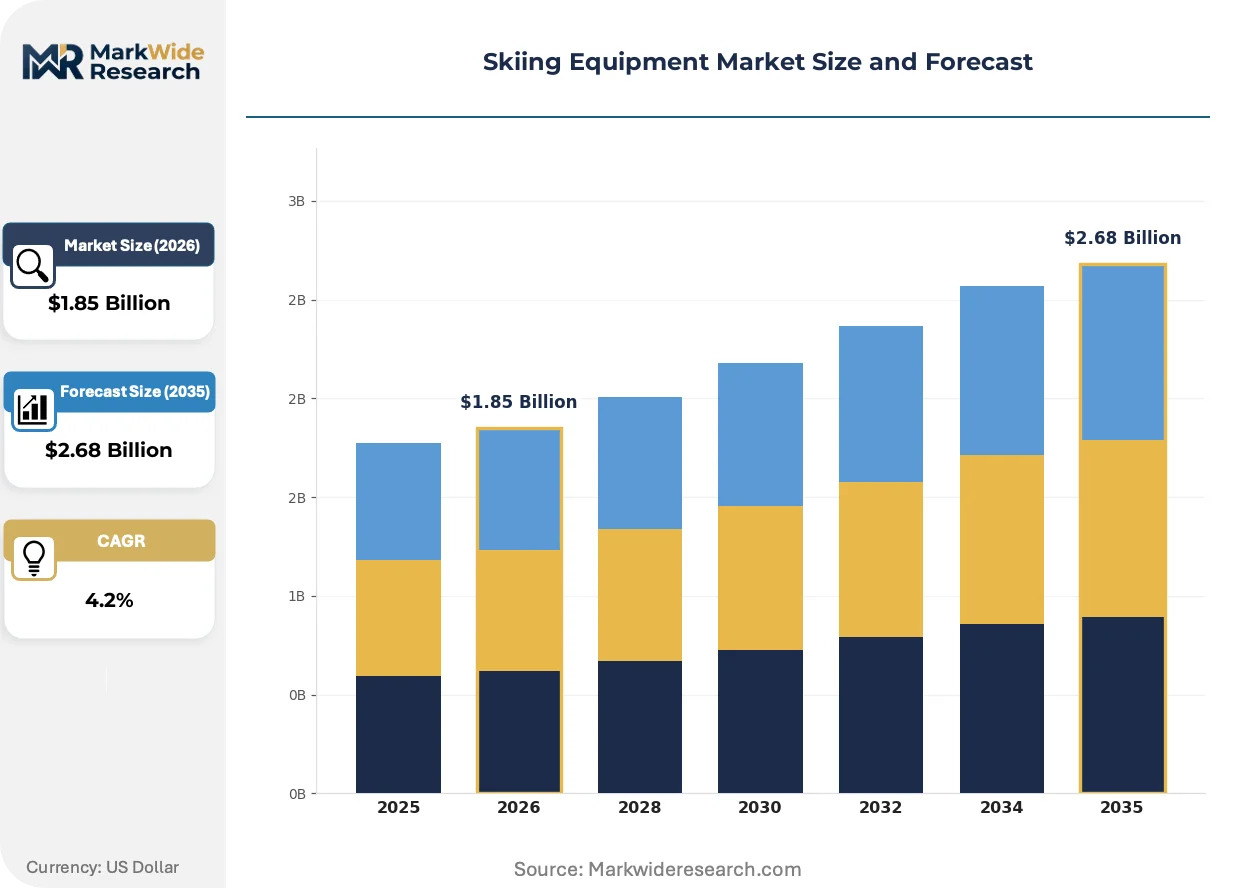
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ski Gear, Snowboards, Ski Boots, Poles End User: Professional Athletes, Recreational Skiers, Beginners, Instructors Technology: Thermal Insulation, Carbon Fiber, Adaptive Fit, Digital Interfaces Distribution Channel: Online Retail, Sporting Goods Stores, Specialty Shops, Rental Services |
| Companies Covered | Tecnica Group S.p.A, Black Diamond Equipment, Ltd., Amer Sports Oyj, Salomon, Head Skis, Fischer Beteiligungsverwaltungs GmbH, K2 Sports LLC, Helly Hansen, Skis Rossignol S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skiing Equipment Market Strategic Shifts & Innovations
Material science convergence with embedded sensor systems is restructuring competitive advantage away from pure hardware performance toward integrated safety-analytics platforms.
Carbon fiber composite layups are fragmenting traditional ski construction hierarchies. Race-grade manufacturers adopt aerospace-grade prepregs for torsional rigidity at reduced mass. Recreational buyers in Colorado and Utah now expect carbon-reinforced options at mid-tier price points. This material diffusion compresses premium positioning windows and forces faster product cycle refreshes.
EU F-Gas Regulation enforcement eliminates perfluorinated compound formulations from competitive wax preparation. Austrian and Swiss race service teams redirect procurement toward hydrocarbon-paraffin blends and experimental plant-derived esters. Performance gaps on cold-snow glide metrics persist, compressing podium outcomes and equipment sponsorship value for European national ski federations.
Resort procurement teams unbundle after-sales service from equipment purchase contracts. French Alps rental operators now source binding calibration and fleet maintenance through specialized third-party technicians. This service externalization concentrates technical expertise with regional specialists while equipment manufacturers absorb warranty cost uncertainty from non-certified service interventions.
Skiing Equipment Market Segmentation
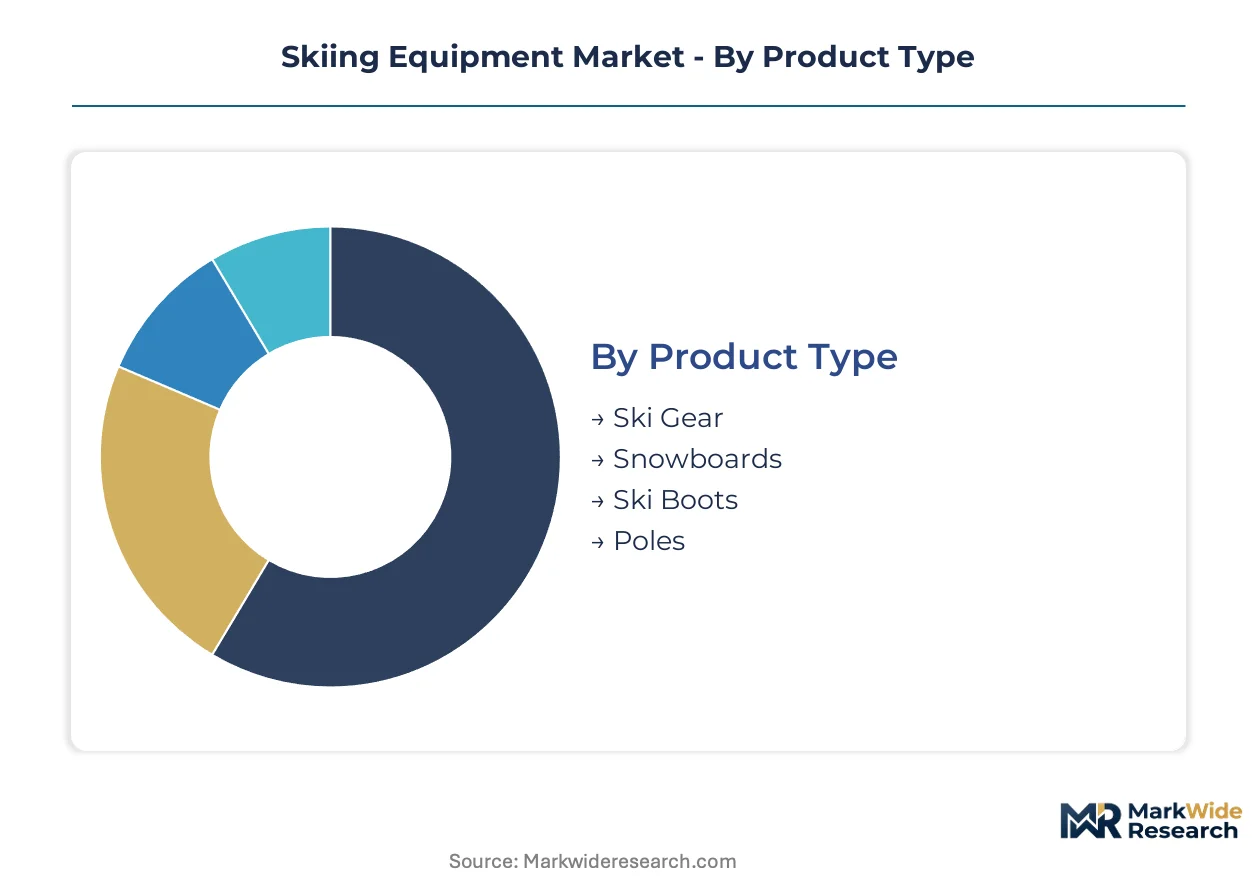
Segmentation in skiing equipment reveals how product complexity, user proficiency, and channel economics split margin pools across vastly different commercial logics. Material intensity and replacement frequency concentrate value in specific product categories, while distribution channel selection determines whether manufacturers capture service revenue or surrender it to intermediaries.
Product Type:
Ski gear and snowboards flow through specialty retail and resort rental fleets, while boots and poles concentrate in sporting goods chains and online direct-to-consumer channels.
- Ski Gear:Laminated wood-core construction with titanal reinforcement layers dominates alpine and Nordic disciplines. Demand concentrates in Colorado and Utah recreational markets, where carbon fiber substitution at mid-tier price points compresses premium positioning windows.
- Snowboards:Composite sandwich constructions with sintered bases and steel edges target terrain park and freeride segments. French Alps rental operators refresh fleets on compressed three-year cycles, pulling production capacity toward high-volume standardized models.
- Ski Boots:Thermoplastic polyurethane shells with thermoformable liners span recreational to race-grade specifications. Austrian manufacturing hubs face technician shortages that unwind custom-molded production capacity.
- Poles:Carbon fiber composite shafts engineered for flexural rigidity at sub-zero temperatures serve both alpine and Nordic applications. Mass-market volume leadership sits with aluminum alternatives in entry-level tiers.
By volume, ski gear leads. By growth pace, carbon fiber-reinforced snowboards are expanding most quickly.
End User:
Cost tier stratification separates professional-grade certification requirements from recreational price sensitivity, with beginners and instructors occupying distinct service-oriented commercial models.
- Professional Athletes:Race-grade equipment with FIS homologation requirements and national federation sponsorship structures. Austrian and Swiss race service teams drive procurement of hydrocarbon-paraffin wax formulations under EU F-Gas Regulation constraints.
- Recreational Skiers:North American resort visitors now drive the largest share of equipment turnover, adopting smart goggles and wearable trackers fastest.
- Beginners:Rental fleet dependency and lesson-package bundling characterize this segment. French Alps operators source binding calibration through specialized third-party technicians.
- Instructors:Durability-focused specifications with seasonal replacement guarantees. ISO 9462 binding recertification mandates shape warranty obligations for fleet operators serving this trained-user category.
Recreational skiers generate the highest absolute revenue. Professional athletes command the steepest per-unit margins.
Technology:
Application-specific performance requirements separate thermal solutions for mass-market comfort from carbon fiber and digital systems targeting premium positioning.
- Thermal Insulation:Synthetic and down-filled layering systems retain volume leadership across mass-market price tiers. European manufacturers face margin compression from petroleum-derived input volatility.
- Carbon Fiber:Aerospace-grade prepregs displace fiberglass layups for torsional rigidity at reduced swing weight. Race-grade and premium recreational segments absorb this material shift despite processing complexity.
- Adaptive Fit:3D scanning and remote thermoforming technology collapses the retail fitting bottleneck. North American specialty retailers pilot hybrid models combining digital measurement with local finishing.
- Digital Interfaces:Smart goggles and wearable trackers embed sensor arrays for real-time slope analytics. Hardware-software bundles create attach-rate expansion in North American recreational markets.
Thermal insulation holds volume dominance. Digital interfaces are gaining share fastest.
Distribution Channel:
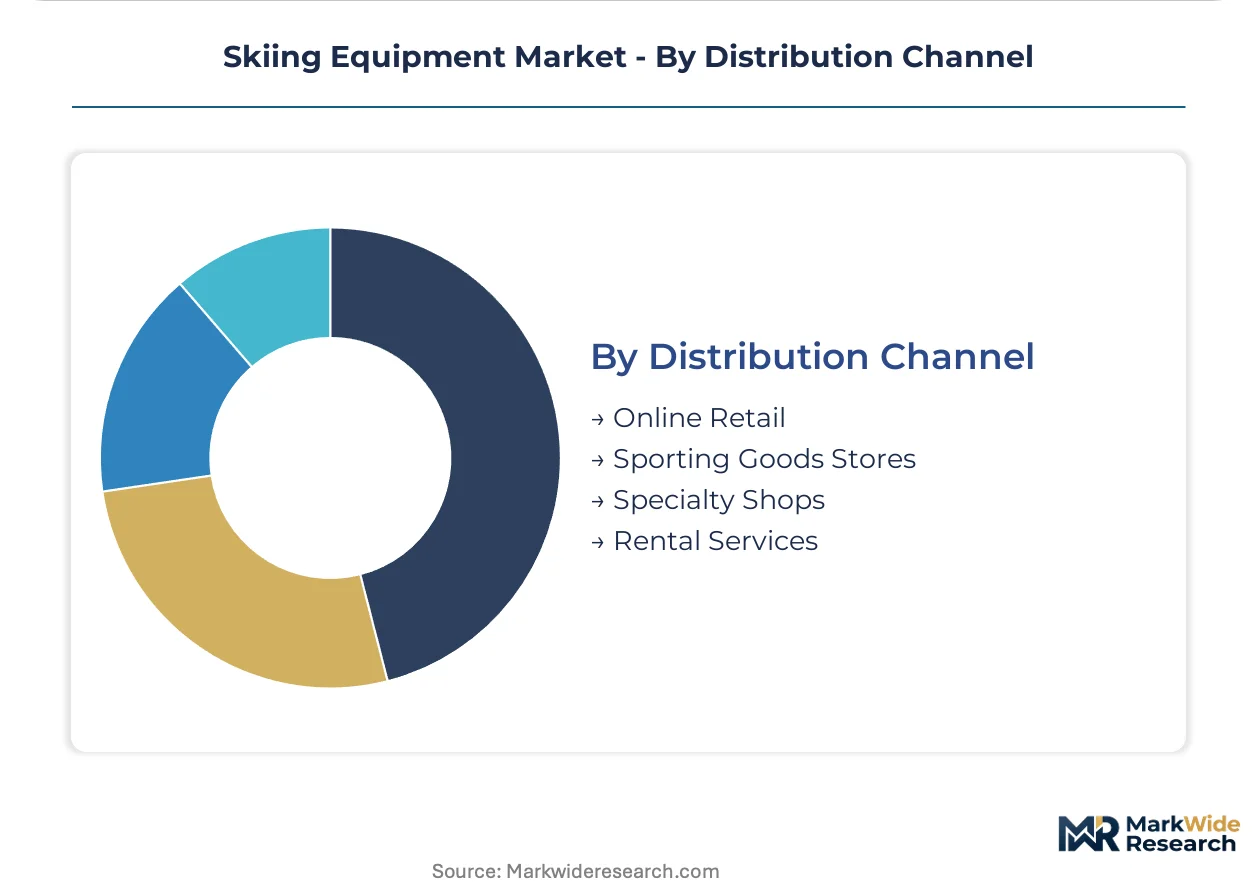
Customer type and product complexity determine whether transactions complete through self-service digital platforms or high-touch physical intermediaries.
- Online Retail:Direct-to-consumer boot fitting via 3D scanning platforms targets custom-molded segments. Manufacturers absorb warranty cost uncertainty from non-certified service interventions.
- Sporting Goods Stores:Mass-market ski boots and poles concentrate here, with limited fitting services and standardized inventory. Price pass-through leverage remains weak for European manufacturers.
- Specialty Shops:High-touch fitting for custom boots and race-grade ski gear. Technician certification gaps exceeding five years constrain service capacity in European hubs.
- Rental Services:French Alps operators dominate fleet scale, with embedded binding sensors enabling usage-based maintenance scheduling. Predictive recalibration testing reduces downtime and extends certified equipment life.
Rental services command the highest transaction frequency. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French regulators at ANSM enforce binding calibration standards that compress equipment replacement cycles across Alpine valleys. ISO 9462 mandates reshape procurement patterns from Chamonix rental fleets to Pyrenees service hubs.
United States
Colorado and Utah recreational markets absorb carbon fiber substitution fastest. The EPA oversees chemical safety in ski wax formulations under TSCA authority. Denver-Boulder corridor specialty retailers pilot 3D scanning for direct-to-consumer boot fitting.
France
Three-year rental fleet refresh cycles dominate French Alps procurement decisions. ANSM enforces ISO 9465 recertification timelines for resort operators. Chamonix-Mont-Blanc valley concentrates third-party binding calibration services.
Austria
Captive manufacturing of race-grade equipment anchors in Alpine valleys. The country's national safety regulator mandates DIN-standard compliance for export-bound bindings. Salzburg-Tyrol industrial corridor faces technician shortages for custom-molded boot production.
Switzerland
Swissmedic oversees medical-grade safety claims for protective equipment. Zurich-Geneva logistics networks distribute hydrocarbon-paraffin wax substitutes under F-Gas Regulation constraints. Zermatt resort operators test predictive maintenance sensors.
Japan
METI promotes carbon fiber composite adoption through industrial technology grants. Nagano Prefecture ski clusters import Austrian race-grade specifications for domestic competition circuits. Hokkaido powder tourism drives premium equipment attach rates.
Skiing Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the skiing equipment landscape. The vendor base clusters around three strategic positions: multi-brand conglomerates sustaining year-round R&D pipelines, Alpine valley specialists with captive manufacturing of race-grade apparatus, and diversified outdoor equipment houses leveraging cross-category material science. Consolidation pressure runs through binding standard harmonization costs and carbon fiber processing complexity. Geographic expansion and portfolio diversification dominate competitive moves as players seek regulatory shelter and sustainability positioning.
Within the multi-brand tier, Amer Sports Oyj exemplifies portfolio breadth across Nordic and alpine disciplines. Alpine manufacturing specialists include Fischer Beteiligungsverwaltungs GmbH and Skis Rossignol S.A., both anchoring competitive stance through valley-based production of race-grade equipment. These three occupy positions that reflect divergent responses to ISO standard tightening and F-Gas Regulation constraints.
| Leading Market Players |
|---|
| Tecnica Group S.p.A |
| Black Diamond Equipment, Ltd. |
| Amer Sports Oyj |
| Salomon |
| Head Skis |
| Fischer Beteiligungsverwaltungs GmbH |
| K2 Sports LLC |
| Helly Hansen |
| Skis Rossignol S.A. |
| Others |
Cost & Logistics Intelligence
French Alps rental fleet scale economies compress manufacturing margins for standardized equipment while elevating price floors for custom-molded alpine boots. Three-year refresh cycles at Chamonix-Mont-Blanc operators concentrate procurement volume with multi-brand conglomerates, squeezing price pass-through leverage for European mass-market manufacturers facing titanal and petroleum-derived TPU input volatility.
Pricing Analysis
Colorado specialty retailers command 15-25% premiums over Austrian direct-channel equivalents for carbon fiber-reinforced ski gear. Three-tier pricing structure across premium race-grade, standard recreational, and economy rental tiers separates FIS-homologated equipment from mass-market fiberglass layups. Pricing pressure stems from commodity volatility in titanal reinforcement layers and thermoplastic polyurethane shell materials. Rental fleet operators exhibit highest price sensitivity due to compressed replacement cycles, while professional athletes demonstrate lowest sensitivity driven by federation sponsorship structures and performance non-negotiability.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade carbon fiber prepregs dominates race-grade manufacturer preferences, contrasting with just-in-time inventory for mass-market fiberglass skis. Captive production concentrates in Austria, France, and Italy, drawing from laminated wood-core suppliers in the Balkans and titanal sheet producers in Germany. Single-source vulnerability sits with Alpine valley technician pools for custom-molded boot thermoforming. Distribution runs through specialty retail fitting services for premium tiers and direct-to-consumer platforms for standardized poles and entry-level gear.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snowboard and outdoor adventure equipment substitution threatens ski gear incumbents as younger demographics pivot toward terrain park versatility and year-round mountain sports participation.
For Market Incumbents: Shield race-grade certification portfolios through accelerated FIS homologation investment ahead of binding standard harmonization between CEN and ASTM committees. Backward integration into captive Austrian carbon fiber prepreg sourcing secures material allocation against aerospace sector competition. Channel control through embedded binding sensor ecosystems locks in rental fleet maintenance contracts and extends certified equipment life cycles.
For New Entrants and Emerging Players: Lead with plant-based glide treatment formulations targeting EU F-Gas Regulation shelter and sustainability positioning among competitive ski federations. North American direct-to-consumer boot fitting via 3D scanning platforms represents the most penetrable white space, collapsing specialty retail technician bottlenecks. Go-to-market angle: hardware-software bundles combining adaptive fit technology with slope analytics subscriptions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among embedded sensor fleet maintenance providers serving French Alps rental operators. Long-term viability across the projection horizon favors technology-integrated equipment platforms over pure hardware manufacturers. Acquisition target archetype: regional third-party binding calibration specialists consolidating technical expertise outside manufacturer warranty structures. Signal to watch: CEN-ASTM protocol convergence eliminating duplicated certification cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Glide Treatment R&D | EU F-Gas Regulation compliance redirects Austrian and Swiss race service procurement toward bio-derived wax performance parity. |
| Embedded Sensor Fleet Integration | Chamonix rental operators testing predictive recalibration reduce downtime and extend ISO 9465 certified equipment life. |
| Direct-to-Consumer Boot Fitting | Denver-Boulder corridor specialty retailers pilot 3D scanning platforms collapsing five-year technician certification bottlenecks. |
| Carbon Fiber Prepreg Backward Integration | Captive aerospace-grade material sourcing secures torsional rigidity specifications against competing industrial demand. |
| Binding Standard Harmonization Lobbying | CEN-ASTM committee alignment eliminates cross-Atlantic duplicated certification costs for multi-regional product lines. |
Research Approach
Operator-level perspectives from resort procurement directors, alpine boot-fitting technicians, race service team managers, and carbon fiber composite suppliers anchored the qualitative base. Primary interviews combined with secondary validation from ISO standard documentation, EU F-Gas Regulation enforcement records, ANSM calibration mandate filings, and SEC disclosures from listed outdoor equipment conglomerates. Bottom-up equipment shipment data from Austrian and French manufacturing hubs triangulated against top-down resort fleet refresh cycle surveys across the analysis window.
Sensitivity analysis tested forecast robustness across binding standard harmonization scenarios, carbon fiber price volatility bands, and technician shortage severity gradients. Segmentation dimensions modeled include product type complexity tiers, end-user proficiency stratification, technology integration levels, and distribution channel economics. CAGRs derived from equipment replacement frequency curves, rental fleet penetration rates, and smart hardware attach-rate expansion patterns. Industry-specific inputs incorporated FIS homologation timelines and EU fluorinated wax prohibition compliance costs.
Underlying assumptions cover ISO 9462/9465 enforcement continuity, Alpine valley manufacturing labor pool stability, and carbon fiber substitution adoption curves, with deviation risk concentrated in CEN-ASTM protocol divergence extension and F-Gas Regulation hydrocarbon substitute performance gaps. Revision becomes warranted when smart goggles and wearable tracker hardware-software integration complexity triggers legacy equipment obsolescence fragmentation across customer loyalty cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Hiking Cleats Market