
 Fishing Waders Market | 2026-2036
Fishing Waders Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Waders Market Intelligence
A shift from single-source material procurement to a multi-source strategy is decoupling wader production from reliance on specific textile suppliers. This allows for greater design flexibility and supply chain resilience. Simms Fishing Products leverages its strong brand and distribution network in the premium fly fishing segment. Patagonia differentiates through its emphasis on sustainable materials and environmental initiatives, while Orvis sustains a loyal customer base with its long-standing reputation and educational programs.
Fishing waders are waterproof garments designed to keep an angler dry while wading in water. They typically feature sealed seams and are constructed from multi-layer fabrics with a waterproof yet breathable membrane. Chest waders represent the dominant product type due to their versatility across different water depths. Within materials, advanced textiles like Gore-Tex command the premium segment, while neoprene remains prevalent for cold-water applications due to its superior insulation properties.
Regulations concerning chemical use in textiles, such as the EPA's actions on PFAS in the United States and the EU's REACH framework, influence material selection. These standards compel manufacturers to adopt alternative waterproofing treatments. Compliance with these evolving environmental regulations is becoming a critical factor for market access and brand reputation. Future competitive advantage will hinge on developing high-performance, eco-friendly materials that meet both consumer expectations and regulatory mandates.
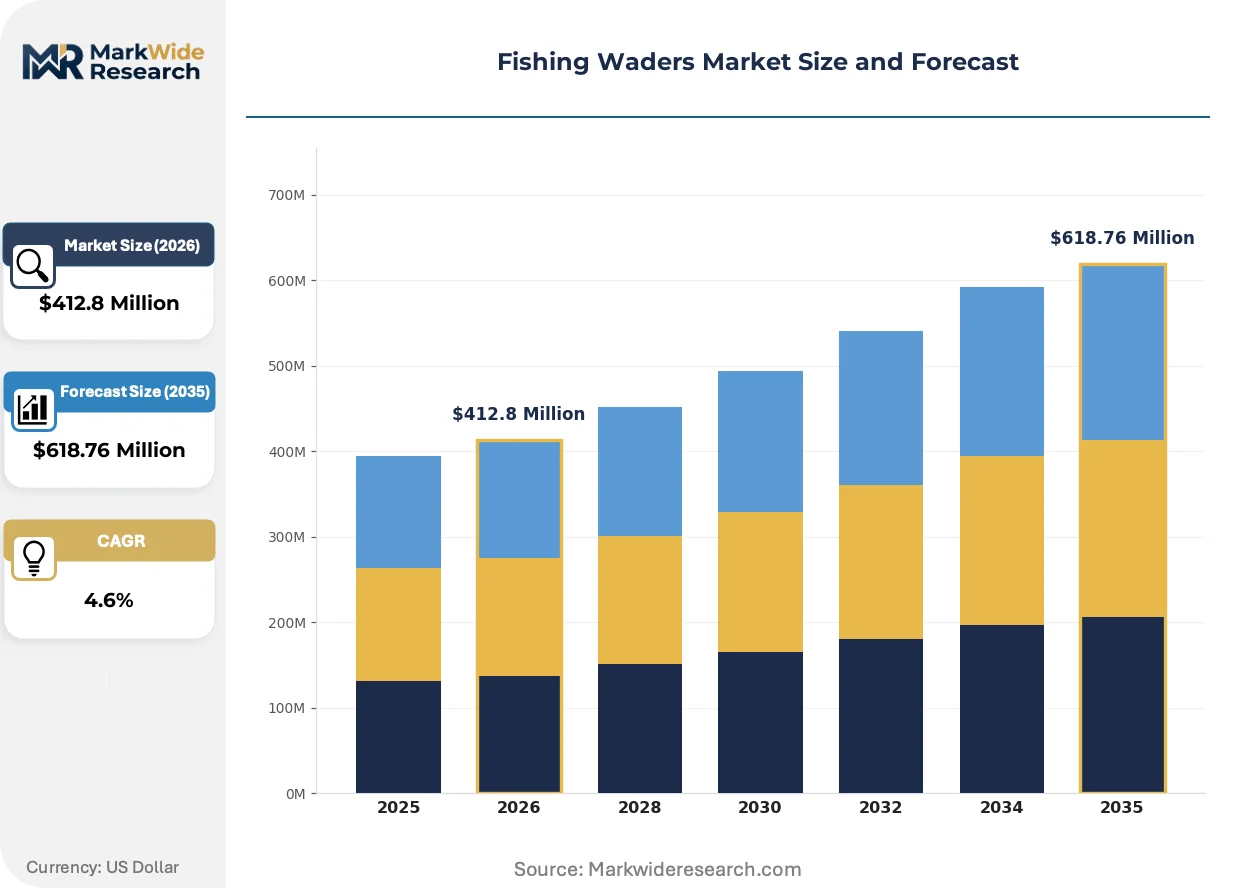
Market Dynamics
The fishing waders market is being fundamentally reshaped by the dual pressures of advancing material science and stringent environmental regulations. This dynamic forces manufacturers to innovate beyond traditional waterproofing technologies while meeting heightened consumer expectations for performance and ecological responsibility.
Growth Catalysts
- Recreational Angler Growth:An expanding base of recreational anglers, particularly in North American fly fishing destinations, directly fuels demand for high-performance waders.
- Material Science Advances:The development of lighter, more durable, and highly breathable multi-layer fabrics enhances user comfort and performance, accelerating replacement cycles.
- E-commerce Channel Expansion:Direct-to-consumer sales and specialized online retailers are broadening market access, enabling brands to reach a wider, more geographically dispersed customer base.
Market Restraints
- Input Cost Volatility:The price of specialized textiles, such as Gore-Tex and other proprietary waterproof breathable membranes, creates significant cost pressures for manufacturers.
- Regulatory Compliance Burden:Adhering to evolving chemical regulations like the EU's REACH and EPA actions on PFAS requires costly R&D and reformulation efforts.
- Performance of Alternatives:Many emerging PFAS-free DWR treatments currently do not match the durability and oleophobicity of legacy C8 and C6 chemistries, creating a performance gap.
Strategic Opportunities
- Sustainable Materials Development:Creating high-performance, biodegradable, or recycled-content wader fabrics presents a significant opportunity to capture environmentally conscious consumers.
- Expansion into Niche Applications:There is untapped potential in adjacent markets such as aquaculture, environmental science fieldwork, and water utility maintenance which require similar protective apparel.
- Women-Specific Designs:Developing anatomically correct waders for the growing segment of female anglers offers a clear path for market differentiation and expansion.
Industry Challenges
- Supply Chain Reconfiguration:Shifting from single-source textile suppliers to a multi-source strategy introduces complexities in quality control, logistics, and material consistency.
- Counterfeit Product Infiltration:The prevalence of counterfeit goods, particularly in online marketplaces, erodes brand equity and poses a safety risk to consumers using substandard products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Waders Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $618.76 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chest Waders, Hip Waders, Waist Waders, Bootfoot Waders Material: Neoprene, Nylon, Polyvinyl Chloride, Rubber, Gore-Tex Application: Freshwater Fishing, Fly Fishing, Saltwater Fishing, Ice Fishing End User: Recreational Anglers, Commercial Fishermen, Guide Services, Sporting Clubs |
| Companies Covered | Skwala, SITKA, Simms Fishing Products, Chota, Redington, Grundéns, Patagonia, DRYFT Fishing, Orvis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Waders Market Strategic Shifts & Innovations
The evolution of material science is converging with a powerful sustainability mandate, creating a new paradigm for product design. This shift is most evident in the composition of waterproof textiles and the lifecycle considerations influencing consumer purchasing decisions.
Multi-layer ePTFE-free waterproof breathable membranes represent a significant technological evolution. These fabrics provide waterproofing and breathability without using perfluorinated compounds, addressing environmental concerns. The premium fly fishing segment is adopting these materials, and this development is rewriting performance benchmarks for environmentally compliant waders.
Regulatory frameworks, including EPA actions on PFAS in the United States and the EU's REACH legislation, directly influence material selection. These rules compel the industry to phase out long-chain fluorocarbon-based durable water repellent (DWR) treatments. The textile supply chain is most impacted, forcing investment in alternative chemistries to maintain market access.
Consumer purchasing behavior shows a pivot towards product longevity and repairability, especially in mature markets. This trend disrupts the model for lower-quality gear, favoring brands that offer robust warranty and repair services. The shift is most pronounced within fly fishing communities in North America and Scandinavia, where environmental stewardship is a core value.
Fishing Waders Market Segmentation
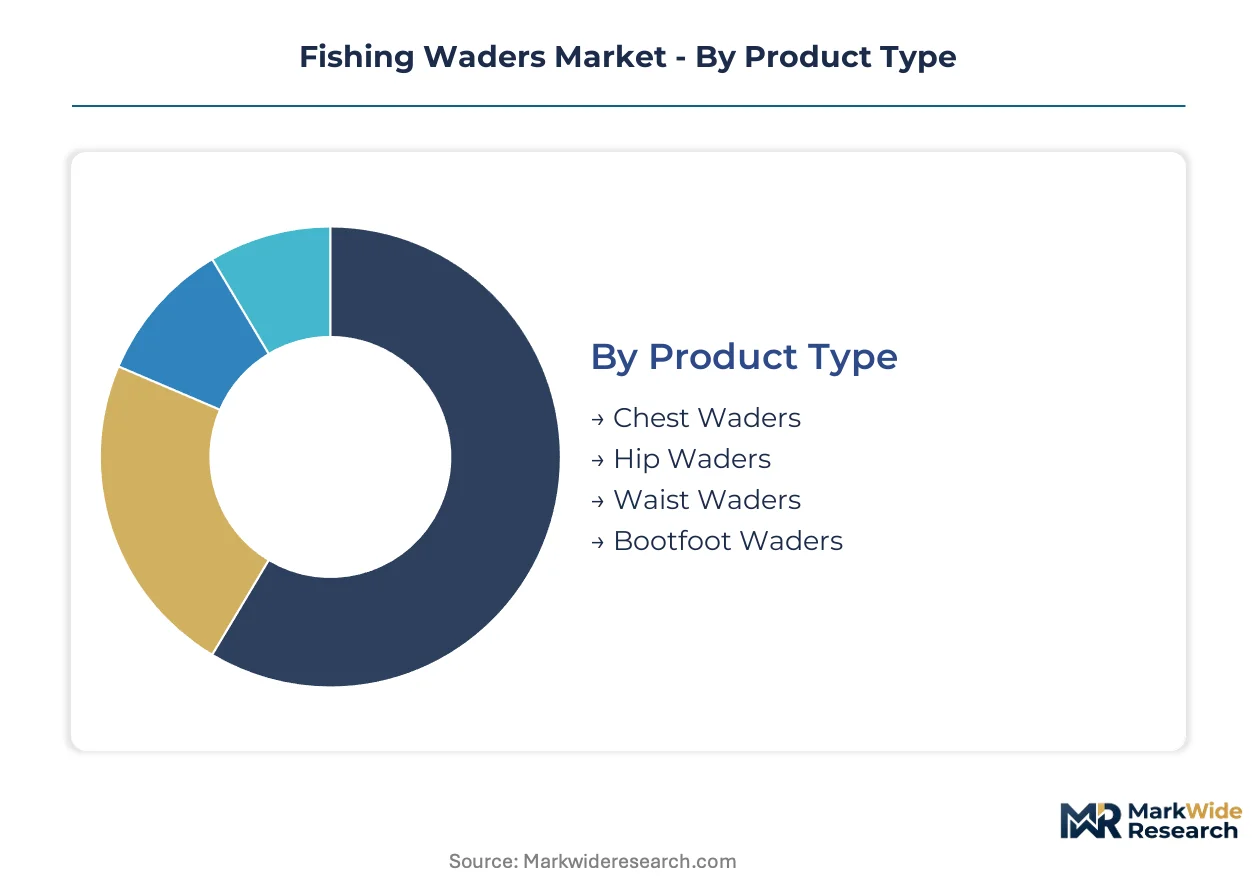
Understanding the distinct segments within the fishing waders market clarifies demand patterns and competitive dynamics. Product variations, material preferences, application specificities, and end-user requirements collectively define the market structure, guiding strategic investments and product development initiatives.
Product Type:
Supply concentration for fishing waders leans heavily towards versatile designs that cater to a broad range of angling conditions.
- Chest Waders:These garments extend from the feet to the chest, offering maximum protection and versatility across varying water depths and conditions. Demand for chest waders is particularly strong in North American fly fishing destinations, driven by the need for full body immersion protection and comfort.
- Bootfoot Waders:Featuring integrated boots, these waders provide convenience and secure footing, eliminating the need for separate wading boots. Anglers in colder climates, such as Canada and Scandinavia, frequently choose bootfoot waders for their superior insulation and ease of use in rugged terrain.
- Hip Waders:Extending to the upper thigh, hip waders are suitable for shallow water fishing or situations requiring minimal water entry. Their lightweight nature appeals to anglers seeking agility and less bulk.
- Waist Waders:Designed to reach the waist, these waders offer greater mobility than chest waders, ideal for shallower waters or warmer conditions. They are favored by anglers prioritizing comfort and freedom of movement.
Chest Waders absorbs the bulk of installed capacity; Bootfoot Waders is expanding most quickly.
Material:
The material segment reflects a clear cost tier differentiation, with advanced fabrics commanding premium prices while traditional options remain accessible.
- Gore-Tex:This advanced textile features a microporous membrane that is waterproof yet breathable, allowing moisture vapor to escape while blocking liquid water. Demand for Gore-Tex waders is highest in the premium fly fishing segment in the United States, where performance and comfort are paramount.
- Neoprene:A synthetic rubber known for its excellent insulation properties, neoprene traps a layer of water against the skin, which is then warmed by body heat. Neoprene waders are highly sought after for cold-water applications, particularly in regions like Alaska and the Great Lakes, due to their thermal efficiency.
- Nylon:Often coated with PVC or polyurethane, nylon waders offer a balance of durability and affordability, making them a popular choice for general recreational use. Their lightweight construction makes them suitable for warmer weather.
- Polyvinyl Chloride:PVC waders are known for their robust waterproofing and lower cost, providing a durable option for entry-level anglers and occasional use. Their resistance to punctures makes them practical.
- Rubber:Traditional rubber waders provide excellent waterproofing and durability, particularly in rugged environments. They are often chosen for their puncture resistance in demanding conditions.
Gore-Tex materials drive the highest average selling prices; Neoprene materials are gaining share fastest in specialized cold-weather applications.
Application:
Application segments highlight the diverse environments and fishing styles that dictate specific wader requirements.
- Fly Fishing:This application demands highly breathable, lightweight, and flexible waders to facilitate casting and movement in rivers and streams. Fly fishing communities in Montana and British Columbia drive significant demand for high-performance breathable waders.
- Saltwater Fishing:Waders for saltwater environments require enhanced durability, corrosion resistance, and protection against abrasive elements like sand and barnacles. Anglers on the Atlantic and Pacific coasts of the United States prioritize robust, puncture-resistant waders.
- Freshwater Fishing:This broad category encompasses various techniques in lakes, rivers, and ponds, requiring versatile waders suitable for different depths and temperatures. General freshwater anglers seek balanced performance and durability.
- Ice Fishing:Specialized waders for ice fishing prioritize maximum insulation and waterproof protection against extreme cold and slush. Anglers in northern states and Canadian provinces use heavily insulated models.
Fly Fishing applications command the most advanced wader technologies; Saltwater Fishing applications show steepest expansion trajectory for heavy-duty models.
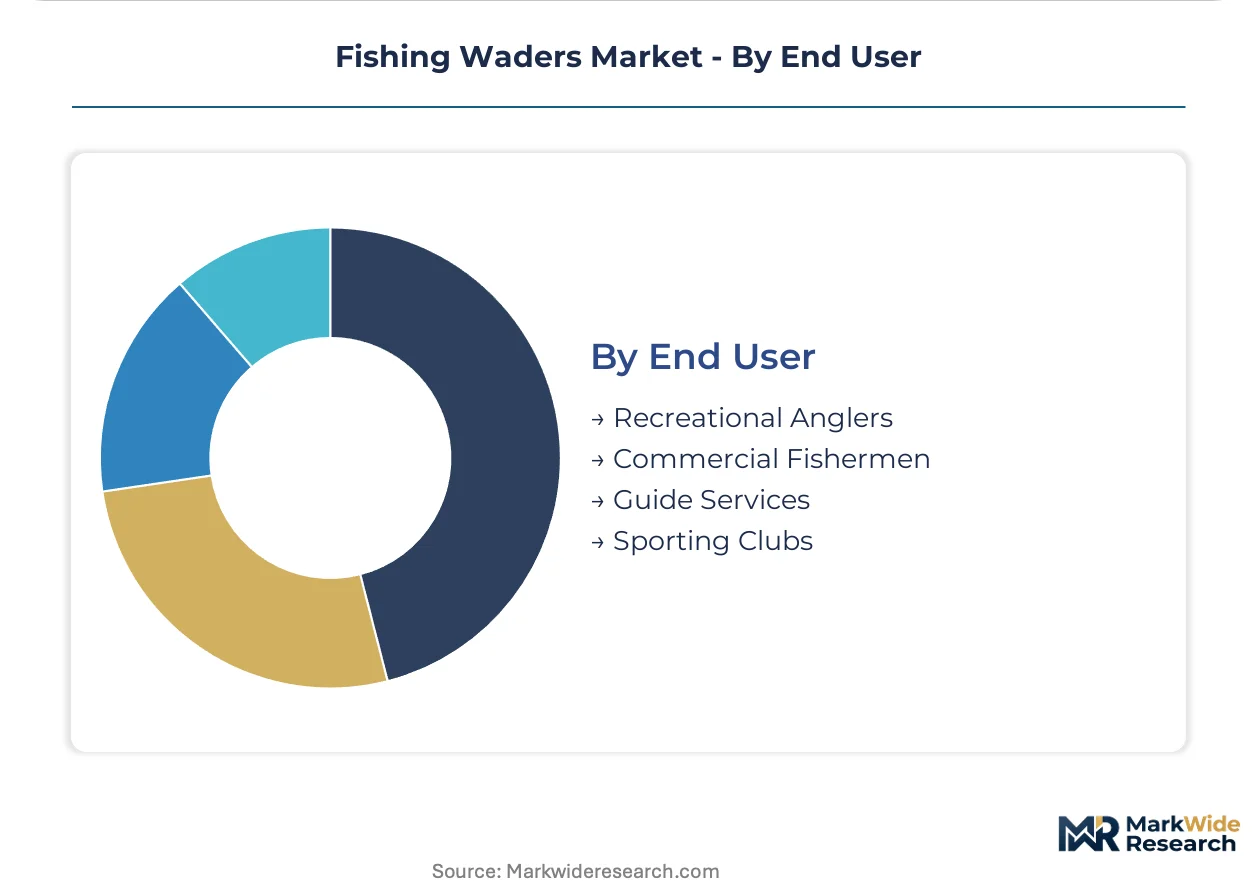
End User:
The end-user segmentation reveals distinct purchasing behaviors and product needs across different user groups.
- Recreational Anglers:This largest segment comprises individuals who fish for leisure, seeking comfort, durability, and performance for various fishing styles. Recreational anglers in the Pacific Northwest and the Northeastern United States constitute a substantial portion of the market.
- Commercial Fishermen:Professional fishermen require extremely durable, heavy-duty waders capable of withstanding constant use and harsh marine or freshwater conditions. Commercial operations in Alaska and the Gulf Coast rely on robust, long-lasting gear.
- Guide Services:Fishing guides need reliable, high-performance waders that can endure frequent use and diverse environments, often prioritizing breathability and repairability. Guide services across the Rocky Mountains invest in premium, durable waders.
- Sporting Clubs:These organizations purchase waders for members or for specific events, often balancing cost-effectiveness with adequate performance for group activities. Clubs frequently seek versatile models for diverse member needs.
Recreational Anglers represent the largest volume segment; Commercial Fishermen are driving demand for specialized, heavy-duty waders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced textile development anchors the fishing waders market across key global regions. Material science innovation and evolving angler preferences shape demand patterns. Regulatory frameworks also influence production and material selection across these diverse geographies.
United States
Recreational anglers, particularly in the premium fly fishing segment, drive consistent demand for high-performance waders. The EPA's actions on PFAS compel manufacturers to invest in alternative waterproofing treatments. The Pacific Northwest region, including cities like Portland, Oregon, remains a hub for outdoor sports gear development and testing.
Canada
Demand for bootfoot waders and insulated models is strong due to cold-water applications and ice fishing in Canadian provinces. Health Canada's environmental regulations increasingly influence the textile supply chain for wader components. British Columbia's extensive river systems and fly fishing tourism support a significant market for specialized waders.
Germany
Germany's outdoor sports culture supports a market for durable, high-performance fishing waders, with a focus on advanced materials. The EU's REACH framework dictates chemical use in textiles, pushing manufacturers towards compliant and sustainable solutions. Southern Germany, particularly Bavaria, features a concentration of outdoor apparel brands and material innovators.
Japan
Japanese anglers show a preference for lightweight, technically advanced waders, reflecting the country's emphasis on precision and material innovation. METI's industrial chemical regulations guide the adoption of new, eco-friendly waterproofing technologies. The Osaka region continues to be a significant center for advanced textile manufacturing and development.
Fishing Waders Market Key Industry Players
Strategic partnerships dominate the current landscape, allowing brands to access specialized material technologies and broaden distribution networks. The market structure features a tiered approach, with premium performance brands at the top, followed by mid-range specialists and value-oriented manufacturers. Key archetypes include innovation-driven material developers, sustainability-focused brands, and established heritage players. Competitive moves center on product innovation through material science and strategic partnerships for enhanced market access.
On the premium-tier vector, Simms Fishing Products exemplifies a brand focused on high-performance fly fishing gear. Patagonia occupies a distinct position by emphasizing sustainable materials and environmental initiatives within its product lines. Orvis, with its long-standing reputation, anchors the market through its loyal customer base and educational programs.
| Leading Market Players |
|---|
| Skwala |
| SITKA |
| Simms Fishing Products |
| Chota |
| Redington |
| Grundéns |
| Patagonia |
| DRYFT Fishing |
| Orvis |
| Others |
Cost & Logistics Intelligence
The performance gap between legacy fluorocarbon-based DWR treatments and emerging PFAS-free alternatives drives a significant divergence in both wader pricing and material procurement strategies. This technical distinction influences consumer willingness to pay and manufacturer sourcing decisions.
Pricing Analysis
Warranty and repair services, often bundled with premium waders, differentiate offerings in the fishing waders market. A value-based pricing model dominates the high-performance segment, where brand premium and advanced material technologies like Gore-Tex justify higher price points. Pricing pressure stems from input cost volatility for specialized textiles and ongoing R&D investments into PFAS-free waterproofing. Entry-level recreational anglers exhibit high price sensitivity, while commercial fishermen prioritize durability over cost for heavy-duty models.
Supply Chain Analysis
Evolving regulatory frameworks, such as the EPA's actions on PFAS in the United States and the EU's REACH framework, reshape sourcing decisions for textile components. The global supply chain for specialized wader materials, including advanced fabrics and waterproofing treatments, primarily draws from manufacturing hubs in Asia and Europe. A structural risk involves commodity price volatility for proprietary membranes and the ongoing challenges of finding high-performance PFAS-free alternatives. Distribution runs through a combination of direct-to-consumer e-commerce platforms and specialized outdoor retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fishing waders market is increasingly a cost-of-compliance narrative, where stringent regulations like the EPA's actions on PFAS create a significant barrier-to-entry moat for compliant manufacturers. This regulatory pressure mandates investment in alternative materials and processes.
For Market Incumbents: Anticipate ongoing regulatory shifts, particularly concerning chemical use in textiles, by proactively investing in next-generation PFAS-free DWR treatments. Incumbents like Simms Fishing Products should leverage their brand equity and distribution networks to counter the threat of counterfeit product infiltration. Deepen vertical integration into material R&D and secure long-term supply agreements for advanced breathable fabrics. Reinforce customer loyalty through robust warranty programs and repair services, aligning with consumer demand for product longevity.
For New Entrants and Emerging Players: Women anglers, an underserved buyer archetype, represent a significant opportunity for new entrants to develop anatomically correct and performance-driven waders. Target niche applications such as environmental science fieldwork or water utility maintenance, where specialized protective apparel is required. A direct-to-consumer sales model emphasizing sustainable materials and transparent sourcing can differentiate offerings. Focus on high-performance, eco-friendly materials that meet stringent regulatory mandates like the EU's REACH framework.
For Investors and Strategic Acquirers: Re-rating potential sits with agile, material-science-focused manufacturers given the accelerating demand for high-performance, eco-compliant waders. Long-term viability hinges on companies that successfully integrate sustainable materials and circular economy principles into their product lifecycle. Target acquisition candidates include innovative textile developers specializing in multi-layer ePTFE-free membranes or brands with strong customer loyalty built on sustainability. The signal to watch is the widespread adoption and performance validation of these new environmentally conscious materials by premium fly fishing communities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in PFAS-Free DWR R&D | Ensures long-term market access by meeting evolving chemical regulations like EPA and REACH. |
| Develop Women-Specific Product Lines | Captures a growing segment of female anglers and drives market differentiation. |
| Expand E-commerce Direct-to-Consumer Channels | Broadens market reach and strengthens brand relationship with geographically dispersed customers. |
| Secure Multi-Source Textile Agreements | Enhances supply chain resilience and reduces reliance on single material suppliers. |
| Offer Robust Repair and Warranty Programs | Builds customer loyalty and aligns with consumer demand for product longevity and sustainability. |
Research Approach
Document review covered regulatory filings from EPA and EU REACH, industry association reports on outdoor sports, and academic material science research, complemented by interviews with key stakeholders. Primary research involved discussions with wader manufacturers, specialized textile suppliers, outdoor retailers, and professional fishing guides. This approach ensured a comprehensive understanding of market dynamics, triangulating insights from both bottom-up and top-down perspectives for validation.
Historical market performance and expert panel input were cross-referenced to develop robust projections across the analysis window. The analytical framework modeled key segmentation dimensions including product type, material composition, application, and end-user demographics. Compound annual growth rates were derived from these granular segment projections, incorporating critical industry-specific inputs such as recreational angler participation rates and material innovation timelines.
Revisions become necessary when unforeseen breakthroughs in material science or abrupt shifts in environmental regulations materialize. Forecasts reflect assumptions regarding consumer preferences and the pace of regulatory enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
North America Personal Watercraft Market