
 Paperboard Jars Market | 2026-2036
Paperboard Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Jars Market Analytics
Plastic is realigning cost structures across rigid packaging as fiber-based alternatives achieve parity at mid-volume runs. Sonoco Products Company leverages its integrated paper mill network to control substrate costs for spiral-wound jar bodies. WestRock Company anchors North American supply through calibrated board grades engineered for moisture resistance in personal care applications. Brdrene Hartmann A/S specializes in molded fiber lids that pair with paperboard bases, extending its dairy packaging expertise into cosmetic jars.
Paperboard jars are cylindrical or polygonal containers fabricated from laminated paperboard substrates, typically incorporating barrier coatings or aluminum foil layers to resist moisture and oxygen ingress; spiral winding or convolute forming processes build rigid sidewalls from plies of recycled or virgin kraft fiber, yielding lightweight yet structurally stable vessels for dry and semi-moist goods. Round Jars dominate current output due to compatibility with standard filling lines and label adhesion economics, while Custom Shapes command margin pools through premium cosmetic positioning and shelf differentiation. Eco-friendly Jars compete on regulatory alignment rather than unit cost, as compostable coatings and water-based inks add processing complexity that narrows addressable volume tiers.
The EU Packaging and Packaging Waste Regulation and the US EPA sustainable materials management framework both mandate extended producer responsibility for packaging recovery, directly shaping substrate selection and end-of-life design requirements for jar manufacturers. FDA food contact substance notifications and EFSA compliance pathways govern barrier coating approvals, creating market access friction for non-certified entrants. Stakeholders must monitor evolving compostability certification standards and regional collection infrastructure gaps before committing capital to coated paperboard capacity expansions.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing plastic jar volumes while calibrated fiber barrier coatings unlock semi-moist cosmetic applications previously reserved for rigid polymers.
Growth Catalysts
- REACH-compliant barrier coatings:ECHA-registered aqueous polymer dispersions now achieve oxygen transmission rates below 0.5 cc/m²/day, qualifying paperboard jars for hyaluronic acid serums and retinol creams.
- German personal care manufacturing corridor:Formulation houses in Hamburg and contract packagers in Stuttgart co-locate with specialized spiral-wound converters, reducing logistics friction for premium skincare brands.
- Compostable lid-to-jar systems:Molded fiber closures paired with paperboard bases create monomaterial packaging streams that satisfy France's AGEC law extended producer responsibility thresholds.
Market Restraints
- Kraft pulp cost volatility:Northern European softwood fiber prices swing with energy input costs, compressing converter margins on mid-volume cosmetic runs.
- Barrier coating certification timelines:FDA food contact substance notifications and EFSA compliance pathways extend 18-24 months, freezing capacity commitments for non-certified entrants.
- Aluminum foil lamination dependency:High-barrier jars require foil layers that complicate repulping and raise material recovery costs under EU waste framework targets.
Strategic Opportunities
- Semi-moist pet treat segment:Premium pet food brands in France and Germany seek moisture-resistant fiber jars as alternatives to plastic tubs for jerky and dental chews.
- Pharmaceutical solid dose expansion:OTC tablet and powder applications present white space as FDA 21 CFR compliance pathways for fiber-based primary packaging mature.
- Digital printing convergence:HP Indigo and Xeikon presses enable run-length-flexible decoration, allowing cosmetic brands to execute limited-edition regional launches without cylinder costs.
Industry Challenges
- Moisture vapor transmission rate calibration:Formulators lack standardized test protocols for semi-moist goods, forcing case-by-case stability studies that extend qualification timelines.
- Spiral-winding technician scarcity:Specialized machine operators for convolute forming and ply-tension control are concentrated in legacy packaging regions, constraining greenfield capacity ramp rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Jars Market |
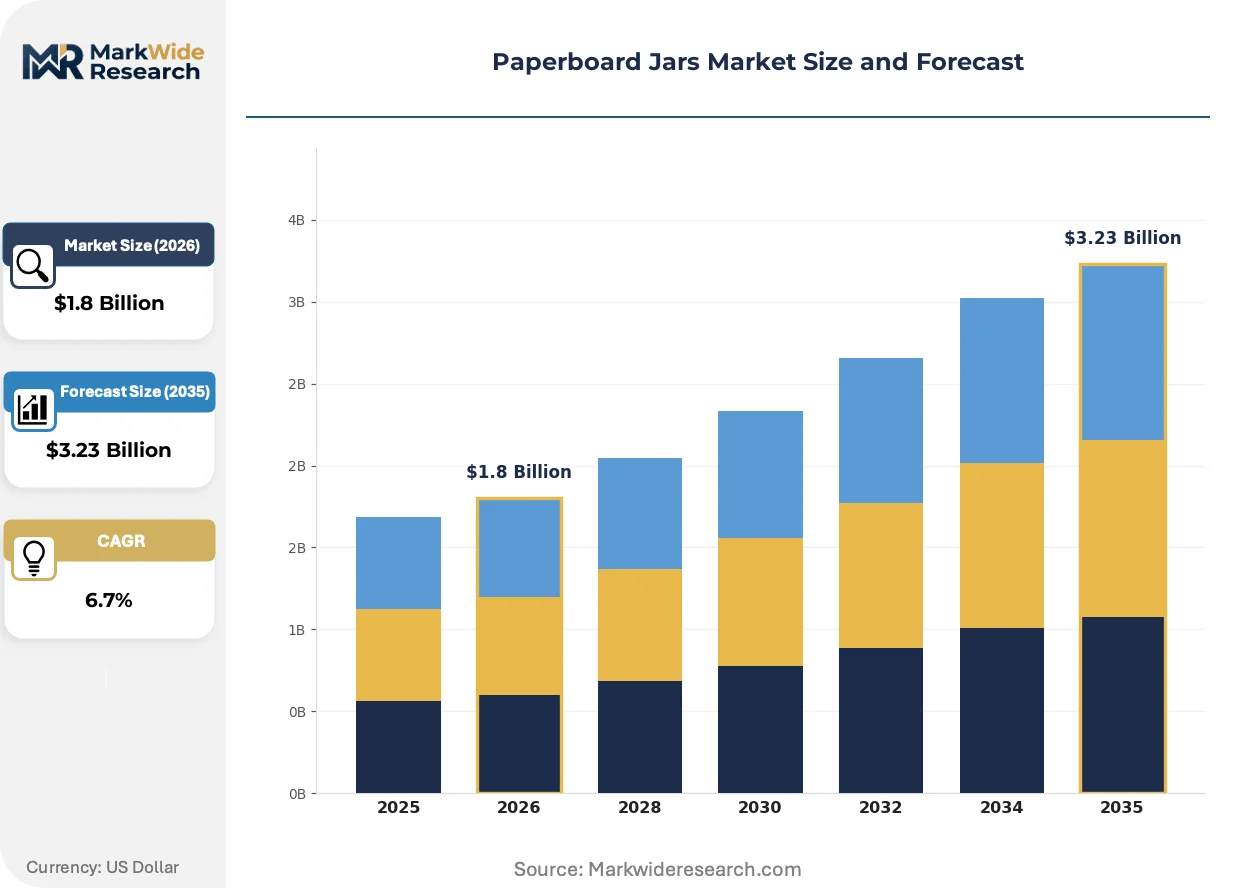
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Jars, Square Jars, Custom Shapes, Eco-friendly Jars End User: Cosmetics, Food & Beverages, Pharmaceuticals, Home Care Capacity: 50 ml, 100 ml, 250 ml, 500 ml Closure Type: Twist-off, Flip-top, Screw Cap, Push-on |
| Companies Covered | Sonoco Products Company, WestRock Company, Chicago Paper Tube & Can Company, Brdrene Hartmann A/S, Nagel Paper, Halaspack Bt, Irwin Packaging Pty Ltd., Ace Paper Tube, Paper Tube Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Jars Market Evolving Landscape
Barrier coating chemistry and digital production workflows are collapsing minimum viable run lengths while regulatory compliance automation reshapes qualification protocols for fiber-based primary packaging.
Water-based ethylene vinyl alcohol copolymer coatings are absorbing moisture protection duties previously assigned to extruded polyethylene layers. Premium cosmetic brands in Germany and France specify these coatings for hyaluronic acid formulations with 12-24 month shelf life requirements. The technology is absorbing volume from aluminum-foil-laminated structures by eliminating delamination risk during temperature cycling.
EU Green Deal packaging sustainability targets now require 70% material recovery rates by 2030, forcing jar designers to eliminate multimaterial constructions. EFSA and national regulators are harmonizing compostability certification requirements across member states, reducing fragmentation that previously blocked cross-border sourcing. Personal care contract manufacturers in the Netherlands and Belgium are consolidating supplier lists to converters with dual FDA-EFSA coating approvals.
Brand procurement teams now specify run-length flexibility as a primary vendor selection criterion, displacing volume-commitment contracts that favored plastic jar suppliers. Digital inkjet decoration enables cosmetic houses to execute 5,000-unit regional test markets without cylinder engraving costs or six-week lead times. This pattern is most visible in French prestige skincare, where seasonal limited editions now constitute 30-40% of annual jar volumes for mid-tier houses.
Paperboard Jars Market Segmentation
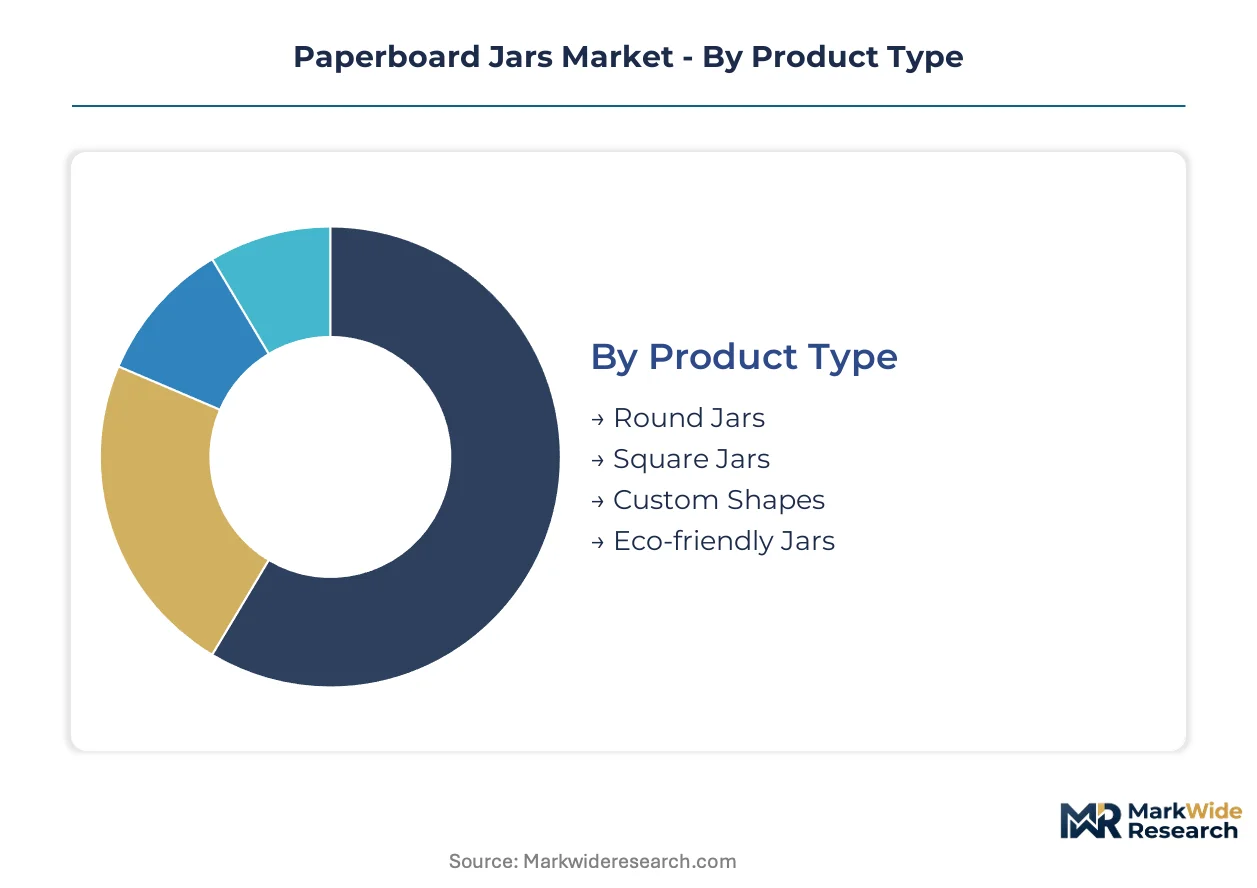
Paperboard jar manufacturers align product architectures with specific filling line requirements and shelf differentiation strategies. Each segmentation dimension carries distinct margin implications and regulatory compliance burdens.
Product Type:
Brand procurement teams cycle through jar geometries based on label adhesion economics and premium positioning requirements.
- Round Jars:Spiral-wound cylindrical bodies maximize compatibility with standard rotary filling equipment and minimize label waste through continuous wrap application. Demand concentrates in Germany's mass-market skincare lines where throughput velocity outweighs shelf differentiation.
- Custom Shapes:Polygonal and asymmetric profiles require convolute forming with calibrated ply tension control, yielding structural stability for prestige cosmetic positioning. French prestige houses specify these for limited-edition launches where silhouette recognition drives repurchase intent.
- Square Jars:Right-angle geometry optimizes pallet density for retail distribution while demanding reinforced corner plies to prevent compression failure.
- Eco-friendly Jars:Compostable substrates and water-based barrier coatings satisfy France's AGEC law extended producer responsibility thresholds.
Volume placements concentrate in Round Jars; the faster expansion belongs to Custom Shapes.
End User:
Formulation chemistry and regulatory pathway maturity determine addressable jar specifications across verticals.
- Cosmetics:Hyaluronic acid serums and retinol creams drive demand for EVOH barrier coatings with oxygen transmission below 0.5 cc/m²/day. German and French contract packagers specify these for 12-24 month shelf life requirements.
- Food & Beverages:Dry and semi-moist applications dominate, with moisture vapor transmission rate calibration forcing case-by-case stability studies that extend qualification timelines.
- Pharmaceuticals:OTC solid dose applications present white space as FDA 21 CFR compliance pathways for fiber-based primary packaging mature.
- Home Care:Powder and tablet formulations utilize standard kraft barriers without specialized coatings, prioritizing unit cost over performance specifications.
Cosmetics commands the dominant placement volume; Pharmaceuticals shows the steepest expansion trajectory as regulatory pathways mature.
Capacity:
Line changeover economics and retail channel requirements shape volume distribution across size tiers.
- 100 ml:Mid-range format balances sample-to-full-size upgrade pathways for skincare brands, dominating German drugstore distribution.
- 250 ml:Standard household quantity for dry goods and bulk cosmetics, optimizing shelf-facing efficiency in French hypermarkets.
- 50 ml:Travel retail and trial-size specifications concentrate in airport duty-free channels.
- 500 ml:Institutional and refill applications require reinforced sidewall plies to prevent handling damage.
100 ml placements lead current output; 250 ml is climbing the fastest as household sizing standardizes.
Closure Type:
Monomaterial system design and user experience requirements drive specification divergence.
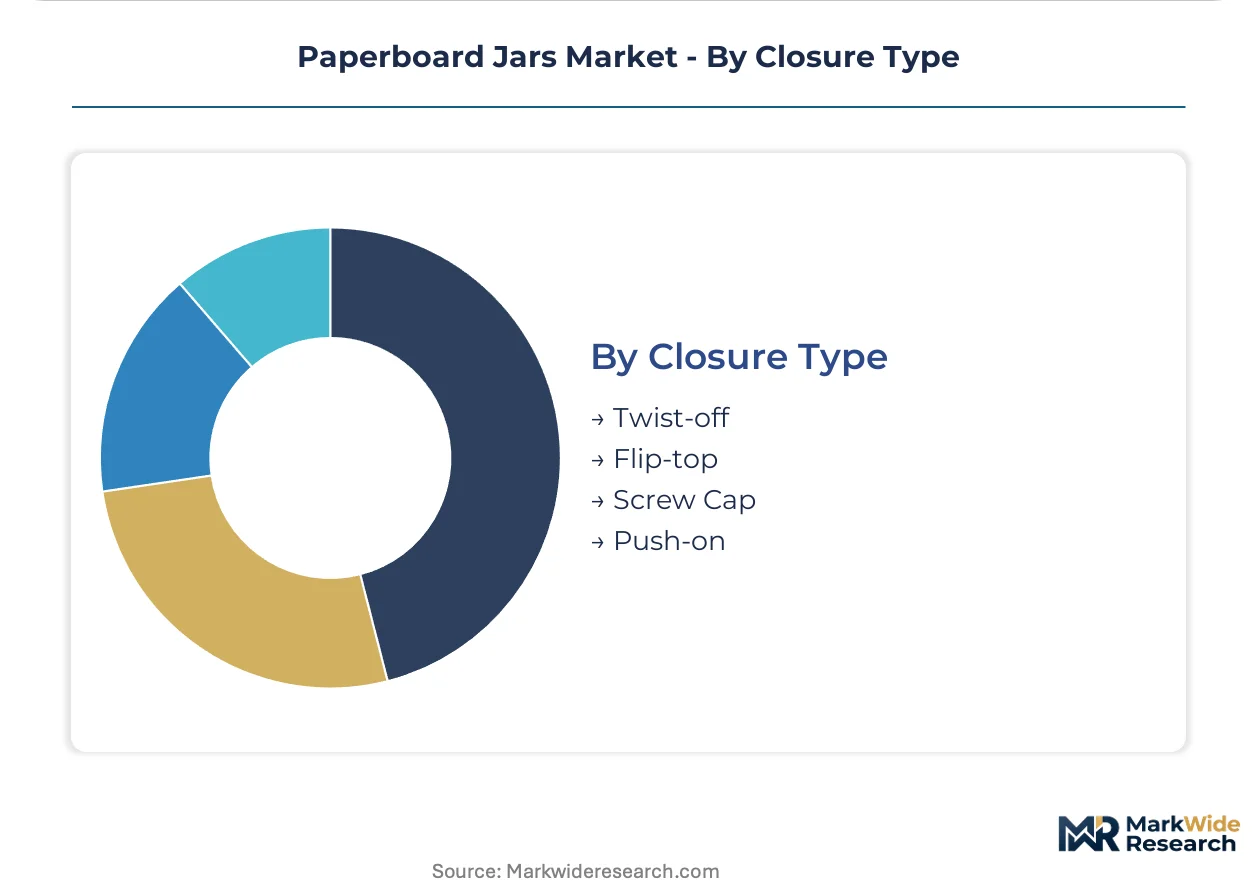
- Twist-off:Metal lug closures on molded fiber lids create resealable systems compatible with existing capping equipment. French dairy converters leverage this expertise for cosmetic jar expansion.
- Screw Cap:Threaded plastic or fiber closures enable precise torque specifications for semi-moist goods, though multimaterial construction complicates EU waste framework compliance.
- Flip-top:Hinged fiber designs suit single-hand dispensing for home care powders, requiring living-hinge ply engineering.
- Push-on:Friction-fit fiber lids enable monomaterial construction that satisfies compostability certification requirements.
Screw Cap volume dominates existing lines; Twist-off configurations are gaining share fastest as monomaterial mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium skincare brands in Germany and France are converting rigid plastic jar volumes to fiber-based alternatives at the fastest clip in Europe. The EU Packaging and Packaging Waste Regulation is compressing polymer demand while calibrated barrier coatings unlock semi-moist applications previously reserved for plastics.
Germany
Formulation houses in Hamburg and contract packagers in Stuttgart co-locate with specialized spiral-wound converters, reducing logistics friction for mid-volume cosmetic runs. ECHA-registered aqueous polymer dispersions now achieve oxygen transmission rates below 0.5 cc/m²/day, qualifying paperboard jars for retinol creams with 24-month shelf life requirements. The Baden-Württemberg packaging cluster hosts multiple converters with dual FDA-EFSA coating approvals.
France
Prestige skincare houses specify custom polygonal jar profiles for limited-edition launches where silhouette recognition drives repurchase intent. France's AGEC law mandates extended producer responsibility thresholds that favor monomaterial fiber systems over multimaterial constructions. The Île-de-France region concentrates digital printing capacity for run-length-flexible decoration of seasonal cosmetic lines.
United States
Personal care contract manufacturers in New Jersey and California are consolidating supplier lists to converters with validated FDA 21 CFR compliance pathways for fiber-based primary packaging. The EPA sustainable materials management framework shapes substrate selection through extended producer responsibility mandates. Chicago-area tube and can specialists anchor North American spiral-winding capacity for mid-volume cosmetic applications.
Netherlands
Personal care contract manufacturers in the Randstad region are standardizing on converters with dual FDA-EFSA coating approvals to streamline cross-border sourcing. The Dutch national implementation of EU Green Deal packaging targets accelerates fiber substitution in semi-moist goods. Rotterdam's logistics hub enables just-in-time delivery of barrier-coated substrates to Belgian and German formulation houses.
Denmark
Molded fiber lid specialists leverage dairy packaging expertise into cosmetic jar closures that pair with paperboard bases for monomaterial systems. Danish converters serve Swedish and Norwegian brands seeking AGEC-aligned packaging for Nordic market entry. The Copenhagen-Oresund corridor hosts technical centers calibrating moisture vapor transmission rates for semi-moist pet treat applications.
Paperboard Jars Market Competitive Landscape
Capacity expansion dominates the current landscape as converters add calibrated board grades and barrier coating lines to capture cosmetic brand conversions. The vendor base clusters around three strategic archetypes: integrated paperboard producers with captive pulp supply, specialized spiral-wound converters with formulation house relationships, and molded fiber specialists extending adjacent packaging expertise. M&A activity concentrates on coating technology acquisitions, while geographic expansion targets the German personal care manufacturing corridor.
Among North American integrated producers, Sonoco Products Company and WestRock Company exemplify the scale-driven archetype with paper mill networks controlling substrate costs. Brdrene Hartmann A/S represents the molded fiber specialist model, leveraging dairy closure expertise into cosmetic jar applications. These three occupy positions across the supply chain from raw fiber through finished container, reflecting the vertical scope required to serve EU regulatory mandates.
| Leading Market Players |
|---|
| Sonoco Products Company |
| WestRock Company |
| Chicago Paper Tube & Can Company |
| Brdrene Hartmann A/S |
| Nagel Paper |
| Halaspack Bt |
| Irwin Packaging Pty Ltd. |
| Ace Paper Tube |
| Paper Tube Co. |
| Others |
Value Network & Pricing Analysis
Cosmetic brand procurement consolidation around dual FDA-EFSA coating approvals is forcing converter capacity investments that compress mid-tier margins while premium custom-shape jars capture widening spreads. This demand-side specification tightening reshapes supply economics across European fiber packaging corridors.
Pricing Analysis
Volume placements in standard round jars trade at thin margins calibrated to kraft pulp input costs, while custom polygonal profiles and EVOH-barrier specifications sustain premium-mid-economy pricing differentiation. Certification tier separates REACH-registered coating systems from uncertified alternatives, with FDA 21 CFR compliance adding further price stratification. Pricing pressure stems from Northern European softwood fiber cost volatility that converters cannot fully pass through on annual contracts. Mass-market skincare brands in Germany exhibit highest price sensitivity; French prestige houses with limited-edition programs show least.
Supply Chain Analysis
Direct-to-formulator channels handle cosmetic brand demand through co-located converter relationships in Hamburg and Stuttgart production clusters. Raw material flows draw from Swedish and Finnish pulp mills, ECHA-registered aqueous polymer dispersion suppliers in Germany, and aluminum foil laminators in Italy. Distribution runs through Rotterdam's logistics hub for just-in-time substrate delivery to Benelux and Nordic formulation houses. Single-source vulnerability concentrates in specialized spiral-winding machine operators for convolute forming, constraining greenfield capacity ramp rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paperboard jar manufacturing sits in a substrate-transition phase as EVOH barrier coatings displace aluminum-foil-laminated structures previously standard for semi-moist cosmetic applications.
For Market Incumbents: Deepen backward integration into captive pulp supply or ECHA-registered coating chemistry to defend margin position against kraft cost volatility. Prioritize dual FDA-EFSA certification investments to capture procurement consolidation among contract manufacturers seeking cross-border sourcing flexibility. Lock in spiral-winding technician training pipelines to preempt labor scarcity constraints on capacity expansion. For New Entrants and Emerging Players: Digital printing-enabled run-length flexibility offers a technology-first wedge against cylinder-dependent incumbents serving French prestige skincare limited editions. Target the semi-moist pet treat segment in France and Germany where moisture-resistant fiber jars lack established supplier relationships. Pursue pharmaceutical solid dose applications as FDA 21 CFR compliance pathways mature, positioning ahead of regulatory threshold crossings. For Investors and Strategic Acquirers: The window for entry favors coating technology specialists with ECHA-registered aqueous polymer platforms applicable to personal care barrier specifications. Long-term viability hinges on monomaterial system design capabilities aligned with EU Green Deal recovery mandates. Watch compostability certification harmonization across member states as the inflection signal for cross-border sourcing scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Technology Acquisition | EVOH chemistry expertise unlocks semi-moist cosmetic applications previously reserved for plastics. |
| Dual Certification Investment | Simultaneous FDA and EFSA approvals streamline procurement for multinational personal care brands. |
| Digital Printing Capacity Addition | HP Indigo and Xeikon presses enable 5,000-unit regional test markets without cylinder costs. |
| Spiral-Winding Technician Training Program | Specialized convolute forming skills constrain greenfield ramp rates across European packaging clusters. |
| Monomaterial System Development | Molded fiber lids paired with paperboard bases satisfy France's AGEC law extended producer responsibility thresholds. |
Research Methodology
Independent corroboration across converter production data, cosmetic brand procurement specifications, and ECHA registration databases underwrites the qualitative findings. Primary interviews with spiral-winding machine operators, formulation house packaging engineers, and contract manufacturer sourcing directors combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation tracking, kraft pulp trade flow data, and FDA food contact substance notification filings. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical cosmetic jar substitution rates and pharmaceutical packaging regulatory pathway maturation timelines structured the projection horizon. The analytical framework segments by jar geometry, barrier specification tier, end-use vertical, and regional manufacturing cluster, with CAGRs derived from elasticity-calibrated penetration curves. EVOH coating adoption trajectories and digital printing run-length economics served as industry-specific forecast inputs throughout the modeling period.
Several conditions sit outside the modeled scope, including abrupt shifts in Northern European energy input costs affecting pulp pricing, unilateral national compostability certification requirements fragmenting EU sourcing, and pharmaceutical regulatory pathway delays extending qualification timelines. Forecasts reflect assumptions about ECHA registration continuity and spiral-winding labor supply stability that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Micro Flute Paper Market