
 Corrugated Board Market | 2026-2036
Corrugated Board Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Board Market Intelligence
North American containerboard producers is expanding mill capacity near Memphis and Green Bay to serve corrugated sheet feeder operations. International Paper leverages vertical integration from pulp through box plants to control cost structures across the Midwest. Smurfit Kappa anchors European supply through its recycled fiber network and pan-regional converting footprint. WestRock competes on specialty coated grades for retail-ready display packaging in grocery and club channels.
Corrugated board consists of fluted paper medium laminated between flat linerboards, typically manufactured through steam-heated corrugating rolls at speeds exceeding 300 meters per minute to produce lightweight yet structurally rigid panels for protective packaging and point-of-sale display. Single-wall configurations dominate volume in food packaging and consumer goods shipping due to cost efficiency, while triple-wall grades command premium positioning in industrial machinery and automotive parts logistics where compression strength requirements exceed 1,000 kilonewtons per meter. Recycled paper feeds the majority of European and North American output, though virgin kraft fiber sustains higher performance tiers in electronics and healthcare applications demanding moisture resistance and cleanliness certification.
The EPA oversees containerboard mill effluent standards under the Clean Water Act, while the EU Green Deal and REACH framework constrain chemical additives in recycled pulp streams and mandate minimum recycled content thresholds for packaging placed on European markets. FDA regulations govern food-contact corrugated materials in the United States through 21 CFR standards for paper and paperboard components. Stakeholders must monitor how evolving extended producer responsibility schemes in multiple jurisdictions reshape collection infrastructure economics and raw material availability for recycled fiber mills.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery timelines, forcing corrugated converters to co-locate box plants within 50 miles of regional distribution hubs to eliminate freight deadheading and reduce damage rates in last-mile transit.
Growth Catalysts
- EU Green Deal recycled-content mandates:Packaging placed on European markets must meet escalating minimum thresholds for post-consumer fiber, redirecting converter procurement toward de-inking and pulp preparation investments.
- Automotive parts logistics:Just-in-time assembly lines in Germany's industrial corridor require triple-wall corrugated dunnage rated above 1,000 kilonewtons per meter for heavy component transit.
- Steam-heated corrugating roll speeds:Lines exceeding 300 meters per minute enable lightweight single-wall production that cuts fiber input per box while maintaining edge crush resistance for parcel sorting systems.
Market Restraints
- Old corrugated container price volatility:Recycled fiber mills face margin compression when OCC export demand from Asian packaging producers spikes, squeezing North American and European converter feedstock costs.
- Pan-regional supply concentration:Smurfit Kappa's recycled fiber network and converting footprint across 35 European countries creates dependency risk for independent sheet feeders in secondary markets.
- Plastic crate substitution:Returnable transit packaging in closed-loop automotive and beverage distribution displaces one-way corrugated for high-frequency routes, capping volume growth in mature logistics corridors.
Strategic Opportunities
- Central and Eastern Europe underpenetration:Poland, Romania, and Hungary show corrugated consumption per capita below Western European averages, creating white space for regional mill-converter integration.
- Smart packaging convergence:Integration of printed electronics and RFID inlays into corrugated retail-ready displays enables inventory tracking and anti-counterfeiting for high-value consumer goods.
- Extended producer responsibility schemes:France, Italy, and Spain are implementing packaging fee structures that reward higher recycled content, tilting procurement toward integrated producers with captive fiber recovery.
Industry Challenges
- Corrugator operator skill shortages:Steam-heated roll maintenance, flute profile calibration, and adhesive viscosity control require specialized technicians that mills struggle to retain in competitive labor markets.
- Food-contact certification timelines:FDA 21 CFR compliance for recycled-content linerboard demands extensive migration testing, delaying product launches by 12-18 months for converters entering fresh produce packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Board Market |
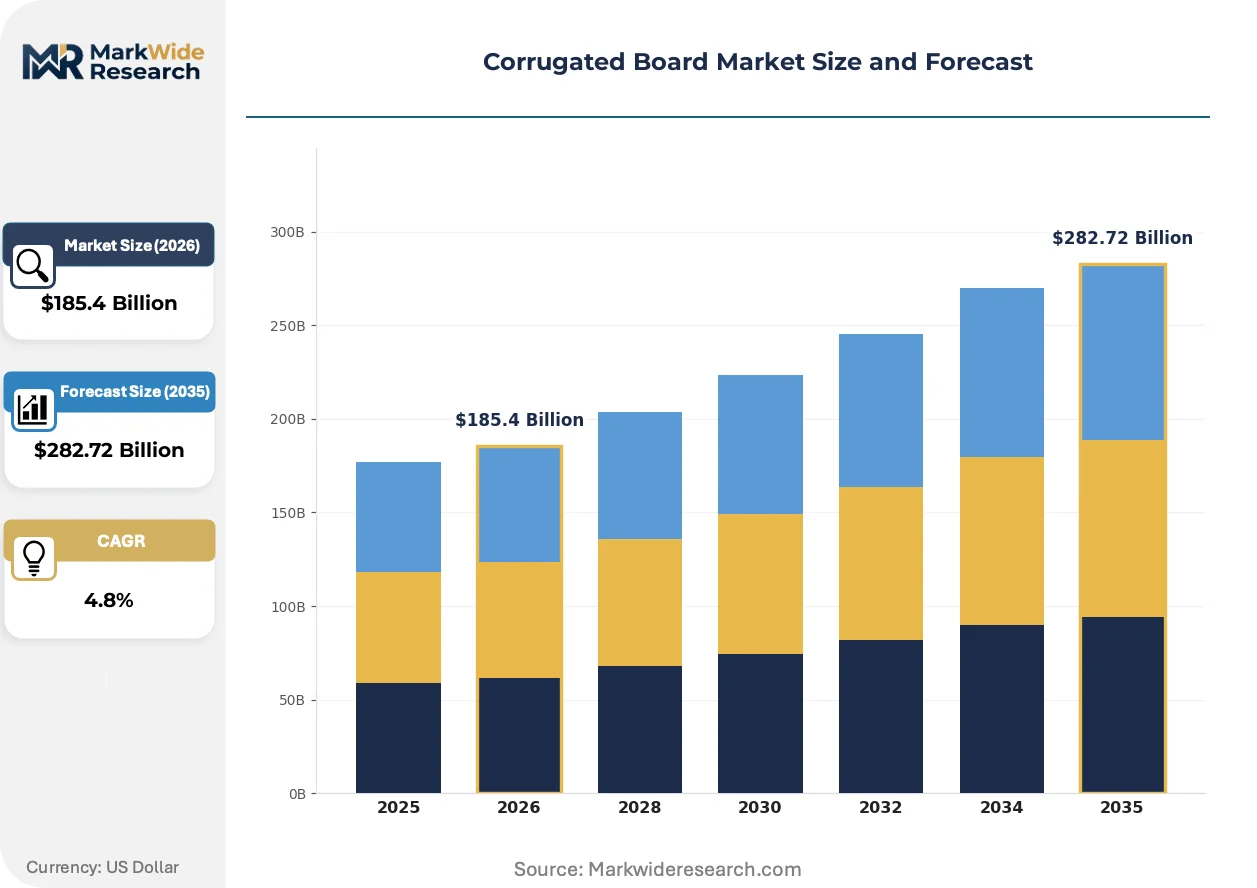
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $282.72 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Decorative End User: Food Packaging, Electronics, Consumer Goods, Healthcare Material: Recycled Paper, Virgin Fiber, Coated Board, Kraft Paper Application: Shipping, Retail Display, Storage, Manufacturing |
| Companies Covered | International Paper, Smurfit Kappa, WestRock, Mondi Group, DS Smith, Packaging Corporation of America, Rengo Co., Ltd., Oji Holdings Corporation, Cascades Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Board Market Strategic Shifts & Innovations
Digital print technologies and fiber engineering advances are collapsing the traditional separation between protective shipping containers and retail-ready display packaging, enabling corrugated to capture shelf-facing applications previously held by folding carton and litho-laminated board.
Water-based flexographic printing with expanded gamut ink sets is unifying short-run customization with high-speed production economics. E-commerce merchants in apparel and electronics are adopting digitally printed boxes at run lengths below 5,000 units. This capability is compressing minimum order quantities and enabling regional converters to serve national brand accounts without plate inventory overhead.
REACH framework constraints on chemical additives in recycled pulp streams are forcing European mills to reformulate wet-strength resins and sizing agents. The industrial consequence is a supply bifurcation: packaging for electronics and healthcare migrates toward virgin kraft fiber certified for cleanliness, while grocery and industrial applications absorb reformulated recycled grades with adjusted performance specifications.
Brand procurement teams are consolidating corrugated suppliers to capture total-cost transparency across box specifications, freight optimization, and inventory carrying charges. This consolidation is displacing fragmented spot-buying relationships that dominated pre-2020 packaging procurement. The shift is most visible in North American grocery and club retail channels, where private-label expansion demands consistent print quality and traceable fiber sourcing across thousands of SKUs.
Corrugated Board Market Segmentation
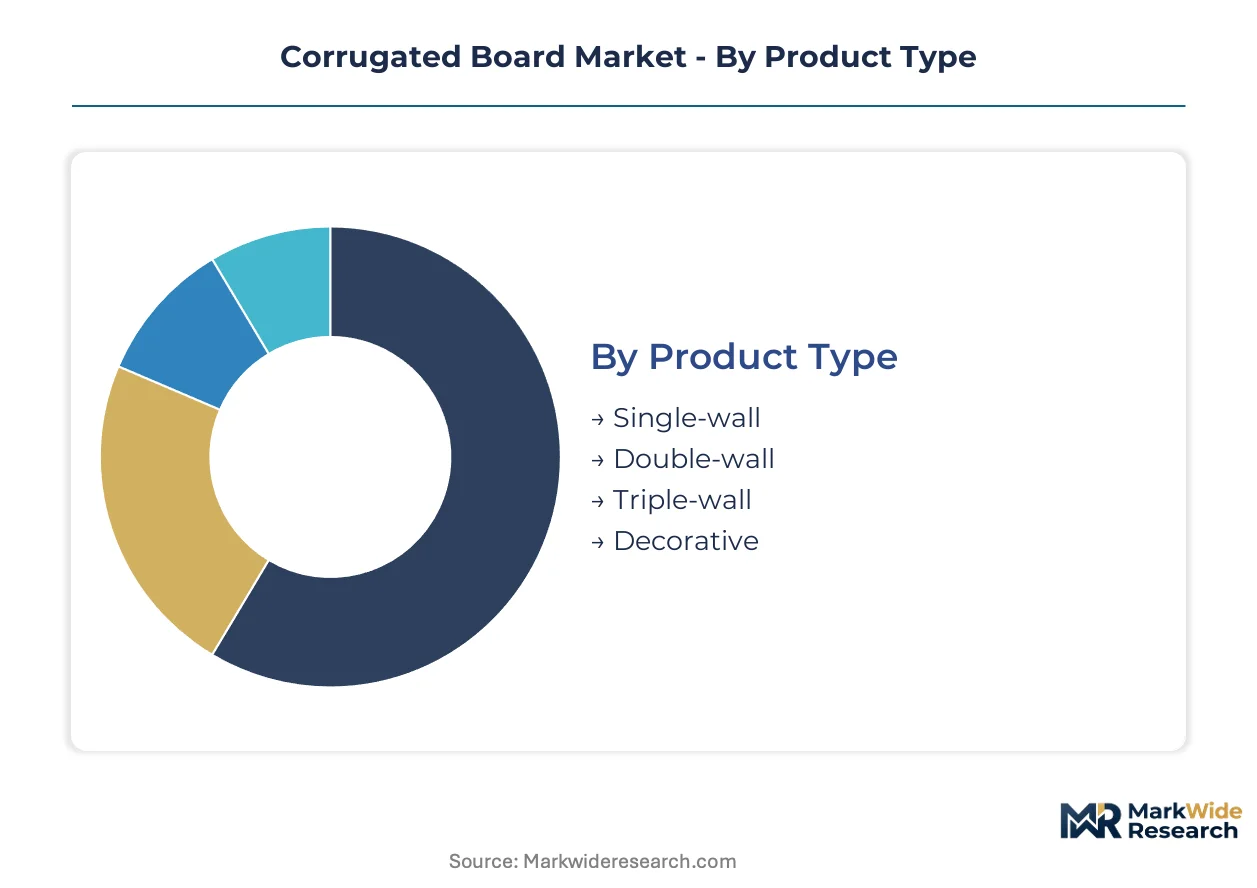
Corrugated board segmentation reflects the tension between protective performance and cost efficiency across supply chains. Product wall configuration, end-use contamination sensitivity, and fiber sourcing strategy each reshape procurement patterns and margin structures for converters.
Product Type:
Wall configuration determines compression strength, stacking height tolerance, and fiber consumption per unit — the core technology axis governing material selection.
- Single-wall:One fluted medium between two linerboards delivers 200-275 kilonewtons per meter edge crush resistance. E-commerce parcel networks in Germany and the United States concentrate demand here for lightweight consumer goods where sorting machinery stress is moderate.
- Triple-wall:Three fluted layers laminated between four linerboards achieve compression ratings exceeding 1,000 kilonewtons per meter. Automotive parts logistics from Stuttgart to Wolfsburg and heavy machinery exports from Milwaukee require this grade for just-in-line assembly protection.
- Double-wall:Two fluted mediums suit mid-weight industrial components and bulk food distribution where pallet stability matters.
- Decorative:Pre-printed linerboards with specialty coatings serve point-of-sale displays in grocery and club retail channels.
Mature deployment sits with single-wall configurations in high-volume e-commerce fulfillment. Newer deployment is concentrated in triple-wall solutions for Germany's automotive corridor.
End User:
Contamination risk and regulatory exposure divide procurement specifications sharply across customer categories.
- Food Packaging:FDA 21 CFR compliance for direct contact and EU framework constraints on recycled fiber migration dominate specification sheets. Fresh produce distribution in California's Central Valley and dairy logistics in Wisconsin demand virgin kraft linerboard with moisture-resistant sizing.
- Electronics:Static control coatings and cleanliness certification separate premium grades from commodity supply. Semiconductor and smartphone fulfillment from Shenzhen to Austin requires low-lint virgin fiber with controlled ionic contamination.
- Consumer Goods:Apparel and home product shippers prioritize print quality and dimensional consistency for unboxing experience.
- Healthcare:Sterility barriers and traceability requirements push medical device packaging toward certified supply chains with batch documentation.
Established procurement patterns center on food packaging with decades of regulatory precedent. Expanding most quickly is electronics fulfillment as unboxing aesthetics merge with protective function.
Material:
Fiber origin governs performance ceiling, sustainability credentialing, and exposure to old corrugated container price cycles.
- Recycled Paper:Post-consumer fiber feeds European output under EU Green Deal mandates. De-inking investments in the Netherlands and Poland determine regional supply quality for grocery and industrial applications.
- Virgin Fiber:Unbleached kraft from southern US pine and Scandinavian softwood sustains moisture resistance and cleanliness tiers. Electronics manufacturers in Austin and healthcare suppliers in Switzerland specify this grade despite cost premiums.
- Coated Board:Polymer or wax barriers extend shelf life for fresh produce and frozen distribution.
- Kraft Paper:Unbleached natural kraft serves export packaging where humidity resistance and tear strength outweigh whiteness requirements.
Volume concentration remains with recycled paper across European converter networks. Virgin fiber is gaining share fastest in electronics and healthcare as REACH chemical constraints tighten.
Application:
Use case determines print investment, structural engineering, and supply chain positioning relative to distribution nodes.
- Shipping:Protective containers for parcel networks and freight consolidation represent the foundational volume base. Amazon's regional fulfillment architecture and Zalando's Polish distribution hub drive specification standardization.
- Retail Display:Shelf-ready packaging with high-graphics flexographic print captures applications from folding carton. Club stores in Texas and grocery chains in Illinois demand consistent color matching across seasonal rotations.
- Storage:Bulk bins and warehouse totes for manufacturing components emphasize reusability and stack height.
- Manufacturing:Dunnage and work-in-process containers for automotive assembly lines require precise dimensional tolerance.
Deployment maturity clusters in shipping applications with established corrugator footprints. Retail display represents the steepest expansion trajectory as digital print collapses run-length economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Old corrugated container supply from the American South and Baltic Sea ports anchors converter procurement across three continents. Recycled fiber flows from these hubs determine regional cost structures and quality tiers.
United States
E-commerce parcel volumes from Amazon's Memphis fulfillment cluster and Walmart's Bentonville distribution network drive single-wall demand for lightweight consumer goods. EPA Clean Water Act effluent standards constrain mill expansion in the Southeast. Containerboard producers near Green Bay and Memphis feed corrugated sheet feeders serving Midwest automotive parts logistics.
Germany
Automotive just-in-time assembly lines from Stuttgart to Wolfsburg require triple-wall dunnage rated above 1,000 kilonewtons per meter for heavy component transit. EU Green Deal recycled-content mandates escalate minimum post-consumer fiber thresholds annually. The industrial packaging corridor between Bavaria and Baden-Württemberg concentrates high-performance converter capacity for machinery exports.
China
Electronics fulfillment from Shenzhen to Austin demands virgin kraft linerboard with low-lint cleanliness certification. MEE environmental standards and dual carbon goals restrict coal-fired steam generation at corrugating plants. Pearl River Delta converters serve cross-border e-commerce merchants with lightweight single-wall configurations for parcel sorting systems.
Japan
Semiconductor and precision equipment shippers specify ionic-contamination-controlled packaging from Oji Holdings and Rengo mill networks. METI circular economy guidelines promote closed-loop fiber recovery from metropolitan collection systems. Kanto region converters cluster near Tokyo-Yokohama distribution hubs for electronics fulfillment to Southeast Asia.
Poland
Corrugated consumption per capita remains below Western European averages, creating expansion space for regional mill-converter integration. EU Green Deal packaging regulations apply fully from 2025, redirecting procurement toward de-inking investments. Warsaw and Łódź logistics corridors attract feeder plant construction to serve Central European distribution networks.
Corrugated Board Market Key Industry Players
Global majors compete with regional champions across fiber sourcing and converting footprint dimensions. The market structure concentrates around integrated producers with captive pulp supply and independent sheet feeders dependent on merchant market fiber. Three archetypes dominate: vertically integrated North American giants, European recycled-fiber specialists, and Asia-Pacific diversified paper conglomerates. Competitive moves center on mill capacity expansion near demand clusters and backward integration into OCC collection infrastructure.
Among integrated North American producers, International Paper and WestRock exemplify the scale-driven archetype with pulp-to-box plant control. Smurfit Kappa anchors the European recycled-fiber specialist tier with pan-regional converting coverage. These three represent distinct strategic positions: captive virgin fiber integration, recycled network density, and specialty coated grades for retail channels respectively.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Kappa |
| WestRock |
| Mondi Group |
| DS Smith |
| Packaging Corporation of America |
| Rengo Co., Ltd. |
| Oji Holdings Corporation |
| Cascades Inc. |
| Others |
Cost & Logistics Intelligence
EU Green Deal recycled-content mandates gate qualified supply and premium-tier pricing access, forcing converters to absorb de-inking investments that bifurcate the market between certified virgin kraft suppliers and reformulated recycled-grade producers. This regulatory threshold concentrates pricing power among integrated mills with captive fiber recovery networks while squeezing independent sheet feeders dependent on merchant OCC markets.
Pricing Analysis
Service bundling separates integrated producers offering technical support and flute calibration from commodity converters selling unbundled board tonnage. Three-tier pricing structure across premium, standard, and economy levels tracks fiber origin and certification grade, with virgin kraft from Scandinavian softwood commanding substantial premiums over post-consumer recycled grades. Pricing pressure stems from OCC export demand spikes to Asian packaging producers, which compress margins for North American and European converters lacking long-term fiber offtake agreements. Small regional sheet feeders exhibit highest price sensitivity due to working capital constraints and limited procurement scale, while automotive OEMs prioritize compression strength specifications over unit cost.
Supply Chain Analysis
Old corrugated container collection flows from metropolitan recovery systems back to de-inking facilities, creating reverse-logistics infrastructure that determines regional feedstock quality and availability. Supply concentrates in the United States, Germany, and China, with Baltic Sea and American South ports anchoring global fiber trade routes. Raw material dependencies center on post-consumer OCC streams, virgin kraft pulp from southern pine forests, and wet-strength resin formulations compliant with REACH chemical constraints. Single-source vulnerability sits with Smurfit Kappa's pan-European recycled fiber network, which creates dependency risk for independent converters in secondary markets. Distribution runs through regional corrugator clusters positioned within 50 miles of major e-commerce fulfillment hubs to eliminate freight deadheading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal recycled-content thresholds and FDA 21 CFR food-contact certification create substantial barrier-to-entry moats for compliant integrated producers.
For Market Incumbents: Anchor defensive positioning through backward integration into OCC collection infrastructure in Poland and Romania, capturing Green Deal-mandated fiber flows before competitors secure feedstock. Prioritize certification investment for triple-wall automotive dunnage rated above 1,000 kilonewtons per meter, as Stuttgart-to-Wolfsburg assembly lines demand traceable supply chains. Plastic crate substitution in closed-loop automotive logistics threatens volume growth; counter by emphasizing one-way corrugated flexibility for route-variable shipments.
For New Entrants and Emerging Players: Regional distributors in Central and Eastern Europe represent the most penetrable channel partner type, offering immediate access to underpenetrated consumption per capita markets without mill-scale capital requirements. Target white-space opportunities in Poland's Warsaw and Łódź logistics corridors, where EU packaging regulations apply fully from 2025 and de-inking capacity lags demand. Pursue go-to-market positioning as specialty digital-print converters serving apparel and electronics merchants with run lengths below 5,000 units, bypassing plate inventory overhead that constrains incumbent flexibility.
For Investors and Strategic Acquirers: Announcement of extended producer responsibility fee structures in France, Italy, and Spain is the leading indicator that integrated producers with captive fiber recovery will capture structural margin expansion over merchant-market-dependent competitors. Over the medium-term horizon, acquisition focus should center on mid-cap converters with established automotive certification and regional de-inking assets in EU member states with escalating recycled-content mandates. Monitor OCC price volatility spikes as the critical inflection signal for margin compression risk among non-integrated sheet feeders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captures Green Deal-mandated fiber flows in Poland and Romania before competitor lock-in. |
| Digital Print Capability Investment | Enables sub-5,000 unit runs for Zalando and Amazon merchants without plate inventory overhead. |
| Triple-Wall Automotive Certification | Qualifies supply for Stuttgart-Wolfsburg assembly lines demanding 1,000+ kilonewton compression ratings. |
| De-Inking Capacity Expansion | Secures compliant pulp supply as REACH constraints tighten on wet-strength resin formulations. |
| Regional Feeder Plant Construction | Positions corrugator capacity within 50 miles of Memphis and Bentonville fulfillment clusters. |
Research Approach
Independent corroboration across mill operations data, customs trade flows, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with corrugator plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at linerboard mills combined with secondary validation from EPA effluent filings, EU Green Deal implementation reports, SEC 10-K disclosures, and OCC price index publications. Bottom-up fiber consumption modeling and top-down packaging demand triangulation anchored volume estimates across the analysis window.
Comparable-period anchoring to historical containerboard production cycles and e-commerce parcel growth trajectories structured the forecast framework. Segmentation dimensions modeled include wall configuration tier, end-use contamination sensitivity, fiber sourcing strategy, and regional regulatory cluster. CAGRs derived from trend-line extrapolation of corrugator line speed investments and recycled-content mandate phase-in schedules, with specific inputs from automotive parts logistics intensity and digital print adoption curves in apparel fulfillment.
Caveats apply where old corrugated container export demand volatility, extended producer responsibility scheme implementation delays, or steam-heated corrugating roll maintenance skill shortages could materially shift the outlook. Forecasts reflect documented assumptions about fiber recovery rates and regulatory enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market