
 Letterpress Card Market | 2026-2036
Letterpress Card Market Size, Share, and Industry Trends Forecast 2026-2036
Letterpress Card Market Foresight
Luxury wedding planners and boutique stationery retailers is redrawing the letterpress card demand map away from mass-market greeting card buyers. Crane and Co. leverages its heritage cotton paper supply chain to command premium positioning in North American bridal stationery. Ernst Reiner GmbH & Co. KG anchors European precision equipment supply for artisan printers seeking mechanized consistency. Ladyfingers Letterpress specializes in hand-fed production for custom wedding suites, occupying a defensible niche against volume competitors.
Letterpress cards are thick-stock correspondence pieces produced by relief printing, where a raised plate is inked and pressed into paper to create a debossed impression with tactile depth; cotton paper at 300-600 gsm remains the preferred substrate for its fiber length and impression retention. Wedding invitations within the usage occasion dimension carry the highest unit margins and sustain the longest design-to-fulfillment cycles. Cotton paper dominates the material dimension for premium commissions, while recycled paper variants are gaining fastest among corporate event buyers seeking ESG-aligned procurement. Custom artwork within design complexity commands price premiums that standard minimalist templates cannot match.
FDA guidelines for consumer product labeling and EPA standards for printing ink volatile organic compounds shape material and process choices for US-based producers. EU REACH compliance on chemical substances in inks and the F-Gas Regulation on industrial refrigeration for climate-controlled paper storage affect cross-border supply configurations. Stakeholders must monitor evolving extended producer responsibility frameworks for paper packaging waste and decide whether to absorb compliance costs or pass them through to price-sensitive segments.
Market Dynamics
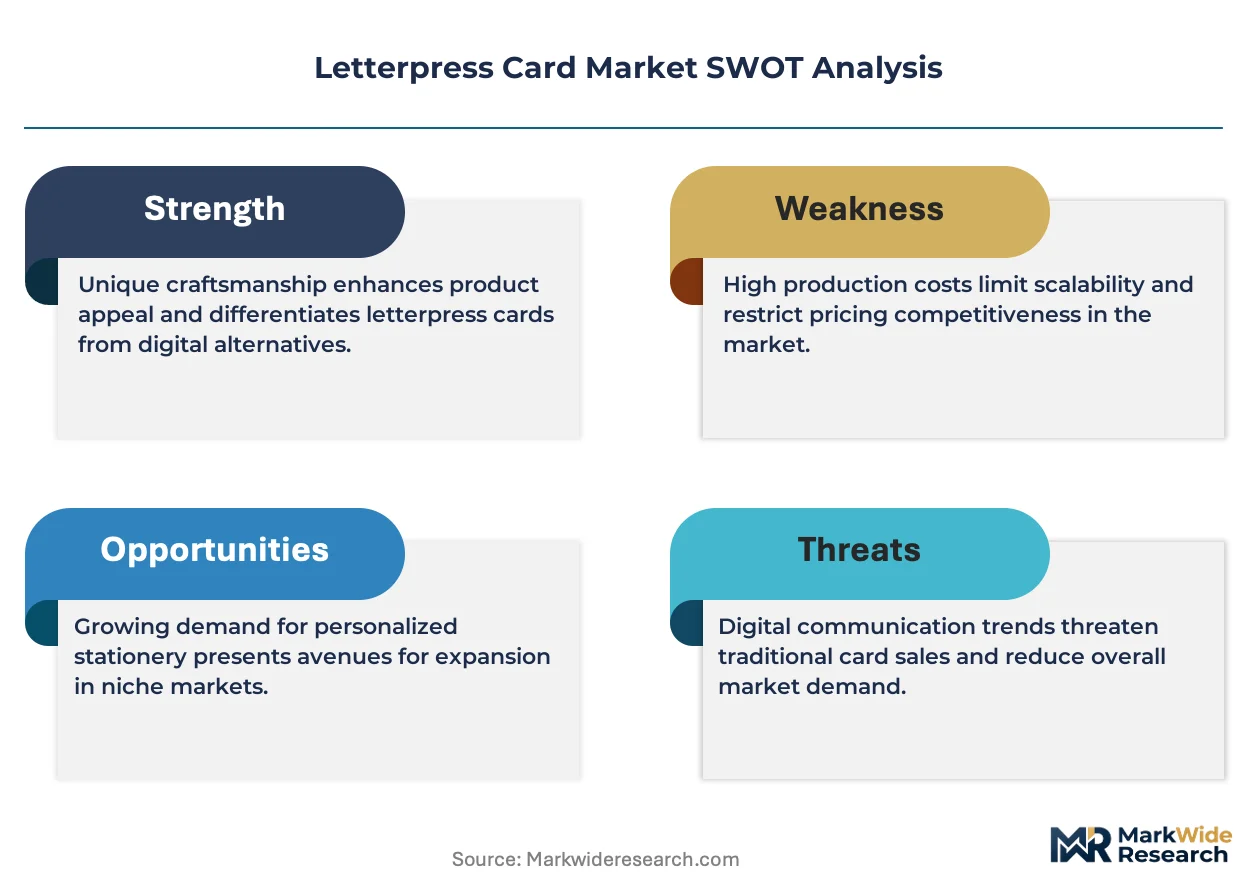
Artisan printing houses face intensifying pressure from EU REACH compliance on chemical substances in inks and F-Gas Regulation requirements for climate-controlled paper storage, forcing capital reallocation toward compliant material lines and refrigerated warehousing infrastructure.
Growth Catalysts
- Heritage cotton paper supply chains:Premium bridal stationery buyers prioritize fiber length and impression retention in 300-600 gsm cotton substrates, sustaining long design-to-fulfillment cycles with elevated unit margins.
- Extended producer responsibility frameworks:EU packaging waste directives channel investment toward recycled paper variants among corporate event buyers seeking ESG-aligned procurement credentials.
- Independent design studio proliferation:United States-based boutique retailers anchor premium segment volume through tactile, artisan-printed correspondence preferences displacing digital alternatives.
Market Restraints
- Cotton fiber input cost volatility:Rising consumer preference for cotton substrates concentrates supplier power with heritage paper mills, compressing margin flexibility for mid-tier printers.
- Mechanized precision equipment concentration:European equipment suppliers control artisan printer access to mechanized consistency, creating geographic dependency in production tooling.
- Digital correspondence substitution:Electronic invitation platforms capture price-sensitive mass-market segments, constraining volume scale for non-premium letterpress producers.
Strategic Opportunities
- Underpenetrated corporate event verticals:Fortune 500 sustainability procurement mandates create white space for ESG-certified recycled paper letterpress suites in executive correspondence.
- Direct-to-consumer channel innovation:Bespoke online configurators bypass boutique retailer markups, capturing margin from design-forward millennial buyers in metropolitan clusters.
- Regulatory tailwind from EU Green Deal:Circular economy action plan incentives reward domestic paper sourcing and closed-loop ink recovery systems with preferential certification status.
Industry Challenges
- Master printer skill scarcity:Hand-fed production expertise for custom wedding suites requires multi-year apprenticeship pipelines that vocational programs no longer reliably supply.
- Legacy equipment capex intensity:Climate-controlled warehousing and VOC-compliant ink formulation systems demand seven-figure infrastructure investments beyond independent studio balance sheet capacity.
- REACH pre-registration timelines:Chemical substance compliance documentation for cross-border ink shipments creates 18-24 month market entry delays for non-EU material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Letterpress Card Market |
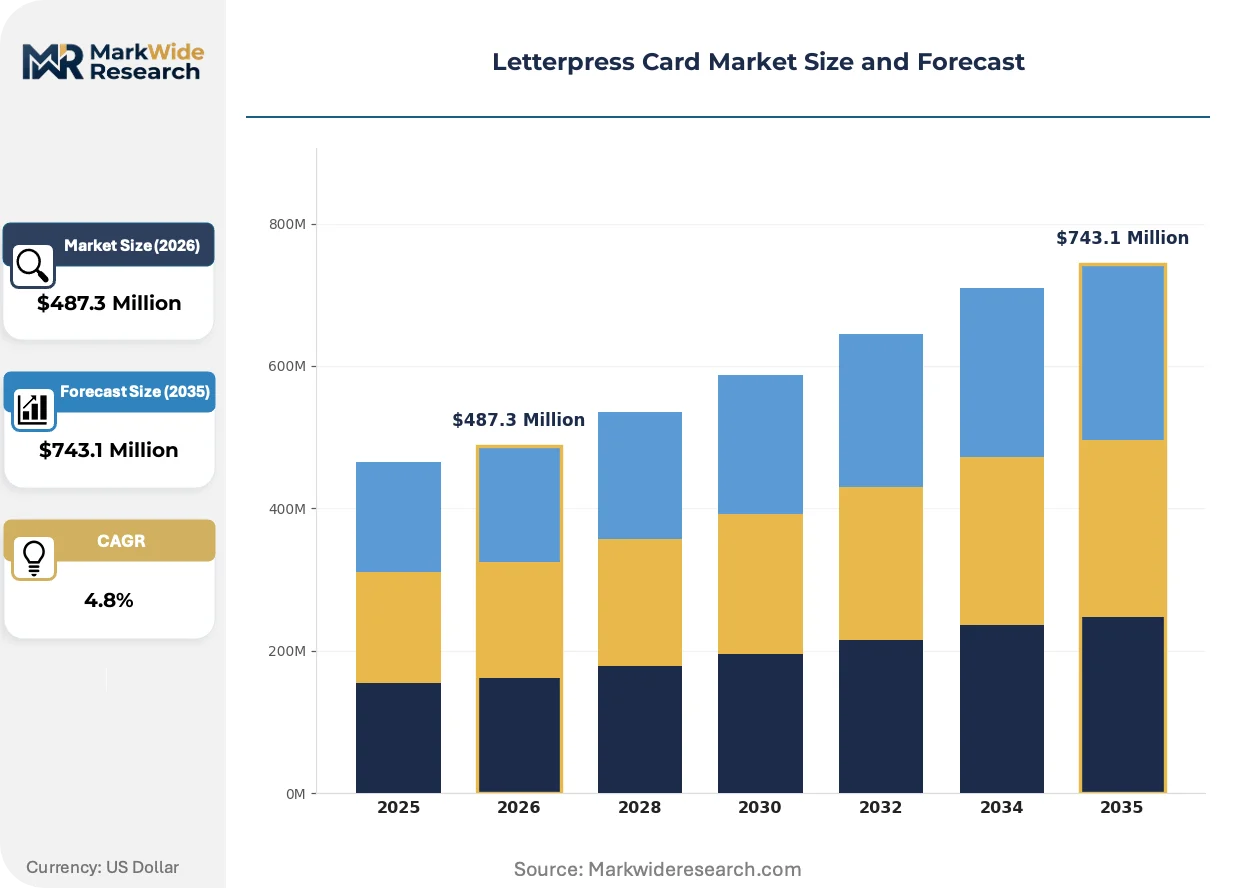
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Postcards, Invitations, Greeting Cards, Art Prints Material: Cotton Paper, Recycled Paper, Cardstock, Handmade Paper Design Complexity: Minimalist, Vintage, Modern, Custom Artwork Usage Occasion: Weddings, Birthdays, Holidays, Corporate Events |
| Companies Covered | Dempsey and Carroll, Eidos S.p.A., Crane and Co., HANWHA Machinery, Ernst Reiner GmbH & Co. KG, Vistaprint, Ladyfingers Letterpress, Labelmen Machinery Co., Ltd., The Wren Press, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Letterpress Card Market Shifts & Advancements
Photopolymer plate technology is compressing production timelines for custom wedding suites while regulatory chemical frameworks and buyer procurement preferences simultaneously reshape material sourcing and distribution pathways.
Photopolymer plate systems enable digital file-to-plate workflows that is supplanting traditional magnesium and copper plate engraving for short-run custom commissions. Boutique bridal stationery studios adopt these systems within 12-18 month replacement cycles. The technology compresses design-to-fulfillment timelines from six weeks to ten days, enabling just-in-time production models previously incompatible with letterpress economics.
EU F-Gas Regulation mandates on industrial refrigeration gases are forcing climate-controlled paper storage facility upgrades across German and French printing clusters. The regulation's phase-down schedule for hydrofluorocarbons triggers capital expenditure decisions on warehouse retrofitting versus relocation. Premium cotton paper suppliers with existing cold-chain infrastructure capture volume from competitors facing 24-month compliance timelines.
Corporate procurement departments now require ESG documentation for event stationery spend above threshold levels, displacing traditional price-per-piece vendor selection. Sustainability certification from recognized frameworks determines shortlist inclusion for Fortune 500 event contracts. This behavioral shift concentrates most visibly in United States technology and financial services verticals with published net-zero procurement mandates.
Letterpress Card Market Segmentation
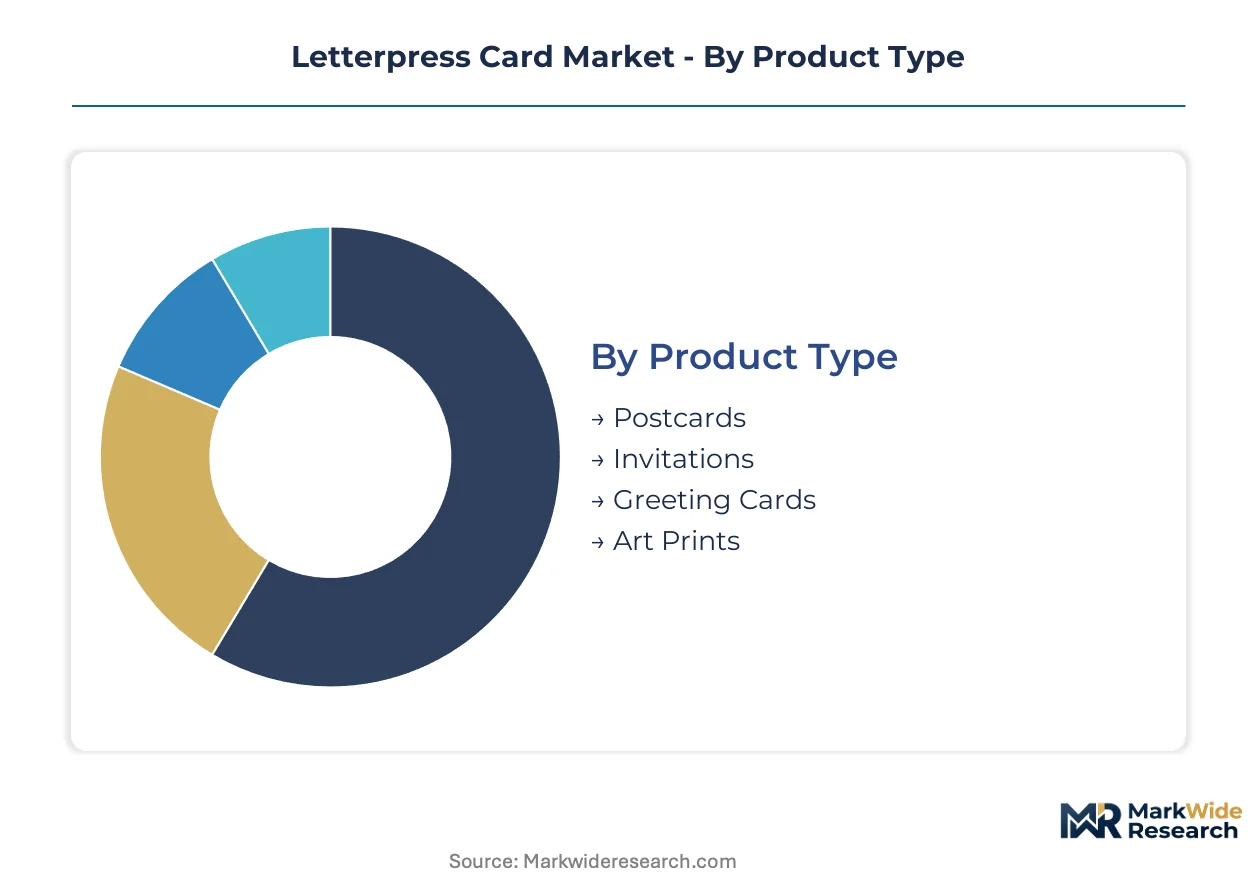
Letterpress card procurement patterns diverge sharply across product formats, material grades, and occasion-based specifications. Understanding these fault lines reveals where premium margin pools concentrate versus where volume scale remains achievable.
Product Type:
Domestic demand in the United States concentrates on wedding-adjacent formats, while export-led growth channels through art print and postcard categories bound for European gallery retail.
- Invitations:Wedding suites dominate this segment with 300-600 gsm cotton substrates and six-week design-to-fulfillment cycles. United States bridal stationery studios in New York and California sustain the highest unit margins through heritage cotton paper procurement from domestic mills.
- Greeting Cards:Boutique retailers stock seasonal assortments with shorter production runs and lower per-piece margins than wedding commissions. Demand clusters in metropolitan gift districts where tactile differentiation commands shelf space against digital alternatives.
- Postcards:Tourism-dependent retail channels in Paris, Rome, and Barcelona absorb volume for destination-branded correspondence.
- Art Prints:Limited-edition gallery releases leverage debossed impression depth as a collectible authentication marker.
Invitations command the established base. The steepest expansion runs through art prints.
Material:
Cost tier stratification separates heritage cotton substrates from recycled variants, with mid-grade cardstock occupying price-sensitive corporate procurement.
- Cotton Paper:Fiber length and impression retention at 300-600 gsm weights make this the preferred substrate for premium bridal commissions. United States heritage mills control supply chains, concentrating supplier power and compressing flexibility for mid-tier printers.
- Recycled Paper:ESG-aligned procurement mandates from Fortune 500 corporate event buyers are accelerating adoption. EU packaging waste directives channel investment toward certified recycled variants with documented chain-of-custody.
- Cardstock:Volume applications in mass-market greeting cards rely on wood-pulp-based substrates with lower per-unit material costs.
- Handmade Paper:Nepalese and Indian craft cooperatives supply fiber inclusions and deckled edges for ultra-premium custom suites.
Cotton paper anchors premium positioning. Recycled paper is climbing the fastest on corporate sustainability mandates.
Design Complexity:
Customer type divides this category: institutional buyers favor templated approaches while individual commission clients invest in bespoke artwork.
- Custom Artwork:Original illustration and monogram development command price premiums that template-based competitors cannot match. Independent design studios in Brooklyn, Austin, and Portland capture margin through direct-to-consumer configurators.
- Vintage:Ornate border reproductions and period typography attract heritage-conscious bridal demographics seeking aesthetic continuity with family archival materials.
- Minimalist:Clean line work and generous negative space reduce plate preparation costs while maintaining tactile impression impact.
- Modern:Geometric patterns and sans-serif typography appeal to design-forward millennial buyers in metropolitan clusters.
Custom artwork captures the highest margin pool. Modern styling is gaining share fastest among first-time letterpress purchasers.
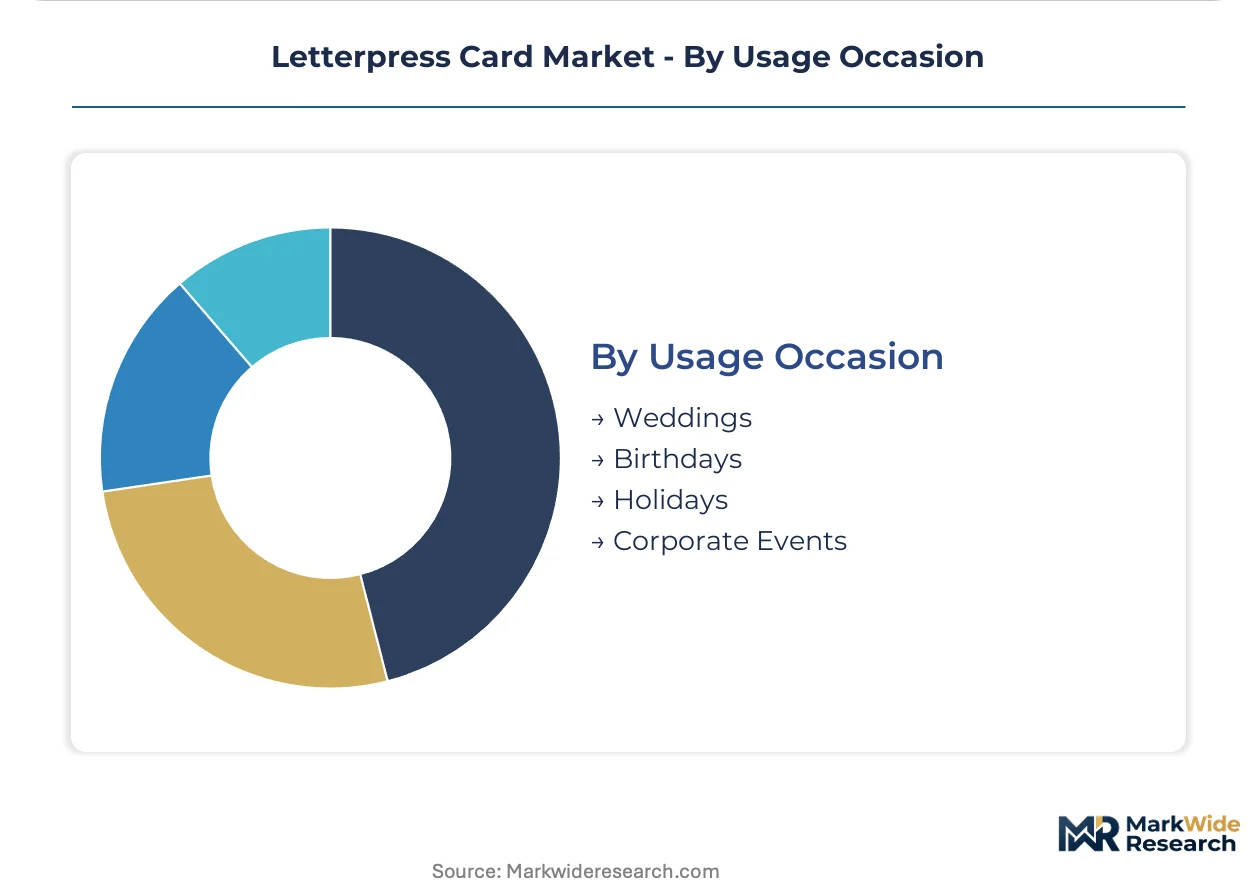
Usage Occasion:
Volume scale concentrates in recurring annual events, while one-life-cycle occasions sustain premium pricing power.
- Weddings:Multi-piece suites with save-the-date, invitation, RSVP, and enclosure cards generate the longest production cycles and highest customer lifetime value. United States independent studios anchor this segment through tactile correspondence preferences displacing electronic platforms.
- Corporate Events:Executive correspondence and board meeting materials now require ESG documentation above threshold spend levels. Sustainability certification determines shortlist inclusion for technology and financial services verticals with published net-zero mandates.
- Birthdays:Milestone celebrations drive periodic demand for personalized age-specific messaging.
- Holidays:Seasonal production peaks strain capacity at letterpress houses with limited press availability.
Weddings retain the revenue concentration. Corporate events are expanding most quickly on procurement policy transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridal stationery studios and heritage printing houses anchor demand concentration across distinct geographic clusters, with cotton paper procurement patterns and regulatory frameworks diverging sharply between North American and European production centers.
United States
Independent design studios in Brooklyn, Austin, and Portland drive premium wedding suite commissions through direct-to-consumer channels. EPA standards for printing ink volatile organic compounds shape material selection for domestic producers. New York and California anchor the highest unit margin concentration, with heritage cotton paper mills supplying 300-600 gsm substrates to bridal stationery houses.
Germany
Precision equipment manufacturing for artisan printers concentrates supplier power in Baden-Württemberg and Bavaria. EU F-Gas Regulation mandates on industrial refrigeration gases force climate-controlled paper storage facility upgrades across German printing clusters. Frankfurt and Munich printing houses capture volume from competitors facing 24-month compliance timelines for warehouse retrofitting.
United Kingdom
Heritage correspondence retailers in London and Edinburgh sustain demand for ornate border reproductions and period typography. Extended producer responsibility frameworks for paper packaging waste channel investment toward certified recycled variants. The Wren Press and boutique retailers in metropolitan gift districts command shelf space through tactile differentiation.
France
Tourism-dependent retail channels in Paris absorb volume for destination-branded postcards and gallery-bound art prints. REACH compliance on chemical substances in inks creates 18-24 month market entry delays for non-EU material suppliers. Lyon and Marseille printing clusters specialize in limited-edition debossed impression releases for collectible authentication.
Italy
Luxury wedding planners in Milan and Rome expand letterpress procurement as artisan-printed correspondence gains preference over digital alternatives. EU Green Deal circular economy action plan incentives reward domestic paper sourcing with preferential certification status. Florentine design studios occupy defensible niches against volume competitors through hand-fed production expertise.
Letterpress Card Market Competitive Landscape
Player mix skews toward heritage paper mills and precision equipment fabricators, with independent design studios occupying fragmented premium niches. Equipment suppliers control mechanized consistency access, creating geographic dependency in production tooling. Three archetypes dominate: cotton substrate specialists, photopolymer plate technology providers, and bespoke bridal commission houses. Competitive moves concentrate on direct-to-consumer channel innovation and ESG-certified material line expansion.
Among heritage cotton paper specialists, Crane and Co. exemplifies premium substrate supply chain anchoring, while Ernst Reiner GmbH & Co. KG represents European precision equipment concentration for artisan printer tooling. Ladyfingers Letterpress occupies the hand-fed production specialist tier, demonstrating defensible niche positioning against mechanized volume competitors.
| Leading Market Players |
|---|
| Dempsey and Carroll |
| Eidos S.p.A. |
| Crane and Co. |
| HANWHA Machinery |
| Ernst Reiner GmbH & Co. KG |
| Vistaprint |
| Ladyfingers Letterpress |
| Labelmen Machinery Co., Ltd. |
| The Wren Press |
| Others |
Supply & Pricing Matrix
Capacity utilization at heritage cotton paper mills in the United States and France shapes both supply concentration and price floors across premium bridal stationery tiers. These scale economies concentrate supplier power with Crane and Co. and European fiber specialists, compressing margin flexibility for mid-tier printers while sustaining elevated entry barriers for artisan competitors.
Pricing Analysis
Cost-plus contracts with cotton fiber indexation dominate procurement between heritage paper mills and bridal stationery houses. Three-tier pricing structure across premium, standard, and economy levels separates custom artwork commissions from template-based minimalist designs and mass-market cardstock alternatives. Price differentiation rests on fiber grade certification and impression depth quality, with cotton substrate premiums widening against recycled variants. Pricing pressure stems from REACH compliance documentation costs for cross-border ink shipments, compressing margins for non-EU material suppliers. Corporate event buyers exhibit lowest price sensitivity due to ESG procurement mandates, while greeting card retailers face acute cost compression from digital substitution.
Supply Chain Analysis
The United States and France anchor cotton paper milling, while Germany and Japan concentrate precision letterpress equipment fabrication. Raw material dependencies draw from Egyptian long-staple cotton, photopolymer resin formulations, and VOC-compliant ink pigment systems. Single-source vulnerability concentrates at Ernst Reiner GmbH & Co. KG for mechanized consistency tooling, creating geographic dependency in production equipment. Distribution runs through boutique stationery retailers in metropolitan clusters, direct-to-consumer configurators, and gallery retail channels for limited-edition art prints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Letterpress card demand sits in early-cycle expansion as tactile correspondence displaces electronic platforms among millennial bridal demographics and Fortune 500 sustainability procurement mandates. Artisan printing houses and heritage cotton mills capture disproportionate value from this adoption tailwind.
For Market Incumbents: Compound defensive positioning through backward integration into cotton fiber supply chains and climate-controlled warehousing infrastructure. Digital invitation platforms threaten mass-market volume tiers, necessitating premium segment concentration. Certification investment in EU REACH-compliant ink formulation systems secures cross-border market access against 18-24 month compliance delays facing non-EU competitors. For New Entrants and Emerging Players: Differentiate on ESG-certified recycled paper lines targeting corporate event procurement above threshold spend levels. Underpenetrated Fortune 500 executive correspondence verticals offer fastest path to revenue traction. Direct-to-consumer channel innovation via bespoke online configurators bypasses boutique retailer markups and captures margin from design-forward metropolitan buyers. For Investors and Strategic Acquirers: Hand-fed production specialists with multi-year apprenticeship pipelines and defensible custom wedding suite positioning represent prime acquisition targets. Long-term viability hinges on master printer skill scarcity creating durable competitive moats. Watch photopolymer plate technology adoption rates as inflection indicator for production timeline compression and just-in-time model economics.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Cotton Paper Supply Chain Integration | Crane and Co. fiber length advantages sustain premium bridal positioning against recycled variants. |
| Photopolymer Plate Technology Adoption | Digital file-to-plate workflows compress design-to-fulfillment cycles from six weeks to ten days. |
| ESG-Certified Recycled Paper Line Launch | Fortune 500 sustainability mandates create white space in corporate event procurement. |
| Direct-to-Consumer Configurator Deployment | Brooklyn and Austin studios capture margin bypassing boutique retailer markups. |
| Climate-Controlled Warehousing Infrastructure | EU F-Gas Regulation compliance creates 24-month barriers for competitors lacking cold-chain capacity. |
Research Methodology
A standing panel of master printers, bridal stationery studio owners, heritage paper mill procurement directors, and boutique retailer category buyers provided ongoing calibration against secondary validation. Primary interviews combined with customs records, EPA VOC emission filings, EU REACH registration databases, and SEC 10-K disclosures from disclosed market participants. Bottom-up volume estimates triangulated against top-down value projections across product type, material grade, and usage occasion dimensions.
Consistency checks validated volume and value outputs against external benchmarks including heritage cotton paper production disclosures and precision equipment shipment records. The analytical framework modeled product format, substrate certification tier, design complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate synthesis with industry-specific inputs including photopolymer plate replacement cycle timing and EU extended producer responsibility framework implementation schedules.
Material uncertainties — cotton fiber input cost volatility, REACH pre-registration timeline delays, and digital correspondence substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained tactile correspondence preference displacement of electronic alternatives. Recalibration cycles align with material shifts in EU Green Deal circular economy incentive structures and corporate procurement policy threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market