
 North America Paper Cone Market | 2026-2036
North America Paper Cone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paper Cone Market Analytics
The EPA's strengthened recycled fiber content requirements under the Comprehensive Procurement Guideline is realigning raw material sourcing economics for North American cone manufacturers. Sonoco Products Company leverages its integrated paper mill network to secure compliant kraft pulp at scale. Conitex Sonoco anchors regional supply through its Mexico-based converting footprint, while Pacific Cones competes on specialty coatings for high-speed textile winding.
Paper cones are rigid, tapered cylinders formed from laminated paperboard layers, typically measuring 3 to 6 degrees in taper angle and 150 to 300 gsm in basis weight, designed to support yarn, thread, or wire during winding, unwinding, and transport operations. Kraft paper dominates material selection due to its superior ring crush strength and moisture resistance in humid mill environments. Single cone configurations lead volume in food industry applications where fill weights are standardized, while double cone structures command premium positioning in textile operations requiring bidirectional unwinding. Direct sales channels capture the largest margin pools by bypassing distributor markups for mill-direct contracts above threshold volumes.
FDA food-contact substance regulations and OSHA workplace safety standards jointly determine permissible coatings and structural tolerances for cones entering food and manufacturing end uses. The USDA BioPreferred program creates procurement preference for virgin paper sourced from certified forestry operations, tightening supply qualification criteria for federal contractors. Stakeholders must monitor how state-level extended producer responsibility bills in California and New York reshape post-use cone recovery obligations and recycled feedstock certification requirements.
Market Dynamics
EPA recycled-content mandates are forcing North American cone manufacturers to requalify their entire kraft paper supply chains, compressing margins for converters lacking integrated pulp access while advantaging mill-direct operators with captive fiber sourcing.
Growth Catalysts
- Automated textile winding:Southeastern US mills are retrofitting production lines for precision-wound cones compatible with robotic doffing systems, driving specification upgrades across yarn handling operations.
- USDA BioPreferred procurement preference:Federal contractors must now source virgin paper from certified forestry operations, creating qualified supplier premiums for domestic cone producers with chain-of-custody documentation.
- Guadalajara industrial corridor expansion:Apparel outsourcing to Mexico's Jalisco state has spurred dedicated cone consumption for export yarn production serving North American retail replenishment cycles.
Market Restraints
- Post-consumer fiber price volatility:EPA-mandated kraft pulp with elevated recycled ratios trades at premiums fluctuating with municipal collection economics, squeezing converter margins.
- Single-source coated paper concentration:Specialty moisture-resistant substrates for humid mill environments rely on a narrow base of Great Lakes-region suppliers, creating vulnerability.
- Plastic cone substitution in food packaging:Injection-molded polypropylene alternatives capture standardized fill-weight applications where moisture resistance exceeds paper performance thresholds.
Strategic Opportunities
- Extended producer responsibility tailwinds:California and New York state bills are mandating post-use cone recovery infrastructure, positioning early compliance investments as competitive differentiators.
- Double cone bidirectional unwinding:Textile operations requiring rapid direction-change winding present premium positioning for structural configurations currently underpenetrated in North American supply.
- Mill-direct digital procurement platforms:Volume-threshold contracts above distributor bypass levels are migrating to integrated ordering systems, compressing channel friction for qualified suppliers.
Industry Challenges
- Ring crush strength certification timelines:FDA food-contact and OSHA workplace safety standards require multi-quarter validation cycles for new coating formulations, delaying product launches.
- Legacy spinning equipment integration:Automated cone handling systems must interface with mechanical winding frames dating to the 1990s, complicating retrofit specifications and field service requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paper Cone Market |
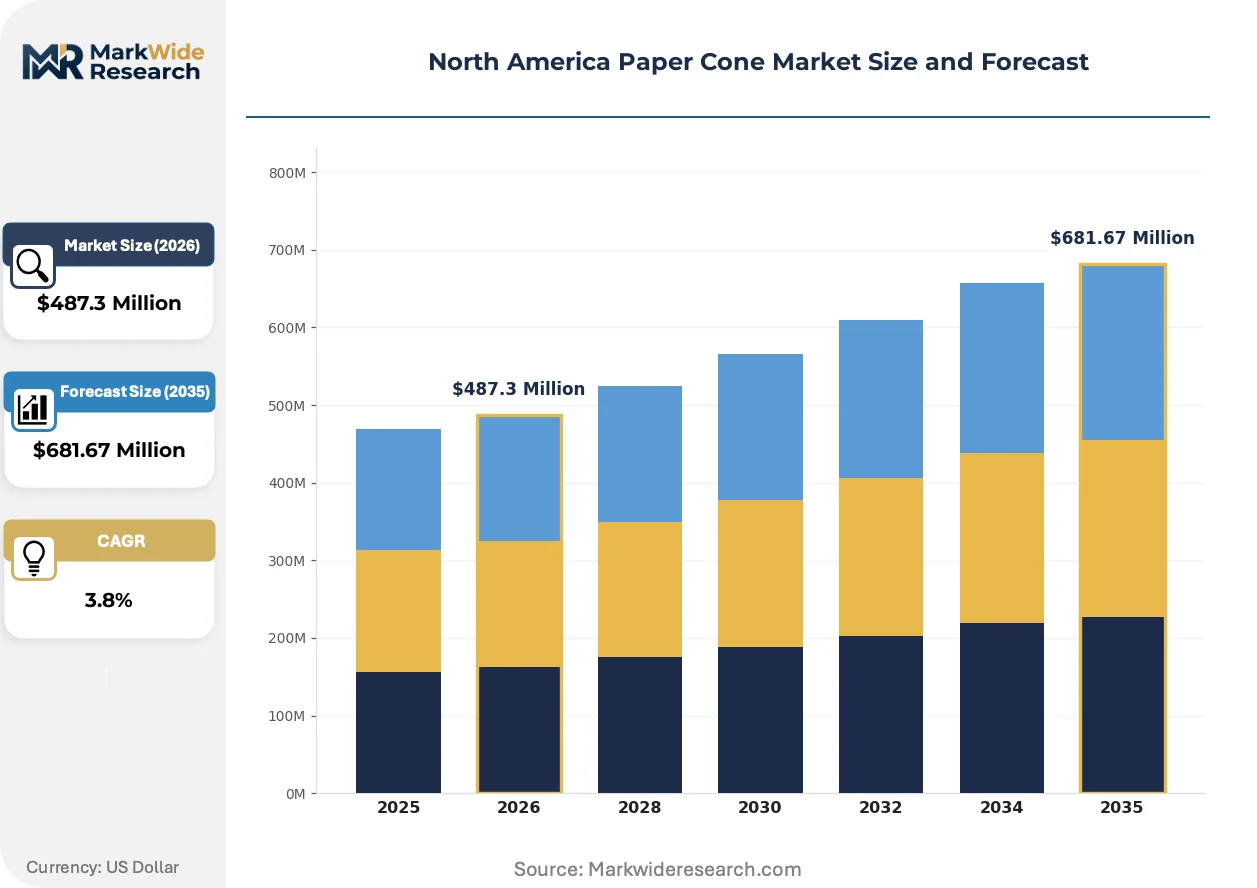
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cone, Double Cone, Cone Holder, Others Material: Recycled Paper, Virgin Paper, Kraft Paper, Others End User: Food Industry, Textile Industry, Manufacturing Sector, Chemical Industry Distribution Channel: Direct Sales, Retail, E-Commerce, Wholesale |
| Companies Covered | Conitex Sonoco, Sonoco Products Company, Pacific Cones, Tubettificio Senese, Savio Texcone Private Limited, Mandahar group of companies, JTS Group of Companies, Saroja Texcone, Royal Paper, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paper Cone Market Evolving Landscape
Digital specification platforms and automated winding compatibility requirements are compressing product development cycles while elevating precision tolerances across North American cone manufacturing.
Precision-wound cone technology is modularizing quality control into discrete, replaceable subsystems. High-speed textile mills in the Carolinas are adopting these configurations to minimize downtime during taper-angle recalibration. The approach is compressing maintenance windows from hours to minutes, enabling continuous-operation contracts that were previously uneconomical.
OSHA workplace safety standards for fiber dust exposure are tightening permissible coating volatile organic compound thresholds. Manufacturers serving food-contact applications face reformulation mandates affecting structural adhesives and surface treatments. California-based converters are absorbing the highest compliance costs, accelerating qualification of water-based alternatives ahead of federal harmonization.
Buyer consolidation among multinational yarn producers is compressing switching cycles and unbundling after-sales service from hardware supply. Direct procurement teams at southeastern US textile headquarters are displacing regional distributor relationships, demanding real-time inventory visibility and consolidated invoicing across multiple mill locations. This pattern is most visible in North Carolina's Piedmont Triad cluster.
North America Paper Cone Market Segmentation
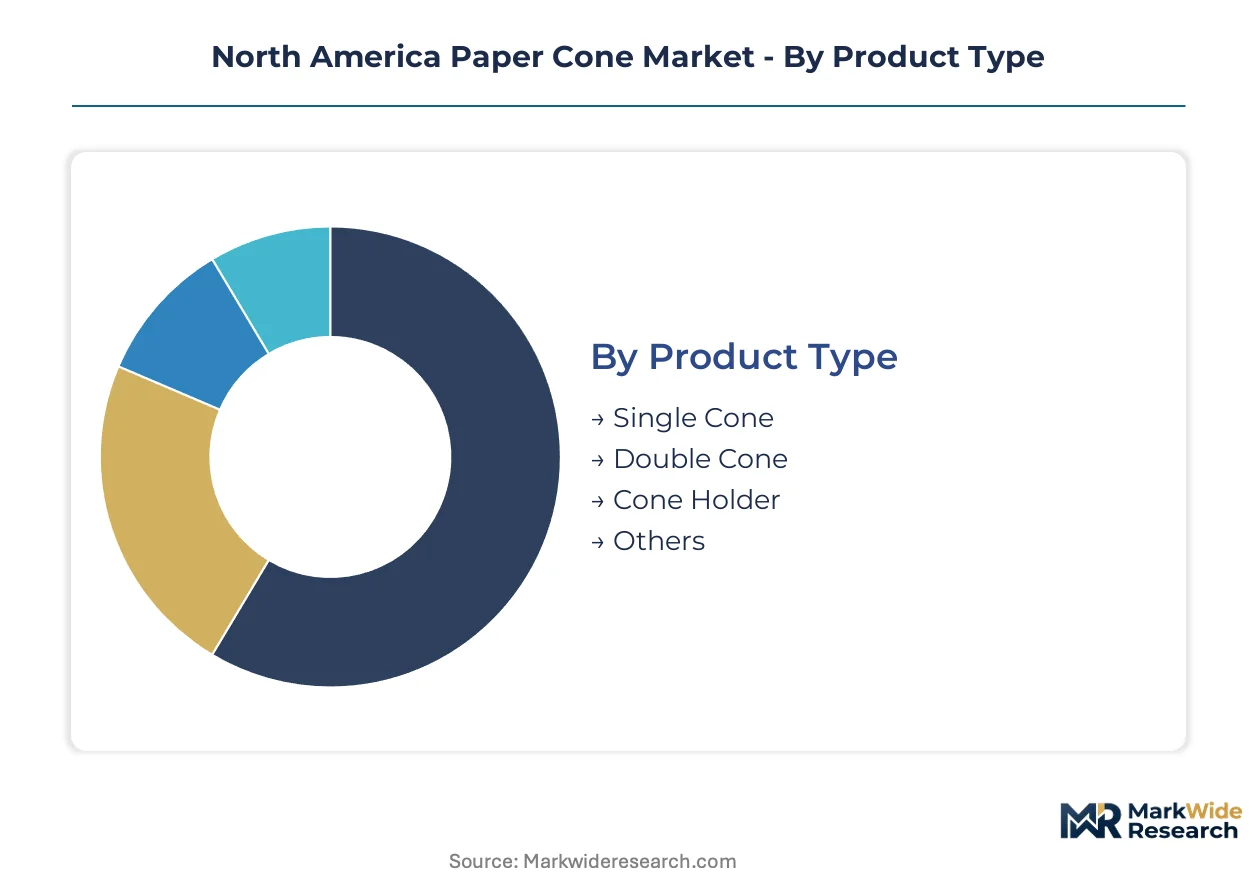
Paper cone segmentation reveals divergent margin structures across product configurations and material grades. Technical specifications from textile automation and food-contact compliance create tiered performance requirements that reshape supplier positioning across North American markets.
Product Type:
Volume leadership concentrates in standardized configurations, while premium positioning accrues to structural designs enabling bidirectional handling.
- Single Cone:Tapered cylinders with unidirectional winding capability dominate food industry fill-weight standardization. Demand clusters in southeastern US poultry processing plants where moisture-resistant coatings meet USDA BioPreferred procurement thresholds.
- Double Cone:Symmetrical tapered structures support bidirectional yarn unwinding without cone rotation. Textile mills across North Carolina's Piedmont Triad are retrofitting for these configurations to enable rapid direction-change winding on automated lines.
- Cone Holder:Auxiliary support fixtures stabilize cones during high-speed transport. Mexican apparel exporters in Guadalajara specify holders compatible with robotic doffing systems.
- Others:Specialty adapters and custom taper angles serve legacy equipment integration requirements.
Today's leader: Single Cone. Tomorrow's challenger: Double Cone.
Material:
EPA mandates are compressing margins for converters dependent on spot-market recycled fiber while rewarding integrated pulp operators.
- Kraft Paper:Virgin and semi-bleached kraft delivers superior ring crush strength for humid mill environments. Southeastern textile mills specify kraft substrates with chain-of-custody documentation to satisfy federal contractor requirements.
- Recycled Paper:Post-consumer fiber content ratios are escalating under Comprehensive Procurement Guideline enforcement. Price volatility in municipal collection markets squeezes independent converters lacking long-term supply contracts.
- Virgin Paper:Unrecycled pulp from certified forestry operations commands procurement preference for USDA BioPreferred compliance. Federal supply contracts in California and New York increasingly specify virgin content minimums.
- Others:Hybrid substrates and experimental agricultural fibers remain niche for specialty moisture-resistance applications.
Today's leader: Kraft Paper. Tomorrow's challenger: Recycled Paper.
End User:
Application-driven specification divergence separates high-volume standardized buyers from precision-tolerance premium purchasers.
- Textile Industry:Precision-wound cone requirements for automated spinning operations concentrate demand in the Carolinas and Mexico's Jalisco state. Robotic doffing compatibility is becoming a non-negotiable specification.
- Food Industry:FDA food-contact substance regulations govern coatings and structural adhesives for poultry, dairy, and dry goods packaging. Single cone standardization dominates where fill weights are predetermined.
- Manufacturing Sector:Wire winding and industrial thread applications require OSHA-compliant fiber dust exposure controls on all surface treatments.
- Chemical Industry:Specialized moisture barriers and chemical-resistant coatings serve fertilizer and agrochemical packaging with stringent EPA discharge standards.
Today's leader: Textile Industry. Tomorrow's challenger: Food Industry.
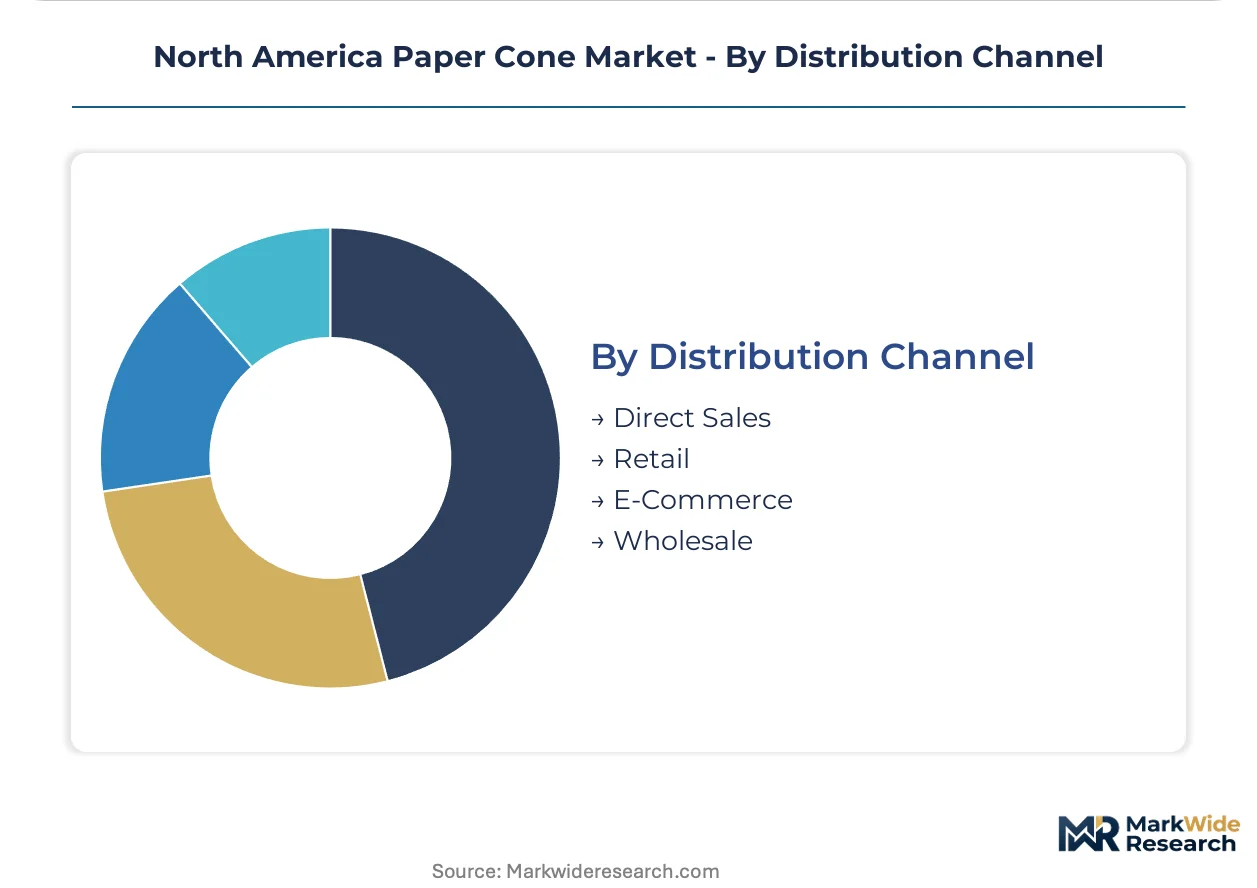
Distribution Channel:
Customer scale determines channel economics, with volume thresholds dictating distributor bypass feasibility.
- Direct Sales:Mill-direct contracts above threshold volumes capture the largest margin pools through distributor markup elimination. Multinational yarn producers in North Carolina are consolidating procurement across multiple mill locations.
- Wholesale:Regional distributors maintain inventory positions for mid-tier textile converters with irregular demand patterns.
- Retail:Small-lot availability for maintenance, repair, and operations purchasing in fragmented manufacturing.
- E-Commerce:Digital procurement platforms are emerging for standardized specifications with real-time inventory visibility.
Today's leader: Direct Sales. Tomorrow's challenger: E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American paper cone industry traces its commercial origins to early 20th-century New England textile mills, where laminated paperboard winding supports replaced wooden spools for yarn handling operations.
United States
Southeastern textile mills in the Carolinas are retrofitting production lines for precision-wound cones compatible with robotic doffing systems. EPA Comprehensive Procurement Guidelines mandate escalating post-consumer fiber ratios in federal supply contracts. North Carolina's Piedmont Triad cluster concentrates demand from multinational yarn producers consolidating procurement across multiple mill locations.
Mexico
Apparel outsourcing to Jalisco state has spurred dedicated cone consumption for export yarn production serving US retail replenishment cycles. Federal environmental standards under SEMARNAT align with US EPA recycled-content thresholds for cross-border supply chains. Guadalajara's industrial corridor hosts converting operations positioned for just-in-time delivery to maquiladora textile facilities.
Canada
Pulp and paper integration in Quebec and Ontario provinces supplies kraft substrates to North American cone manufacturers. Health Canada food-contact regulations govern coatings for poultry and dairy packaging applications. Southern Ontario manufacturing corridors serve as distribution nodes for US Midwest textile and food processing demand.
North America Paper Cone Market Competitive Landscape
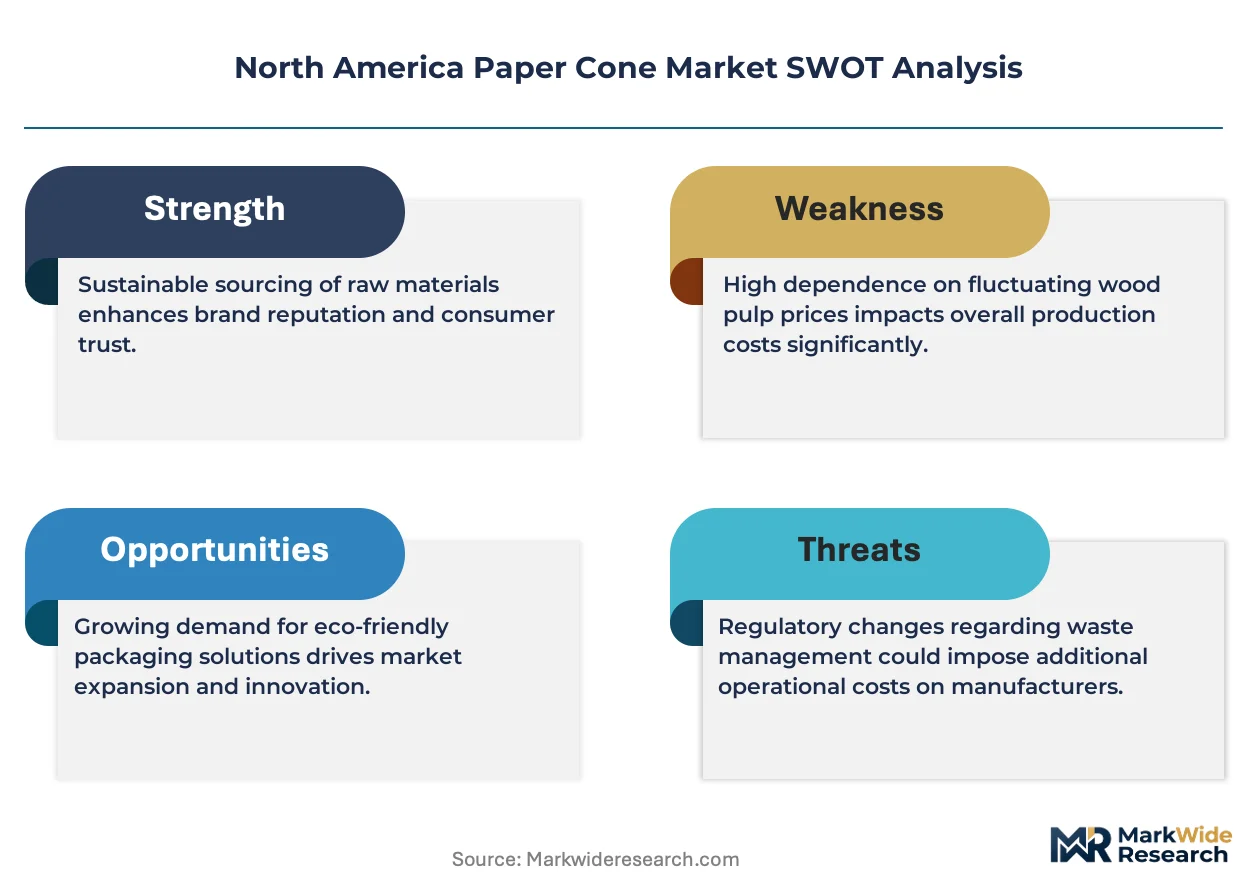
The competitive structure tilts toward integrated packaging conglomerates with captive pulp supply. Mill-direct operators with backward integration into kraft paper production capture margin advantages under EPA recycled-content mandates, while independent converters face procurement cost volatility. Three archetypes dominate: vertically integrated paperboard producers, regional specialty converters, and offshore suppliers leveraging cost-positioned fiber sourcing. Capacity rationalization and distributor bypass strategies represent the primary competitive moves reshaping channel economics.
Among integrated packaging operators, Sonoco Products Company exemplifies the captive-fiber archetype through its paper mill network. Conitex Sonoco occupies a position bridging multinational scale with regional converting footprint. Pacific Cones represents the specialty-coating tier targeting high-speed textile winding specifications.
| Leading Market Players |
|---|
| Conitex Sonoco |
| Sonoco Products Company |
| Pacific Cones |
| Tubettificio Senese |
| Savio Texcone Private Limited |
| Mandahar group of companies |
| JTS Group of Companies |
| Saroja Texcone |
| Royal Paper |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in the Great Lakes region anchor supply discipline through long-term kraft pulp contracts that buffer spot-market volatility, while their pricing power erodes against integrated competitors with captive fiber access. This ownership pattern concentrates procurement risk among independents lacking backward integration into recycled-content kraft production.
Pricing Analysis
Contract-based long-term offtake dominates mill-direct relationships above volume thresholds, with price differentiation separating USDA BioPreferred-certified virgin kraft from standard recycled-content grades. Cost compression in the recycled fiber tier intensifies because EPA-mandated post-consumer ratios trade at premiums tied to municipal collection economics. Multinational yarn producers in North Carolina exhibit lowest price sensitivity due to specification rigidity for robotic doffing compatibility, while mid-tier food processors face acute margin pressure from polypropylene substitution.
Supply Chain Analysis
Kraft pulp supply rests on integrated paperboard producers in the United States, Canadian pulp and paper operations in Quebec and Ontario, and Mexican converting facilities in Jalisco state. Raw material dependencies include post-consumer fiber streams, semi-bleached kraft substrates, and specialty moisture-resistant coatings from Great Lakes-region chemical suppliers. Single-source coated paper concentration creates vulnerability for humid mill environment specifications. Distribution runs through mill-direct contracts for volume buyers and regional wholesale networks for fragmented manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates among integrated operators capturing recycled-content premiums and specialty coating tiers, as EPA mandates and automation requirements simultaneously compress converter economics and elevate specification value.
For Market Incumbents: Anchor defensive positioning through backward integration into kraft pulp production or captive post-consumer fiber sourcing, locking in EPA compliance ahead of state-level extended producer responsibility mandates. Deepen mill-direct digital procurement platforms to bypass distributor markups and consolidate multinational yarn producer relationships across southeastern US Piedmont Triad clusters. Plastic cone substitution in food packaging represents the most acute substitution threat requiring moisture-resistant coating R&D investment. For New Entrants and Emerging Players: California and New York state extended producer responsibility bills open a window for post-use cone recovery infrastructure plays, positioning early compliance investments as competitive differentiators. Target the double cone bidirectional unwinding segment in North Carolina textile retrofits, where rapid direction-change winding specifications remain underpenetrated relative to single cone saturation. Pursue Guadalajara industrial corridor proximity for just-in-time delivery to Mexican apparel exporters serving US retail replenishment cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters lacking integrated pulp access, presenting consolidation targets for packaging conglomerates seeking EPA-compliant fiber supply. The five-to-ten year viability window favors operators with chain-of-custody documentation and robotic doffing compatibility certifications already in place. Watch for state-level extended producer responsibility implementation timelines as the signal indicating margin compression acceleration for non-compliant independents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp | Captive fiber sourcing secures EPA recycled-content compliance at stable cost structures. |
| Mill-Direct Digital Procurement Platform | Real-time inventory visibility consolidates multinational yarn producer contracts across Piedmont Triad mills. |
| Double Cone Bidirectional Configuration | Rapid direction-change winding capability captures premium positioning in automated textile retrofits. |
| Post-Use Recovery Infrastructure Investment | California and New York extended producer responsibility mandates create first-mover compliance advantage. |
| Robotic Doffing Compatibility Certification | Precision-wound cone specifications become non-negotiable for southeastern US mill automation projects. |
Research Methodology
Multiple input streams — primary interviews with paperboard plant managers, textile procurement directors, and EPA regulatory compliance officers, alongside secondary validation through SEC 10-K filings, customs and trade data, and USDA BioPreferred program documentation — were reconciled through bottom-up and top-down triangulation. Conversations with distribution channel partners and aftermarket service heads supplemented mill-direct contract analysis.
Data-stream reconciliation across product type, material grade, end-use industry, and distribution channel dimensions informed analytical framework construction throughout the forecast period. CAGRs were derived from segment-level volume and value trajectories, incorporating kraft pulp price volatility indices and textile automation adoption curves as industry-specific forecast inputs.
Revisions become necessary when EPA recycled-content mandate enforcement timelines accelerate, post-consumer fiber collection economics deteriorate, or polypropylene substitution rates in food packaging exceed baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Paper Cup Machine Market