
 Micro Flute Paper Market | 2026-2036
Micro Flute Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Flute Paper Market Analysis
The EU Packaging and Packaging Waste Regulation is repositioning micro flute specifications toward mono-material recyclability across European supply chains. Smurfit Kappa leverages integrated containerboard mills to control substrate quality from pulp to finished flute. WestRock Company anchors North American demand through its corrugated packaging network serving e-commerce fulfillment centers. DS Smith specializes in display-grade micro flute for retail-ready shelf applications.
Micro flute paper denotes corrugated board with flute heights below 1.5 millimeters, manufactured through single-facer corrugation of recycled or virgin kraft liners bonded to fluted medium. The material delivers high crush resistance and printable surface area per unit weight, serving protective cushioning and structural display functions. E-Flute and F-Flute product types capture expanding share in electronics protective packaging where dimensional precision reduces void fill requirements. Food Packaging applications command premium positioning as grease-resistant coatings and barrier laminations add functional value to lightweight substrates.
EMA and EFSA frameworks govern food-contact micro flute compliance across Europe, while EPA guidelines shape recycled content thresholds in US manufacturing. REACH chemical restrictions and GB standards in China limit certain coating chemistries, redirecting R&D toward water-based barrier technologies. Stakeholders must monitor evolving extended producer responsibility schemes that will redefine cost allocation between converters and brand owners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across corrugated supply chains as converters race to certify mono-material substrates before enforcement deadlines. This regulatory compression is reshaping capital allocation toward recyclable barrier coatings and away from multi-layer laminates.
Growth Catalysts
- E-Commerce Protective Packaging:Electronics fulfillment networks in Germany and the Netherlands are specifying E-Flute and F-Flute grades to reduce dimensional weight charges and void fill volumes.
- REACH Chemical Restrictions:ECHA's evolving substance restrictions on per- and polyfluoroalkyl substances are redirecting coating R&D toward water-based barrier chemistries for food-contact applications.
- Recycled Containerboard Integration:Paper mills with captive pulping capacity are capturing margin from virgin linerboard volatility by feeding recycled furnish into micro flute medium production.
Market Restraints
- Old Corrugated Container Price Volatility:OCC bale costs in European spot markets swing 15-40% seasonally, compressing converter margins on fixed-price annual contracts.
- Single-Facer Equipment Concentration:Narrow-web corrugator manufacturing concentrates among German and Italian machinery suppliers, creating 12-18 month order backlogs for capacity expansion.
- Plastic Protective Packaging Substitution:Polyethylene foam and air pillow systems retain cost advantage for high-cushion electronics applications above 2-meter drop-test requirements.
Strategic Opportunities
- Indian E-Commerce Fulfillment:Flipkart and Amazon India fulfillment centers are piloting micro flute dunnage to replace expanded polystyrene in appliance shipments, creating first-mover positioning for substrate suppliers.
- CSRD-Driven Packaging Disclosures:The EU Corporate Sustainability Reporting Directive is mandating scope 3 emissions transparency, advantaging micro flute with verified recycled content and forest certification.
- Digital Print Convergence:Single-pass inkjet systems are enabling run-length flexibility down to 500 units, opening short-run display packaging previously uneconomical for flexographic plate costs.
Industry Challenges
- Barrier Coating Certification Timelines:EFSA and FDA food-contact notifications for novel water-based grease barriers require 18-24 month review cycles, delaying product launches.
- Corrugator Skilled Technician Shortages:European and North American converters face retirement waves among glue kitchen operators and flute profile specialists without replacement pipeline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Flute Paper Market |
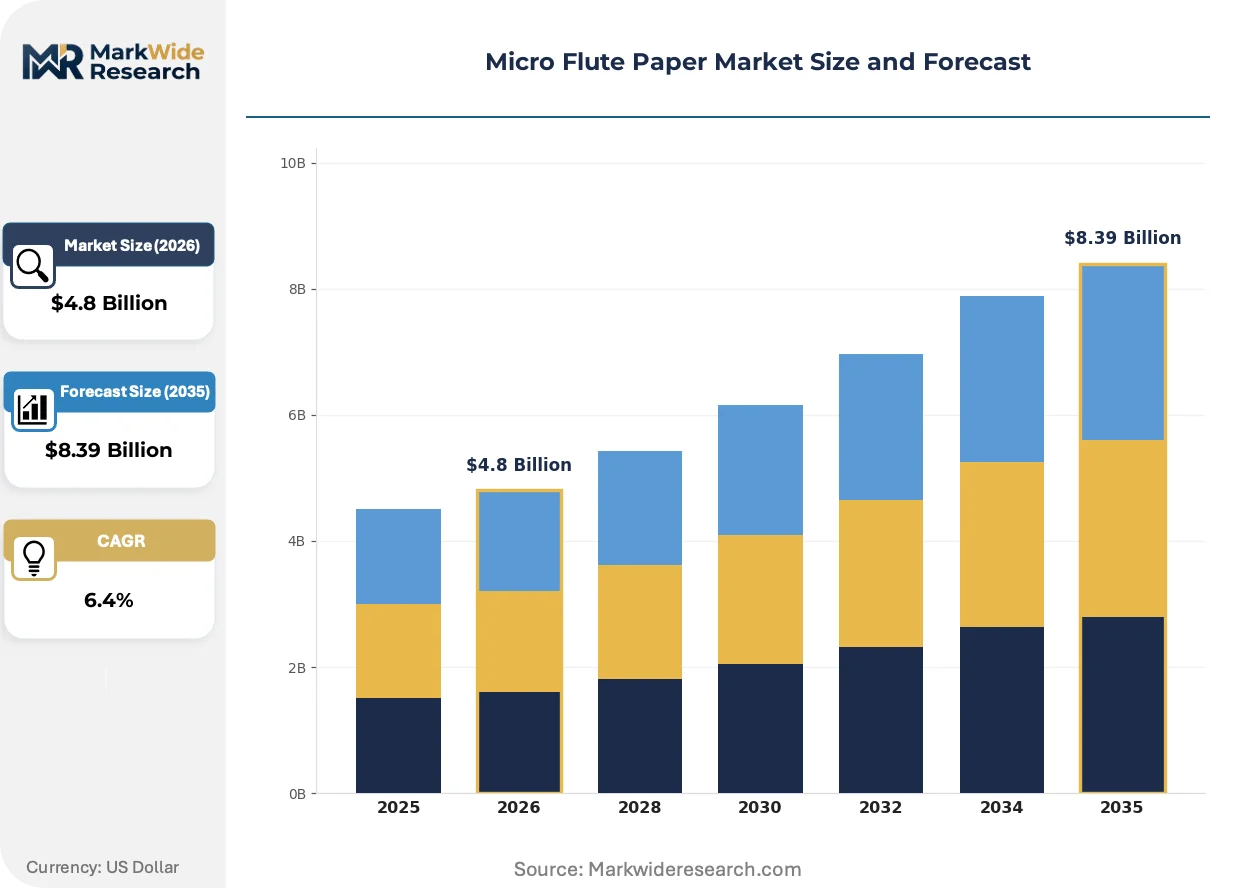
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: B-Flute, E-Flute, F-Flute, G-Flute, N-Flute Application: Protective Packaging, Retail Packaging, Display Packaging, Industrial Packaging, Food Packaging End Use Industry: Electronics, Consumer Goods, Pharmaceutical Manufacturers, Textile Producers, Automotive Suppliers Packaging Style: Rolls, Sheets, Pre-Cut Pads, Laminated Boards, Coated Layers |
| Companies Covered | Smurfit Kappa, WestRock Company, International Paper Company, DS Smith, Stora Enso, Mondi Group, Novolex Holdings, Oji Holdings Corporation, Nine Dragons Paper Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Flute Paper Market Emerging Trajectories
Digitalization of corrugated production workflows is collapsing the traditional separation between structural design, prepress, and manufacturing execution. This convergence is enabling mass customization at unit economics previously reserved for long production runs.
Nano-cellulose barrier coatings are expanding into food packaging applications where mineral oil migration resistance and grease protection must combine with repulpability. European dairy and chilled ready-meal brands are piloting these substrates for modified-atmosphere trays. The technology is expanding into premium positioning where conventional polyethylene extrusion would contaminate paper recycling streams.
REACH Annex XVII restrictions on perfluorinated chemicals are forcing reformulation of legacy grease-resistant treatments for bakery and fast-food packaging. German coating specialists are commercializing bio-based alternatives using plant-derived waxes and polysaccharide complexes. Food service distributors in France and Belgium are accelerating qualification timelines to secure supply ahead of 2025 enforcement windows.
Direct-to-retail procurement models are compressing traditional distributor layers in European corrugated supply chains. Major grocery retailers in the UK and Nordic markets are contracting directly with integrated paper and packaging producers for private-label display packaging. This disintermediation is visible most acutely in fresh produce categories where weekly promotional cycles demand 48-hour turnaround from artwork approval to shelf delivery.
Micro Flute Paper Market Segmentation
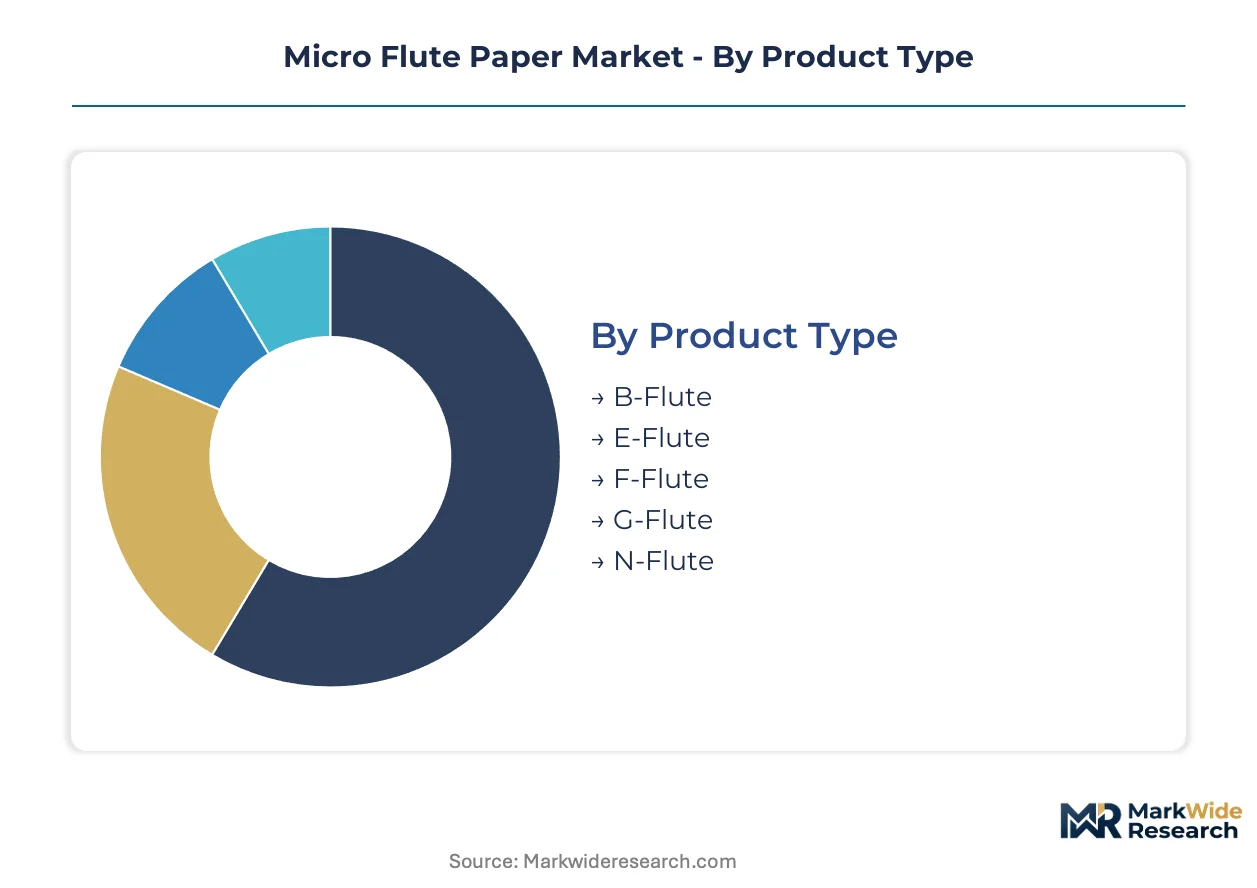
Micro flute paper segmentation reflects divergent technical specifications across protective cushioning, retail presentation, and food-contact applications. Each category carries distinct margin profiles and regulatory compliance burdens that reshape converter capital allocation.
Product Type:
Integration depth varies sharply — E-Flute and F-Flute dominate embedded protective systems, while B-Flute serves standalone structural applications.
- B-Flute:Flute height of 2.5-3.0 millimeters delivers superior stacking strength for palletized industrial shipments. German automotive suppliers specify this grade for returnable component containers where compression resistance exceeds printability requirements.
- E-Flute:1.0-1.5 millimeter flute profile balances crush protection with surface smoothness for litho-laminated retail boxes. Netherlands-based electronics fulfillment networks are converting void-fill programs to E-Flute dunnage to reduce dimensional weight charges.
- F-Flute:Sub-1.0 millimeter construction enables high-resolution flexographic and digital print reproduction on lightweight substrates.
- G-Flute:Ultra-fine corrugation below 0.9 millimeters targets premium cosmetic and pharmaceutical folding carton substitution.
- N-Flute:Minimal flute height of 0.4-0.5 millimeters approaches solid fiberboard characteristics for micro-scale protective applications.
E-Flute leads volumes today; F-Flute is gaining share fastest.
Application:
Cost tier stratification separates commodity protective uses from value-added display and food-contact segments.
- Protective Packaging:Cushioning and blocking functions for fragile goods in transit. Electronics manufacturers in Germany specify precision-cut E-Flute inserts to replace expanded polystyrene in laptop and smartphone shipments.
- Retail Packaging:Shelf-ready cartons and secondary packaging for consumer goods. UK grocery retailers are piloting micro flute substitution for solid bleached sulphate folding cartons in private-label dry goods.
- Display Packaging:Point-of-sale structures with high print fidelity and die-cut complexity.
- Industrial Packaging:Bulk containment and dunnage for manufacturing supply chains.
- Food Packaging:Grease-resistant and barrier-coated substrates for bakery, fast-food, and chilled ready-meal applications. EFSA compliance requirements and REACH Annex XVII restrictions on fluorinated chemistries are extending qualification timelines for new coating formulations.
Protective Packaging leads volumes today; Food Packaging is climbing the fastest.
End Use Industry:
Customer type concentration drives specification divergence between precision-tolerance electronics and cost-optimized consumer goods.
- Electronics:Dimensional precision and static-dissipative coatings for semiconductor and consumer device protection. German and Dutch fulfillment centers specify F-Flute grades with tight caliper tolerance to minimize void fill volume.
- Consumer Goods:High-volume retail packaging for household products and personal care. Mass-market brands prioritize unit cost over structural customization, favoring standard E-Flute specifications.
- Pharmaceutical Manufacturers:Serialization-ready cartons with tamper-evidence and child-resistance features.
- Textile Producers:Flat-packed garment shipping boxes with minimal crease and print registration requirements.
- Automotive Suppliers:Returnable packaging systems for just-in-sequence component delivery. German tier-1 suppliers specify B-Flute and E-Flute combinations with reinforced corners for multi-trip durability.
Electronics leads volumes today; Pharmaceutical Manufacturers are expanding most quickly.
Packaging Style:
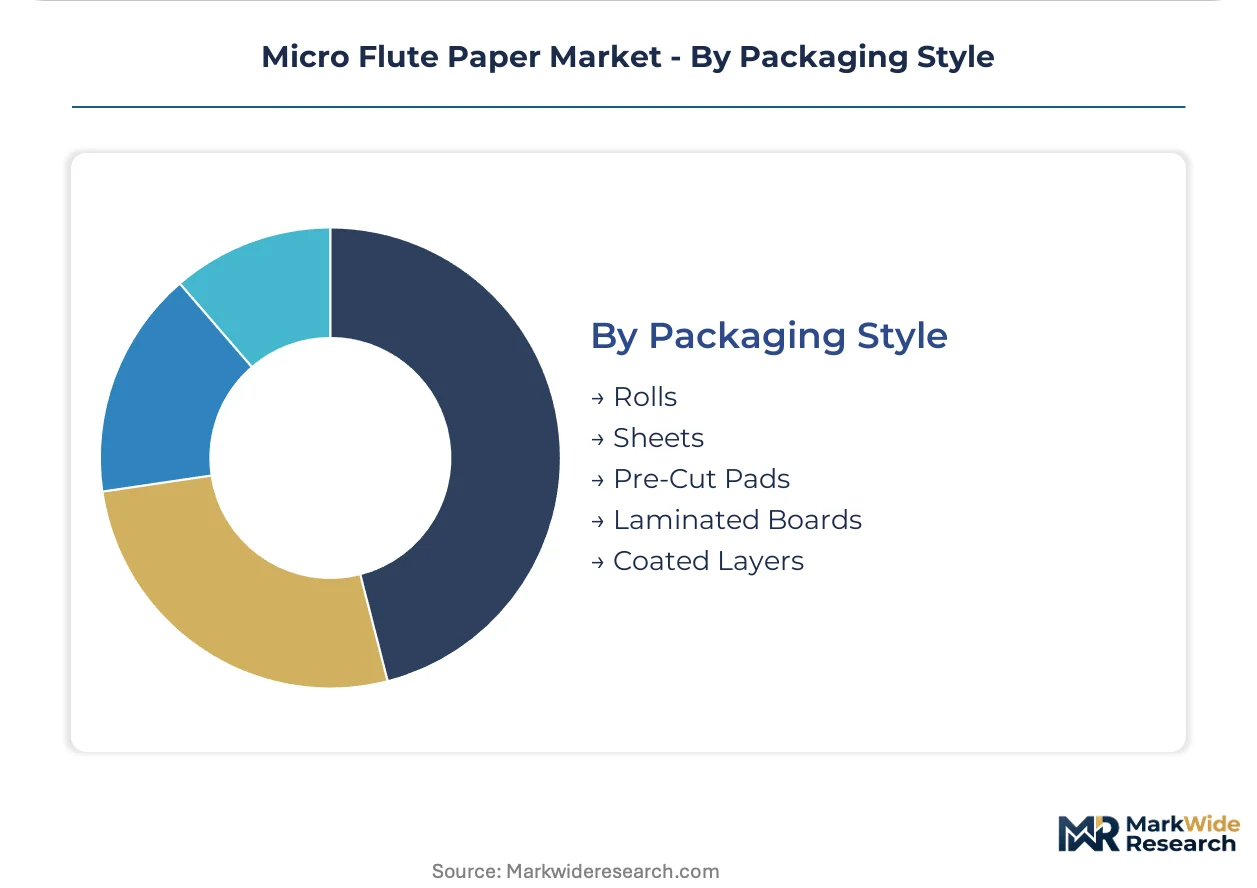
Supply concentration among narrow-web corrugator specialists shapes format availability and lead time economics.
- Rolls:Continuous web supply for automated case erection and inline die-cutting operations. High-volume e-commerce fulfillment centers in Germany consume roll-fed E-Flute for on-demand box sizing systems.
- Sheets:Flat palletized units for sheet-fed offset and flexographic printing. Commercial print providers in France and Belgium stock standard sheet sizes to support 48-hour promotional turnaround contracts.
- Pre-Cut Pads:Dimensionally finished blanks for manual assembly or automated tray forming.
- Laminated Boards:Litho-labeled or pre-printed liner adhesion for premium retail presentation.
- Coated Layers:Functional barrier treatments for grease, moisture, or mineral oil migration resistance.
Sheets lead volumes today; Rolls are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glue kitchen operators and flute profile specialists anchor European micro flute technical capacity, while Chinese papermakers concentrate substrate production in the Yangtze River Delta. Indian converter talent pools in Gujarat and Maharashtra are scaling up to serve e-commerce fulfillment expansion.
Germany
Automotive suppliers in Stuttgart and Munich specify B-Flute and E-Flute combinations for returnable component containers. The EU Packaging and Packaging Waste Regulation is compressing design cycles for mono-material certification. Smurfit Kappa's integrated containerboard mills in the Rhineland control substrate quality from pulp to finished flute.
United States
WestRock Company's corrugated packaging network serves e-commerce fulfillment centers across the Southeast and Midwest. EPA guidelines shape recycled content thresholds in domestic manufacturing. Chicago and Dallas logistics clusters consume roll-fed E-Flute for automated case erection systems.
China
Nine Dragons Paper Holdings Limited and regional producers feed recycled furnish into micro flute medium production. GB standards and REACH-aligned chemical restrictions limit certain coating chemistries. The Yangtze River Delta concentration of narrow-web corrugator manufacturing creates 12-18 month order backlogs.
India
Flipkart and Amazon India fulfillment centers in Bangalore and Hyderabad pilot micro flute dunnage to replace expanded polystyrene. BIS standards govern packaging material specifications for domestic appliance shipments. Gujarat's converter base is scaling technical capacity to meet qualification timelines.
Netherlands
Electronics fulfillment networks in Eindhoven and Rotterdam specify F-Flute grades with tight caliper tolerance to minimize void fill volume. ECHA's evolving substance restrictions on per- and polyfluoroalkyl substances redirect coating R&D. Dutch distribution hubs serve as entry points for EU-wide retail packaging programs.
Micro Flute Paper Market Vendor Landscape
Capital-heavy integrated paper producers compete with asset-light specialized converters across micro flute value chains. The vendor base fragments between containerboard multinationals with captive pulping, regional corrugator networks, and niche coating specialists. Two strategic archetypes dominate: backward-integrated substrate controllers and precision-conversion specialists. Competitive moves concentrate on recyclable barrier coating certification and narrow-web corrugator capacity expansion.
Among Irish-Dutch integrated producers, Smurfit Kappa represents the backward-integrated archetype with containerboard mill control. US-based WestRock Company exemplifies the corrugated network scale model. DS Smith occupies a position as the display-grade specialization anchor. These three sit within distinct competitive vectors—substrate integration, fulfillment network density, and retail-ready print fidelity—rather than direct product overlap.
| Leading Market Players |
|---|
| Smurfit Kappa |
| WestRock Company |
| International Paper Company |
| DS Smith |
| Stora Enso |
| Mondi Group |
| Novolex Holdings |
| Oji Holdings Corporation |
| Nine Dragons Paper Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Old Corrugated Container spot price volatility in European markets cascades through converter margins into three distinct pricing tiers for micro flute substrates, with integrated paper producers capturing premium positioning while independent converters absorb raw material swings on fixed annual contracts.
Pricing Analysis
Coated-versus-uncoated substrate splits dominate pricing architecture across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates food-contact certified barriers from industrial protective grades and commodity dunnage, with EFSA-compliant grease-resistant coatings commanding substantial premiums over uncoated E-Flute. Price differentiation hinges on barrier certification status and volume scale, with annual offtake commitments above containerboard mill minimums unlocking standard-tier access. Cost compression in economy grades is intensifying because Chinese recycled furnish imports displace domestic OCC collections. E-commerce fulfillment centers exhibit highest price sensitivity due to dimensional weight optimization mandates, while pharmaceutical serialization-ready cartons show lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian narrow-web corrugator manufacturers, where equipment order backlogs extend operational risk for capacity expansion timelines. Geographic supply concentration centers on Germany, China, and the United States, with Rhineland integrated mills, Yangtze River Delta recycled furnish processors, and Southeast US corrugated networks anchoring substrate flows. Raw material dependencies draw from OCC bale markets, virgin kraft linerboard contracts, and water-based barrier coating chemistries. Tariff exposure on corrugator machinery imports from European Union sources threatens North American converter capital expenditure programs. Distribution runs through direct mill relationships for high-volume roll-fed customers and regional sheet distributors serving short-run commercial print providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro flute paper functions as a stable compounder anchored by e-commerce protective packaging demand, where dimensional weight optimization mandates create durable substitution pull against plastic void-fill alternatives.
For Market Incumbents: Deploy captive containerboard capacity to defend margin position against OCC price volatility and emerging Asian substrate imports. Integrated producers should accelerate EFSA-compliant water-based barrier certification timelines before REACH Annex XVII enforcement windows close, while regional corrugator networks must secure narrow-web equipment slots with German machinery suppliers to preempt competitor capacity additions. For New Entrants and Emerging Players: Begin with Indian e-commerce fulfillment pilots targeting Flipkart and Amazon India appliance dunnage substitution programs, where BIS qualification pathways remain less saturated than European regulatory frameworks. White-space opportunity concentrates in Gujarat converter technical scaling and Bangalore-Hyderabad logistics cluster proximity. Go-to-market positioning should emphasize expanded polystyrene replacement credentials with documented drop-test performance. For Investors and Strategic Acquirers: Asymmetric upside sits with coating specialists possessing EFSA food-contact notifications and REACH-compliant water-based grease barrier formulations, as regulatory compression accelerates qualification value. Five-to-ten year viability rests on mono-material recyclability certification and forest chain-of-custody verification. Acquisition target archetype: European mid-cap converters with digital print convergence capabilities and narrow-web corrugator installed base. Signal to watch: EU Packaging and Packaging Waste Regulation enforcement timeline acceleration prompting brand-owner specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Production | Captive OCC pulping capacity insulates Smurfit Kappa from virgin linerboard price swings across European supply chains. |
| Water-Based Barrier Coating Certification | EFSA-compliant grease-resistant treatments unlock food packaging premium positioning ahead of fluorinated chemistry bans. |
| Narrow-Web Corrugator Capacity Expansion | German machinery supplier order backlogs create 12-18 month first-mover advantages for confirmed equipment slots. |
| Digital Print Convergence Investment | Single-pass inkjet systems enable 500-unit minimum runs for promotional retail packaging previously uneconomical for flexography. |
| Direct-to-Retailer Procurement Contracts | UK grocery retailer disintermediation bypasses distributor layers and captures 48-hour promotional turnaround requirements. |
Methodological Framework
Direct dialogue with glue kitchen operators, flute profile specialists, corrugated plant managers, and coating R&D directors grounded qualitative findings in operational realities across German, Dutch, and US converter networks. Secondary validation drew from EFSA food-contact notifications, ECHA REACH substance restrictions, EPA recycled content guidelines, and containerboard mill production disclosures. Bottom-up and top-down triangulation reconciled substrate volume flows with end-use demand segmentation.
Bottom-up demand modeling aggregated protective packaging, retail display, and food-contact application volumes across electronics, consumer goods, and automotive end-use industries. Segmentation dimensions included flute profile tier, barrier coating functionality, packaging format, and regional production hub clustering. CAGRs were derived from recursive substitution analysis of plastic void-fill displacement and e-commerce fulfillment network expansion trajectories. Industry-specific forecast inputs incorporated EU Packaging and Packaging Waste Regulation compliance timelines and narrow-web corrugator capacity commissioning schedules.
Several conditions sit outside the modeled scope, including unforeseen EFSA notification delays, abrupt OCC bale market dislocations, and single-facer equipment supply chain disruptions. Forecasts reflect assumptions about regulatory enforcement consistency and brand-owner specification conversion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paper Tubes Market