
 Global Paper and Paperboard Packaging Market | 2026-2036
Global Paper and Paperboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper and Paperboard Packaging Market Intelligence
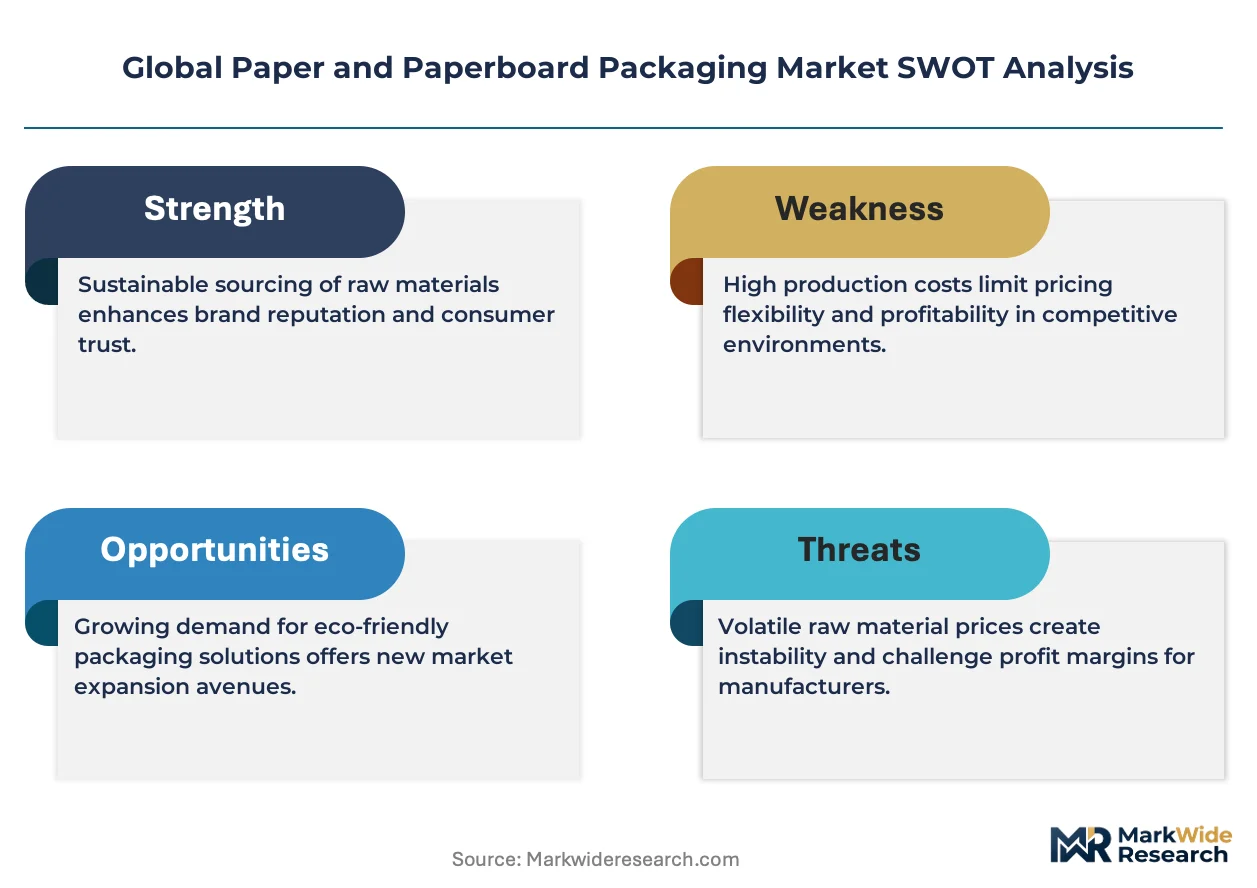
Forest Stewardship Council (FSC) certification is rotating the competitive landscape toward suppliers with verified sustainable sourcing. International Paper leverages its vast forestland assets to ensure certified fiber supply. Smurfit Westrock sustains market leadership through its integrated model of recycled fiber collection and box manufacturing. Mondi Group positions its portfolio around sustainable materials, aligning with corporate buyer environmental, social, and governance mandates.
Paper and paperboard packaging comprises materials derived from wood pulp or recycled fibers, engineered into various structural forms. These materials are defined by their grammage and caliper, which determine their suitability for containing, protecting, and transporting goods. Corrugated boxes dominate volume due to their essential role in logistics and e-commerce supply chains. The folding cartons segment, driven by consumer goods applications, offers higher margin potential through advanced printing and finishing capabilities.
Regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern food-contact safety, setting strict chemical migration limits. China's GB standards for packaging materials also impose compliance hurdles for market access, influencing material formulation. Producers must navigate the complex trade-offs between recycled content mandates and the performance requirements of virgin fiber for demanding applications.
Market Dynamics
The push for circular economy models, exemplified by EU directives, creates a fundamental tension with the finite availability and quality degradation of recycled fiber. This dynamic forces innovation in material blending, collection infrastructure, and coating technologies to meet performance demands.
Growth Catalysts
- E-commerce Expansion:Concentrated demand for corrugated boxes from e-commerce fulfillment centers in the United States and China provides a foundational volume driver for the entire industry.
- Plastic Substitution Mandates:Regulations like the EU's Single-Use Plastics Directive directly stimulate demand for paper-based alternatives in food service, retail, and consumer goods applications.
- Barrier Technology:Development of functional barrier coatings enables paper and paperboard to enter applications previously dominated by plastics, particularly in the food and beverage sector.
Market Restraints
- Input Cost Volatility:Fluctuation in the price and availability of virgin pulp and recovered paper creates margin pressure and complicates long-term planning for converters and manufacturers.
- Performance Gaps:Inherent limitations in moisture resistance, durability, and transparency compared to plastic polymers restrict paper's use in certain high-performance packaging applications.
- Regulatory Divergence:Conflicting food-contact safety standards, such as the distinct chemical migration limits set by the US FDA and Europe's EFSA, increase compliance costs for global producers.
Strategic Opportunities
- Molded Fiber Applications:Molded pulp packaging presents a direct substitution opportunity for expanded polystyrene (EPS) and thermoformed plastics in protective packaging for electronics and consumer durables.
- Emerging Market Retail:The growth of organized retail and supermarket chains in Southeast Asia and Latin America creates new, centralized demand for high-quality folding cartons and corrugated displays.
- Smart Packaging Integration:Embedding technologies like RFID or NFC into paperboard packaging offers enhanced supply chain visibility and consumer engagement, creating a new value-added service layer.
Industry Challenges
- Certification Complexity:The administrative and financial burden of achieving and maintaining chain-of-custody certifications like the Forest Stewardship Council (FSC) across complex global supply chains is substantial.
- Recycling Infrastructure Gaps:Inconsistent collection, sorting, and processing infrastructure for post-consumer packaging, particularly for coated or composite materials, limits the effective supply of high-quality recycled fiber.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper and Paperboard Packaging Market |
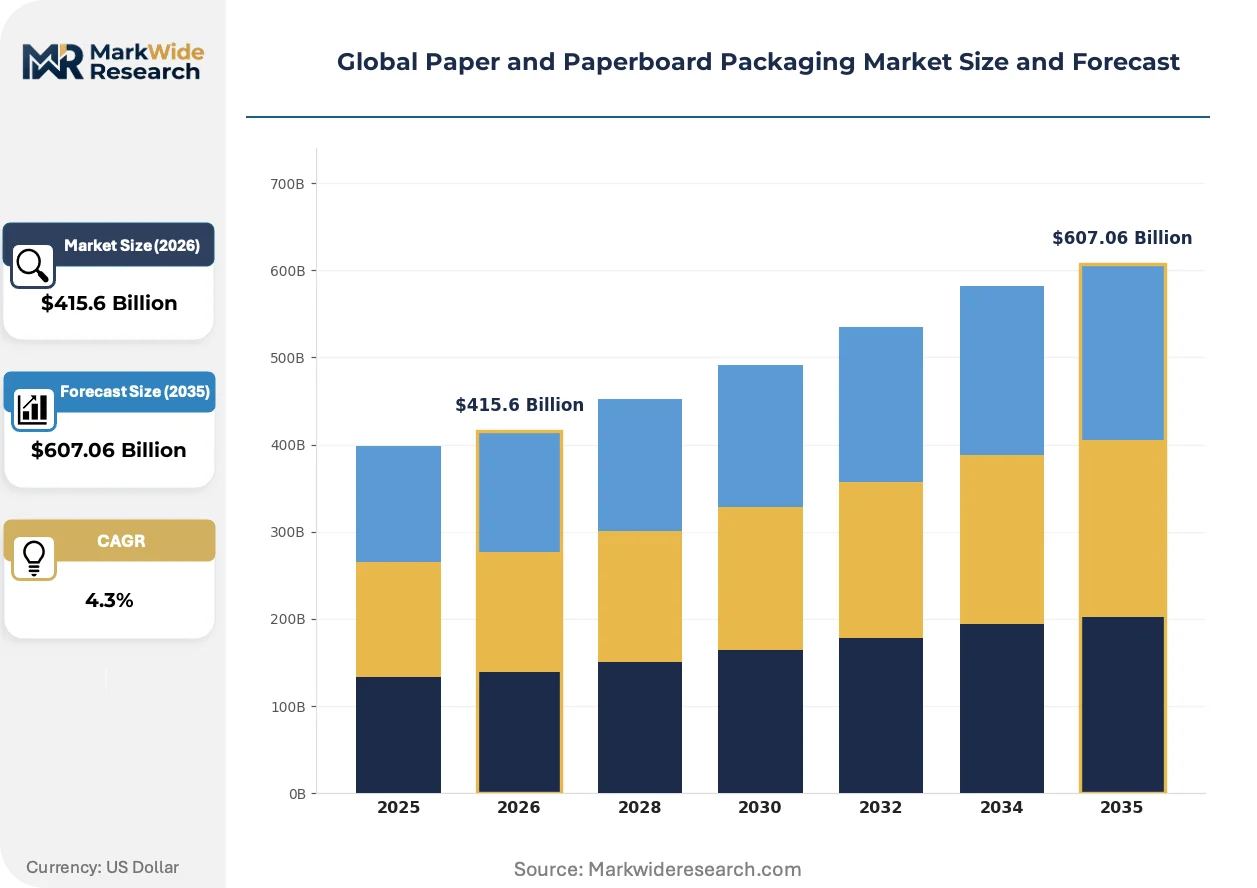
| Market Size in 2026 | $415.6 Billion |
| Market Size in 2035 | $607.06 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Folding Cartons, Paper Bags, Wrapping Paper, Cardboard Sheets, Labels Material Grade: Kraft Paper, Bleached Paper, Recycled Paper, Virgin Fiber, Coated Paper, Uncoated Paper Application: Food & Beverage, Personal Care, Electronics, Pharmaceuticals, Consumer Goods, Industrial Products End User: Manufacturers, Wholesalers, Retail Chains, E-commerce Companies, Distributors, Packaging Service Providers |
| Companies Covered | Tetra Pak, Oji Holdings, International Paper, Sonoco Products Company, DS Smith, Smurfit Westrock, Mondi Group, Packaging Corporation of America, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper and Paperboard Packaging Market Strategic Shifts & Innovations
Material science advancements and regulatory pressures are compelling a re-evaluation of fiber-based packaging's core capabilities. This drives a focus on enhancing functional properties without compromising recyclability, creating new competitive battlegrounds for material suppliers and converters.
Water-based dispersion coatings provide paperboard with essential moisture and grease resistance. Food service and frozen food sectors are rapidly adopting these materials to replace products lined with polyethylene. This development is fragmenting the rigid barrier packaging market, allowing paper to compete in segments it previously could not.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on supply chain environmental impacts. This policy forces packaging producers to provide customers with verifiable data on recycled content, carbon footprint, and end-of-life management. The corrugated box segment is most affected, as its industrial customers must now report these metrics.
Large consumer-packaged goods companies are consolidating suppliers around partners offering global consistency in sustainable material specifications. This moves procurement away from regional spot buys toward strategic agreements based on ESG alignment. The trend is most pronounced in the personal care and premium food sectors in North America and Europe.
Global Paper and Paperboard Packaging Market Segmentation
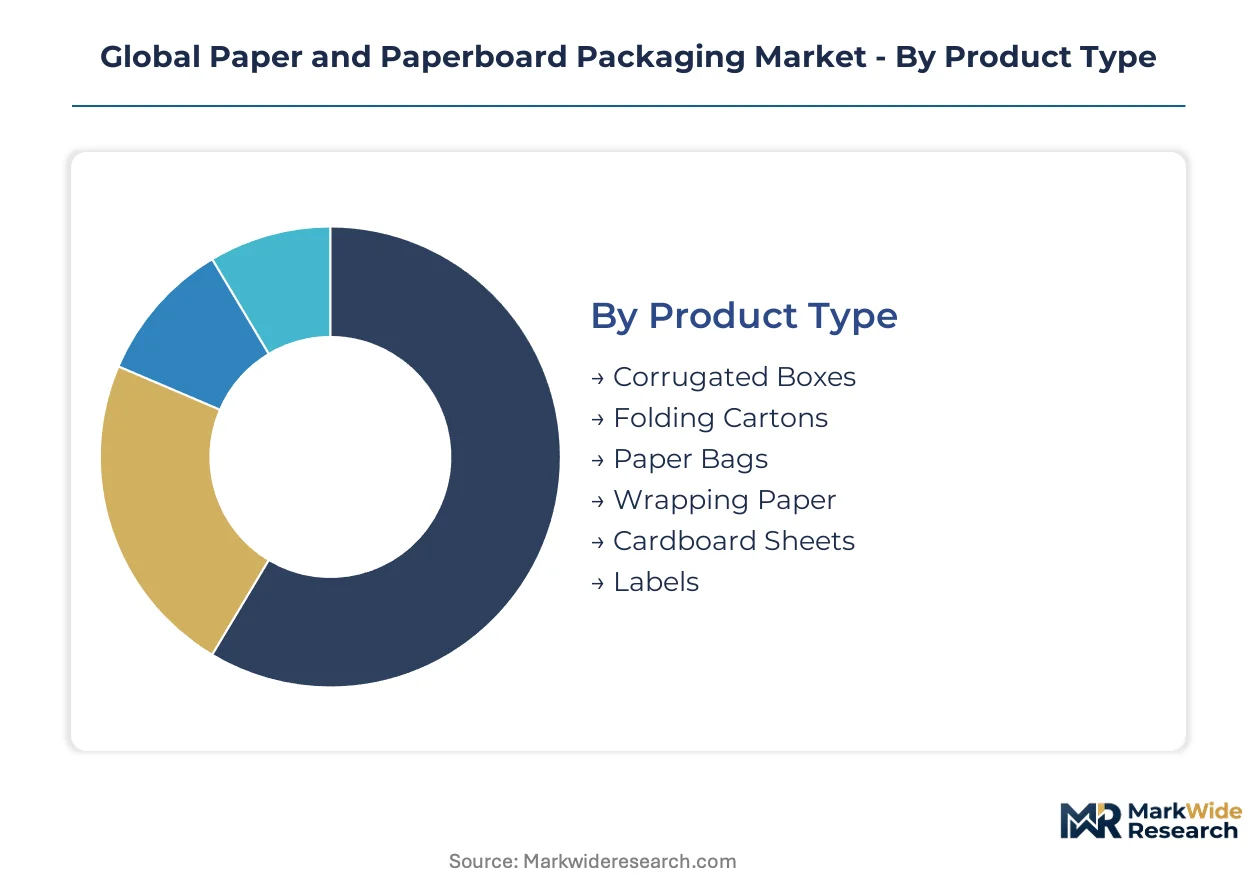
Market segmentation provides a granular understanding of demand patterns and competitive dynamics within the paper and paperboard packaging industry. Analyzing these distinct segments reveals where value creation concentrates and how regulatory pressures reshape material preferences across various applications.
Product Type:
Profitability within product types varies significantly, with specialized formats commanding higher margins.
- Corrugated Boxes:These multi-layered fiberboard structures provide exceptional strength and cushioning for transport. E-commerce fulfillment centers in the United States and China generate foundational volume demand for shipping and protective packaging.
- Folding Cartons:Typically made from paperboard, these pre-creased cartons are shipped flat and assembled at the point of filling. Consumer goods applications, particularly in North America and Europe, offer higher margin potential through advanced printing and finishing capabilities.
- Paper Bags:These flexible containers are common in retail and food service, increasingly replacing single-use plastic bags due to environmental mandates.
- Wrapping Paper:Used for protective interleaving or decorative purposes, this segment serves industrial packaging and gift wrapping markets.
- Cardboard Sheets:Flat, rigid paperboard sheets find application in layer pads, dividers, and as raw material for further conversion.
- Labels:Paper-based labels provide product identification and branding for a vast array of consumer and industrial goods.
The dominant share belongs to Corrugated Boxes, while Folding Cartons are closing the gap fastest.
Material Grade:
Material grade selection often reflects a balance between cost efficiency and specific performance requirements.
- Recycled Paper:Composed primarily of post-consumer or post-industrial waste fibers, this grade aligns with circular economy objectives. However, quality degradation and infrastructure gaps limit its use in demanding food-contact applications.
- Virgin Fiber:Derived directly from wood pulp, this material offers superior strength, purity, and consistency compared to recycled alternatives. Demanding applications, particularly those requiring direct food contact or high structural integrity, depend on virgin fiber performance.
- Kraft Paper:Known for its high tensile strength and tear resistance, kraft paper is a robust material for industrial bags and heavy-duty packaging.
- Bleached Paper:Chemically treated to achieve a bright white appearance, bleached paper enhances printability for premium packaging and graphic applications.
- Coated Paper:Surface-treated with a coating to improve smoothness, gloss, and print fidelity, this paper type is common in high-quality folding cartons.
- Uncoated Paper:This basic paper grade offers a natural, matte finish suitable for various packaging applications where aesthetic demands are less critical.
Virgin Fiber maintains a performance advantage for critical applications, but Recycled Paper exhibits the steepest expansion trajectory.
Application:
Volume demand across applications is largely driven by consumer purchasing patterns and regulatory shifts.
- Food & Beverage:This segment encompasses packaging for fresh produce, frozen foods, and prepared meals, driven by consumer demand for sustainable options. Functional barrier coatings enable paperboard to compete in applications previously dominated by plastics.
- Electronics:Protective packaging for consumer electronics and components increasingly utilizes molded fiber solutions. This directly substitutes expanded polystyrene (EPS) and thermoformed plastics in protective applications.
- Personal Care:Premium cosmetics and hygiene products leverage folding cartons for branding and product protection in North America and Europe.
- Pharmaceuticals:Strict regulatory requirements for product integrity and tamper-evidence shape packaging solutions for medicines and medical devices.
- Consumer Goods:This broad category includes packaging for household items, apparel, and toys, where shelf appeal and brand differentiation are critical.
- Industrial Products:Heavy-duty corrugated boxes and specialized paper packaging protect machinery parts, automotive components, and bulk goods during transit.
Food & Beverage applications represent the largest volume, with Electronics gaining share fastest.
End User:
End-user requirements dictate packaging specifications, influencing material choices and design complexity.
- E-commerce Companies:These businesses require robust, lightweight, and often customizable packaging for direct-to-consumer shipments. Concentrated demand from e-commerce fulfillment centers in the United States and China drives significant corrugated box volume.
- Retail Chains:Supermarket chains and organized retail in Southeast Asia and Latin America demand high-quality folding cartons and corrugated displays for product presentation. Shelf-ready packaging solutions are crucial for efficient restocking.
- Manufacturers:Industrial manufacturers utilize packaging for internal logistics, component protection, and shipping finished goods to distributors.
- Wholesalers:These intermediaries require bulk packaging solutions for efficient storage and distribution to smaller retailers or businesses.
- Distributors:Packaging service providers offer specialized design, printing, and assembly services, catering to diverse client needs.
- Packaging Service Providers:These companies specialize in contract packaging, offering expertise in design, material selection, and fulfillment for various clients.
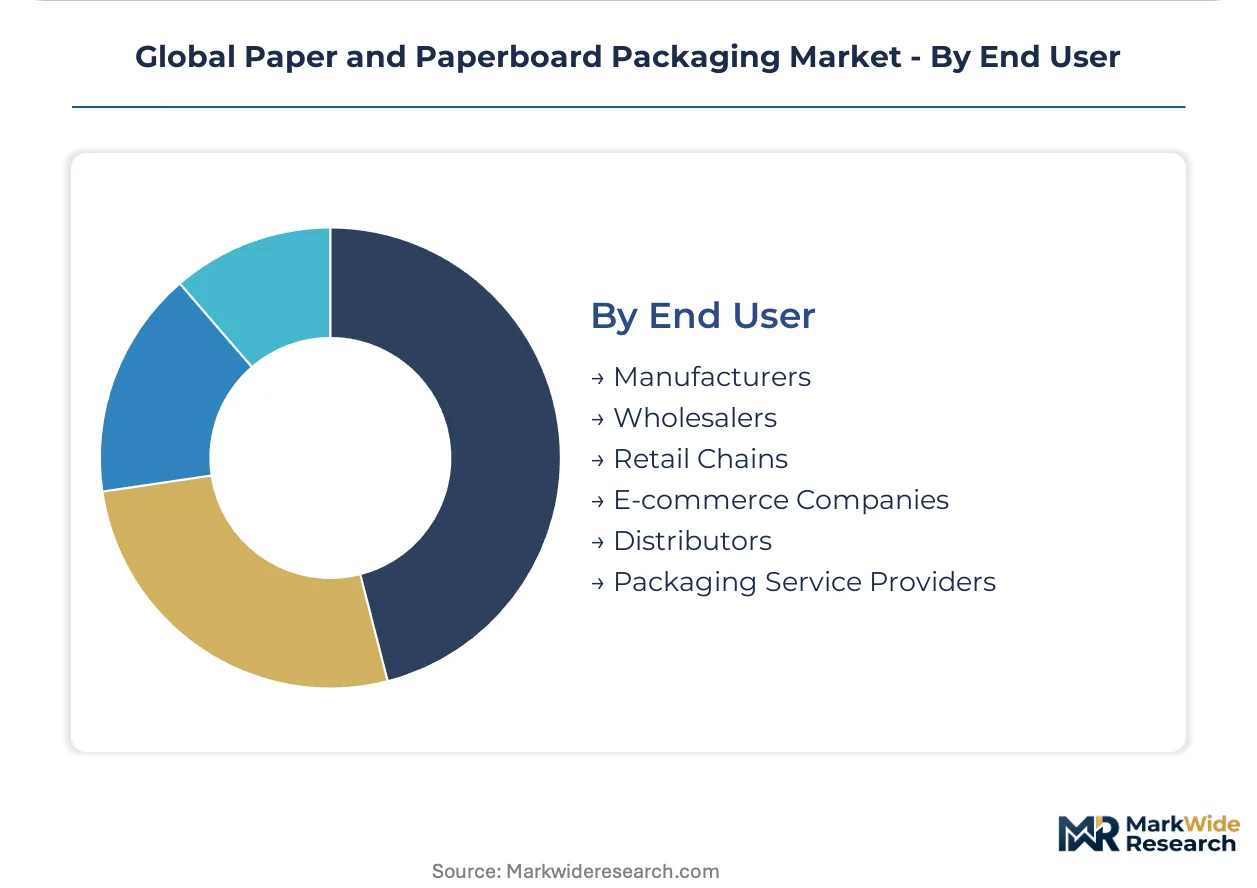
Manufacturers constitute a foundational end-user segment, but E-commerce Companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU directives against single-use plastics drive significant demand for paper-based packaging alternatives across Europe. This regulatory push, combined with expanding e-commerce operations, reshapes material procurement globally. Emerging market retail growth also concentrates new demand for high-quality packaging formats.
United States
E-commerce expansion and consumer goods demand generate substantial corrugated box volume in the United States. The US Food and Drug Administration (FDA) sets strict chemical migration limits for food-contact packaging. Major logistics hubs like Chicago and Los Angeles concentrate significant packaging distribution activities.
China
Rapid e-commerce growth and industrial manufacturing fuel an immense demand for corrugated boxes in China. China's GB standards for packaging materials impose specific compliance hurdles for market access. Manufacturing centers in the Yangtze River Delta drive innovation in material formulation.
Germany
Strong consumer goods sectors and a focus on circular economy models underpin paper packaging demand in Germany. The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed environmental impact disclosure. The Rhine-Ruhr region, a major industrial cluster, sees increased adoption of sustainable packaging solutions.
India
Expanding organized retail and a burgeoning middle class propel folding carton and paper bag demand in India. The Bureau of Indian Standards (BIS) continually updates packaging material specifications for consumer safety. Industrial zones around Mumbai and Delhi are experiencing significant growth in packaging conversion facilities.
Brazil
Growth in consumer goods and food & beverage sectors creates robust demand for paperboard packaging in Brazil. ANVISA, the national health surveillance agency, regulates food-contact materials with specific safety requirements. Manufacturing hubs in São Paulo concentrate packaging production and innovation.
Global Paper and Paperboard Packaging Market Key Industry Players
Player mix skews toward large, vertically integrated manufacturers controlling significant forestland or recycling infrastructure. The industry exhibits a tiered structure, with global giants alongside regional specialists and niche innovators. Strategic archetypes include integrated fiber producers, specialized barrier solution providers, and sustainable material converters. Capacity expansion, driven by e-commerce demand, and strategic partnerships for technology development remain dominant competitive moves across the sector.
Global leaders like International Paper exemplify the integrated fiber producer archetype, leveraging vast forestland assets to ensure certified fiber supply and consistency for demanding applications. Smurfit Westrock represents another key archetype, sustaining market leadership through its integrated model of recycled fiber collection and box manufacturing for diverse product types. Mondi Group further anchors the segment of companies positioning their portfolio around sustainable materials, aligning with corporate buyer environmental, social, and governance mandates. These companies collectively shape procurement patterns for large consumer goods enterprises seeking global consistency and verifiable sustainability data.
| Leading Market Players |
|---|
| Tetra Pak |
| Oji Holdings |
| International Paper |
| Sonoco Products Company |
| DS Smith |
| Smurfit Westrock |
| Mondi Group |
| Packaging Corporation of America |
| Amcor |
| Others |
Cost & Logistics Intelligence
Three-month lead times for specialized barrier-coated paperboard directly influence pricing leverage for advanced material suppliers, reflecting complex production schedules and limited global capacity. This dynamic creates distinct pricing tiers based on technical specifications and order volumes across the supply chain.
Pricing Analysis
FSC certification level creates the primary spread in virgin fiber pricing, reflecting verifiable sustainable sourcing and premium buyer demand. The dominant pricing model combines long-term contract-based offtake for large integrated producers with commodity spot pricing for recovered paper. Pricing pressure stems from input cost volatility, particularly for virgin pulp and energy, impacting converter margins. E-commerce companies demonstrate high price sensitivity for corrugated boxes, while premium personal care brands prioritize performance over cost for folding cartons.
Supply Chain Analysis
Just-in-time inventory strategies dominate for standard corrugated boxes, driven by e-commerce fulfillment centers in the United States and China. The supply chain draws heavily from virgin pulp producers in North America and Scandinavia, alongside recovered paper collection networks across Europe. Commodity price volatility for virgin pulp and recovered paper presents a structural risk to converters. Distribution runs through a mix of integrated packaging manufacturers and specialized packaging service providers directly serving end-user industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a high-growth disruption, driven by plastic substitution mandates and continuous barrier technology advancements.
For Market Incumbents: Consolidate certified fiber supply through strategic land acquisitions or long-term offtake agreements with sustainable forestry operations. Invest heavily in recycled fiber collection and processing infrastructure to mitigate input cost volatility and meet circular economy mandates. Develop advanced barrier coatings in-house to counter performance gaps against plastics, particularly for food and beverage applications. Leverage existing global distribution networks to offer consistent sustainable packaging solutions to multinational consumer goods enterprises.
For New Entrants and Emerging Players: Certification fast-track programs, such as for molded fiber products, offer a rapid entry point into protective packaging for electronics. Target emerging market retail in Southeast Asia and Latin America, where demand for high-quality folding cartons is expanding. Specialize in water-based dispersion coatings for food service applications, offering a sustainable alternative to polyethylene-lined products. Focus go-to-market strategies on verifiable ESG alignment to attract corporate buyers seeking sustainable material specifications.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational materials play because essential goods packaging remains indispensable, and sustainability mandates will only intensify. Seek acquisition targets with strong intellectual property in barrier coating technologies or integrated recycled fiber processing capabilities. The signal to watch is the widespread adoption of water-based dispersion coatings across the frozen food sector, indicating a successful shift away from plastic-lined alternatives. Prioritize companies demonstrating robust compliance with EU CSRD requirements, offering verifiable data on environmental impact.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Corrugated Boxes | Meets concentrated e-commerce demand in China and the United States. |
| Backward Integration into Virgin Pulp | Secures consistent, high-quality fiber supply for demanding applications. |
| Investment in Water-Based Barrier Coatings | Enables paperboard to enter plastic-dominated food and beverage segments. |
| Development of Molded Fiber Solutions | Substitutes expanded polystyrene in electronics protective packaging. |
| Global Certification Program Alignment | Provides verifiable sustainability data for multinational consumer goods clients. |
Research Approach
A standing panel of packaging manufacturers, material suppliers, e-commerce logistics managers, and food & beverage procurement leads provided ongoing calibration for market data. This primary intelligence was triangulated with secondary research from regulatory body publications, industry association reports, corporate sustainability disclosures, and trade statistics. Both bottom-up and top-down approaches ensured comprehensive market sizing and validation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material grade, application, end user, and regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected market dynamics, incorporating inputs like e-commerce penetration rates in China and plastic substitution mandate timelines in Europe.
Underlying assumptions cover stable economic growth and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility and recycling infrastructure development. Practitioners should keep alternative scenarios live as global trade policies and material science advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Corrugated Shippers Market