
 Push-Up Paperboard Tube Market | 2026-2036
Push-Up Paperboard Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Push-Up Paperboard Tube Market Analytics
The EU Packaging and Packaging Waste Regulation is decoupling push-up paperboard tube demand from virgin plastic dependency across European personal care supply chains. Sonoco Products Company leverages its recycled fiber expertise to supply major cosmetics brands with certified post-consumer content tubes. WestRock anchors North American capacity through integrated pulp-to-converted-tube operations at scale. Smurfit Kappa Group competes on structural design, offering crush-resistant spiral-wound constructions that protect solid-form products through distribution.
Push-up paperboard tubes are cylindrical containers manufactured from spiral-wound or convolute-wound kraft paperboard layers, typically 1.5–3.0 mm wall thickness, with an inner wax or bio-based barrier coating and a push-up disk mechanism that elevates product during use; they serve as primary packaging for solid and semi-solid goods requiring controlled dispensing without rigid plastic shells. Eco-friendly tubes lead structural growth as brand owners mandate plastic-free claims and home-compostable end-of-life pathways. Custom tubes capture concentrated margin pools where short-run digital printing and bespoke diameters serve premium cosmetics and limited-edition food packaging. Standard tubes remain the volume base for stationery and pharmaceutical applications where cost efficiency dominates procurement criteria.
The EU Green Deal and REACH frameworks govern chemical migration limits and fiber sourcing disclosures for paperboard food and cosmetic contact materials in Europe. FDA regulations in the United States set barrier performance standards for oil and moisture resistance in direct-contact packaging applications. Stakeholders must monitor evolving extended producer responsibility fee structures and bio-based coating certification schemes to secure compliant raw material positions.
Market Dynamics
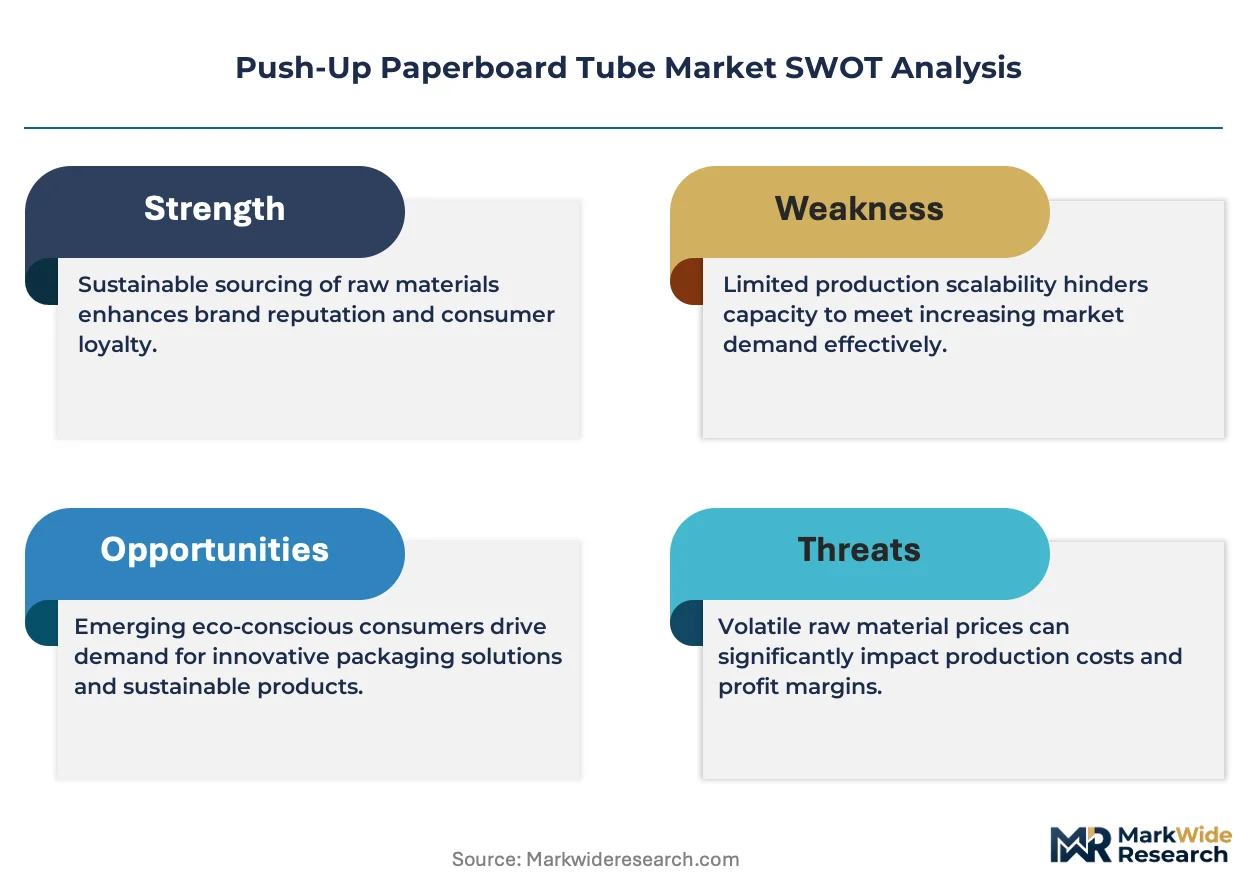
EU Packaging and Packaging Waste Regulation mandates are forcing cosmetics and personal care manufacturers to eliminate virgin plastic from primary packaging, redirecting capital toward fiber-based tube conversion lines and certified compostable barrier coatings.
Growth Catalysts
- REACH chemical migration limits:European cosmetic contact material rules are accelerating brand migration from plastic to paperboard substrates with compliant bio-based barriers.
- Solid-format personal care:Waterless deodorant and lip balm formulations are proliferating, creating natural pairing with push-up paperboard mechanics.
- German domestic converter concentration:Personal care manufacturers source certified compostable tubes from local supply chains, reducing lead times and import dependency.
Market Restraints
- Kraft pulp price volatility:Unbleached fiber input costs fluctuate with energy-intensive pulping operations, compressing converter margins during supply shocks.
- Bio-based coating certification gaps:Home-compostable claims lack harmonized testing protocols across EU member states, creating market access friction.
- Aluminum laminate substitution:Metal barrier tubes retain moisture and oxygen performance advantages for oil-rich cosmetic formulations.
Strategic Opportunities
- India PLI scheme for packaging:Domestic manufacturing incentives are attracting paperboard tube investment to serve emerging personal care brands.
- Pharmaceutical solid-dose applications:Suppository and pessary packaging represents untapped demand for child-resistant push-up formats.
- Digital printing convergence:Short-run customization capabilities are enabling limited-edition cosmetics with variable design and regional versioning.
Industry Challenges
- Barrier coating R&D talent scarcity:Formulation chemists with bio-based polymer expertise command premium compensation, constraining mid-tier converter innovation capacity.
- Extended producer responsibility fee complexity:Evolving EPR structures across EU member states require dedicated compliance infrastructure and multi-jurisdiction reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Push-Up Paperboard Tube Market |
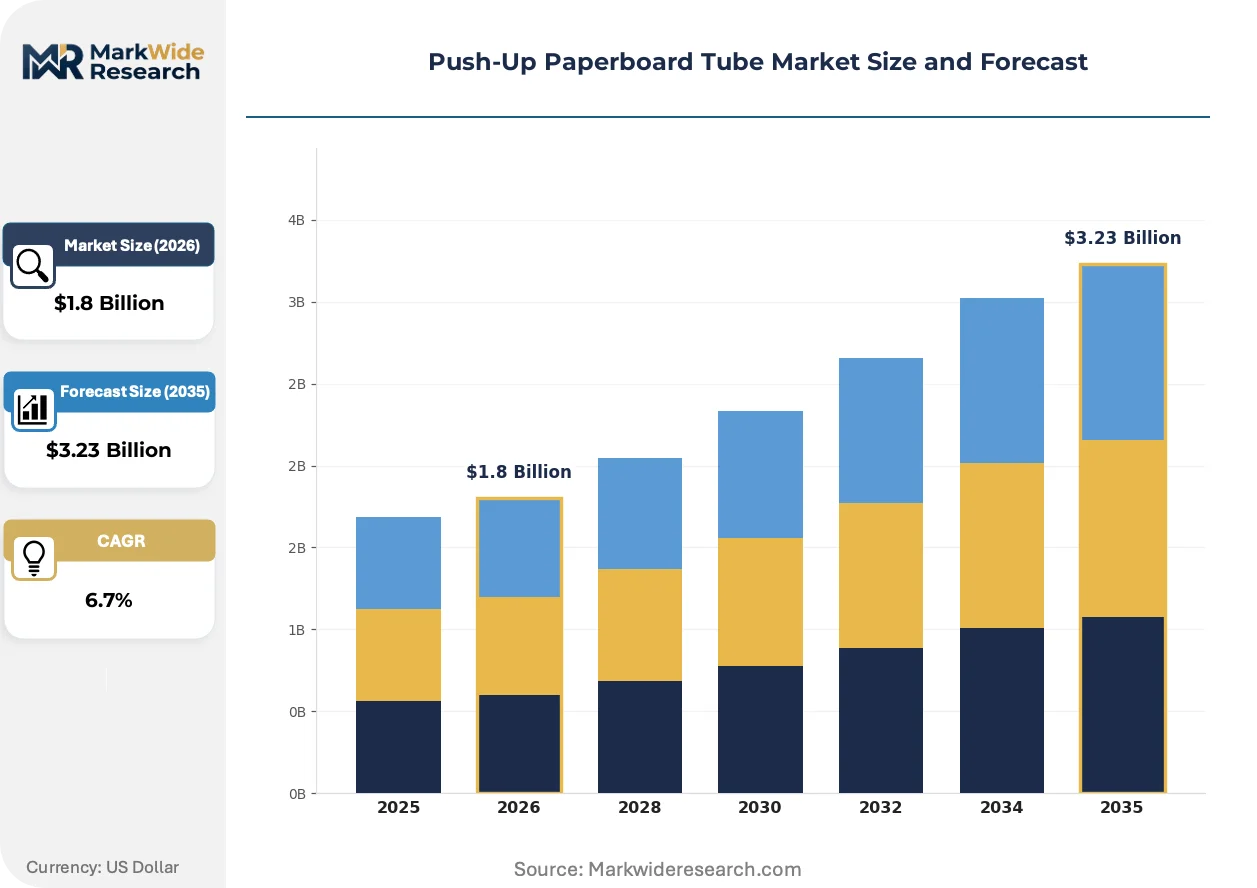
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Custom Tubes, Eco-Friendly Tubes, Decorative Tubes Size: Small Tubes, Medium Tubes, Large Tubes, Jumbo Tubes End Use: Cosmetics, Food Packaging, Pharmaceuticals, Stationery Closure Type: Screw Closure, Snap Closure, Push-Up Closure, Flip Top |
| Companies Covered | Sonoco Products Company, WestRock, Smurfit Kappa Group, Yazoo Mills, Valk Industries, Ace Paper Tube, Pacific Paper Tube, Chicago Mailing Tube, Marshall Paper Tube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Push-Up Paperboard Tube Market Evolving Landscape
Barrier coating chemistry and converting automation are the primary vectors of competitive differentiation, with fiber sourcing transparency and end-of-life certification becoming non-negotiable procurement criteria.
Water-based acrylic barrier coatings are electrifying moisture and oil resistance performance in paperboard tubes. Premium cosmetics brands in France and Germany are specifying these formulations for solid perfume and balm applications. The technology is compressing the performance gap against plastic laminates while maintaining home-compostable disposal pathways.
EU Green Deal circular economy action plans are mandating minimum recycled fiber content thresholds for packaging placed on the single market. Converters must reconfigure pulp sourcing and implement mass-balance chain-of-custody documentation. Personal care brands with pan-European distribution are consolidating supplier relationships to reduce audit burden.
Brand procurement teams are embedding plastic-free claims as mandatory line-item specifications in packaging tenders. Direct-to-consumer cosmetics channels are replacing traditional wholesale distribution for tube-intensive product categories. This pattern is most pronounced in Nordic markets where consumer willingness-to-pay for certified sustainable packaging exceeds continental averages.
Push-Up Paperboard Tube Market Segmentation
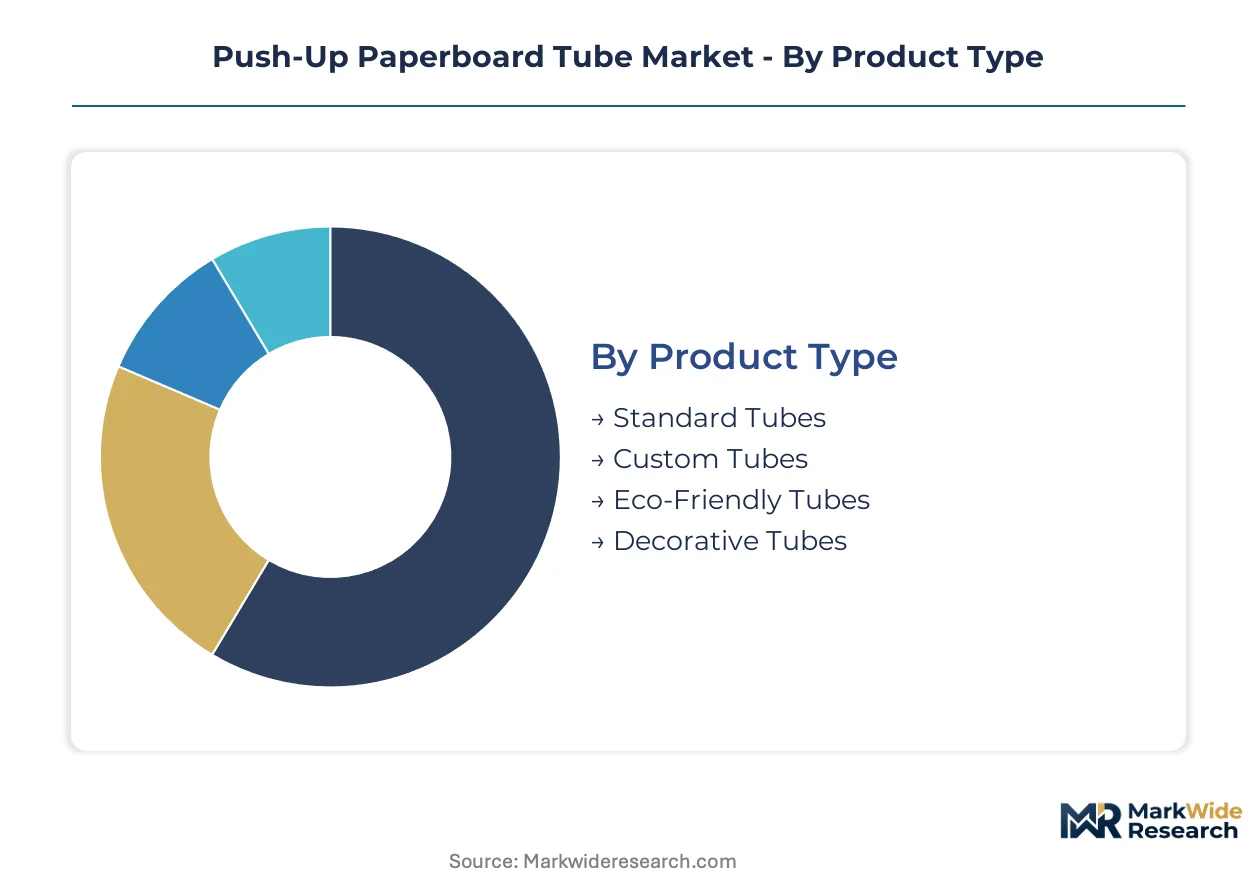
Segmentation in push-up paperboard tubes reflects divergent technical requirements across solid-form product categories. Cosmetic brands demand bespoke diameters and premium finishes, while pharmaceutical and food applications prioritize barrier integrity and regulatory compliance over customization.
Product Type:
Upgrade cycles in this market track brand sustainability commitments and short-run marketing calendars, with converters investing in digital printing and compostable coating lines to capture specification shifts.
- Eco-Friendly Tubes:Manufactured from unbleached kraft fiber with bio-based wax or PLA barrier coatings certified for home composting. Demand concentrates among German and French cosmetics manufacturers eliminating virgin plastic from primary packaging under EU Green Deal procurement mandates.
- Custom Tubes:Short-run production with variable diameter, length, and surface finishing enabled by digital printing and precision die-cutting. Premium cosmetics brands in direct-to-consumer channels specify these formats for limited-edition launches requiring rapid design turnaround.
- Standard Tubes:High-volume spiral-wound construction with conventional wax barriers for cost-sensitive stationery and pharmaceutical applications.
- Decorative Tubes:Embossed, foil-stamped, or specialty-laminated finishes for gift and promotional product packaging.
Standard tubes sit at the top of the volume ranking, with eco-friendly tubes climbing the fastest.
Size:
Tube dimension selection correlates with product dose volume and retail display requirements, with personal care brands optimizing for shelf presence and travel-portability trade-offs.
- Small Tubes:Diameters under 25mm for lip balm, solid perfume, and sample-size cosmetics. Nordics direct-to-consumer brands favor this format for subscription box compatibility.
- Medium Tubes:25-40mm diameter range dominating deodorant and balm applications. This specification captures the highest unit volume across European personal care converters.
- Large Tubes:40-60mm diameter for solid shampoo bars and multi-use body balms.
- Jumbo Tubes:Exceeding 60mm diameter for institutional food service and bulk pharmaceutical packaging.
Medium tubes command the largest production share, though small tubes are expanding most quickly through sampling and miniaturization trends.
End Use:
Application-driven segmentation reveals divergent barrier performance thresholds and regulatory exposure across contact material categories.
- Cosmetics:Primary demand driver requiring oil-resistant barriers for anhydrous balms and deodorants. REACH chemical migration limits govern bio-based coating selection for products contacting European skin.
- Pharmaceuticals:Suppository and pessary packaging with child-resistant closure requirements. FDA moisture barrier standards apply to US-bound solid-dose applications.
- Food Packaging:Spice sticks, confectionery, and portion-control formats requiring grease resistance and flavor barrier integrity.
- Stationery:Glue sticks and craft materials where cost efficiency outweighs advanced barrier specifications.
Cosmetics generates the steepest value per unit, while food packaging shows the strongest volume growth trajectory.
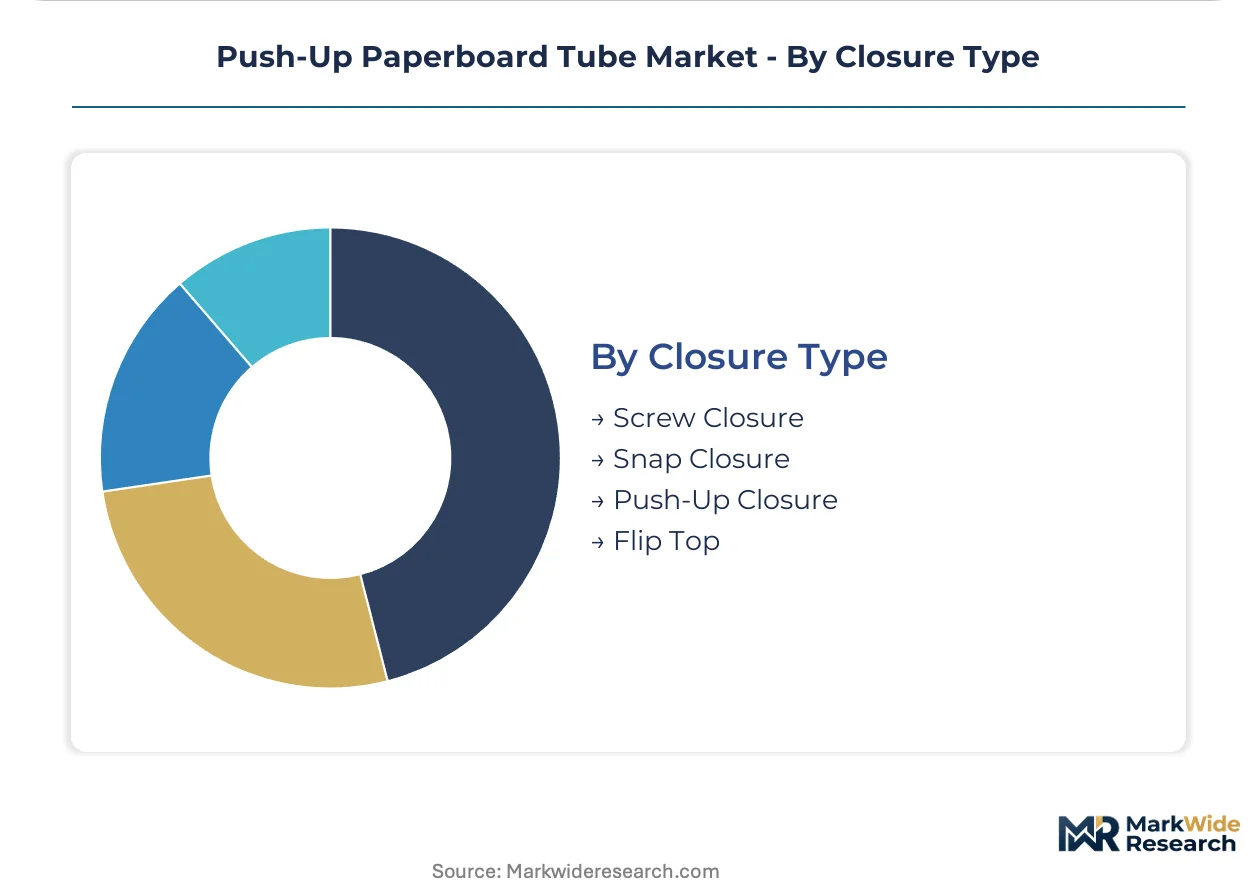
Closure Type:
Mechanism selection determines dispensing control, tamper evidence, and end-of-life material compatibility for circular economy claims.
- Push-Up Closure:Integrated disk mechanism elevating product through finger pressure. Solid-format deodorant brands specify this format for plastic-free positioning and home-compostable disposal pathways.
- Screw Closure:Threaded cap with gasket seal for moisture-sensitive pharmaceuticals and food products requiring resealability.
- Snap Closure:Friction-fit cap for cost-optimized stationery and low-moisture cosmetic applications.
- Flip Top:Hinged lid enabling single-hand operation for convenience-oriented personal care products.
Push-up closures lead on sustainability-aligned positioning, with screw closures retaining the largest installed base in regulated applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized barrier-coating chemists and converting engineers cluster in Germany's industrial heartland, anchoring European innovation capacity for compostable tube formats. North American pulp-to-package integration draws technical talent to southeastern US mill towns. Asian converters recruit formulation specialists from regional polymer science institutes to close the bio-based coating performance gap.
Germany
Personal care brands in Hamburg and Berlin mandate plastic-free primary packaging for deodorant and lip balm lines, converting rigid container volumes to fiber-based push-up formats. The EU Packaging and Packaging Waste Regulation enforces material recovery targets that favor certified compostable tubes. Domestic converters in North Rhine-Westphalia operate integrated coating and winding lines supplying certified post-consumer content tubes to pan-European cosmetics distributors.
United States
Direct-to-consumer cosmetics brands in Brooklyn and Los Angeles specify short-run custom tubes for subscription box and limited-edition launches. FDA barrier performance standards govern oil and moisture resistance claims for cosmetic contact materials. Integrated pulp-to-converted-tube operations in Virginia and Georgia leverage captive kraft fiber supply to serve mass-market personal care manufacturers with cost-optimized standard formats.
France
Premium solid perfume and anhydrous balm brands in Paris and Grasse specify water-based acrylic barrier coatings for home-compostable disposal positioning. REACH chemical migration limits restrict coating chemistry selections for skin-contact applications. Converters in the Auvergne-Rhône-Alpes region supply spiral-wound tubes with embossed and foil-stamped finishes to luxury cosmetics houses.
India
Emerging personal care brands in Mumbai and Bangalore source push-up tubes for waterless shampoo bar and solid sunscreen formats. The PLI scheme for packaging manufacturing attracts paperboard tube investment with production-linked incentives. Domestic converters in Gujarat and Maharashtra install digital printing and precision die-cutting capacity to serve regional brand owners with short-run customization capabilities.
United Kingdom
Niche cosmetics brands in London and Manchester eliminate virgin plastic from primary packaging to meet retailer sustainability scorecards. Extended producer responsibility fee structures penalize non-recyclable packaging formats in England and Scotland. Converters in the Midlands supply crush-resistant spiral-wound constructions with bio-based wax barriers to direct-to-consumer personal care startups.
Push-Up Paperboard Tube Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the push-up paperboard tube value chain. Integrated paperboard mills with captive pulp supply anchor the volume tier, while specialized converters with digital printing and custom die-cutting capabilities capture premium specification pools. Three archetypes dominate: pulp-integrated giants with backward fiber control, mid-scale regional converters with coating formulation expertise, and niche custom shops with short-run agility. Capacity expansion and strategic partnerships with bio-based coating suppliers represent the dominant competitive vectors as brands mandate compostable end-of-life pathways.
Among North American integrated packaging manufacturers, Sonoco Products Company and WestRock occupy positions exemplifying pulp-to-converted-tube scale advantage. Smurfit Kappa Group represents the European converter archetype with structural design specialization. These three entities anchor the competitive landscape across distinct geographic and capability vectors.
| Leading Market Players |
|---|
| Sonoco Products Company |
| WestRock |
| Smurfit Kappa Group |
| Yazoo Mills |
| Valk Industries |
| Ace Paper Tube |
| Pacific Paper Tube |
| Chicago Mailing Tube |
| Marshall Paper Tube |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between home-compostable bio-barrier tubes and conventional wax-coated formats splits both procurement premiums and fiber sourcing networks across European and North American supply chains. Brand owners in Germany and France pay material surcharges for certified compostable coatings while North American mass-market buyers optimize around captive kraft pulp supply chains in the southeastern United States.
Pricing Analysis
Bundled coating-and-certification services command premiums over unbundled tube-only supply. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance grades and compostable certification status. Cost compression in standard formats intensifies as integrated pulp producers leverage captive fiber supply. Mass-market personal care manufacturers exhibit highest price sensitivity, while premium cosmetics brands absorb certification premiums for plastic-free claims.
Supply Chain Analysis
Certification and qualification gating concentrates supply relationships among converters with validated bio-based coating formulations and mass-balance chain-of-custody documentation. Production clusters in Germany, the United States, and India anchor global capacity, with German converters specializing in REACH-compliant cosmetic contact materials. Raw material dependencies center on unbleached kraft pulp, bio-based wax and PLA barrier resins, and water-based acrylic formulations. Single-source vulnerability in specialty coating chemistry creates supply risk. Distribution runs through direct-to-consumer channels and pan-European cosmetics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed manufacturing and certification expenses in India under the PLI scheme for packaging.
For Market Incumbents: Anticipate aluminum laminate substitution threats in oil-rich cosmetic formulations by deepening captive pulp supply and accelerating water-based acrylic barrier R&D. Secure mass-balance certification infrastructure to defend position against emerging Indian converters with cost-advantaged digital printing capacity. For New Entrants and Emerging Players: The premium-to-economy price-point gap in custom short-run tubes opens white-space in Nordic direct-to-consumer subscription cosmetics and Indian waterless personal care brands. Target pharmaceutical solid-dose applications with child-resistant push-up formats as the most penetrable regulated segment. Lead with rapid-turnaround digital printing capabilities to bypass incumbent tooling advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters lack integrated coating formulation expertise and struggle with multi-jurisdiction EPR compliance costs. Long-term viability favors pulp-integrated producers with backward fiber control and certified compostable barrier pipelines. Watch for inflection when EU member states harmonize home-compostable testing protocols, eliminating certification friction and accelerating specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber access insulates margin compression from energy-intensive pulping cost volatility. |
| Bio-Based Barrier Coating Certification | Home-compostable validation unlocks EU Green Deal procurement mandates from German cosmetics brands. |
| Digital Printing Capacity Installation | Short-run agility captures limited-edition cosmetics specifications from Brooklyn and Los Angeles direct-to-consumer channels. |
| Pharmaceutical Solid-Dose Format Development | Child-resistant push-up mechanics address untapped suppository and pessary packaging demand under FDA moisture standards. |
| Multi-Jurisdiction EPR Compliance Infrastructure | Dedicated reporting systems navigate evolving extended producer responsibility fee structures across England, Scotland, and EU member states. |
Research Methodology
Direct dialogue with coating formulation chemists, paperboard converting engineers, cosmetics brand procurement managers, and pharmaceutical packaging regulatory specialists grounded the qualitative foundation. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance registrations, FDA barrier performance guidance documents, and Indian PLI scheme beneficiary disclosures. Bottom-up and top-down triangulation cross-checked converter capacity estimates against brand sustainability commitment timelines.
Bottom-up modeling segmented volume and value across the projection horizon by product type, size tier, end-use application, closure mechanism, and geographic production cluster. CAGRs were derived from trend extrapolation of brand plastic-free packaging commitments and regulatory mandate implementation schedules. Industry-specific forecast inputs included kraft pulp price trajectory assumptions and bio-based coating performance improvement curves.
Caveats apply where EU member state harmonization delays, kraft pulp supply shocks, or aluminum laminate technological breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions on regulatory implementation timing and brand procurement specification velocity. A model refresh is warranted upon material change in home-compostable certification protocol harmonization or bio-based barrier oil-resistance performance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paper Canisters Market