
 India Paper and Paperboard Packaging Market | 2026-2036
India Paper and Paperboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Paper and Paperboard Packaging Market Foresight
A shortage of skilled machine operators for high-speed corrugators and die-cutting lines is reorganizing plant location strategy across the sector. ITC Limited – Paperboards & Specialty Papers Division leverages captive pulp supplies and backward integration into bleached hardwood pulp to sustain margin stability. Parksons Packaging Ltd. anchors its position through specialized pharmaceutical and liquor carton printing capabilities. Smurfit WestRock competes with global design standards and automated box-plant technology transferred from European operations.
India paper and paperboard packaging encompasses kraft linerboard, testliner, folding boxboard, and solid bleached sulphate grades manufactured through multi-ply sheet forming, calendering, and surface coating processes. These materials provide structural protection, printability, and barrier properties for consumer and industrial goods distribution. Cartons and containers dominate volume throughput, with recyclable packaging types drawing capital as Extended Producer Responsibility rules harden post-consumer collection obligations. Coated grades retain premium positioning in cosmetics and electronics end uses where offset lithography demands smooth, bright surfaces.
BIS food-contact safety standards, the Plastic Waste Management Rules, and state-level pollution control board effluent norms collectively determine mill compliance costs and product qualification timelines. FSSAI notification requirements for primary food packaging constrain substrate selection and additive chemistry for domestic suppliers. Stakeholders must track how EPR target escalations and import tariff adjustments on waste paper reshape raw material procurement economics and recycling infrastructure investment priorities.
Market Dynamics
The Indian paper and paperboard packaging sector is undergoing structural reorganization as Extended Producer Responsibility mandates harden post-consumer collection obligations and reshape mill-level capital allocation decisions across Maharashtra and Gujarat manufacturing clusters.
Growth Catalysts
- FMCG Shelf-Ready Carton Demand:Rigid paperboard formats are displacing plastic shrink-wrap in modern retail channels as brands prioritize shelf visibility and stock-keeping efficiency.
- BIS Food-Contact Certification:Mandatory Bureau of Indian Standards compliance for primary food packaging is filtering out informal substrate suppliers and consolidating qualified mill capacity.
- Western India Cluster Density:Integrated pulp-to-box operations in Vapi, Tarapur, and Nagpur reduce logistics drag for pharmaceutical and liquor carton manufacturers serving export corridors.
Market Restraints
- Recovered Paper Import Tariff Volatility:DGFT duty adjustments on OCC and mixed waste paper create raw material cost unpredictability for non-integrated corrugators lacking captive pulp.
- Bleached Hardwood Pulp Supply Concentration:Dependence on Indonesian and Brazilian hardwood pulp imports exposes folding boxboard producers to currency and freight oscillations.
- Coating Chemistry Constraints:FSSAI notification requirements for mineral oil migration limits constrain conventional offset coating formulations in direct food-contact applications.
Strategic Opportunities
- Uttar Pradesh and Madhya Pradesh Underpenetration:Nascent corrugated containerboard demand in Tier-2 and Tier-3 cities offers first-mover positioning before integrated players establish regional box plants.
- Pharmaceutical Serialization Convergence:Track-and-trace mandates combining paperboard cartons with digital watermarking and RFID inlays create premium substrate opportunities.
- State Pollution Control Board Effluent Incentives:Zero liquid discharge compliance subsidies in Gujarat and Tamil Nadu reward closed-loop kraft pulping investments with faster environmental clearance timelines.
Industry Challenges
- High-Speed Corrugator Operator Scarcity:Shortage of technicians trained on 300-meter-per-minute flute laminators and rotary die-cutters forces wage inflation and automation acceleration.
- FSSAI-BIS Dual Certification Timelines:Sequential food-contact safety approvals stretch product qualification cycles to 14-18 months for new substrate entrants.
- Legacy DCS Integration Complexity:Paper mill distributed control system upgrades to accommodate digital printing workflows require parallel operational technology cybersecurity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Paper and Paperboard Packaging Market |
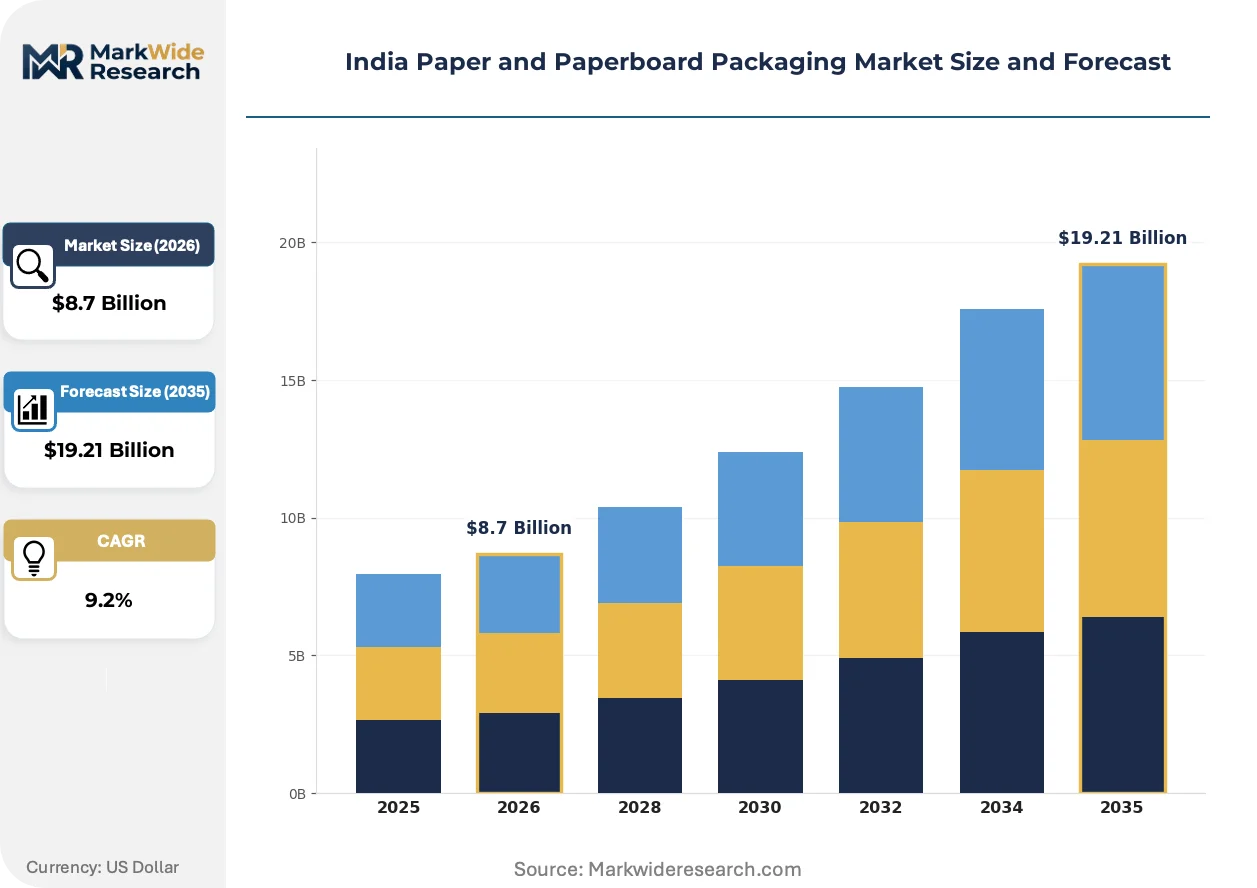
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartons, Containers, Bags, Wraps End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Packaging Type: Recyclable, Biodegradable, Coated, Uncoated Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Parksons Packaging Ltd., Oji Holdings Corp. (Oji India Packaging Pvt. Ltd.), Smurfit WestRock, Andhra Paper Ltd., West Coast Paper Mills Ltd., JK Paper Ltd., ITC Limited – Paperboards & Specialty Papers Division, Mysore Paper Mills Ltd., TCPL Packaging Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Paper and Paperboard Packaging Market Shifts & Advancements
Digital printing workflows and barrier coating chemistries are compressing minimum order quantities and expanding substrate functionality beyond conventional paperboard formats. These shifts are redrawing equipment vendor relationships and mill technology roadmaps.
Water-based barrier coatings incorporating bio-wax and polylactic acid laminates are supplanting conventional polyethylene extrusion in chilled and frozen food cartons. Dairy and ready-to-eat meal brands in Mumbai and Bangalore are piloting these formats at 5,000-10,000 unit runs. This transition is compressing lead times from six weeks to seventy-two hours for seasonal promotional packaging.
Plastic Waste Management Rules amendments and state-level EPR target escalations are mandating 30% recycled content thresholds in paper-based primary packaging. FSSAI is aligning notification requirements with these thresholds, creating dual compliance checkpoints for domestic mills. Pharmaceutical and cosmetics cartons face the steepest reformulation timelines due to existing brand equity in high-brightness substrates.
Brand procurement teams are consolidating vendor panels from twelve to four qualified converters per category, prioritizing integrated substrate-to-print capabilities over pure-play box manufacturers. This concentration is visible in Maharashtra's FMCG corridor where ITC and Parksons anchor multi-year framework agreements. Tier-1 suppliers are absorbing design and pre-press functions previously handled by brand marketing agencies.
India Paper and Paperboard Packaging Market Segmentation
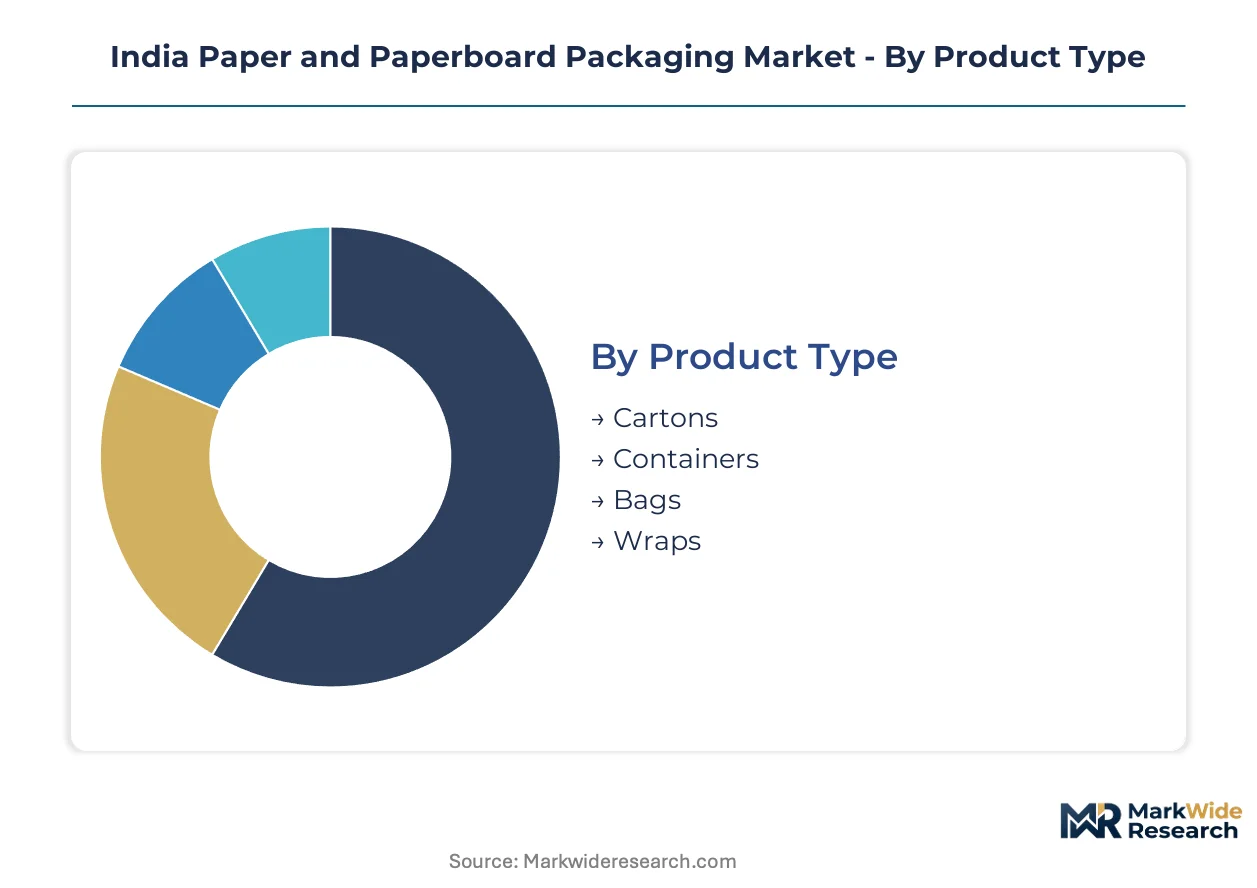
Segmentation in India's paper and paperboard packaging market reveals how substrate specifications, end-use compliance requirements, and channel economics fragment procurement decisions across Maharashtra-Gujarat manufacturing clusters and export corridors.
Product Type:
Domestic consumption dominates cartons and containers for FMCG and pharmaceutical applications, while bags and wraps serve export-led agro-commodity and textile packaging from Gujarat ports.
- Cartons:Folding boxboard and solid bleached sulphate grades provide structural rigidity and premium printability for pharmaceutical and liquor packaging. Demand concentrates in Mumbai-Pune and Vapi-Tarapur corridors where ITC and Parksons operate integrated substrate-to-print facilities, driven by BIS food-contact certification mandates filtering out informal suppliers.
- Containers:Corrugated fiberboard boxes in single-wall, double-wall, and triple-wall flute configurations protect industrial and consumer goods through distribution. Maharashtra's pharmaceutical exporters and Gujarat's chemical processors anchor volume, constrained by DGFT tariff volatility on recovered paper imports that squeezes non-integrated corrugator margins.
- Bags:Multiwall kraft paper sacks with pasted valve or open-mouth construction handle cement, chemicals, and food grains. Domestic infrastructure and construction activity in Uttar Pradesh and Madhya Pradesh drives regional production scaling.
- Wraps:Greaseproof and glassine papers provide moisture barrier for food service and industrial interleaving. Quick-service restaurant chains in Bangalore and Hyderabad pilot compostable wrap formats under EPR compliance pressure.
Cartons hold the largest share; momentum sits with containers as e-commerce fulfillment demands expand corrugated volume.
End User:
Cost-tier segmentation separates premium compliance-heavy applications from price-sensitive bulk packaging, with certification requirements and volume scale determining supplier qualification.
- Food & Beverage:Primary and secondary packaging for dairy, ready-to-eat meals, and beverages demands FSSAI-compliant substrates with mineral oil migration controls. Mumbai and Bangalore brands pilot water-based barrier coatings at 5,000-10,000 unit promotional runs, compressing lead times from six weeks to seventy-two hours.
- Healthcare:Pharmaceutical cartons require serialization-ready substrates compatible with digital watermarking and track-and-trace mandates. Export-oriented producers in Goa and Sikkim face steepest reformulation timelines as EPR thresholds harden.
- Consumer Goods:Cosmetics and personal care packaging prioritizes coated grades with offset lithography compatibility for shelf differentiation. Premium brightness specifications conflict with 30% recycled content mandates.
- Electronics:Anti-static corrugated and molded pulp cushions protect smartphones and appliances through distribution. Tamil Nadu's electronics manufacturing clusters near Chennai drive specialized die-cutting demand.
Food & Beverage commands volume leadership; Healthcare exhibits steepest expansion trajectory as serialization convergence creates premium substrate opportunities.
Packaging Type:
Margin structure varies sharply across certification tiers, with EPR compliance costs and coating chemistry investments separating qualified mill production from commodity supply.
- Recyclable:Unbleached kraft and testliner grades with post-consumer fiber content meet Plastic Waste Management Rules thresholds. Collection infrastructure gaps in Tier-2 cities constrain actual recovery rates despite regulatory mandates.
- Biodegradable:PLA-laminated and bio-wax coated formats target chilled dairy and frozen food applications. Pilot programs with organized retail chains in Delhi-NCR test compostability claims under FSSAI notification alignment.
- Coated:Clay-coated and polyethylene-extruded boards provide moisture barrier and print gloss for cosmetics and electronics. Mineral oil migration limits are forcing coating reformulation investments.
- Uncoated:Natural kraft and unbleached grades serve cost-sensitive industrial and agricultural packaging. Price competition from recycled molded pulp alternatives intensifies in export markets.
Recyclable formats anchor current volume; biodegradable alternatives are gaining share fastest as dairy and ready-to-eat brands pilot compostable formats.
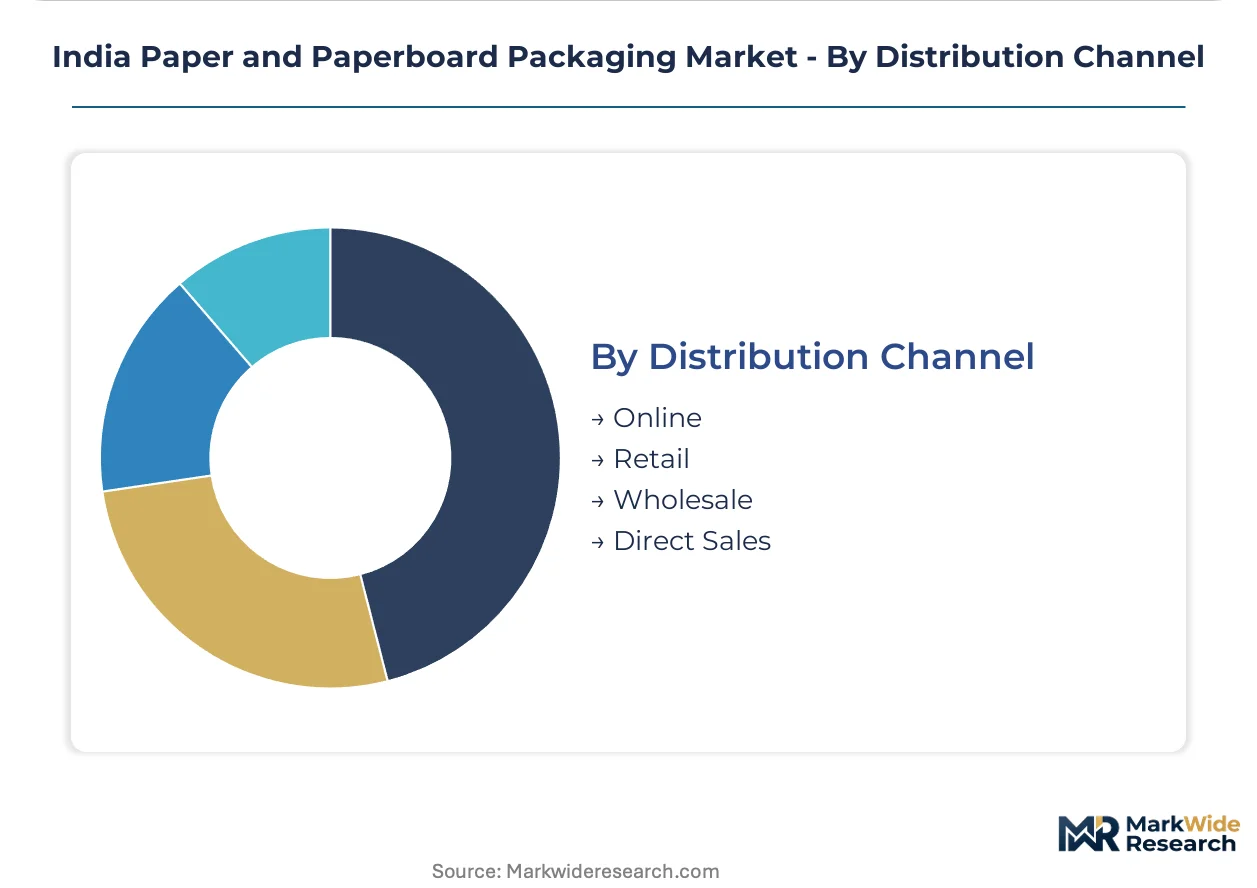
Distribution Channel:
Customer-type segmentation distinguishes integrated direct procurement by FMCG majors from fragmented wholesale supply to small converters and regional box plants.
- Online:E-commerce marketplace sales of standardized carton and corrugated specifications serve small converters and Tier-3 manufacturers. Platform logistics favor lightweight, volume-efficient formats.
- Retail:Stationery and packaging material distributors stock standard sheet sizes for immediate availability. Maharashtra and Gujarat distributor networks concentrate near integrated mill zones.
- Wholesale:Bulk traders aggregate demand from non-integrated corrugators lacking direct mill relationships. Price transparency from OCC import tariff fluctuations compresses trading margins.
- Direct Sales:Multi-year framework agreements between ITC, Parksons, and FMCG majors consolidate vendor panels from twelve to four qualified converters per category, absorbing design and pre-press functions.
Direct Sales captures the highest value per ton; Online channels are expanding most quickly as small converters bypass traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat consume paperboard packaging differently from other Indian states, with western India favoring high-value pharmaceutical and liquor cartons while northern and southern markets prioritize cost-optimized corrugated for e-commerce and agro-commodity distribution.
Maharashtra
Mumbai-Pune pharmaceutical exporters and organized retail chains drive folding boxboard consumption for track-and-trace compliant cartons. BIS certification mandates for food-contact materials filter substrate suppliers serving dairy brands in Nashik and Nagpur. Vapi-Tarapur integrated pulp-to-box clusters anchor western India's manufacturing corridor with captive bleached hardwood pulp supplies.
Gujarat
Chemical processors and agro-commodity exporters in Ahmedabad and Surat anchor corrugated containerboard demand for domestic and export markets. State Pollution Control Board zero liquid discharge subsidies accelerate closed-loop kraft pulping investments with faster environmental clearance timelines. Hazira port proximity enables integrated mills to serve Middle East and African export corridors.
Karnataka
Bangalore's quick-service restaurant chains and ready-to-eat meal brands pilot water-based barrier coatings and bio-wax laminates at compressed 5,000-10,000 unit promotional runs. FSSAI notification alignment with Plastic Waste Management Rules drives compostable format adoption in chilled dairy applications. Electronics manufacturing clusters near Chennai draw specialized anti-static corrugated from cross-border Tamil Nadu suppliers.
Tamil Nadu
State Pollution Control Board effluent incentives reward closed-loop kraft pulping investments alongside Gujarat, creating competitive parity for zero liquid discharge compliance. Chennai's electronics manufacturing clusters demand precision die-cut molded pulp cushions for smartphone distribution. Coimbatore textile exporters utilize multiwall kraft sacks for yarn and fabric shipment consolidation.
Delhi-NCR
Organized retail chains and dairy cooperatives in the national capital region test biodegradable PLA-laminated formats under EPR compliance pressure. Collection infrastructure gaps in surrounding Tier-2 cities constrain actual post-consumer recovery rates despite regulatory mandates. Sonipat and Faridabad box plants serve as distribution nodes for Uttar Pradesh underpenetration strategies.
India Paper and Paperboard Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's paperboard packaging structure. ITC Limited and West Coast Paper Mills operate captive pulp facilities that buffer margin volatility from imported hardwood price swings. Parksons Packaging and TCPL Packaging anchor specialized pharmaceutical and liquor carton segments. Competitive moves concentrate on backward integration into bleached pulp and automated box-plant technology transfers.
Among integrated domestic leaders, ITC Limited – Paperboards & Specialty Papers Division represents the captive pulp archetype with in-house bleached hardwood production. Parksons Packaging Ltd. and TCPL Packaging Ltd. exemplify specialized substrate-to-print capabilities serving compliance-heavy pharmaceutical and liquor segments. Smurfit WestRock occupies a position reflecting global design standards and European-originated automated box-plant technology.
| Leading Market Players |
|---|
| Parksons Packaging Ltd. |
| Oji Holdings Corp. (Oji India Packaging Pvt. Ltd.) |
| Smurfit WestRock |
| Andhra Paper Ltd. |
| West Coast Paper Mills Ltd. |
| JK Paper Ltd. |
| ITC Limited – Paperboards & Specialty Papers Division |
| Mysore Paper Mills Ltd. |
| TCPL Packaging Ltd. |
| Others |
Supply & Pricing Matrix
Water-based barrier coatings displacing polyethylene extrusion in chilled food cartons are simultaneously redrawing mill procurement geographies around bio-wax and polylactic acid suppliers while compressing pricing premiums previously captured by conventional moisture-barrier substrates.
Pricing Analysis
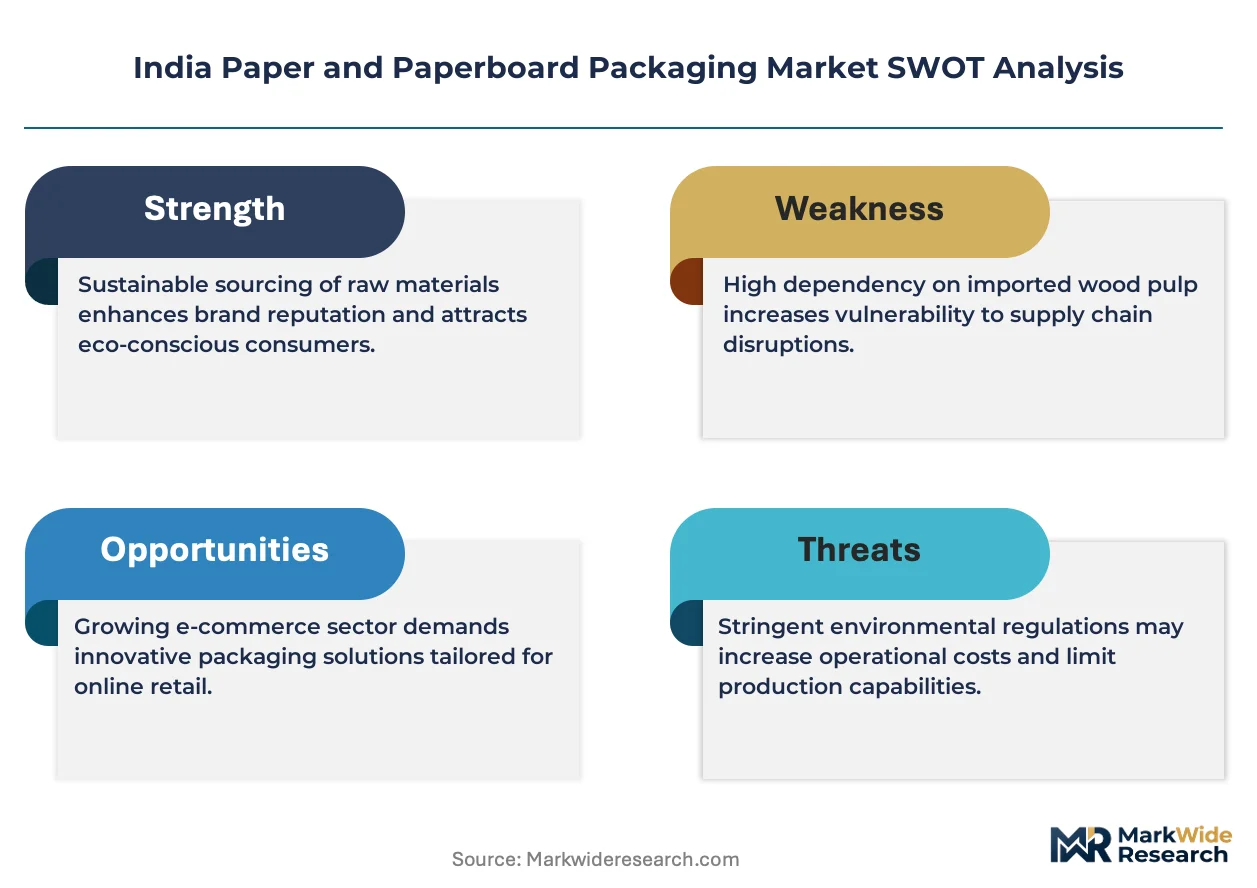
Long-term offtake agreements between ITC, Parksons, and FMCG majors anchor pricing stability for folding boxboard and solid bleached sulphate grades, while spot-market transactions dominate recovered paper procurement for non-integrated corrugators. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-BIS dual-certified substrates from single-compliant and uncertified alternatives. Cost compression in testliner and kraft linerboard is intensifying because DGFT duty volatility on OCC imports squeezes converter margins without captive pulp integration. Small regional corrugators in Uttar Pradesh and Madhya Pradesh exhibit highest price sensitivity due to limited volume leverage and informal supplier relationships.
Supply Chain Analysis
Indonesian and Brazilian bleached hardwood pulp exports through Hazira and Mumbai ports constitute a chokepoint that exposes folding boxboard producers to currency and freight oscillations. Geographic supply concentration centers on Indonesia, Brazil, and domestic captive pulp operations at ITC and West Coast Paper Mills. Raw material dependencies rest on imported hardwood pulp, recovered OCC from domestic collection networks, and bio-wax coating chemistries. Tariff exposure on DGFT waste paper duty adjustments creates margin unpredictability for non-integrated players. Distribution runs through direct mill-to-converter framework agreements for qualified suppliers, with wholesale traders aggregating fragmented regional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as FMCG procurement teams consolidate vendor panels from twelve to four qualified converters per category, shifting negotiation leverage toward volume-anchored framework agreements and away from fragmented spot-market sourcing.
For Market Incumbents: Compound captive pulp advantages by accelerating zero liquid discharge investments in Gujarat and Tamil Nadu to capture faster environmental clearance timelines before competitors replicate closed-loop kraft pulping. Deepen substrate-to-print integration by absorbing design and pre-press functions previously handled by brand marketing agencies, creating switching costs against emerging digital-print specialists. Defend against water-based barrier coating disruptors by locking multi-year supply contracts with bio-wax and PLA laminate suppliers before raw material scarcity elevates input costs.
For New Entrants and Emerging Players: BIS certification fast-track investments in food-contact safety standards open qualification pathways into dairy and ready-to-eat meal segments where incumbent capacity is constrained by FSSAI notification alignment timelines. Target corrugated containerboard demand in Tier-2 and Tier-3 cities across Uttar Pradesh and Madhya Pradesh before integrated players establish regional box plants. Pursue pharmaceutical serialization convergence opportunities by developing digital watermarking-compatible substrates for track-and-trace mandates, leveraging 14-18 month dual certification delays facing new substrate entrants.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale corrugators with established OCC collection networks and proximity to underpenetrated northern and central Indian markets, where first-mover positioning precedes integrated mill expansion. Long-term viability over the projection horizon hinges on regulatory compliance infrastructure rather than pure capacity scale, given escalating EPR thresholds and FSSAI notification requirements. Monitor DGFT tariff adjustment announcements as the critical inflection signal for raw material cost trajectories and non-integrated player margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pulp Integration | Backward integration into bleached hardwood pulp buffers margin stability against Indonesian and Brazilian import volatility. |
| Zero Liquid Discharge Compliance | Closed-loop kraft pulping investments in Gujarat and Tamil Nadu accelerate environmental clearance timelines under state subsidy programs. |
| Digital Printing Workflow Adoption | Automated box-plant technology compresses minimum order quantities from six weeks to seventy-two hours for promotional packaging. |
| Water-Based Barrier Coating Transition | Bio-wax and PLA laminate formulations displace polyethylene extrusion in chilled dairy applications under FSSAI mineral oil migration limits. |
| Serialized Pharmaceutical Substrate Development | Track-and-trace compatible cartons with digital watermarking and RFID inlays capture premium positioning in export-oriented Goa and Sikkim corridors. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with paper mill operations directors, FMCG packaging procurement heads, pharmaceutical regulatory affairs managers, and corrugated converter plant engineers; and secondary validation through BIS certification databases, FSSAI notification records, DGFT customs duty circulars, and state pollution control board effluent compliance filings. Bottom-up triangulation across substrate production volumes, converter capacity utilization, and end-use demand patterns was cross-referenced with top-down macroeconomic indicators and trade flow analysis.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, end-user industry vertical, packaging certification tier, and distribution channel structure, with particular attention to Maharashtra-Gujarat cluster density versus northern and southern market underpenetration. CAGRs were derived from regression analysis of historical production data, capacity expansion announcements, and regulatory compliance cost escalations. Industry-specific inputs incorporated EPR target escalation schedules, BIS certification backlog estimates, and recovered paper import tariff sensitivity scenarios.
Underlying assumptions cover sustained FMCG shelf-ready carton adoption, DGFT duty stability within historical bands, and state-level environmental clearance timeline consistency, with deviation risk concentrated in FSSAI notification alignment delays and bio-wax coating chemistry scale-up bottlenecks. Practitioners should keep alternative scenarios live as EPR threshold enforcement intensity and import substitution policy direction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market