
 Paperboard Partition Market | 2026-2036
Paperboard Partition Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Partition Market Analytics
Multi-source procurement among corrugated packaging buyers is broadening as brand owners diversify supply risk across fiber-based protective formats. Smurfit Kappa Group leverages its integrated European containerboard network to sustain high-volume partition output for automotive and electronics clients. Mondi Group anchors its position through specialty kraftliner grades engineered for die-cut partition applications. WestRock Company competes on North American boxboard integration, controlling pulp-to-partition cost structures across multiple end-use channels.
Paperboard partition denotes a corrugated or solid fiber insert engineered with flute profiles ranging from E-flute to triple-wall configurations, designed to compartmentalize and cushion products within outer shipping containers against compression and impact damage. The primary commercial purpose centers on eliminating secondary wrapping materials while maintaining item separation during distribution. Double wall and triple wall configurations dominate heavy-goods applications where stacking strength requirements exceed single-wall capabilities, while die-cut formats capture premium electronics and pharmaceutical segments where dimensional precision protects high-value components. Thickness specifications at 3mm and 5mm align with consumer goods and foodservice tray applications where partition depth must accommodate variable product heights without excess material bulk.
FDA food-contact substance regulations and EU REACH restrictions on heavy metals in recycled fiber streams directly shape material sourcing decisions for food and beverage partition applications. EPA industrial effluent guidelines and OSHA dust exposure limits govern pulping and converting operations, influencing capital allocation toward closed-loop water systems and automated cutting equipment. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as these programs increasingly assign end-of-life collection costs to original packaging suppliers rather than downstream recyclers.
Market Dynamics
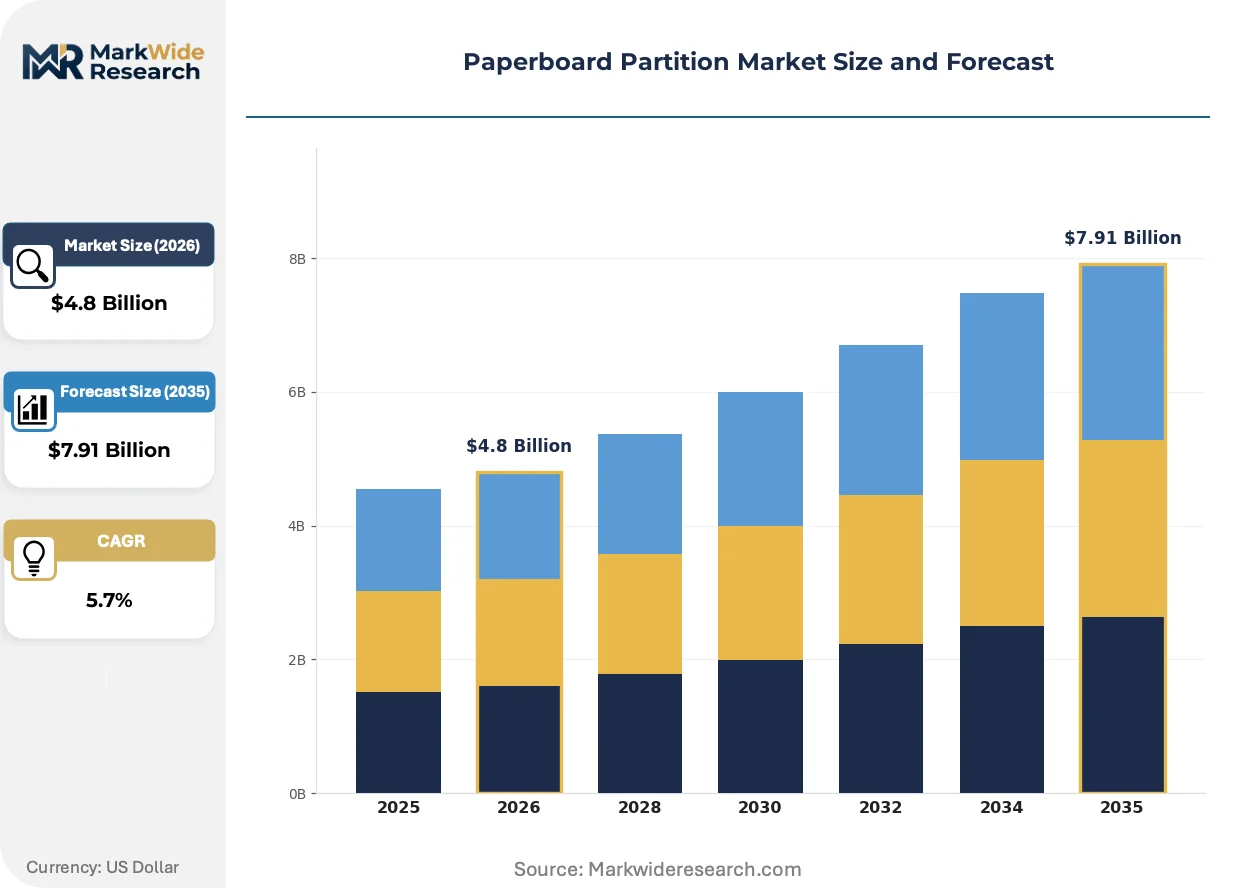
EU REACH restrictions on heavy metals in recycled fiber streams are forcing material sourcing restructuring across food-contact partition applications, while India's pharmaceutical export corridor tightens cold-chain specifications.
Growth Catalysts
- E-commerce fulfillment density:Electronics manufacturers in Asia-Pacific are expanding protective packaging procurement as direct-to-consumer shipment volumes strain legacy cushioning methods.
- REACH compliance mandates:EU regulations on recycled fiber content are accelerating certified partition adoption among exporters targeting European consumer markets.
- Die-cut precision technology:Advanced laser scoring systems enable micron-level tolerances for pharmaceutical vial protection, displacing molded pulp alternatives in high-value segments.
Market Restraints
- Containerboard price volatility:OCC (old corrugated containers) supply fluctuations in North American recycling streams compress converter margins during demand spikes.
- Triple-wall capacity concentration:Heavy-goods partition production clusters among integrated European mills, limiting spot-market availability for regional converters.
- Plastic corrugated substitution:Reusable PP (polypropylene) partitions capture closed-loop automotive logistics, eroding fiber-based share in returnable packaging programs.
Strategic Opportunities
- India pharmaceutical corridor expansion:Cold-chain partition specifications for temperature-sensitive biologics exports create premium positioning for validated insulating fiber formats.
- EU Green Deal packaging mandates:Extended producer responsibility frameworks assign end-of-life collection costs to suppliers, favoring recyclable paperboard over multi-material alternatives.
- Smart packaging convergence:Integration of RFID-enabled partition tracking with inventory management systems is modularizing logistics visibility for high-value electronics.
Industry Challenges
- Die-cutting automation talent gap:Converters face shortages of technicians capable of programming CNC knife systems for complex pharmaceutical tray geometries.
- FDA food-contact certification timelines:Substance notification reviews for recycled fiber additives extend product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Partition Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die Cut End User: Electronics, Food & Beverage, Consumer Goods, Pharmaceuticals Thickness: 1mm, 2mm, 3mm, 5mm Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Smurfit Kappa Group, International Paper Company, Mondi Group, WestRock Company, DS Smith plc, Stora Enso Oyj, Nippon Paper Industries Co., Ltd., NEFAB GROUP, RTS Packaging, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Partition Market Evolving Landscape
Active reshaping in paperboard partition markets centers on precision manufacturing convergence with regulatory compliance automation, compressing traditional specification-to-production cycles while elevating performance thresholds for protective applications.
Micro-flute E-flute and F-flute configurations are penetrating electronics packaging as OEMs demand thinner protective profiles to maximize cubic utilization in parcel networks. Smartphone and laptop manufacturers in Taiwan and South Korea specify these formats for direct-to-consumer shipments. The technology is modularizing warehouse footprint requirements by enabling denser pallet configurations without sacrificing drop-test performance.
EU REACH Annex XVII restrictions on cadmium and lead in recycled paperboard are compelling Asian exporters to segregate fiber streams and implement batch testing protocols. The regulation forces dual-track sourcing strategies—virgin kraftliner for EU-bound pharmaceutical partitions, mixed recovered fiber for domestic consumer goods. Indian converters serving European generic drug markets bear the steepest compliance cost escalation.
Consolidated procurement among multinational CPG brands is compressing supplier rosters from regional fragmentation toward approved-vendor lists with integrated quality systems. Tier-one food and beverage manufacturers now mandate ISO 22000 certification and real-time production data access as baseline qualification criteria. This concentration is most pronounced in Germany's bakery and confectionery clusters, where three buying groups control 60% of partition volume.
Paperboard Partition Market Segmentation
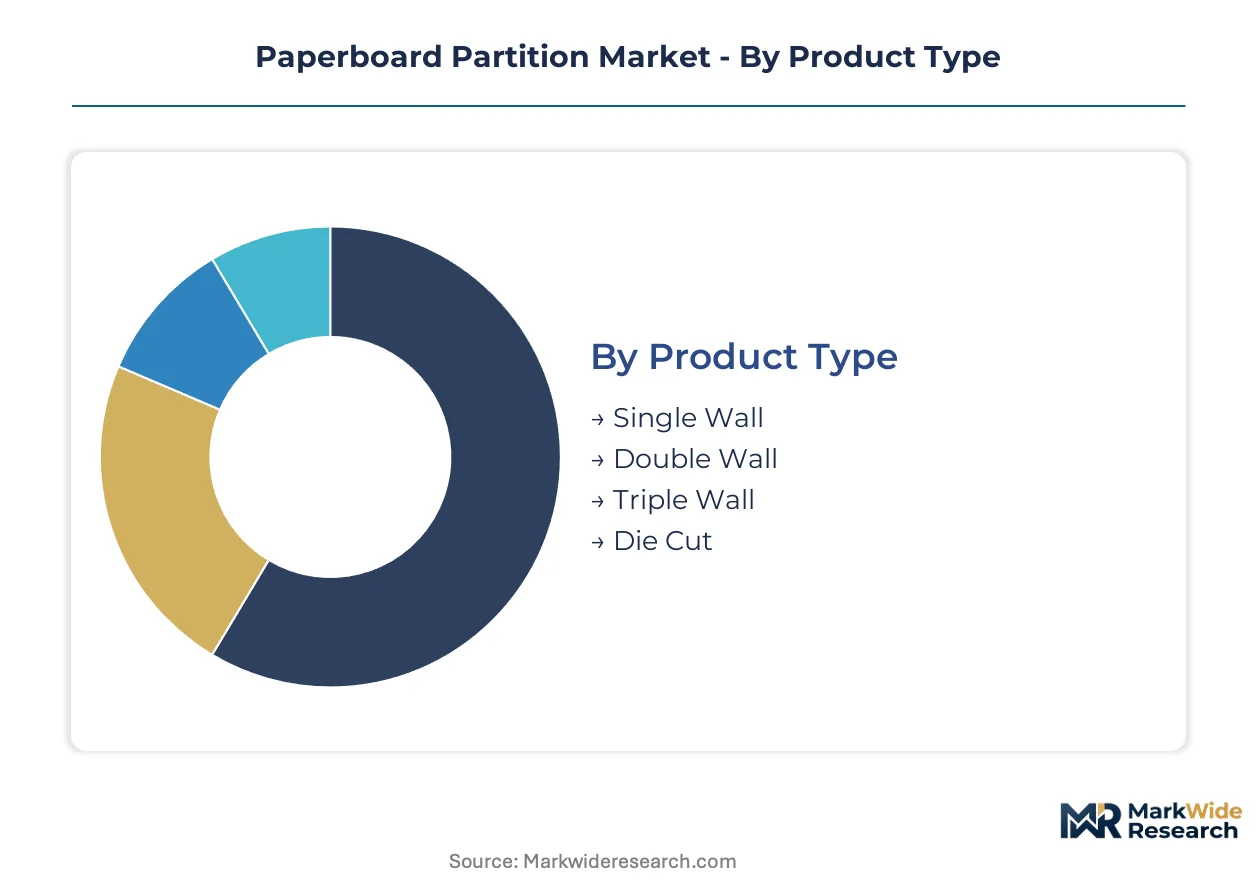
Paperboard partition specifications diverge sharply between commodity logistics and precision protective applications. Thickness tolerances, flute geometry, and converting complexity create tiered performance bands that command distinct pricing positions across end-use channels.
Product Type:
Volume production clusters in single-wall formats while premium positioning concentrates in precision-engineered configurations.
- Single Wall:Single flute layer construction using B-flute or C-flute profiles delivers baseline cushioning for consumer goods and lightweight industrial components. FMCG manufacturers in India's pharmaceutical export corridor specify this format for high-velocity domestic distribution where unit economics dominate procurement decisions.
- Double Wall:Dual flute layers with BC-flute combinations provide enhanced stacking strength for medium-weight electronics and automotive parts. Taiwan's semiconductor packaging suppliers favor this configuration for wafer cassette shipments requiring calibrated compression resistance during ocean freight.
- Triple Wall:Heavy-goods format serving industrial machinery and bulk liquid containers where load-bearing requirements exceed standard corrugated capabilities.
- Die Cut:Precision-converted formats with laser-scored edges for pharmaceutical vial trays and smartphone component protection.
Today's leader: Single Wall. Tomorrow's challenger: Die Cut.
End User:
Application requirements reshape material specifications from food-contact compliance to electrostatic discharge protection.
- Electronics:Anti-static coatings and micro-flute precision protect semiconductors, displays, and battery cells during global distribution. South Korean smartphone OEMs specify E-flute partitions with conductive additives for direct-to-consumer parcel networks.
- Pharmaceuticals:Validated cold-chain partitions with thermal insulation properties serve temperature-sensitive biologics exports. Indian generic drug manufacturers face EU REACH compliance costs for recycled fiber segregation in vial tray applications.
- Food & Beverage:FDA food-contact substance regulations govern recycled fiber content in bakery and confectionery tray inserts.
- Consumer Goods:Standard-grade partitions for apparel, cosmetics, and household products where aesthetic presentation requirements are minimal.
Electronics commands premium pricing through specification intensity. Pharmaceuticals is climbing the fastest on regulatory compliance barriers.
Thickness:
Dimensional precision determines partition depth relative to product height and container cubic utilization.
- 1mm:Micro-flute F-flute and N-flute profiles for ultra-thin electronics packaging where space optimization overrides cushioning depth.
- 2mm:Intermediate specification capturing small appliance and premium cosmetic applications.
- 3mm:Standard partition depth for consumer goods and foodservice trays accommodating variable product heights without excess bulk. German bakery clusters specify this format for frozen pastry distribution.
- 5mm:Maximum standard thickness for heavy-goods applications requiring substantial compression resistance and drop-test performance.
3mm thickness anchors current procurement volumes. 1mm micro-flute formats are gaining share fastest in electronics densification.
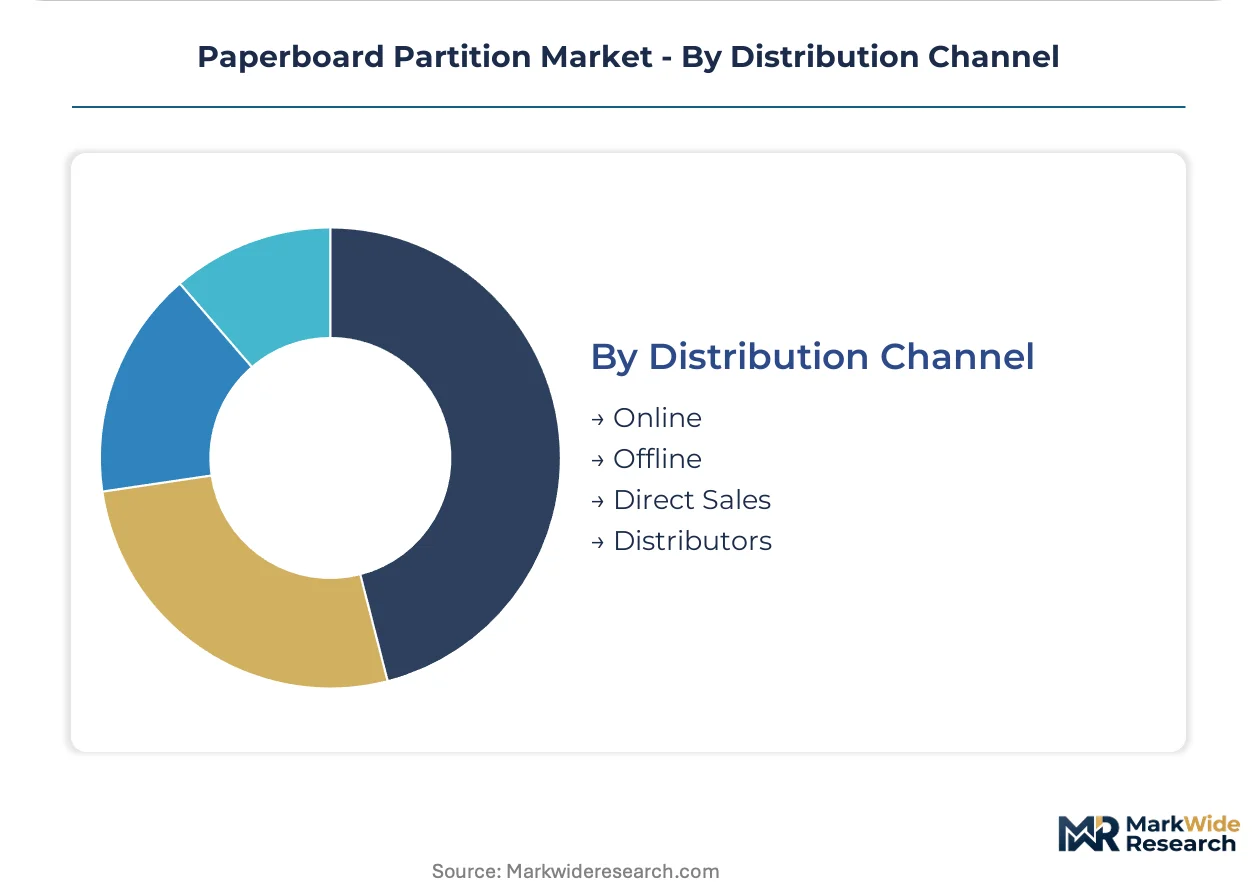
Distribution Channel:
Channel selection reflects order scale, specification complexity, and converter relationship depth.
- Direct Sales:Integrated mill-to-brand relationships for high-volume automotive and electronics programs with dedicated quality systems.
- Distributors:Regional inventory positioning for mid-tier consumer goods manufacturers requiring rapid replenishment.
- Online:Digital procurement platforms serving small-batch pharmaceutical and specialty food producers with standardized specifications.
- Offline:Traditional converter relationships for custom die-cut applications requiring technical consultation and sampling iterations.
Direct Sales captures the largest contract value. Online channels are expanding most quickly in SME pharmaceutical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and bakery clusters anchor paperboard partition procurement across precision die-cut and foodservice tray specifications. The country's integrated containerboard mills supply high-volume automotive programs while REACH compliance mandates reshape export-oriented converter operations.
Germany
Automotive OEMs in Baden-Württemberg specify triple-wall partitions for powertrain component shipments. ECHA REACH Annex XVII restrictions on cadmium in recycled fiber force dual-track sourcing strategies. Stuttgart's supplier ecosystem concentrates die-cutting automation investments for just-in-time automotive logistics.
United States
Food and beverage manufacturers drive FDA food-contact grade partition demand for bakery and confectionery distribution. EPA industrial effluent guidelines govern pulping operations in the Southeast containerboard corridor. Chicago's logistics hub anchors Midwest procurement for consumer goods fulfillment networks.
China
Electronics OEMs in the Pearl River Delta specify micro-flute E-flute partitions for smartphone direct-to-consumer shipments. GB standards on packaging recyclability accelerate certified fiber adoption. Shenzhen's converter base scales laser-scoring capacity for precision electronics protection.
India
Pharmaceutical exporters in Gujarat and Maharashtra face EU REACH compliance costs for recycled fiber segregation in vial tray applications. CDSCO cold-chain validation requirements tighten specifications for temperature-sensitive biologics. Ahmedabad's generic drug manufacturers invest in batch testing protocols for European market access.
South Korea
Semiconductor and display manufacturers specify anti-static coated partitions for wafer and panel shipments. MFDS pharmaceutical packaging regulations align with EU standards for export-bound products. Gyeonggi-do's electronics cluster drives micron-level die-cut tolerance requirements.
Paperboard Partition Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty die-cut and pharmaceutical-grade certifications. The market structures around three tiers: integrated European containerboard groups controlling high-volume automotive supply, North American boxboard converters serving food-contact applications, and regional Asian specialists capturing electronics micro-flute demand. Two archetypes dominate: backward-integrated mills with captive pulp supply, and precision converters with CNC die-cutting technology. Competitive moves center on capacity expansion in triple-wall heavy-goods formats and strategic partnerships for pharmaceutical validation capabilities.
Within the integrated mill tier, Smurfit Kappa Group and Mondi Group exemplify European containerboard dominance through network scale. WestRock Company anchors North American positioning through boxboard integration. These three represent distinct geographic supply architectures rather than overlapping market contests.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| International Paper Company |
| Mondi Group |
| WestRock Company |
| DS Smith plc |
| Stora Enso Oyj |
| Nippon Paper Industries Co., Ltd. |
| NEFAB GROUP |
| RTS Packaging, LLC. |
| Others |
Value Network & Pricing Analysis
EU REACH compliance mandates on recycled fiber heavy metal content are forcing Indian pharmaceutical exporters to dual-source virgin kraftliner for European-bound vial trays, compressing converter margins and reshaping procurement cost structures across the export corridor.
Pricing Analysis
OCC pulp cost pass-through dominates transactional pricing for commodity single-wall formats, while FDA food-contact certification tiers create three-tier pricing structure across premium, standard, and economy levels. Die-cut precision specifications for semiconductor wafer protection command substantial premiums over standard bakery tray inserts. Pricing pressure stems from containerboard volatility in North American recycling streams, with integrated mills least exposed and regional converters most vulnerable. FMCG manufacturers in India exhibit highest price sensitivity; South Korean electronics OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
ISO 22000 and EU REACH certification gating concentrates qualified supply among integrated European containerboard groups and select Asian precision converters. Production gravity centers on Germany, China, and the United States for high-volume automotive and foodservice applications. Raw material flows draw from Swedish bleached kraft pulp, American OCC recovery streams, and Indonesian mixed tropical hardwood. Single-source vulnerability runs through triple-wall heavy-goods capacity clustered in European mills. Distribution runs through direct mill-to-brand relationships for automotive programs, with distributor networks serving mid-tier consumer goods replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU REACH compliance costs in India create cost-advantaged positioning for German and South Korean converters serving European pharmaceutical markets.
For Market Incumbents: Hedge against plastic corrugated substitution in automotive returnable packaging by accelerating anti-static coating R&D and securing long-term kraftliner offtake agreements. Backward integration into virgin pulp supply insulates margin compression from OCC volatility. Prioritize die-cutting automation investments to offset technician shortages in pharmaceutical tray geometries.
For New Entrants and Emerging Players: Small-batch pharmaceutical producers in India's Gujarat corridor represent an underserved buyer archetype seeking validated cold-chain partitions without minimum order thresholds. White-space exists in RFID-enabled smart partition modules for electronics logistics visibility. A digital-first go-to-market angle through procurement platforms bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision converters holding pharmaceutical-grade certifications and CNC die-cutting capabilities. Long-term viability hinges on regulatory compliance automation rather than commodity scale. Watch for inflection in EU extended producer responsibility implementation timelines, which would accelerate recyclable fiber demand against multi-material alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Automation Investment | Indian exporters reduce batch testing costs for European pharmaceutical market access. |
| Die-Cutting Capacity Expansion | Taiwanese electronics OEMs secure micron-level tolerance supply for semiconductor shipments. |
| Anti-Static Coating Development | South Korean battery manufacturers specify conductive fiber protection for lithium cell distribution. |
| Cold-Chain Validation Partnership | Generic drug exporters meet CDSCO thermal specification requirements for biologics exports. |
| Smart Packaging Module Integration | German automotive suppliers embed RFID tracking for powertrain component logistics visibility. |
Research Methodology
Direct dialogue with containerboard mill procurement directors, pharmaceutical packaging engineers, electronics supply chain managers, and corrugated converter operations heads grounded qualitative findings. Secondary validation drew from ECHA REACH guidance documents, FDA food-contact substance notifications, EPA industrial effluent compliance records, and trade flow data from major fiber-exporting nations. Bottom-up volume estimates triangulated against top-down containerboard consumption models.
Segment-level value outputs across product type, end-use industry, thickness specification, and distribution channel were generated through the analytical framework. CAGRs were derived from regression analysis against corrugated packaging demand drivers and electronics shipment velocity indices. Forecast inputs incorporated EU Green Deal packaging mandate implementation schedules and Indian pharmaceutical export growth trajectories.
Underlying measurement precision varies by segment; die-cut pharmaceutical and electronics specifications carry tighter precision than commodity single-wall consumer goods. Forecasts reflect assumptions regarding regulatory enforcement consistency and fiber recycling stream stability. A model refresh is warranted upon material change in EU extended producer responsibility cost allocation frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market