
 Paper Bottles Market | 2026-2036
Paper Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Bottles Market Outlook
Barrier coating innovation is tilting the paper bottle technology stack away from conventional polyethylene linings toward mineral and bio-based alternatives. Paboco leverages its Danish R&D hub to refine fiber molding precision for carbonated drinks. Frugalpac anchors production flexibility through its patented machine technology that allows brands to manufacture bottles on-site. Notpla differentiates with seaweed-derived coatings that eliminate synthetic barriers entirely.
Paper bottles consist of molded fiber bodies with specialized interior coatings designed to resist liquid penetration, typically achieving burst strengths above 150 kPa and moisture vapor transmission rates below 10 g/m²/day depending on barrier formulation. Their primary commercial purpose is to replace petroleum-based rigid packaging in shelf-stable and chilled liquid applications. Beverage containers lead volume deployment due to compatibility with existing filling lines, while barrier technologies command the widest margin pools as coating patents determine shelf-life performance. Personal care bottles represent a faster-growing segment as cosmetics brands pursue plastic-free claims.
The EU Green Deal and REACH frameworks restrict conventional plastic additives in food-contact materials, while FDA evaluates fiber-based packaging for expanded beverage approvals in the United States. These regulatory trajectories directly shape which barrier chemistries achieve commercial scale and where capital deploys for manufacturing capacity. Stakeholders must monitor coating migration test results and compostability certification timelines to time capacity investments against regulatory clearance milestones.
Market Dynamics
Barrier coating chemistry is the decisive pivot point in paper bottle commercialization, with mineral and bio-based formulations displacing conventional polyethylene linings and determining which products achieve shelf-stable performance.
Growth Catalysts
- EU Green Deal enforcement:Single-use plastics directives mandate fiber substitution in beverage packaging across Germany, France, and the United Kingdom, creating immediate compliance-driven demand.
- Carbonated drink compatibility breakthroughs:Refined fiber molding precision now withstands internal pressures above 150 kPa, opening beer and sparkling water segments previously closed to paper alternatives.
- Cosmetics plastic-free claims:Personal care brands pursue fiber-based bottles to satisfy retailer sustainability scorecards and consumer-facing environmental commitments.
Market Restraints
- Barrier coating cost premiums:Seaweed-derived and mineral barrier formulations command raw material multiples above synthetic polyethylene, compressing margins at price-sensitive volume tiers.
- Equipment concentration:Precision fiber molding machinery suppliers cluster in Northern Europe, creating lead time vulnerabilities and capital access constraints for new entrants.
- Shelf-life performance gaps:Current bio-based barriers achieve moisture vapor transmission rates near but not below the 10 g/m²/day threshold required for extended ambient distribution.
Strategic Opportunities
- On-site manufacturing adoption:Brands deploying patented machine technology at bottling facilities eliminate transport-stage damage and reduce working capital requirements.
- Chilled juice and dairy expansion:Shorter distribution cycles and cold-chain logistics relax barrier performance requirements, enabling faster commercialization than shelf-stable categories.
- Compostability certification acceleration:Industrial composting infrastructure expansion in France and the Netherlands aligns with forthcoming EN 13432 compliance timelines.
Industry Challenges
- Migration testing bottlenecks:EFSA and FDA evaluation timelines for novel barrier chemistries extend 18-24 months, delaying capacity investment decisions.
- Filling line integration complexity:Existing beverage production equipment requires retrofitting for fiber body handling, creating downtime costs and technical validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Bottles Market |
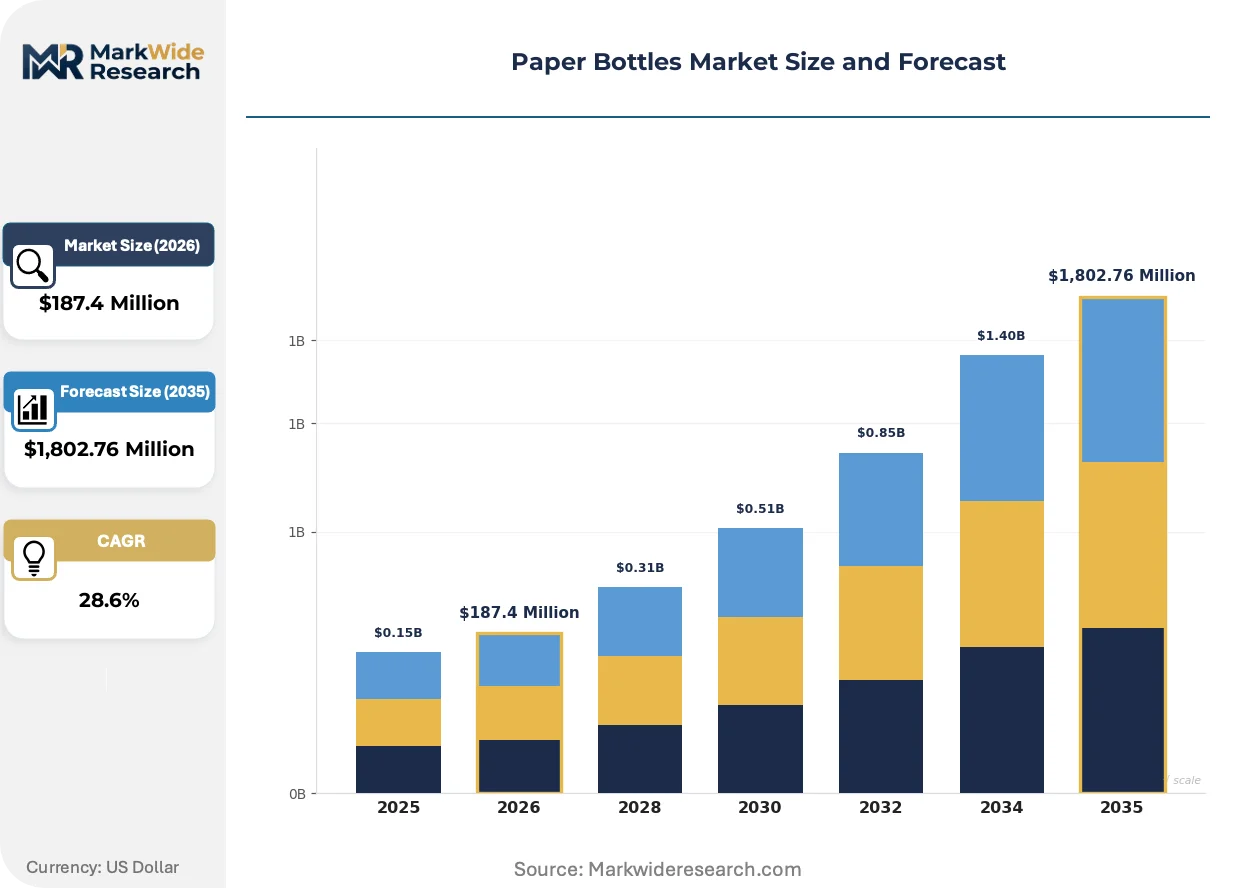
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Bottles, Beverage Containers, Packaging Solutions, Personal Care Bottles End User: Food & Beverage Industry, Cosmetics Industry, Retailers, Distribution Centers Size: Small, Medium, Large, Custom Sizes Technology: Biodegradable Coatings, Recyclable Materials, Barrier Technologies, Printing Techniques |
| Companies Covered | Frugalpac, Paboco, Notpla, Pulpex, Paper Bottle Company, LYS Packaging, PAPACKS Sales GmbH, Ecologic Brands, Choose Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Bottles Market Strategic Shifts
Coating innovation and regulatory alignment are compressing commercialization timelines, while demand-side procurement evolution is redrawing competitive boundaries between centralized and distributed manufacturing models.
Barrier technology is migrating from polyethylene-based interior linings toward mineral and bio-based alternatives. Beverage manufacturers in carbonated and still water categories are adopting these formulations at pilot scale. This migration from synthetic to renewable barriers is compressing the patent landscape and concentrating margin capture among coating specialists.
REACH frameworks now restrict conventional plastic additives in food-contact materials across EU member states. Industrial consequence includes forced reformulation of legacy barrier chemistries and accelerated R&D allocation toward fiber-compatible alternatives. Beverage containers face the strictest compliance timelines, with German and French regulators leading enforcement priority.
Brand procurement of packaging is consolidating around direct equipment partnerships rather than arm's-length supply contracts. Bottlers are acquiring or licensing on-site manufacturing technology to capture margin and control quality. This pattern is most visible in the United Kingdom, where retailer sustainability mandates compress supplier qualification cycles.
Paper Bottles Market Segmentation
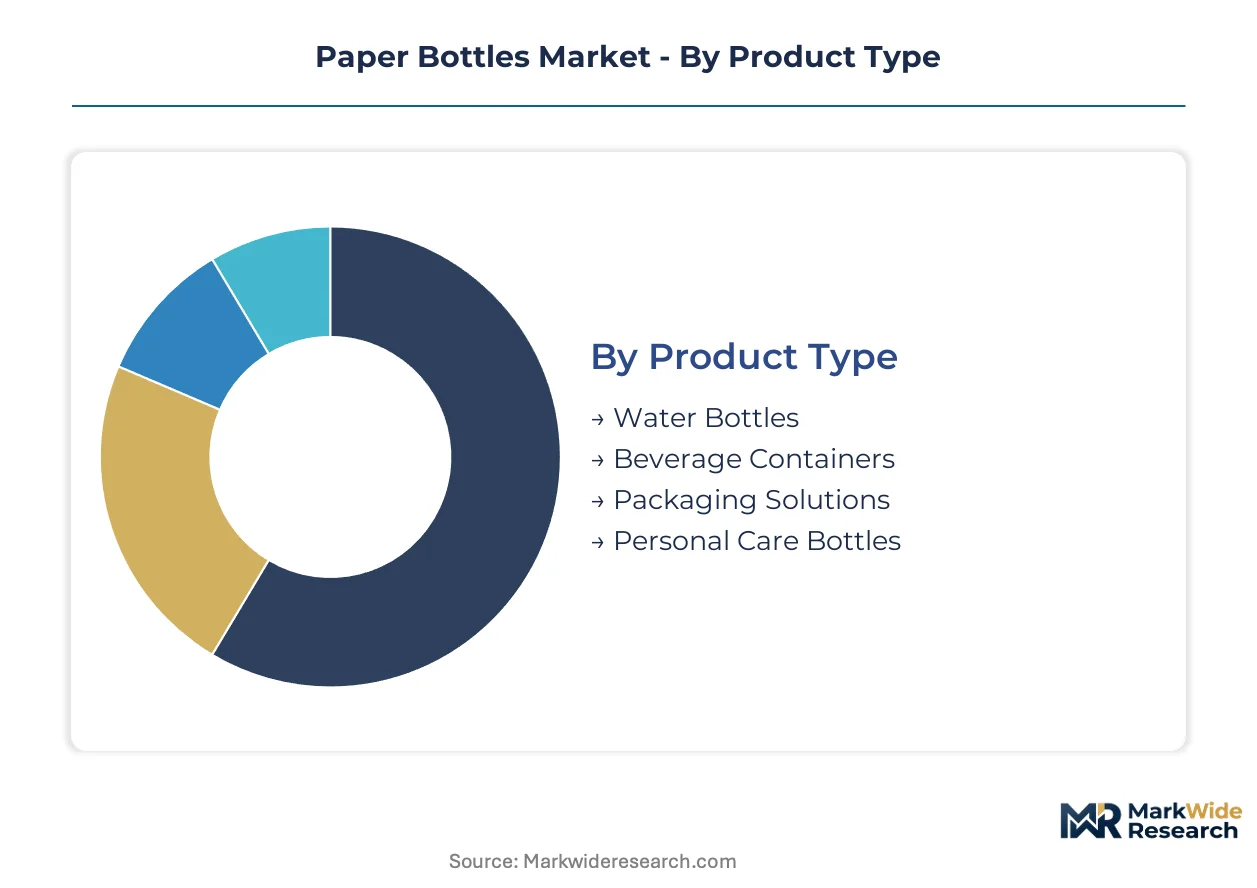
Paper bottle segmentation reflects divergent commercialization timelines across applications and technologies. Cycle times vary from months for beverage pilots to years for personal care certification, shaping where capital deploys and which segments attract coating innovation first.
Product Type:
Water bottles turn inventory fastest with standardized formats, while personal care variants face extended qualification cycles for cosmetic compatibility testing.
- Beverage Containers:Molded fiber bodies with mineral or bio-based interior barriers achieve burst strengths above 150 kPa for carbonated compatibility. Demand concentrates in Germany and France where EU Green Deal mandates force immediate plastic substitution in beer and sparkling water.
- Personal Care Bottles:Thicker wall constructions accommodate pump dispensers and oil-based formulations with specialized grease-resistant coatings. Cosmetics brands in the United Kingdom pursue these for retailer sustainability scorecards, though fragrance migration testing extends launch timelines.
- Water Bottles:Simplest barrier requirements enable fastest pilot-to-scale transitions.
- Packaging Solutions:Multi-use formats for industrial and institutional liquid dispensing.
Beverage containers dominate installed base. Personal care bottles are where expansion concentrates.
End User:
Food and beverage procurement moves on compliance deadlines, while cosmetics buying follows brand positioning cycles with longer vendor qualification.
- Food & Beverage Industry:Bottlers retrofit existing filling lines for fiber body handling, prioritizing shelf-stable categories with established distribution. German regulators enforce the strictest migration testing timelines under EFSA frameworks.
- Cosmetics Industry:Formulation-sensitive brands require coating chemistries that resist essential oils and alcohols without synthetic barriers. French and Dutch markets lead adoption where industrial composting infrastructure supports end-of-life claims.
- Retailers:Supermarket chains impose sustainability scorecards that accelerate supplier switching.
- Distribution Centers:Bulk handling requirements drive standardization around pallet-compatible formats.
Food and beverage industry commands current volume. Cosmetics industry is gaining share fastest.
Size:
Small formats amortize coating cost premiums across fewer units, while large sizes exploit fiber molding economies in institutional channels.
- Medium:500ml to 750ml capacities match mainstream beverage and personal care applications with optimal barrier cost-to-volume ratios. United Kingdom retailers specify these for private-label water and juice lines to meet packaging reduction targets.
- Custom Sizes:Brand-specific molds differentiate premium positioning while requiring dedicated tooling investment. Craft beverage producers in France commission these for limited releases that justify higher per-unit packaging spend.
- Small:Sample and travel-size formats for cosmetics trial programs.
- Large:Institutional and food-service containers for bulk liquid dispensing.
Medium sizes anchor production planning. Custom sizes are climbing the fastest as brand differentiation intensifies.
Technology:
Barrier technologies command longest development cycles and widest margins, while printing techniques turn over with seasonal label redesigns.
- Barrier Technologies:Interior coating formulations determine shelf-life performance with moisture vapor transmission targets below 10 g/m²/day. Mineral and seaweed-derived alternatives displace polyethylene linings as EFSA evaluates novel chemistries for food-contact approval.
- Biodegradable Coatings:Seaweed-derived and polysaccharide barriers eliminate synthetic content entirely for compostability certification. Dutch and French infrastructure expansion aligns with EN 13432 compliance timelines driving R&D allocation.
- Recyclable Materials:Fiber sourcing and post-consumer content ratios for paper body construction.
- Printing Techniques:Direct-to-fiber branding and variable data encoding for supply chain traceability.
Barrier technologies capture the steepest expansion trajectory. Printing techniques remain commoditized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage conglomerates and cosmetics multinationals concentrate procurement decisions in Northern Europe, where regulatory deadlines force immediate packaging transitions. These buyers prioritize suppliers with proven migration testing clearance and existing filling line retrofit partnerships.
Germany
Beer and mineral water bottlers drive fiber bottle trials under the EU Green Deal's single-use plastic phase-out. EFSA enforces the strictest food-contact migration testing timelines for novel barrier chemistries. Bavarian packaging clusters around Munich host precision fiber molding machinery suppliers serving carbonated drink compatibility programs.
France
Cosmetics houses in the Île-de-France region pursue plastic-free claims for retailer sustainability scorecards. ANSM coordinates with ECHA on REACH-compliant barrier additive approvals for essential oil-resistant coatings. The Hauts-de-France industrial belt hosts industrial composting infrastructure expansion aligned with EN 13432 certification timelines.
United Kingdom
Supermarket private-label water and juice lines specify medium-format fiber bottles to meet packaging reduction targets. Retailer mandates compress supplier qualification cycles below twelve months. Greater Manchester and West Midlands manufacturing zones concentrate on-site bottle production technology licensing for brand captive supply.
Netherlands
Dairy and chilled juice distributors pilot fiber bottles where cold-chain logistics relax barrier performance requirements. National composting infrastructure expansion supports end-of-life claims under forthcoming EN 13432 harmonization. Rotterdam-Antwerp logistics corridors enable just-in-time fiber body supply to Benelux bottling facilities.
United States
Craft beverage producers in California and the Pacific Northwest commission custom-format fiber bottles for limited releases. FDA evaluation timelines for expanded fiber-based beverage approvals extend commercialization roadmaps. Northeast corridor distributors test shelf-stable applications pending moisture vapor transmission threshold achievements.
Paper Bottles Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure where coating patent holders capture margin pools and machinery licensors control production access. The participant base clusters around three strategic archetypes: barrier chemistry specialists, fiber molding equipment providers, and brand-integrated manufacturing partners. Capacity expansion and strategic technology licensing constitute the dominant competitive moves as entrants seek to bypass Northern European equipment lead time constraints.
Within the barrier chemistry tier, Notpla and Paboco exemplify divergent approaches to synthetic elimination. Frugalpac occupies a position at the equipment-manufacturing intersection, representing the on-site production archetype that brands increasingly favor for margin capture. These three entities anchor the competitive topology through their respective concentrations in coating innovation, Danish R&D hub proximity, and patented machine technology deployment.
| Leading Market Players |
|---|
| Frugalpac |
| Paboco |
| Notpla |
| Pulpex |
| Paper Bottle Company |
| LYS Packaging |
| PAPACKS Sales GmbH |
| Ecologic Brands |
| Choose Packaging |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Danish precision fiber molding machinery is stretching equipment lead times past eighteen months and pushing contract terms toward upfront deposits with price escalation clauses indexed to Nordic industrial input costs.
Pricing Analysis
Cost-plus contracts with Nordic pulp indexation dominate long-term supply agreements between barrier coating specialists and beverage bottlers. Three-tier pricing structure across premium mineral-barrier, standard bio-based, and economy polyethylene-lined tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from seaweed-derived barrier raw material multiples compressing margins at price-sensitive volume tiers. Mass-market water bottlers exhibit highest price sensitivity while cosmetics brands pursuing plastic-free claims absorb premium coatings with lower volume elasticity.
Supply Chain Analysis
Export control restrictions on precision fiber molding technology limit equipment flows from Denmark and Germany to non-EU markets, constraining capacity expansion timelines. Supply concentration rests on Danish R&D hubs, German Bavarian machinery clusters, and French coating formulation centers. Raw material dependencies include Nordic wood pulp, seaweed harvests from North Atlantic fisheries, and mineral barrier precursors from Scandinavian mining operations. Single-source vulnerability concentrates in precision molding machinery where two Danish suppliers control patent-protected tooling. Distribution runs through Rotterdam-Antwerp logistics corridors into bottling facilities with just-in-time fiber body supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward beverage conglomerates consolidating procurement around direct equipment partnerships, fragmenting traditional supplier relationships and compressing qualification cycles below twelve months.
For Market Incumbents: Entrench coating patent positions through accelerated EFSA migration testing submissions for novel mineral formulations. Deepen backward integration into Nordic pulp supply to secure fiber body input cost stability against raw material volatility. Defensive priority rests on filling line retrofit partnerships that lock bottlers into proprietary handling equipment.
For New Entrants and Emerging Players: Pursue chilled juice and dairy segments where shorter distribution cycles relax barrier performance requirements and enable faster commercialization than shelf-stable categories. White-space opportunity concentrates in Netherlands dairy distributors piloting fiber bottles with cold-chain logistics support. Go-to-market angle should emphasize on-site manufacturing technology licensing to capture margin and control quality.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barrier coating R&D as EFSA evaluation timelines extend and migration testing costs concentrate among specialists with clearance track records. Long-term viability favors coating patent holders with proven food-contact approvals over equipment manufacturers facing commoditization pressure. Acquisition target archetype: mineral barrier specialists with EFSA pre-submission feedback. Signal to watch: EN 13432 compostability certification acceleration in France and Netherlands as infrastructure expansion aligns with compliance timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Patent Expansion | Mineral formulation patents determine shelf-life performance and margin capture in carbonated applications. |
| On-Site Manufacturing Technology Licensing | Frugalpac-style machine deployment eliminates transport damage and reduces working capital for bottlers. |
| EFSA Migration Testing Acceleration | Novel chemistry clearance timelines directly shape capacity investment decisions and competitive positioning. |
| Nordic Pulp Supply Integration | Backward integration into fiber body inputs secures cost stability against raw material price volatility. |
| Industrial Composting Infrastructure Partnership | EN 13432 certification alignment in France and Netherlands enables end-of-life claims for cosmetics brands. |
Study Parameters
Initial hypotheses were tested against primary input from beverage packaging procurement directors, barrier coating R&D leads, filling line equipment engineers, and cosmetics brand sustainability officers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation across EFSA migration testing databases, EU Green Deal implementation trackers, REACH additive restriction filings, and Nordic pulp trade flow customs records. Bottom-up fiber molding capacity estimates and top-down beverage packaging substitution demand were cross-referenced to anchor volume projections.
Demand-supply balance modeling across the projection horizon incorporated segmentation by barrier technology tier, end-use application, and regional regulatory cluster. Analytical framework tracked coating chemistry migration, filling line retrofit penetration, and composting infrastructure expansion as industry-specific forecast inputs. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints.
Sensitivities concentrate around EFSA clearance timeline delays, Nordic equipment capacity bottlenecks, and seaweed harvest yield volatility. Forecasts reflect documented assumptions on regulatory enforcement intensity and industrial composting rollout pace. Material shifts in EU Green Deal implementation timelines or breakthrough polyethylene barrier displacement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
GCC Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market