
 Greyboard Market | 2026-2036
Greyboard Market Size, Share, and Industry Trends Forecast 2026-2036
Greyboard Market Foresight
Aging millwright and paper-machine operator cohorts across European mills is unwinding production capacity just as e-commerce packaging demand accelerates. Smurfit Kappa Group leverages its integrated containerboard-to-converted-products chain to secure furnish for greyboard lines. Mondi Group sustains competitive supply through its Central European pulp and recycled fiber network. DS Smith anchors regional distribution by controlling converting assets near major German automotive and consumer goods clusters.
Greyboard denotes a multi-ply paperboard manufactured from recycled pulp fibers, typically calendered to densities between 0.55 and 0.85 g/cm³ and valued for dimensional stability in die-cutting and lamination operations. Its primary commercial purpose centers on rigid box construction, bookbinding substrates, and protective dunnage where structural integrity at low grammage outweighs surface print quality. Sheet Greyboard dominates volume throughput in European converting halls where flatbed die-cutters process standardized formats for cosmetics and electronics packaging. Roll Greyboard occupies the fastest-expanding demand channel among automated rigid-box lines serving online retail fulfillment centers. Recycled Grade captures widening margin pools as brand owners specify post-consumer content thresholds in packaging briefs.
EMA guidelines on pharmaceutical packaging material traceability, REACH restrictions on heavy metals in recycled fiber streams, and FSC chain-of-custody certification requirements collectively elevate compliance costs for greyboard suppliers serving regulated end-uses. CE marking obligations for packaging in contact with food-grade applications further narrow the qualified supplier base across the continent. Stakeholders must monitor recycled fiber cost spreads against virgin pulp alternatives and assess converting automation investments before labor availability tightens further in mill towns.
Market Dynamics
The EU Green Deal and Packaging and Packaging Waste Regulation are forcing converters to reengineer furnish mixes and certification pipelines faster than aging mill infrastructure can adapt.
Growth Catalysts
- E-commerce rigid-box demand:Online retail fulfillment centers specify automated roll-fed greyboard lines to accelerate box assembly throughput.
- REACH compliance differentiation:Suppliers certifying heavy-metal-free recycled fiber streams capture pharmaceutical and food-contact packaging briefs.
- Automotive component tray specifications:German OEM clusters standardize greyboard dunnage for EV battery module shipping.
Market Restraints
- Recycled fiber cost volatility:OCC price spreads against virgin pulp swing converter margins unpredictably.
- German production concentration:Mill closures in the Rhineland and Bavaria reduce regional furnish security.
- Plastic corrugated substitution:Reusable polypropylene dunnage erodes greyboard share in closed-loop automotive logistics.
Strategic Opportunities
- Eastern European converting capacity:Poland and Czech Republic offer lower labor costs for rigid-box assembly serving EU markets.
- FSC chain-of-custody premium tier:Brand owners specify certified post-consumer content thresholds in sustainability briefs.
- Digital print lamination convergence:Hybrid inkjet-coating lines enable short-run premium packaging without cylinder engraving delays.
Industry Challenges
- Paper-machine operator attrition:European mills face 15-20% retirement waves through 2030 with insufficient apprentice pipelines.
- CE marking timeline compression:Food-contact certification cycles extend 8-14 months, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greyboard Market |
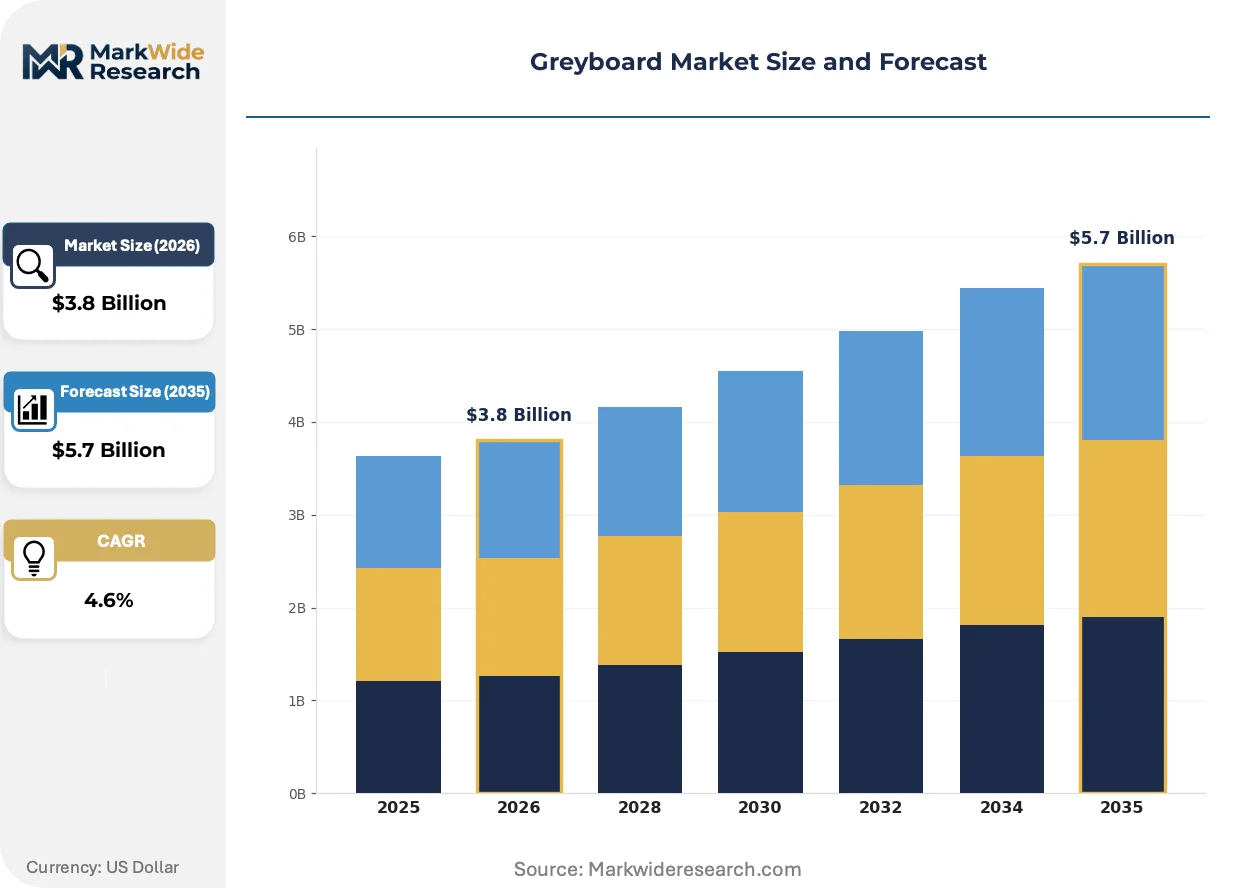
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Greyboard, Roll Greyboard, Laminated Greyboard, Coated Greyboard End Use Industry: Packaging, Arts & Crafts, Stationery, Automotive Grade: Standard Grade, Heavyweight Grade, Lightweight Grade, Recycled Grade Thickness: 2mm, 3mm, 5mm, 10mm |
| Companies Covered | Smurfit Kappa Group, Mondi Group, DS Smith, International Paper, Stora Enso, Westrock Company, Skjern Papirfabrik A/S, EskaBoard, Emami Paper Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greyboard Market Shifts & Advancements
Digital coating and inline quality verification systems are compressing batch sizes while regulatory traceability mandates reshape supplier qualification protocols across pharmaceutical and food-contact segments.
Water-based barrier coatings is fragmenting the traditional PE-laminated greyboard segment by enabling direct paper-to-paper adhesion without plastic film interlayers. Premium cosmetics brands in France and Italy specify these grades for mono-material packaging claims. The technology is fragmenting incumbent supply chains by forcing converters to choose between coating line retrofits or specialty mill partnerships.
EMA guidelines on pharmaceutical packaging material traceability now require lot-level fiber provenance documentation for secondary packaging. This elevates compliance costs for greyboard suppliers serving regulated end-uses. German and Swiss pharmaceutical clusters are consolidating supplier bases to those with integrated pulp-to-convert chain-of-custody systems.
Direct mill-to-brand procurement contracts are displacing traditional merchant distribution for high-volume e-commerce packaging buyers. Automated rigid-box lines in Netherlands and Belgium fulfillment centers now specify roll formats with tolerances tighter than merchant stocking standards permit. This pattern concentrates volume with integrated producers capable of custom slitting and just-in-time delivery scheduling.
Greyboard Market Segmentation
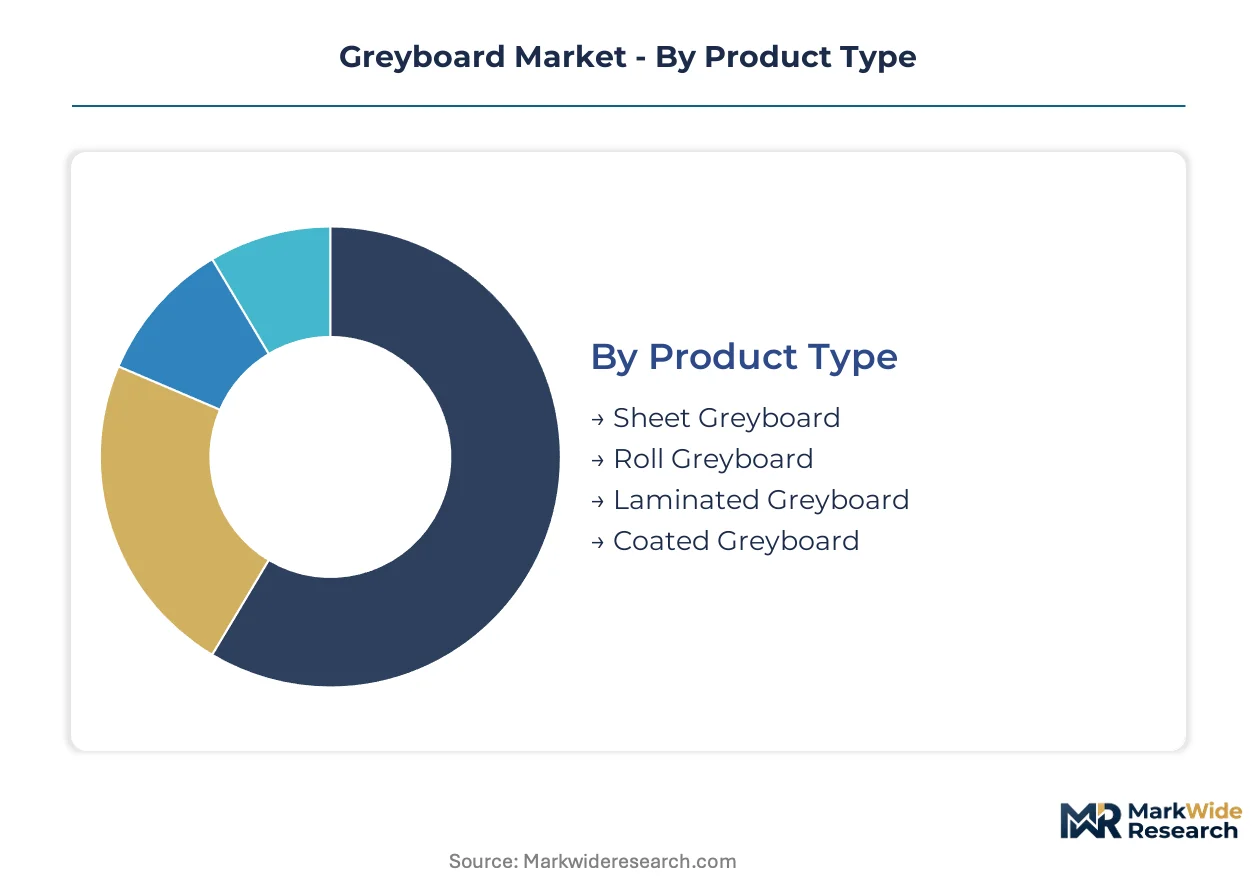
Greyboard demand fragments across product formats, end-use specifications, and certification tiers that dictate procurement patterns. Converters align inventory strategies to the density, dimensional stability, and surface finish requirements of each segment.
Product Type:
German and Polish converters dominate sheet format procurement for flatbed die-cutting operations, while roll formats flow primarily to automated lines in Netherlands and Belgium fulfillment centers.
- Sheet Greyboard:Flat-cut sheets calendered to precise thickness tolerances serve cosmetics and electronics packaging lines. German converting halls in the Rhineland cluster standardize on 700x1000mm and 800x1200mm formats for rigid box construction.
- Roll Greyboard:Continuous web formats feed automated rigid-box lines with slitting tolerances tighter than merchant stocking standards permit. Demand concentrates in Netherlands and Belgium e-commerce fulfillment centers specifying just-in-time delivery scheduling.
- Laminated Greyboard:Multi-ply constructions with PE or water-based barrier interlayers target food-contact and pharmaceutical secondary packaging applications.
- Coated Greyboard:Surface-treated grades enable direct inkjet printing for short-run premium packaging without cylinder engraving delays.
Sheet Greyboard holds the largest share; momentum sits with Roll Greyboard.
End Use Industry:
Cost-tier stratification separates commodity packaging procurement from premium automotive and craft segments requiring certified fiber provenance.
- Packaging:Rigid box construction for cosmetics, electronics, and online retail fulfillment absorbs the majority of European greyboard volume. E-commerce buyers specify recycled-content thresholds aligned with EU Green Deal mandates.
- Automotive:EV battery module shipping trays and component dunnage standardize on heavyweight grades with dimensional stability under load. German OEM clusters in Bavaria and Baden-Württemberg anchor specifications.
- Arts & Crafts:Premium bookbinding substrates and archival boards demand FSC chain-of-custody certification with post-consumer content documentation.
- Stationery:Binder boards and file folder substrates prioritize cost efficiency over surface print quality in Eastern European converting.
Packaging commands the volume base; automotive specifications are climbing the fastest.
Grade:
Margin pools concentrate in certified recycled grades as brand owners embed post-consumer content thresholds in sustainability briefs.
- Recycled Grade:Post-consumer fiber streams with heavy-metal-free certification capture pharmaceutical and food-contact packaging briefs. REACH compliance differentiation elevates pricing power against virgin pulp alternatives.
- Heavyweight Grade:Densities above 0.75 g/cm³ provide structural integrity for automotive dunnage and industrial protective packaging. German OEM tray specifications standardize on this tier.
- Standard Grade:Mid-density constructions balance cost and performance for general packaging applications across Central European converting.
- Lightweight Grade:Reduced grammage targets stationery and low-load protective applications where material cost minimization outweighs rigidity requirements.
Standard Grade maintains the broadest installed base; Recycled Grade shows the steepest expansion trajectory.
Thickness:
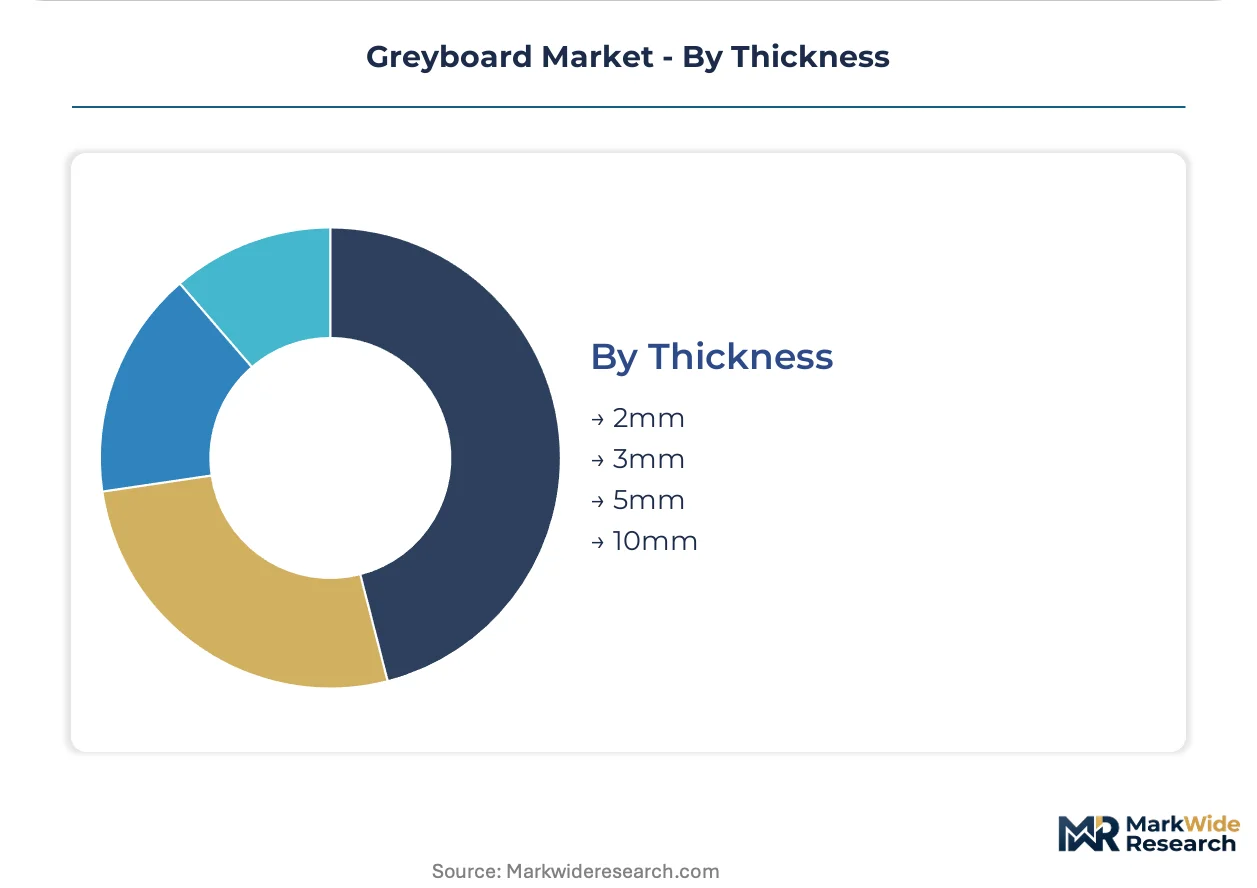
Volume throughput concentrates in 2mm and 3mm specifications, with thicker grades serving niche protective and display applications.
- 2mm:The workhorse specification for cosmetics rigid boxes and electronics packaging. Flatbed die-cutters across German and French converting halls process this thickness at highest throughput rates.
- 3mm:Premium gift packaging and heavier electronics applications require the additional rigidity. Italian and Spanish converters favor this grade for luxury brand briefs.
- 5mm:Display stands and point-of-sale applications leverage the structural depth for freestanding constructions.
- 10mm:Specialized protective dunnage and architectural model boards occupy limited volume with custom slitting requirements.
2mm specifications anchor volume; 3mm grades are gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command 15-20% pricing premiums over Polish competitors due to certification density and just-in-time logistics infrastructure, while Baltic producers undercut both on standard-grade sheet formats. This asymmetry is reshaping procurement routing across EU rigid-box supply chains.
Germany
Automotive dunnage specifications from Bavarian EV battery manufacturers and Rhineland cosmetics rigid-box clusters absorb the majority of premium-grade volume. The EU Green Deal's recycled-content mandates are accelerating mill consolidation around certified post-consumer fiber streams. Stuttgart and Munich fulfillment centers now specify roll-format tolerances tighter than merchant stocking standards permit.
Poland
Lower labor costs and proximity to German demand clusters position Polish converting halls as rigid-box assembly alternatives for EU brands. REACH heavy-metal compliance documentation remains uneven across regional suppliers, creating tiered qualification barriers. The Łódź and Poznań industrial corridors are attracting automated roll-fed line investments from Netherlands-based packaging buyers.
Netherlands
E-commerce fulfillment centers in Rotterdam and Eindhoven drive roll-format demand with specifications for custom slitting and synchronized delivery scheduling. The Dutch national packaging covenant imposes stricter recycled-content verification than baseline EU requirements. Direct mill procurement contracts are displacing traditional merchant distribution for high-volume buyers.
France
Premium cosmetics brands in Paris and Lyon specify water-based barrier coatings for mono-material packaging claims under extended producer responsibility frameworks. ANSM pharmaceutical traceability guidelines are elevating lot-level fiber documentation requirements. The Auvergne-Rhône-Alpes converting cluster is consolidating supplier bases around integrated chain-of-custody systems.
Belgium
Antwerp and Brussels logistics hubs anchor cross-border distribution for roll-greyboard feeding automated lines in Netherlands and German fulfillment networks. CE marking obligations for food-contact applications narrow the qualified supplier base. Flemish regional sustainability procurement guidelines mandate FSC certification thresholds above EU baseline.
Greyboard Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated European paperboard groups controlling certification pipelines while regional converters compete on labor arbitrage. The market exhibits tiered concentration: three pan-European producers anchor premium-grade supply, mid-scale specialists occupy geographic niches, and merchant distributors face margin compression from direct mill procurement. Strategic moves center on coating line retrofits for water-based barrier adoption and backward integration into recycled fiber collection networks.
Among integrated paperboard groups, Smurfit Kappa Group, Mondi Group, and DS Smith represent the dominant archetype combining containerboard production with converting assets. These firms exemplify the certification-integrated model that pharmaceutical and food-contact buyers now mandate. Smurfit Kappa's Irish-registered structure and Mondi's Anglo-Austrian footprint position both within EU regulatory frameworks, while DS Smith's UK-based operations anchor distribution near German automotive clusters. Regional specialists such as Skjern Papirfabrik A/S occupy narrower positions serving Nordic sustainability briefs.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith |
| International Paper |
| Stora Enso |
| Westrock Company |
| Skjern Papirfabrik A/S |
| EskaBoard |
| Emami Paper Mills |
| Others |
Supply & Pricing Matrix
Mill-scale economies in Rhineland and Bavaria concentrate furnish security among integrated producers, compressing price floors for merchant distributors while elevating premiums for certified grades. Smurfit Kappa and Mondi leverage captive pulp networks to defend margin positions against Baltic undercutting on standard sheet formats.
Pricing Analysis
The customization-premium spread between configured-to-order roll formats and merchant-stocked sheet standards exceeds fifteen percentage points. Contract-based long-term offtake dominates high-volume e-commerce procurement, with price differentiation driven by REACH heavy-metal certification and FSC chain-of-custody tier. Cost compression in standard grades intensifies as Polish converters absorb German automotive overflow demand. Brand owners specifying post-consumer content thresholds show lowest price sensitivity; stationery distributors in Eastern Europe exhibit highest.
Supply Chain Analysis
Inventory lead-times stretch longest for pharmaceutical-grade lots requiring EMA traceability documentation, compressing to days for commodity sheet formats. Supply concentrates in Germany, Poland, and the Netherlands, with furnish anchored in recycled OCC streams, virgin pulp alternatives, and water-based coating chemicals. Single-source vulnerability runs through Rhineland mill clusters facing operator retirement waves. Distribution feeds from integrated producers direct to Netherlands and Belgium fulfillment centers, bypassing traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greyboard demand fragments across certification tiers and automation readiness, creating niches for specialists between integrated giants and regional converters. EU Green Deal mandates accelerate this fragmentation by disqualifying uncertified suppliers from pharmaceutical and food-contact briefs.
For Market Incumbents: Secure backward integration into recycled fiber collection networks before OCC price volatility erodes converter margins. Defend position by retrofitting coating lines for water-based barrier adoption; plastic corrugated substitution in automotive closed-loop logistics threatens heavyweight grade volumes. Prioritize FSC chain-of-custody investments to capture pharmaceutical consolidation toward integrated pulp-to-convert systems.
For New Entrants and Emerging Players: Anchor in Polish converting corridors serving German automotive and cosmetics clusters through labor arbitrage. White-space targets include automated roll-fed line installation for Netherlands e-commerce fulfillment and REACH-compliant recycled grade production for pharmaceutical secondary packaging. Go-to-market angle: just-in-time slitting capabilities with tighter tolerances than merchant stocking standards permit.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating line retrofit specialists over greenfield mill investments. Long-term viability hinges on water-based barrier adoption curves and labor automation substitution rates. Acquisition target archetype: regional converters with established pharmaceutical customer relationships and incomplete certification pipelines. Signal to watch: German OEM tray specifications shifting from greyboard to reusable polypropylene dunnage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captive OCC supply insulates Smurfit Kappa and Mondi from price spread volatility. |
| Water-Based Barrier Coating Line Retrofit | Enables mono-material packaging claims for French premium cosmetics brands. |
| FSC Chain-of-Custody Certification Investment | Qualifies suppliers for German pharmaceutical cluster consolidation trends. |
| Automated Roll-Fed Line Installation | Matches Netherlands fulfillment center specifications for synchronized delivery. |
| Eastern European Converting Capacity Expansion | Leverages Polish labor costs for rigid-box assembly serving EU demand clusters. |
Research Methodology
The analysis maps sheet greyboard, roll greyboard, laminated constructions, and coated grades, each validated through mill operations directors, converting plant managers, automotive packaging engineers, and pharmaceutical procurement leads. Primary interviews with Smurfit Kappa, Mondi, and DS Smith supply chain executives combined with secondary validation against EU customs data, CEPI industry statistics, EMA regulatory filings, and FSC certification databases. Bottom-up volume triangulation against top-down macroeconomic drivers ensures cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, end-use industry, certification tier, thickness specification, and regional production hub. CAGRs derived from fitted growth curves incorporating e-commerce fulfillment center expansion rates, automotive EV battery shipment volumes, and recycled fiber cost spread trajectories.
Material uncertainties — mill operator attrition acceleration, REACH enforcement intensity shifts, and plastic corrugated substitution thresholds — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and automation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Butchers Paper Market