
 Unbleached Kraft Paperboard Market | 2026-2036
Unbleached Kraft Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Unbleached Kraft Paperboard Market Analytics
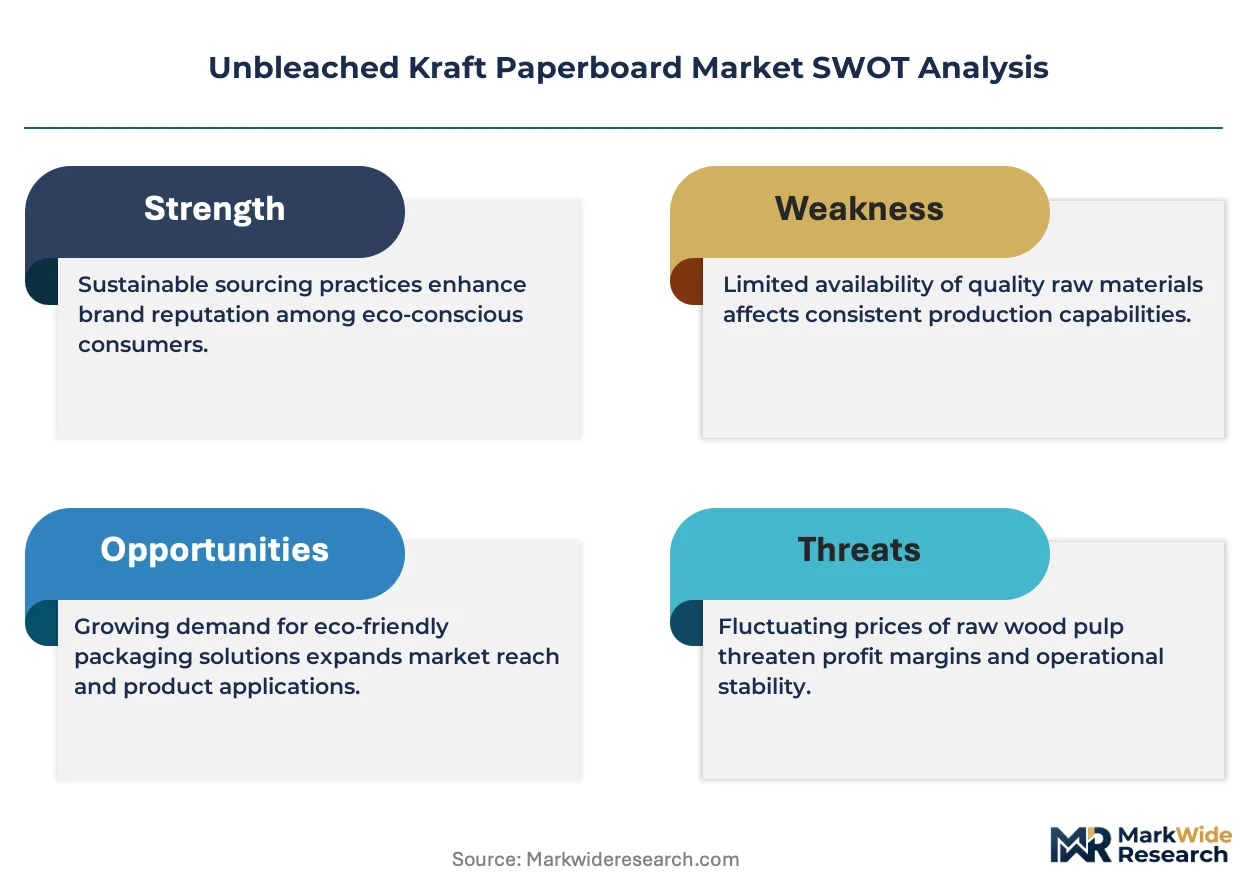
Forest Stewardship Council (FSC) chain-of-custody certification is bifurcating the competitive landscape into credentialed and uncertified supply tiers. International Paper Company leverages its North American timberland base to sustain integrated pulp-to-board output. Smurfit WestRock anchors European volume through recycled-fiber synergies at its converted packaging network. Mondi Group differentiates via specialty kraft grades for moisture-resistant food-contact applications.
Unbleached kraft paperboard denotes a brown, unbleached pulp-based board typically manufactured with 80-100% virgin softwood kraft fibers, yielding burst strengths of 200-400 kPa and basis weights from 150-450 gsm for protective packaging and structural containers. Containerboard occupies the dominant volume position as e-commerce shipping demand pulls tonnage through corrugated box plants. Folding boxboard commands premium positioning in branded consumer goods where printability and structural rigidity intersect. Specialty paperboard segments are capturing margin pools in grease-resistant and freezer-grade niches where functional performance justifies higher unit economics.
The US EPA guides recycled content benchmarks under Comprehensive Procurement Guidelines, while EU REACH restricts certain chemical treatments in food-contact boardstock. FDA food-contact substance notifications govern direct-contact kraft applications in the United States, creating compliance thresholds for imported board. Stakeholders must monitor evolving extended producer responsibility frameworks and fiber sourcing disclosure rules that will reshape procurement qualifications and supplier qualification cycles.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing recyclability timelines and forcing converters toward virgin-fiber unbleached grades that bypass de-inking complexity. This single regulatory vector is redrawing qualification requirements across European procurement desks and North American export channels simultaneously.
Growth Catalysts
- E-commerce fulfillment acceleration:Corrugated box demand from third-party logistics hubs in Germany and the Netherlands is pulling tonnage through Rhine-Ruhr converter clusters at elevated run rates.
- FSC chain-of-custody mandates:Retail grocery chains in France and Belgium now require certified boardstock for private-label food packaging, bifurcating supplier tiers into credentialed and uncertified pools.
- Moisture-resistant food-contact grades:Specialty kraft formulations incorporating synthetic polymer barriers are capturing freezer-grade and grease-resistant niches where functional performance commands premium positioning.
Market Restraints
- Softwood pulp cost volatility:Northern European timber supply constraints and energy-intensive kraft pulping economics create input cost pressure that converters cannot fully pass through to box pricing.
- Recycled-fiber substitution in non-contact applications:Testliner and recycled corrugating medium grades displace unbleached kraft in secondary packaging layers where direct food contact is not required.
- REACH chemical restrictions:ECHA limitations on certain fluorinated treatments for grease resistance complicate formulation strategies for freezer-grade boardstock destined for EU markets.
Strategic Opportunities
- Extended producer responsibility tailwinds:Germany's Verpackungsgesetz mandates higher recycling quotas that favor unbleached kraft's compatibility with existing paper recovery streams versus plastic alternatives.
- Pharmaceutical cold-chain expansion:Insulated shipping containers for temperature-sensitive biologics represent an emerging application where structural rigidity and moisture resistance intersect.
- Digital print compatibility:Water-based ink adhesion improvements on unbleached surfaces are enabling short-run customized packaging for craft food brands through hybrid flexo-digital presses.
Industry Challenges
- FSC certification timeline compression:Chain-of-custody audits require 12-18 month implementation cycles that delay supplier qualification for urgent retail procurement windows.
- Legacy corrugator width constraints:Existing box plant machinery in older European facilities cannot run lightweight high-performance fluting that maximizes yield from premium unbleached linerboard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unbleached Kraft Paperboard Market |
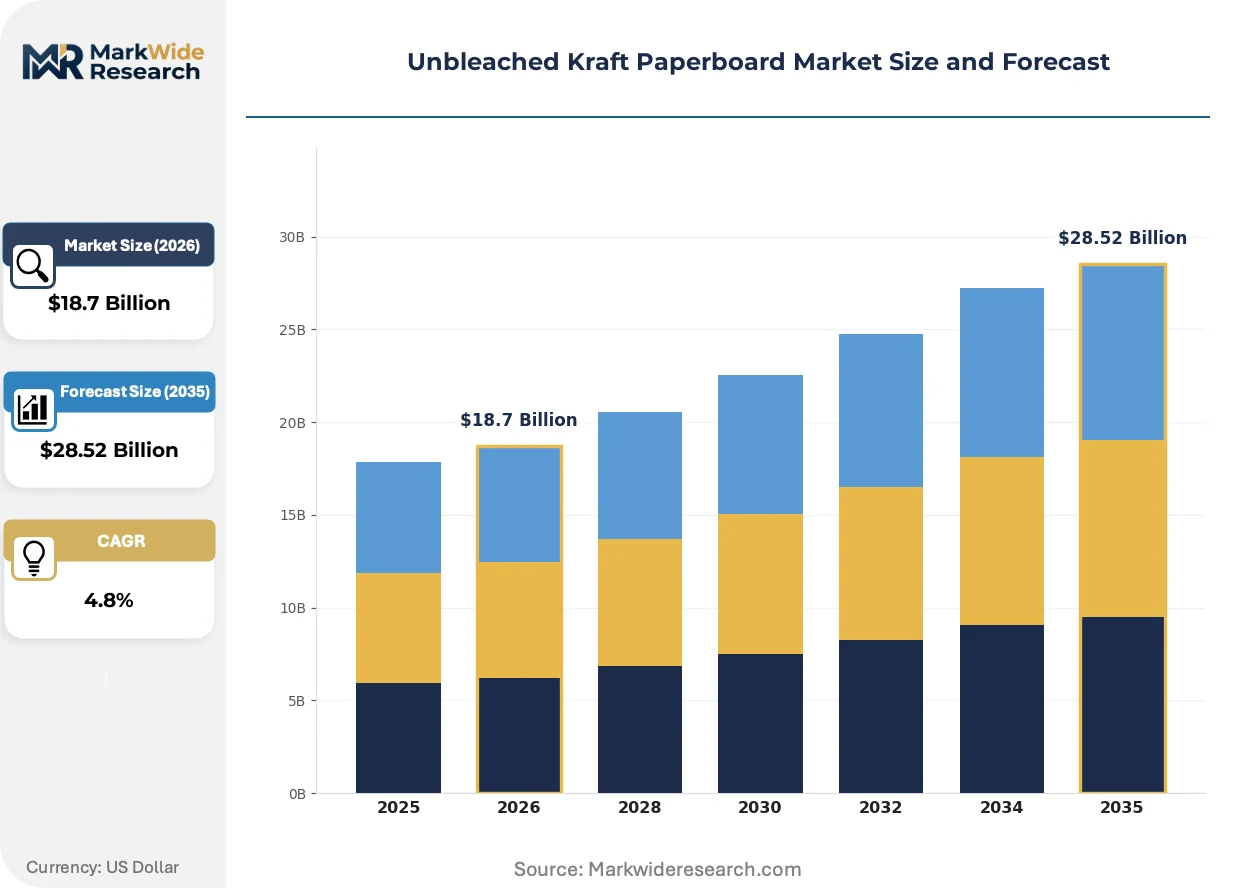
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerboard, Folding Boxboard, Linerboard, Specialty Paperboard End User: Packaging, Consumer Goods, Furniture, Food Service Thickness: Single Wall, Double Wall, Heavy Duty, Light Duty Application: Food Packaging, Shipping Boxes, Stationery, Arts & Crafts |
| Companies Covered | International Paper Company, Smurfit WestRock, Mondi Group, Stora Enso, Georgia-Pacific LLC, Sappi Limited, Billerud AB, Nine Dragons Paper (Holdings) Limited, Nordic Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unbleached Kraft Paperboard Market Evolving Landscape
Functional coating technologies and digital manufacturing integration are reshaping how unbleached kraft paperboard delivers value beyond structural containment. These developments are compressing traditional trade-offs between printability, barrier performance, and end-of-life recyclability.
Barrier coating technology is miniaturizing the functional layer thickness required for grease and moisture resistance. Food-service packaging converters in Scandinavia are adopting nanocellulose-reinforced coatings at pilot scale. This miniaturizing of barrier thickness preserves repulpability while matching polyethylene-laminated performance in fry cartons and freezer boxes.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproof chemistries from EU food-contact boardstock. Kraft producers are pivoting toward plant-based sizing agents and mineral-oil-free barriers. The chilled ready-meal segment in Germany and Austria is most affected, with converters accelerating qualification of alternative formulations ahead of 2025 enforcement milestones.
Brand owners are consolidating specification authority at central procurement hubs rather than delegating to regional packaging engineers. This concentration is compressing supplier rosters and elevating FSC certification and carbon disclosure to primary selection criteria. The shift is most visible among pan-European grocery retailers sourcing private-label corrugated displays and shelf-ready packaging.
Unbleached Kraft Paperboard Market Segmentation
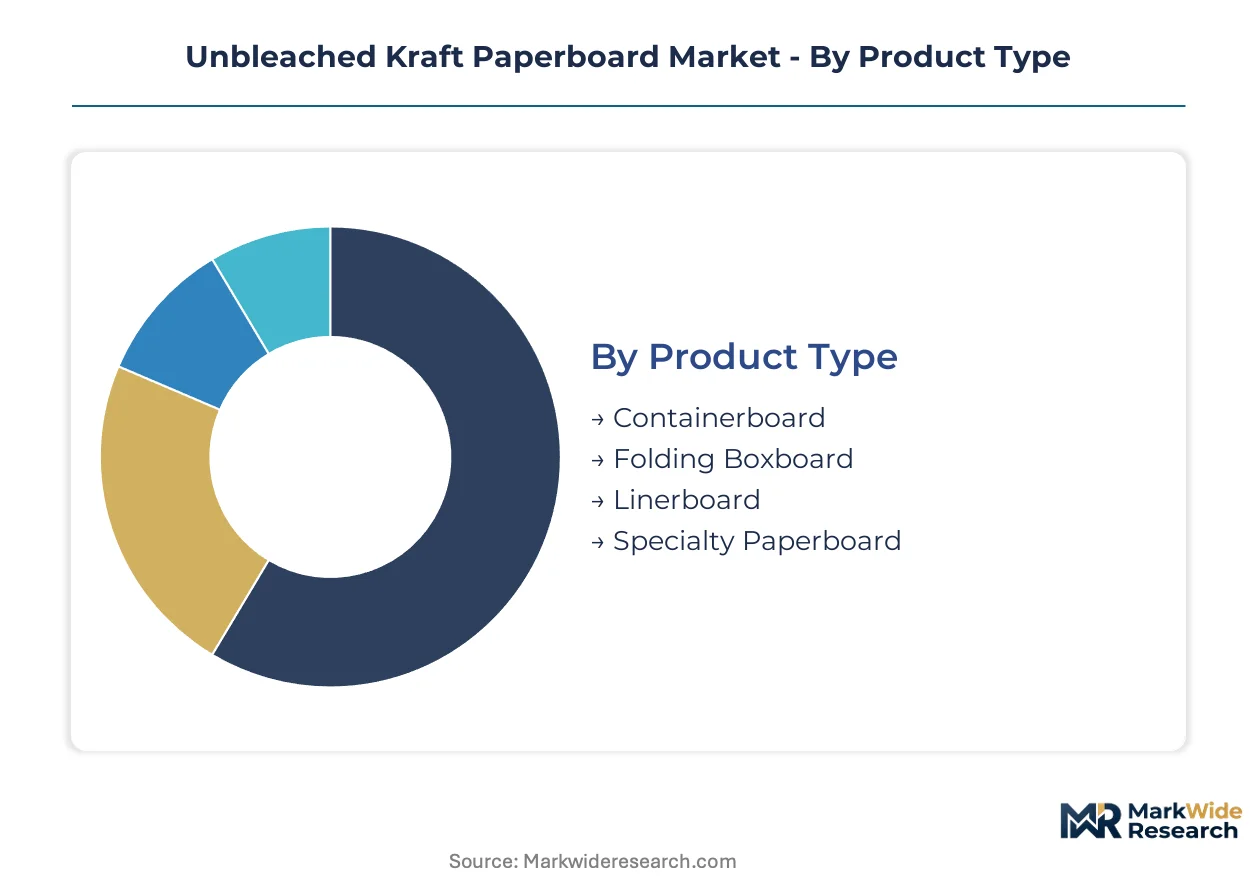
Unbleached kraft paperboard segments respond differently to regulatory pressure on recyclability and food-contact compliance. Procurement desks now weight certification status and barrier performance alongside traditional cost metrics when qualifying suppliers across these categories.
Product Type:
EU REACH restrictions on fluorinated treatments and FDA food-contact substance notifications create divergent compliance pathways for each grade, reshaping export qualification requirements.
- Containerboard:Corrugating medium and linerboard grades manufactured from 80-100% virgin softwood kraft fibers, typically basis weights of 125-200 gsm for outer liners. Demand concentrates in Rhine-Ruhr converter clusters serving German e-commerce fulfillment hubs, pulled by third-party logistics expansion and Verpackungsgesetz recycling quotas favoring virgin-fiber compatibility.
- Folding Boxboard:Multi-ply constructions combining bleached or unbleached outer layers with recycled or virgin inner plies, engineered for printability and structural rigidity in branded consumer goods. French and Belgian retail grocery chains now mandate FSC-certified folding boxboard for private-label food packaging, bifurcating supplier tiers into credentialed and uncertified pools.
- Linerboard:High-strength outer facing for corrugated containers, burst strengths typically 200-350 kPa.
- Specialty Paperboard:Grease-resistant and freezer-grade formulations with functional barriers for moisture protection.
Containerboard handles the majority of throughput; Specialty Paperboard is climbing the fastest on share as functional performance commands premium positioning.
End User:
Cost tier differentiation separates high-compliance food-contact applications from structural packaging where recycled-fiber substitution is eroding virgin kraft penetration.
- Packaging:Corrugated shipping containers, protective wraps, and industrial dunnage requiring burst strength and stacking performance. German pharmaceutical cold-chain expansion for temperature-sensitive biologics is pulling specialty kraft grades into insulated shipping container applications.
- Consumer Goods:Branded retail boxes and shelf-ready packaging where print quality and structural presentation intersect. Pan-European grocery retailers are consolidating specification authority at central procurement hubs, elevating FSC certification and carbon disclosure to primary selection criteria.
- Furniture:Protective corner boards and flat-pack wrapping for distribution durability.
- Food Service:Direct-contact takeout containers and food trays governed by FDA notifications in the United States and EFSA compliance in Europe.
Packaging absorbs the dominant volume position; Food Service is expanding most quickly as direct-contact regulations tighten recycled-fiber substitution.
Thickness:
Application-driven performance requirements dictate wall construction, with legacy corrugator machinery constraints limiting lightweight high-performance adoption in older European facilities.
- Single Wall:One fluted medium between two linerboards, standard for lightweight consumer goods and e-commerce parcels.
- Double Wall:Two fluted layers with three linerboard facings, engineered for heavy retail and industrial distribution where stacking strength is critical.
- Heavy Duty:Triple-wall or reinforced constructions for export shipping and bulk agricultural containment.
- Light Duty:Reduced caliper grades for display packaging and temporary protective applications where structural demands are minimal.
Single Wall maintains the highest shipment volumes; Double Wall is gaining share fastest as e-commerce parcel weights increase.
Application:
Functional coating advances are compressing traditional trade-offs between barrier performance and end-of-life recyclability across these use cases.
- Food Packaging:Direct-contact boardstock for chilled ready-meals, frozen goods, and grease-resistant service items. Scandinavian converters are piloting nanocellulose-reinforced coatings that preserve repulpability while matching polyethylene-laminated performance in fry cartons and freezer boxes.
- Shipping Boxes:Corrugated containers for e-commerce fulfillment and industrial distribution, where ECT and burst strength specifications dominate qualification.
- Stationery:Cover stock and binder components requiring stiffness and printability for office and educational supplies.
- Arts & Crafts:Structural and decorative applications where natural kraft aesthetics and workability are valued over performance specifications.
Shipping Boxes carries the bulk of tonnage; Food Packaging shows the steepest expansion trajectory as barrier coating miniaturization unlocks new compliant formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food packaging buyers and corrugated converters cluster around industrial belts with integrated pulp-to-board infrastructure and strict recyclability mandates. Procurement desks prioritize FSC-certified supply tiers where virgin-fiber unbleached grades bypass de-inking complexity.
Germany
E-commerce fulfillment hubs along the Rhine-Ruhr belt pull containerboard tonnage through converter clusters at elevated run rates. Verpackungsgesetz mandates higher recycling quotas that favor unbleached kraft's compatibility with paper recovery streams. Corrugated plants in North Rhine-Westphalia serve third-party logistics centers in the Netherlands and Belgium.
United States
FDA food-contact substance notifications govern direct-contact kraft applications, creating compliance thresholds for imported boardstock. EPA Comprehensive Procurement Guidelines steer recycled content benchmarks for federal contractors. Integrated mills in the Southeast leverage timberland proximity to sustain pulp-to-board output.
France
Retail grocery chains mandate FSC-certified boardstock for private-label food packaging, bifurcating supplier pools into credentialed and uncertified tiers. ECHA restrictions on fluorinated treatments complicate grease-resistant formulations. Paris-based procurement hubs consolidate specification authority across pan-European operations.
China
Nine Dragons Paper and domestic producers scale recycled-fiber synergies amid tightening import regulations on recovered paper. GB standards for food-contact materials diverge from Western compliance pathways. Yangtze River Delta converters supply e-commerce packaging demand from Shanghai fulfillment centers.
Sweden
Scandinavian converters pilot nanocellulose-reinforced coatings that preserve repulpability while matching polyethylene-laminated performance. Forest Stewardship Council chain-of-custody certification anchors export qualification to EU markets. Timber supply constraints in Northern Europe intensify kraft pulping cost pressure.
Unbleached Kraft Paperboard Market Competitive Landscape
Player mix skews toward integrated forest products conglomerates with captive pulp supply and recycled-fiber specialists leveraging converted packaging networks. The competitive landscape bifurcates along certification status, with FSC chain-of-custody credentials separating premium-tier suppliers from commodity-positioned competitors. Strategic archetypes include North American timberland-integrated producers, European recycled-fiber converters, and Asian scale-driven manufacturers. Dominant competitive moves center on backward integration into pulp supply and specialty-grade formulation for moisture-resistant food-contact applications.
Within the integrated producer tier, International Paper Company exemplifies the North American timberland-anchored archetype with captive softwood kraft pulp supply. Smurfit WestRock occupies a position representing European recycled-fiber synergies across converted packaging networks. Mondi Group sits within the specialty-grade differentiation vector, anchoring moisture-resistant and grease-resistant formulation capabilities for premium food-contact segments.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit WestRock |
| Mondi Group |
| Stora Enso |
| Georgia-Pacific LLC |
| Sappi Limited |
| Billerud AB |
| Nine Dragons Paper (Holdings) Limited |
| Nordic Paper |
| Others |
Value Network & Pricing Analysis
EU REACH compliance gates simultaneously separate credentialed suppliers from commodity tiers and compress price premiums for certified unbleached kraft grades entering food-contact channels. This dual-gating mechanism concentrates pricing power among FSC-certified integrated producers while squeezing margins for uncertified converters facing qualification barriers.
Pricing Analysis
Cost-plus contracts indexed to northern European softwood pulp benchmarks dominate transactional arrangements between Rhine-Ruhr converters and integrated linerboard suppliers. Three-tier pricing structure across FSC-certified premium, standard virgin-fiber, and recycled-content economy levels reflects certification investment and barrier performance differentiation. Pricing pressure stems from energy-intensive kraft pulping economics that converters cannot fully pass through to box pricing. Small-to-mid-sized independent box plants exhibit highest price sensitivity due to limited volume leverage and single-source dependencies.
Supply Chain Analysis
Inbound logistics costs from Baltic Sea port congestion and container availability constraints on Asia-Europe trade lanes compress landed margins for specialty kraft imports. Supply concentrates in Sweden, Finland, and Germany where integrated pulp-to-board infrastructure draws from regional timber basins. Raw material dependencies center on northern European softwood pulp, starch adhesives, and barrier coating chemistries. Single-source vulnerability runs through concentrated linerboard supply from Scandinavian integrated mills. Distribution runs through converter clusters in North Rhine-Westphalia serving pan-European fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EFSA, and GB standards creates service-layer niches where specialized compliance advisory and rapid certification support remain under-developed. This demand-side shift rewards players bridging qualification gaps between virgin-fiber producers and export-bound converters.
For Market Incumbents: Consolidate backward integration into captive softwood pulp supply to defend against recycled-fiber substitution in non-contact applications. Anchor FSC chain-of-custody certification investments as a non-negotiable procurement criterion for pan-European retail grocery accounts. Prioritize capacity repositioning toward moisture-resistant specialty grades where barrier performance commands sustainable premium positioning.
For New Entrants and Emerging Players: Digital print compatibility services for short-run craft food brands represent an under-served layer where incumbent mills lack flexible production scheduling. Target central European pharmaceutical cold-chain expansion with insulated shipping container solutions combining structural rigidity and moisture resistance. Deploy hybrid flexo-digital press partnerships as the primary go-to-market angle to bypass legacy corrugator width constraints.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nanocellulose-reinforced coating pilot facilities and specialty barrier formulation R&D. Long-term viability favors integrated producers with timberland access and converted packaging network control over standalone board mills. Monitor ECHA enforcement milestones on fluorinated greaseproof chemistries as the critical signal for alternative formulation qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softwood Pulp Supply | Captive timberland access insulates International Paper from northern European supply constraints and energy cost volatility. |
| FSC Chain-of-Custody Certification Investment | Mandatory credentialing for French and Belgian retail grocery procurement bifurcates supplier tiers into premium and commodity pools. |
| Nanocellulose Barrier Coating Scale-Up | Scandinavian pilot programs preserve repulpability while matching polyethylene-laminated performance for freezer-grade food contact. |
| Digital Print Compatibility Development | Water-based ink adhesion improvements enable short-run customization for craft food brands through hybrid flexo-digital presses. |
| Pharmaceutical Cold-Chain Packaging Expansion | Insulated shipping containers for temperature-sensitive biologics intersect structural rigidity and moisture resistance requirements. |
Research Methodology
Operator-level perspectives from corrugated plant managers, retail grocery procurement directors, FSC certification auditors, and specialty coating formulators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through trade association filings, customs import records, and EU regulatory enforcement databases. Bottom-up volume estimates from converter throughput data triangulated against top-down pulp production statistics and packaging demand indices.
Sensitivity analysis tested forecast robustness across alternative scenarios for softwood pulp cost trajectories and REACH compliance timeline acceleration. Segmentation modeling spanned product grade tiers, end-use applications, thickness constructions, and regional regulatory clusters. CAGRs derived from trend extrapolation of historical shipment data adjusted for identified inflection drivers. Industry-specific inputs included e-commerce fulfillment hub expansion rates and Verpackungsgesetz recycling quota implementation progress.
Underlying assumptions cover stable northern European timber supply, gradual fluorinated treatment phase-out, and continued e-commerce parcel growth, with deviation risk concentrated in energy cost volatility and regulatory enforcement acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Paper Canisters Market