
 Hanging Box Market | 2026-2036
Hanging Box Market Size, Share, and Industry Trends Forecast 2026-2036
Hanging Box Market Analytics
FSC chain-of-custody certification is rotating as the primary gatekeeper for supplier qualification in European retail supply chains. WestRock Company leverages its integrated pulp-to-box infrastructure across the southeastern United States to sustain volume leadership in corrugated hanging displays. Smurfit Kappa Group anchors its competitive position through specialized kraftliner grades engineered for die-cut hanging tabs in grocery environments.
A hanging box is a suspended storage or display container engineered with integrated apertures, hooks, or fold-out tabs that enable vertical mounting on rods, rails, or peg systems, typically fabricated from corrugated board between 200–400 gsm or extruded polypropylene sheet. The structure serves dual functions: protective containment during transit and immediate shelf-ready presentation without secondary unpacking. Plastic hanging boxes lead in mass-market retail due to moisture resistance and repeated handling durability, while wood variants command premium positioning in boutique household segments where tactile finish and natural grain justify higher unit economics. Fabric-based designs represent the fastest-expanding category, driven by fold-flat shipping profiles that reduce inbound freight cube for direct-to-consumer brands.
The EU Packaging and Packaging Waste Regulation and the FDA's indirect food contact substance notifications govern material migration limits and recyclability claims across respective jurisdictions, with California's SB 54 extended producer responsibility framework adding state-level compliance complexity for North American suppliers. ISO 18601 series standards on packaging and the environment provide the technical baseline for lifecycle assessments that major retailers now mandate in vendor scorecards. Stakeholders must monitor evolving extended producer responsibility fee structures and bio-based content thresholds as these mechanisms increasingly determine which material platforms retain shelf access in priority retail channels.
Market Dynamics
E-commerce fulfillment centers are driving collapsible hanging storage systems into automated assembly workflows, compressing traditional corrugated display lead times while EU Packaging and Packaging Waste Regulation mandates force material recovery redesigns.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material recovery requirements for display-ready containers are accelerating closed-loop fiber sourcing across European retail supply chains.
- Automated box assembly lines:German retail fixture manufacturers are scaling robotic die-cutting and tab-forming equipment to reduce per-unit labor content.
- Fold-flat shipping profiles:Direct-to-consumer brands are adopting fabric-based hanging boxes to minimize inbound freight cube and last-mile packaging waste.
Market Restraints
- Pulp price volatility:Kraftliner input costs fluctuate with Nordic softwood fiber availability, squeezing margin predictability for corrugated specialists.
- Supply concentration in southeastern United States:Integrated pulp-to-box infrastructure creates geographic dependency risk for North American volume.
- Extruded polypropylene substitution:Plastic hanging boxes threaten fiber-based formats in moisture-exposed retail environments.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic manufacturing incentives could localize production for Asian e-commerce fulfillment networks.
- Dual carbon goals in China:Bio-based content thresholds are creating preferential shelf access for certified renewable fiber containers.
- California SB 54 extended producer responsibility:State-level compliance frameworks reward recyclable mono-material designs with reduced fee structures.
Industry Challenges
- FSC chain-of-custody certification timelines:Supplier qualification delays average 8-14 months, blocking access to European retail vendor scorecards.
- Legacy ERP integration with automated assembly:Die-cut hanging tab production requires real-time nesting software that conflicts with existing MRP systems.
- Specialized kraftliner formulation expertise:Grocery-grade tear resistance specifications exceed standard corrugated training curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hanging Box Market |
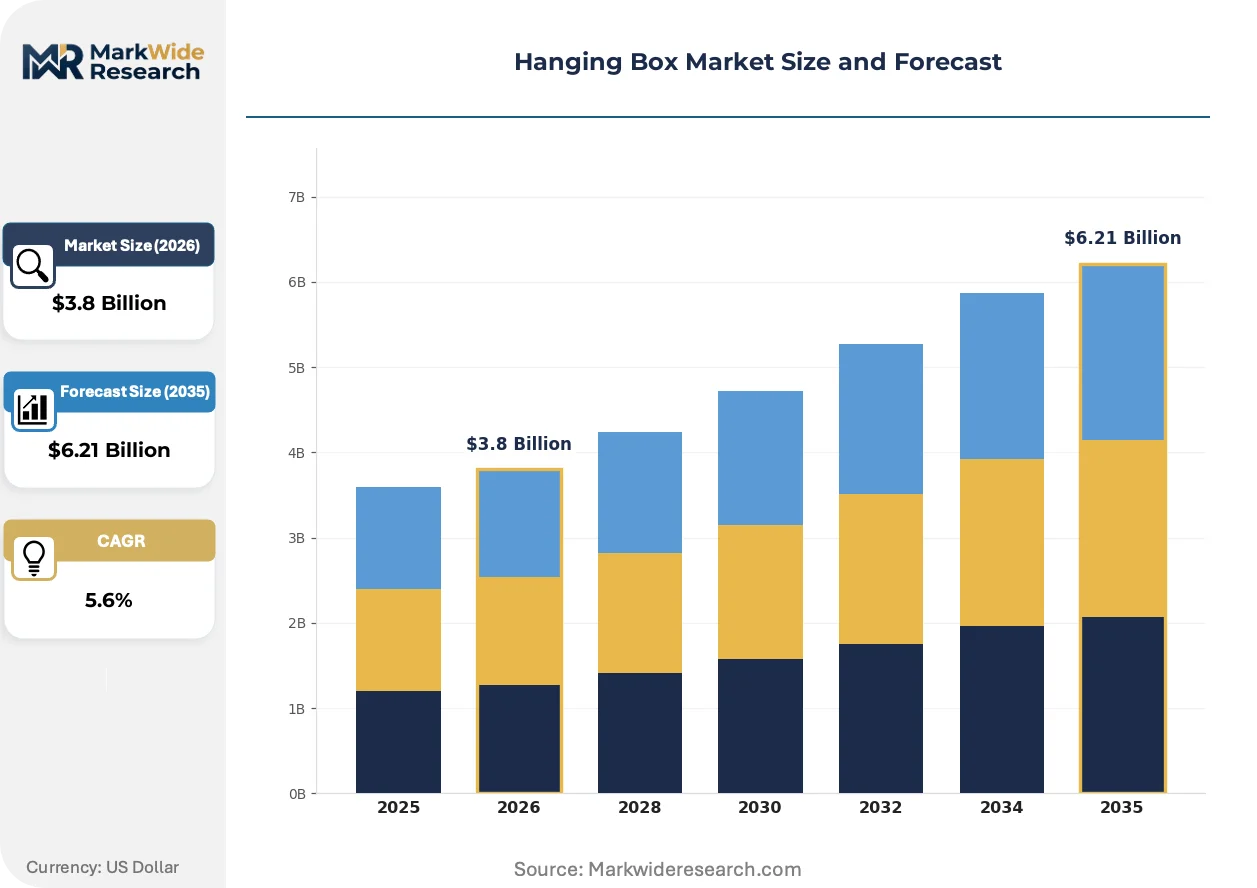
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Wood, Fabric End User: Households, Retail Stores, Offices, Schools Size: Small, Medium, Large, Extra Large Design Style: Modern, Rustic, Vintage, Minimalist |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, DS Smith, Mondi Group, Packaging Corporation of America, Oji Holdings Corporation, Nine Dragons Paper Holdings Limited, Rengo Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hanging Box Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are converging to redefine hanging box performance specifications and supplier qualification pathways across retail supply chains.
Water-based barrier coatings are supplanting polyethylene extrusion layers in corrugated hanging tabs. German supermarket chains are piloting these formats for fresh produce displays. The shift is compressing plastic content thresholds while maintaining moisture resistance for high-humidity cold chain environments.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from food-contact hanging boxes. Reformulation costs are concentrating among kraftliner producers with in-house chemical laboratories. Bakery and deli segments in France and Benelux are accelerating acceptance testing for fluorine-free alternatives.
Consolidated vendor scorecards now bundle ISO 18601 lifecycle assessments with FSC certification requirements. Mass-market retailers are rejecting suppliers lacking documented environmental product declarations. This preference compression is most visible in German and Austrian hard discount channels where private-label penetration exceeds 70 percent.
Hanging Box Market Segmentation
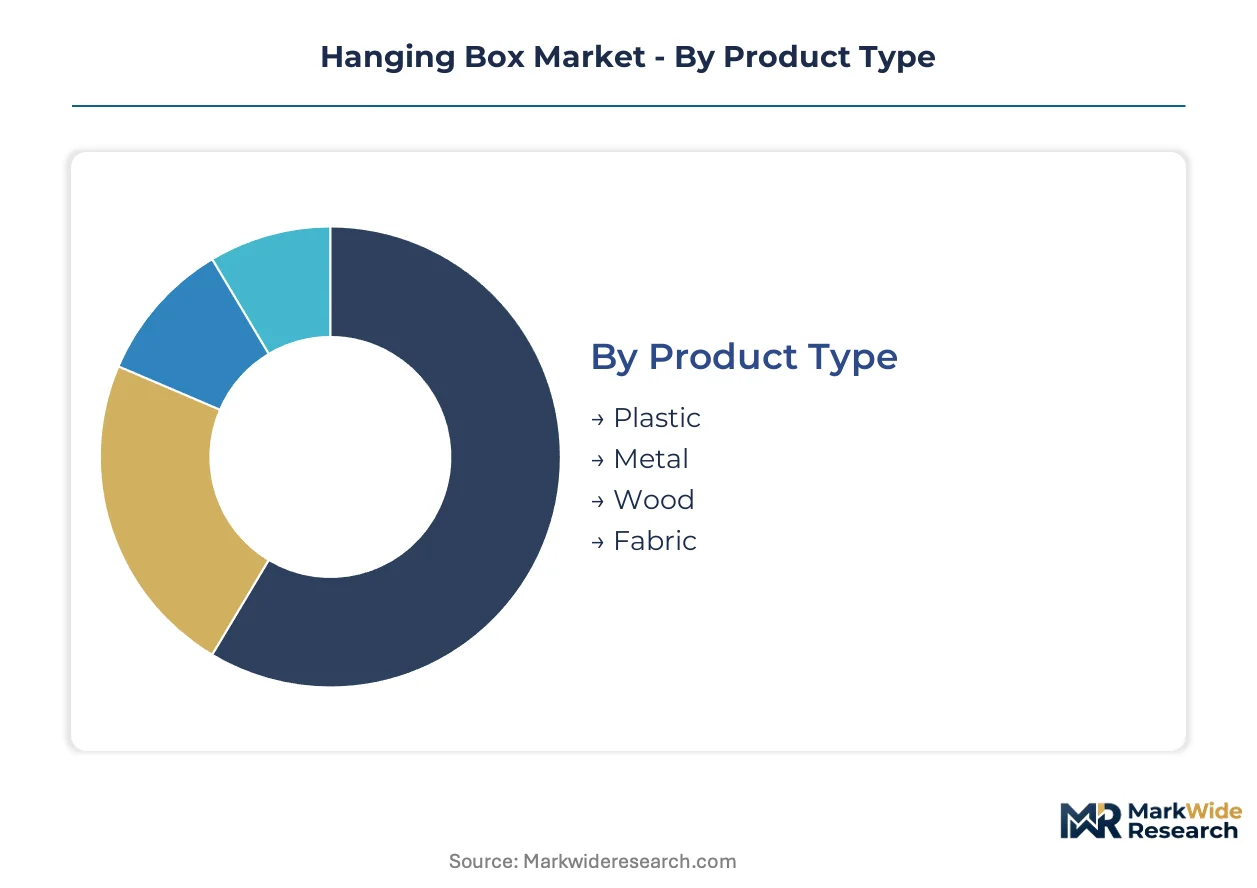
Segmentation in the Hanging Box Market reveals how material platforms and use-case specifications determine competitive vulnerability to substitutes. Each dimension exposes different pressure points where corrugated fiber faces displacement from extruded polymers or fabric alternatives.
Product Type:
Plastic hanging boxes exert the strongest substitution pressure on legacy fiber formats, particularly in moisture-exposed retail environments where polyethylene and polypropylene barriers outperform uncoated paperboard.
- Plastic:Extruded polypropylene and polyethylene terephthalate formulations deliver moisture resistance and repeated handling durability for mass-market retail displays. German supermarket chains are piloting these formats for fresh produce sections where cold chain humidity degrades fiber alternatives.
- Fabric:Non-woven polypropylene and canvas constructions fold flat for inbound shipping, reducing freight cube by 60-70% versus assembled rigid formats. Direct-to-consumer brands in California and New York are adopting these for closet and pantry organization kits.
- Metal:Powder-coated steel wire frames support heavy-load applications in industrial stockrooms and garage storage systems.
- Wood:Solid pine and bamboo variants command premium positioning in boutique household segments where tactile grain justifies higher unit economics.
Plastic anchors the volume base while fabric gains share at the steepest rate.
End User:
Application context determines whether protective containment or immediate shelf-ready presentation dominates specification requirements.
- Retail Stores:Corrugated hanging displays with die-cut tabs serve dual functions—transit protection and pegboard-ready merchandising—driving automated assembly adoption in German fixture manufacturing.
- Households:Fabric and wood variants concentrate in closet organization and decorative storage where aesthetic finish overrides logistics efficiency.
- Offices:Metal mesh and plastic combinations address document and supply organization in hybrid workspace configurations.
- Schools:Lightweight polypropylene withstands institutional handling cycles in classroom supply distribution.
Retail stores dominate procurement volumes while households show the most rapid format diversification.
Size:
Dimensional tiering aligns with freight optimization constraints and retail fixture standardization.
- Small:Compact formats under 15 centimeters suit jewelry, cosmetics, and hardware components for pegboard density maximization.
- Medium:Standard 20-30 centimeter widths match European retail fixture spacing norms and automated case packing equipment.
- Large:Expanded formats accommodate bulk merchandise and multi-pack displays in warehouse club channels.
- Extra Large:Oversized constructions require reinforced hanging tabs and specialized kraftliner grades for load-bearing integrity.
Medium sizes capture the highest shipment frequency while extra large formats expand most quickly in e-commerce fulfillment applications.
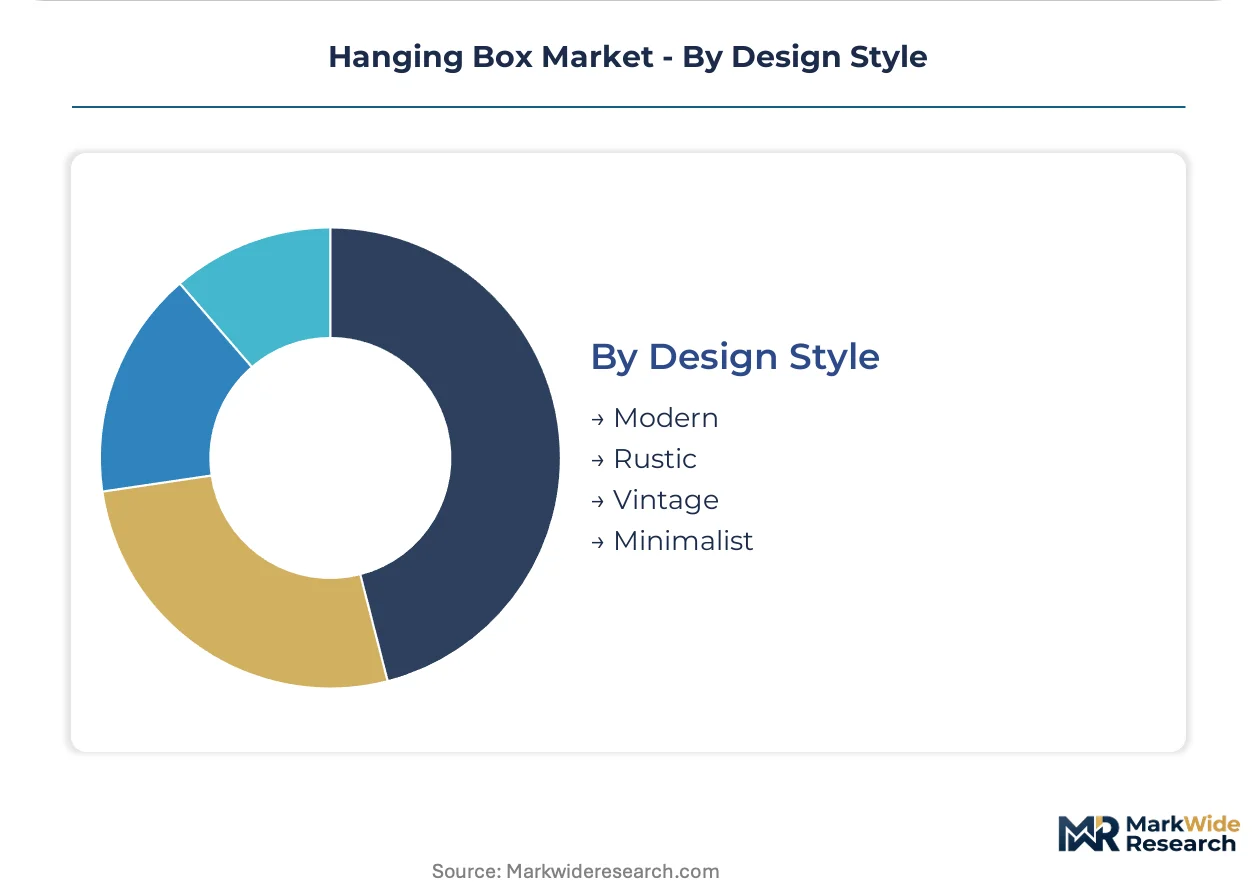
Design Style:
Aesthetic differentiation creates pricing stratification across certification-grade and finish-tier boundaries.
- Modern:Clean lines and matte finishes align with Scandinavian-influenced retail environments and private-label hard discount channels in Germany and Austria.
- Minimalist:Reduced material profiles and neutral palettes appeal to urban direct-to-consumer brands emphasizing sustainability credentials.
- Rustic:Distressed wood and vintage metal treatments target boutique household segments with tactile authenticity requirements.
- Vintage:Retro-styled hardware and patina finishes serve specialty retail and gift shop channels.
Modern styling commands the broadest retail placement while minimalist designs are climbing the fastest in online-native brand portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redrawing procurement geography across the hanging box supply chain. Material recovery mandates and extended producer responsibility fee structures are concentrating investment in jurisdictions with integrated fiber infrastructure and automated assembly capabilities.
Germany
Retail fixture manufacturers in Baden-Württemberg and North Rhine-Westphalia are scaling robotic die-cutting lines for corrugated hanging displays. The EU Packaging and Packaging Waste Regulation's material recovery thresholds are accelerating closed-loop kraftliner sourcing from domestic mills. Stuttgart-based equipment suppliers are shipping tab-forming machinery to discount grocery chains across the DACH region.
United States
Southeastern pulp-to-box infrastructure sustains volume leadership in corrugated hanging displays despite geographic concentration risk. California's SB 54 extended producer responsibility framework rewards recyclable mono-material designs with reduced fee structures versus multi-layer alternatives. Charlotte and Atlanta logistics corridors handle outbound distribution to mass-market retail consolidation centers.
China
Dual carbon goals are creating preferential shelf access for certified renewable fiber containers in domestic e-commerce channels. The Ministry of Ecology and Environment bio-based content thresholds favor suppliers with documented chain-of-custody credentials. Yangtze River Delta converters are retrofitting lines for water-based barrier coatings to serve European export specifications.
India
The PLI scheme for packaging is incentivizing domestic manufacturing localization for Asian e-commerce fulfillment networks. BIS standards on recycled content are tightening specification windows for imported display-ready containers. Maharashtra and Gujarat corrugated specialists are piloting automated assembly for fold-flat fabric hanging box formats.
France
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from food-contact hanging boxes. ANSM compliance timelines are accelerating fluorine-free alternative acceptance testing in bakery and deli segments. Île-de-France retail headquarters are consolidating vendor scorecards that bundle ISO 18601 lifecycle assessments with FSC certification requirements.
Hanging Box Market Competitive Landscape
Player mix skews toward integrated pulp-to-box conglomerates with captive fiber supply and specialized kraftliner formulators serving grocery-grade tear resistance specifications. The competitive structure concentrates around three strategic archetypes: integrated fiber producers controlling upstream pulp assets, specialized converters with die-cut tab engineering expertise, and automated assembly equipment suppliers capturing value from labor substitution trends. Capacity expansion in water-based barrier coating lines and strategic partnerships between corrugated specialists and retail fixture automation vendors represent the dominant competitive moves reshaping supplier positioning.
Within the integrated fiber tier, WestRock Company and Smurfit Kappa Group exemplify divergent geographic anchoring strategies. WestRock's southeastern United States infrastructure leverages proximity to softwood fiber sources and deepwater export terminals. Smurfit Kappa's European base aligns with the regulatory complexity of EU Packaging and Packaging Waste Regulation compliance and REACH reformulation requirements. International Paper Company occupies a position bridging North American scale with emerging market joint venture structures, representing the multinational conglomerate archetype that competes through volume leverage and geographic optionality rather than specialized formulation expertise.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith |
| Mondi Group |
| Packaging Corporation of America |
| Oji Holdings Corporation |
| Nine Dragons Paper Holdings Limited |
| Rengo Co. Ltd. |
| Others |
Value Network & Pricing Analysis
FSC chain-of-custody certification gates both supplier qualification and price differentiation simultaneously, separating certified renewable fiber containers from uncertified alternatives in European retail vendor scorecards while compressing margins for producers lacking documented environmental product declarations.
Pricing Analysis
Cost-plus contracts with Nordic softwood fiber indexation dominate kraftliner supply agreements, anchoring corrugated hanging box pricing to pulp futures volatility. Three-tier pricing structure across FSC-certified premium, standard recycled-content, and economy virgin-fiber grades reflects certification investment recovery timelines. Pricing pressure stems from extruded polypropylene substitution in moisture-exposed retail environments. Mass-market discount grocery chains exhibit highest price sensitivity, while boutique household segments absorb premium wood and fabric format markups.
Supply Chain Analysis
Germany and the United States anchor automated die-cutting and tab-forming equipment production for corrugated hanging displays. The supply chain draws from Nordic softwood pulp, Yangtze River Delta water-based coating chemicals, and Baden-Württemberg robotics components. Single-source vulnerability concentrates in southeastern United States integrated pulp-to-box infrastructure. Distribution runs through Stuttgart-based machinery vendors, Charlotte logistics corridors, and direct-to-consumer fold-flat fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated mass-market retailers bundling ISO 18601 lifecycle assessments with FSC certification requirements in vendor scorecards, fragmenting supplier access for uncertified producers.
For Market Incumbents: Fortify automated assembly capabilities through robotic die-cutting line investments in Germany and the southeastern United States to offset labor content compression. Deepen captive kraftliner supply through backward integration into Nordic softwood fiber sourcing. Prioritize water-based barrier coating R&D to defend against polyethylene extrusion layer substitution in fresh produce cold chain applications. For New Entrants and Emerging Players: Fabric-based fold-flat shipping profiles represent an underserved service-layer gap where incumbent corrugated specialists under-serve direct-to-consumer brands seeking inbound freight cube reduction. Target California and New York closet organization kit segments with non-woven polypropylene constructions. Pursue white-label partnerships with e-commerce fulfillment centers lacking automated box assembly integration. For Investors and Strategic Acquirers: California SB 54 extended producer responsibility implementation reshapes the acquisition landscape, rewarding mono-material recyclable designs with reduced fee structures versus multi-layer alternatives. Long-term viability favors specialized converters with die-cut tab engineering expertise and documented chain-of-custody credentials. Monitor bio-based content threshold enforcement in China as the inflection signal for preferential shelf access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Assembly Line Deployment | Robotic die-cutting in Baden-Württemberg compresses per-unit labor content for discount grocery chains. |
| Water-Based Barrier Coating Scale-Up | Yangtze River Delta retrofitting serves EU Packaging and Packaging Waste Regulation compliance specifications. |
| FSC Chain-of-Custody Certification | Documented credentials unblock access to German and Austrian hard discount vendor scorecards. |
| Fabric Format Manufacturing Localization | Maharashtra and Gujarat piloting addresses PLI scheme incentives for Asian e-commerce networks. |
| Specialized Kraftliner Formulation Investment | In-house chemical laboratories accelerate fluorine-free grease-resistant treatment acceptance testing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across retail fixture manufacturers, corrugated converters, kraftliner producers, e-commerce fulfillment center procurement managers, and automated assembly equipment vendors. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, BIS standards documentation, FDA indirect food contact substance notifications, SEC 10-K disclosures from integrated pulp-to-box conglomerates, and customs records tracking Nordic softwood fiber trade flows. Bottom-up shipment data triangulated against top-down retail fixture investment surveys.
Across the projection horizon, the analytical framework modeled material platform segmentation, end-use application context, dimensional tiering, and design style certification grade. CAGRs derived from correlated regression against retail automation capital expenditure indices and e-commerce fulfillment center square footage expansion. Industry-specific forecast inputs incorporated EU extended producer responsibility fee structure evolution and bio-based content threshold enforcement patterns.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation, California SB 54, and REACH substance restriction regimes; material policy shifts would require re-modeling. Specific risks include pulp price volatility from Nordic softwood fiber availability disruptions, extruded polypropylene substitution acceleration, and FSC certification timeline delays blocking European retail access. Recalibration cycles align with material shifts in automated assembly adoption rates and water-based barrier coating commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market