
 Natural Sack Kraft Papers Market | 2026-2036
Natural Sack Kraft Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Sack Kraft Papers Market Foresight
European pulp mill curtailments in Finland and Sweden are rebalancing natural sack kraft paper availability across Atlantic trade lanes. Mondi plc leverages its integrated forestry operations to sustain virgin fiber supply security for high-tensile grades. Smurfit Westrock plc anchors North American volume through extensive containerboard co-location. Segezha Group PJSC dominates Russian and CIS markets with specialized extensible kraft production for cement packaging.
Natural sack kraft papers are unbleached, high-strength paper grades manufactured from long-fiber softwood pulp via the sulfate process, engineered to withstand multi-ton filling stresses in valve and open-mouth bag constructions. Basis weights typically range from 70 to 100 grams per square meter with tear indices exceeding 15 mN·m²/g, serving primary roles in powder and granular material containment across construction, food, and chemical supply chains. Biodegradable bags command premium positioning as brand owners face downstream compostability mandates, while FIBC formats experience fastest volume expansion driven by bulk agricultural export flows from Black Sea and South American origins. Barrier bags concentrate margin pools where polyethylene-free grease and moisture resistance satisfies emerging single-use plastic restrictions.
EU REACH and F-Gas Regulation frameworks govern chemical additives in pulp processing and restrict fluorinated barrier treatments, redirecting R&D toward bio-based coating alternatives. FDA food contact substance notifications and BIS certification requirements for food-grade kraft imports into India shape cross-border product qualification pathways. Stakeholders must monitor evolving extended producer responsibility schemes and fiber traceability standards to secure market access and avoid stranded inventory positions.
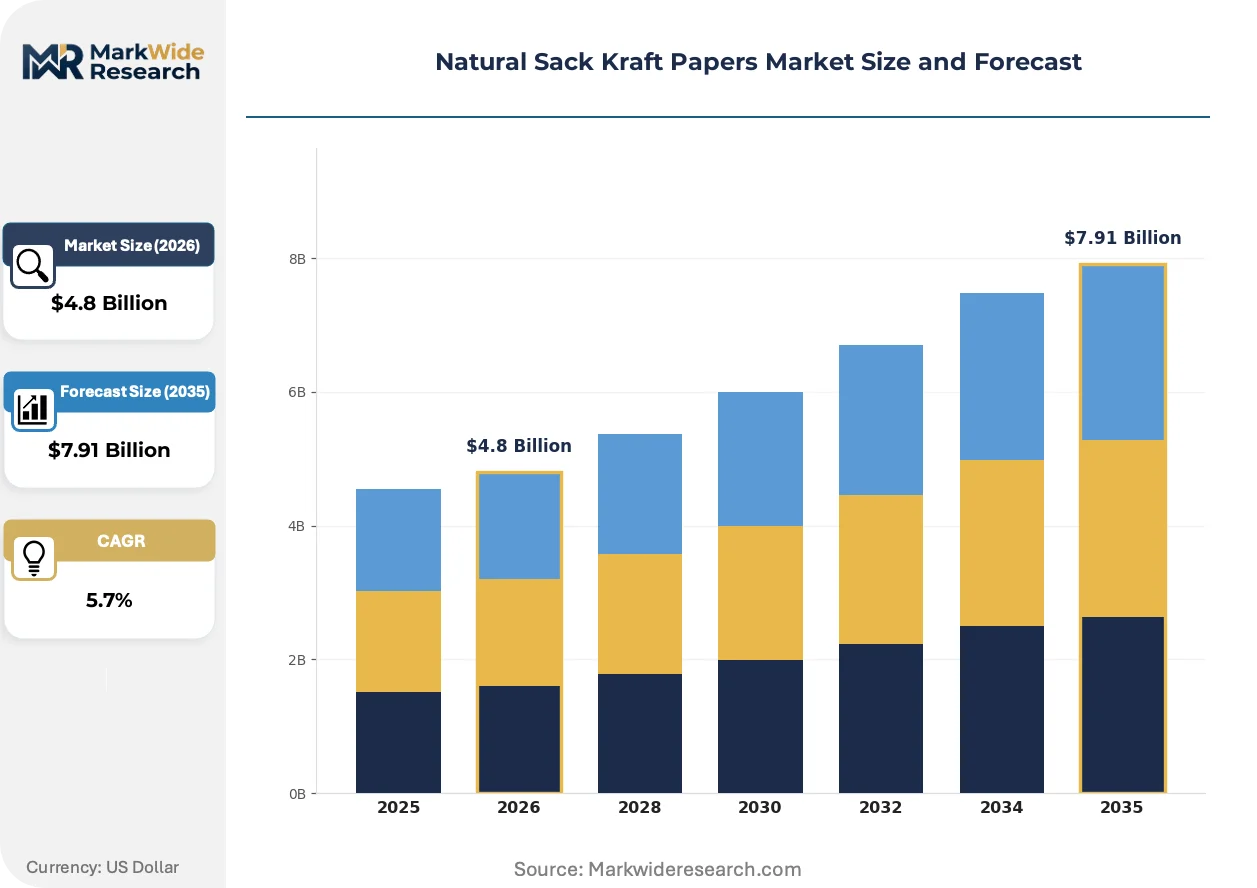
Market Dynamics
EU Green Deal packaging waste directives and China's dual carbon goals are compressing virgin fiber availability while cement producers across emerging economies accelerate procurement of biodegradable industrial packaging. This regulatory-supply tension is rebalancing trade flows and forcing capacity relocation toward integrated forestry operators.
Growth Catalysts
- FIBC Adoption for Agricultural Exports:Flexible intermediate bulk container formats are displacing traditional multi-wall bags for grain and seed shipments from Black Sea origins. Indian agricultural commodity exporters are driving fastest volume expansion in extensible kraft grades.
- EU Green Deal Directives:Extended producer responsibility schemes and compostability mandates are redirecting brand owner procurement toward biodegradable barrier bags. Food contact applications now require polyethylene-free grease resistance certifications.
- Dual Carbon Goals in China:Beijing's emissions reduction frameworks are tightening virgin fiber sourcing rules and accelerating domestic mill consolidation. Construction material producers face downstream pressure to demonstrate supply chain carbon intensity reductions.
Market Restraints
- Softwood Pulp Price Volatility:Long-fiber sulfate pulp costs fluctuate with energy input pricing and Nordic mill curtailments. Cement packaging margins compress when pulp futures spike above contract hedging bands.
- Finnish and Swedish Supply Concentration:European pulp mill curtailments in the Nordic region create Atlantic trade lane imbalances. Buyers face extended lead times when integrated operators prioritize captive consumption.
- Fluorinated Barrier Treatment Restrictions:EU F-Gas Regulation frameworks prohibit per- and polyfluoroalkyl substance coatings in food-contact applications. R&D timelines extend while bio-based alternatives achieve comparable moisture resistance.
Strategic Opportunities
- Underpenetrated Indian Food-Grade Segment:BIS certification requirements for imported kraft have created qualification barriers that domestic integrated mills can exploit. Local production avoids cross-border compliance delays and currency exposure.
- Valve Bag Automation in Construction:High-speed filling equipment convergence with extensible kraft formulations enables 25-kilogram cement bag throughput improvements. Turkish and Saudi Arabian construction material producers are piloting automated lines.
- Bio-Based Coating Technology Convergence:Cellulose nanofibril and chitosan barrier treatments are approaching cost parity with synthetic alternatives. Pilot scale production in Brazilian and Indonesian mills targets EU export qualification.
Industry Challenges
- Extended BIS Certification Timelines:Indian food-grade import approvals require 12-18 month testing cycles for migration and heavy metal compliance. Inventory stranding risk rises when specifications shift mid-qualification.
- Valve Bag Converting Equipment Capex:Multi-wall bag production lines for high-tensile grades require specialized corrugating and bottomer machinery. Mid-tier converters face financing constraints for 4-6 million euro installations.
- Legacy ERP Integration with Traceability Systems:Fiber provenance documentation for EU due diligence directives demands blockchain or RFID overlay on existing MRP platforms. Implementation complexity delays supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Sack Kraft Papers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FIBC, Biodegradable Bags, Barrier Bags, Laminated Bags Application: Agricultural Packaging, Food Packaging, Industrial Packaging, Retail Packaging End User: Food Manufacturers, Chemical Producers, Retailers, Logistics Providers Packaging Type: Flat Bags, Gusseted Bags, Pouch Bags, Multiwall Bags |
| Companies Covered | Mondi plc, Smurfit Westrock plc, Segezha Group PJSC, International Paper Company, Billerud AB, Stora Enso Oyj, Georgia-Pacific LLC, Nordic Paper Holding AB, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Sack Kraft Papers Market Shifts & Advancements
Barrier coating chemistry and filling automation are converging to displace multi-material packaging in powder and granular applications. Three developments are compressing traditional supply chain configurations and opening premium positioning for compliant producers.
Cellulose nanofibril barrier coatings are rewriting moisture and grease resistance specifications for food-contact sack kraft. European confectionery and dry ingredient packers are qualifying these polyethylene-free alternatives at accelerated pace. The technology is compressing synthetic film lamination demand and enabling compostability certification premiums.
EU F-Gas Regulation amendments are prohibiting fluorinated treatments in pulp processing and final bag constructions. Industrial consequence includes forced R&D redirection toward bio-based coating platforms and qualification delays for incumbent suppliers. Food-grade applications in Germany and France face tightest compliance windows with Q4 2025 enforcement milestones.
Cement producers are consolidating procurement around automated valve bag filling lines that demand precise extensibility and tensile consistency. Turkish construction material giants are displacing open-mouth formats with high-speed systems requiring customized kraft specifications. This equipment-driven specification shift concentrates volume with mills capable of tight basis weight control and lot traceability.
Natural Sack Kraft Papers Market Segmentation
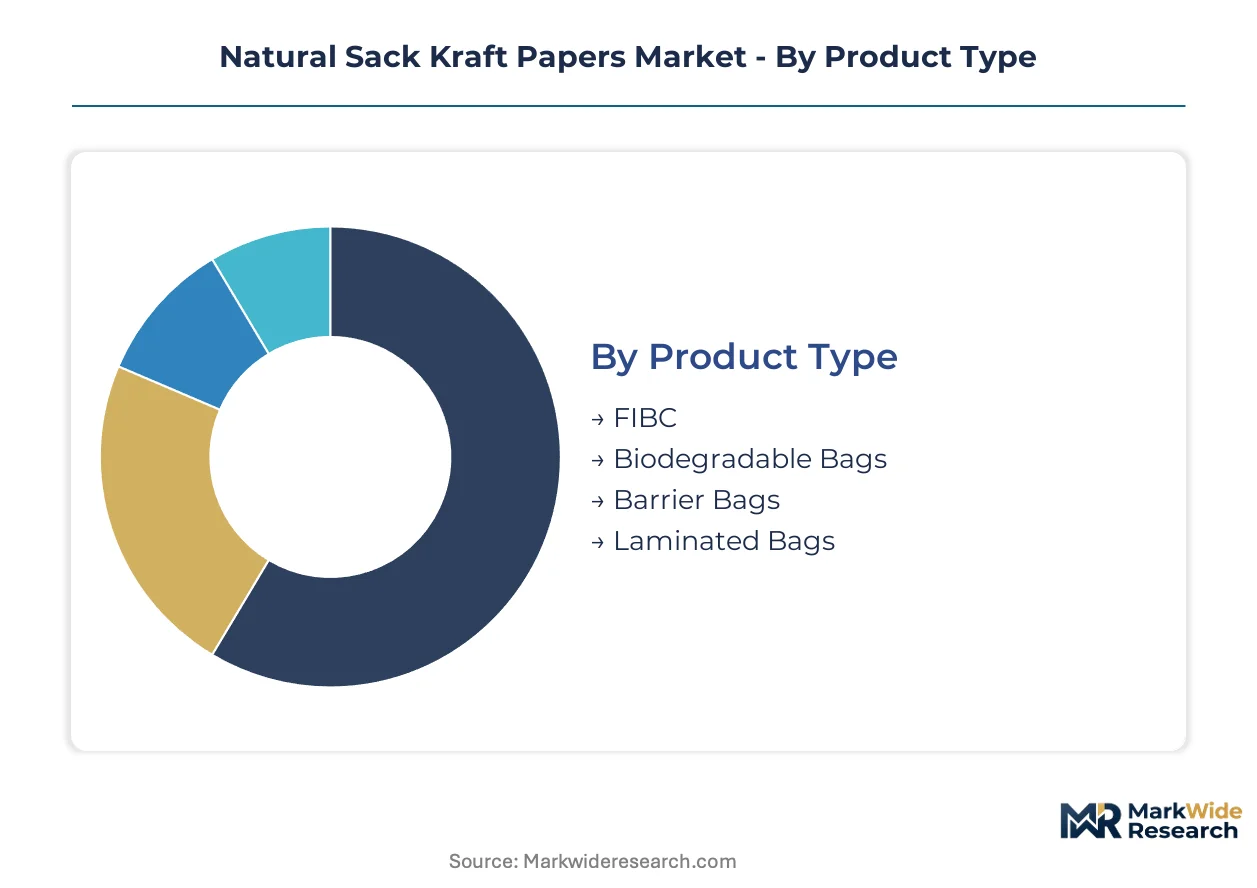
Natural sack kraft paper specifications diverge sharply across filling equipment, regulatory exposure, and shelf-life requirements. Procurement teams segment specifications by load-bearing capacity, barrier performance, and compostability certification to align with downstream compliance mandates and automation investments.
Product Type:
Equipment upgrade cycles and filling-line automation are driving specification shifts across product categories, with cement and agricultural producers retiring legacy multi-wall formats.
- FIBC:Flexible intermediate bulk containers utilize extensible kraft grades engineered for 500-2000 kilogram payloads with woven polypropylene reinforcement layers. Indian grain exporters and Black Sea agricultural commodity shippers are displacing traditional 50-kilogram multi-wall bags with FIBC formats to reduce handling costs and container loading times.
- Biodegradable Bags:Unbleached sulfate kraft constructions with bio-based coatings achieve industrial compostability certification under EN 13432 and ASTM D6400 standards. EU Green Deal extended producer responsibility schemes are redirecting French and German food brand procurement toward these polyethylene-free alternatives.
- Barrier Bags:Grease and moisture-resistant grades employ cellulose nanofibril or chitosan treatments to replace fluorinated and synthetic film laminations.
- Laminated Bags:Kraft-polyethylene extrusion laminations retain cost advantage in moisture-critical cement and chemical applications where compostability is not mandated.
Volume placements concentrate in FIBC for bulk agricultural flows; the faster expansion belongs to biodegradable bags as EU compostability deadlines approach.
Application:
Cost-tier differentiation separates commodity construction grades from certified food-contact specifications with migration testing and heavy metal documentation requirements.
- Agricultural Packaging:Seed, grain, and fertilizer applications dominate tonnage consumption with standard 70-80 gsm unbleached grades. Brazilian soybean exporters and Ukrainian wheat traders are consolidating procurement around FIBC-compatible extensible kraft with specific elongation characteristics for automated filling.
- Food Packaging:Dry ingredients, confectionery, and specialty flour demand grease-resistant barrier treatments and FDA or BIS food contact substance notifications. Indian domestic mills are capturing share from imports by qualifying local production under compressed BIS certification timelines.
- Industrial Packaging:Cement, chemicals, and minerals utilize high-tensile valve and open-mouth constructions with tear indices exceeding 15 mN·m²/g.
- Retail Packaging:Consumer-facing formats with printed branding and window features serve specialty food and agricultural premium positioning.
Industrial packaging maintains the largest volume footprint; food packaging is climbing the fastest as polyethylene-free barrier coatings achieve cost parity.
End User:
Customer-type segmentation reveals divergent procurement sophistication, with integrated multinationals demanding lot traceability and mid-tier converters prioritizing price stability.
- Food Manufacturers:Bakeries, confectioners, and dry ingredient processors specify migration-compliant kraft with cellulose-based grease resistance. German and French food contact regulations are accelerating qualification of bio-coated alternatives ahead of Q4 2025 enforcement milestones.
- Chemical Producers:Fertilizer, pigment, and construction chemical manufacturers prioritize tensile consistency and valve bag runnability over barrier performance. Turkish cement giants are piloting automated filling lines that demand precise basis weight control and extensibility specifications.
- Retailers:Private-label and branded food retailers are consolidating supplier bases around compostability certification and blockchain traceability documentation.
- Logistics Providers:Third-party packaging and bulk handling contractors specify FIBC formats for agricultural commodity transshipment efficiency.
Chemical producers anchor volume demand; food manufacturers are gaining share fastest as compostability mandates tighten.
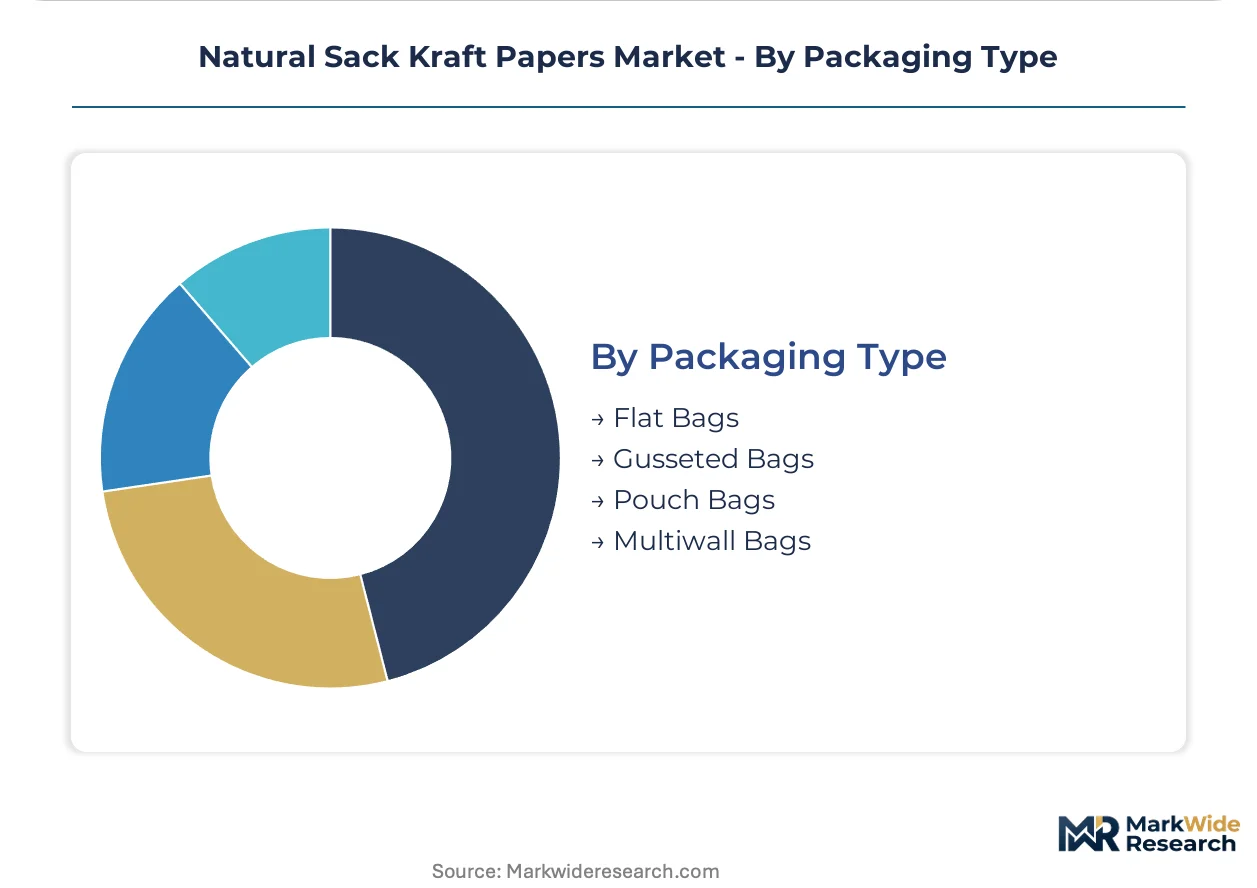
Packaging Type:
Geography-of-use patterns differentiate flat and gusseted formats for palletized transport against valve constructions for high-speed automated filling.
- Flat Bags:Standard open-mouth constructions serve manual filling operations in emerging market cement and agricultural applications with lowest capital equipment requirements.
- Gusseted Bags:Side-folded designs maximize pallet cube efficiency for export grain and seed shipments from Black Sea and South American origins.
- Pouch Bags:Stand-up and block-bottom formats with resealable features address retail-facing specialty food and premium agricultural positioning.
- Multiwall Bags:Layered kraft constructions with intermediate plies provide burst resistance for abrasive mineral and chemical filling.
Gusseted bags concentrate volume in export agricultural flows; multiwall formats are expanding most quickly in automated cement filling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Softwood pulp availability from Nordic forestry operations anchors production capacity across Atlantic and Pacific trade lanes. Integrated mill operators in Finland and Sweden curtail output during energy price spikes, redirecting procurement flows toward Russian and North American suppliers. Cement packaging demand concentrates in Turkey, India, and Brazil where construction material producers automate filling lines.
United States
Southeastern containerboard complexes supply high-tensile grades for domestic cement and agricultural markets. FDA food contact substance notifications govern kraft imports for dry ingredient packaging. Georgia-Pacific operates integrated pulp-to-paper facilities across the Gulf Coast serving chemical and construction sectors.
Germany
EU Green Deal extended producer responsibility schemes accelerate compostable bag procurement from confectionery and bakery segments. F-Gas Regulation amendments prohibit fluorinated barrier treatments in food-contact applications. Bavarian packaging converters pilot cellulose nanofibril coating lines for grease-resistant specifications.
China
Dual carbon goals tighten virgin fiber sourcing rules and consolidate domestic mill capacity around state-owned forestry operations. Construction material producers face downstream pressure to demonstrate supply chain carbon intensity reductions. Shandong Peninsula clusters specialize in extensible kraft for automated valve bag filling systems.
India
FIBC adoption for grain and seed exports drives fastest volume expansion in extensible kraft grades. BIS certification requirements for imported food-grade kraft create qualification barriers that domestic integrated mills exploit. Maharashtra-based converters capture share from European suppliers by qualifying local production under compressed timelines.
Brazil
Soybean and coffee exporters displace traditional multi-wall bags with FIBC formats to reduce container loading costs. ANVISA food contact regulations align with FDA migration testing standards for dry ingredient shipments. São Paulo state mills develop bio-based coating platforms targeting EU export qualification.
Natural Sack Kraft Papers Market Competitive Landscape
Global majors compete with regional champions across integrated forestry operations and specialized converting capabilities. The vendor base stratifies into three tiers: multinational pulp-to-paper operators with captive fiber supply, mid-scale regional specialists in extensible grades, and commodity converters dependent on spot market pulp. Strategic moves concentrate on backward integration into forestry assets and capacity relocation toward emerging market demand centers.
Within the integrated operator tier, Mondi plc and Smurfit Westrock plc exemplify scale-driven positioning through captive pulp supply and extensive containerboard co-location. Segezha Group PJSC occupies a specialized regional anchor role in Russian and CIS markets with dedicated extensible kraft production for cement packaging. Nordic Paper Holding AB represents the mid-tier specialist archetype concentrated on high-tensile grades for industrial applications.
| Leading Market Players |
|---|
| Mondi plc |
| Smurfit Westrock plc |
| Segezha Group PJSC |
| International Paper Company |
| Billerud AB |
| Stora Enso Oyj |
| Georgia-Pacific LLC |
| Nordic Paper Holding AB |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between food-contact barrier kraft and commodity construction grades manifests in divergent pricing architectures and procurement network configurations across Atlantic and Pacific trade lanes. Premium polyethylene-free coatings with BIS or FDA food contact substance notifications command substantial markups over standard extensible grades for cement packaging, while integrated Nordic operators leverage captive pulp supply to resist margin compression during energy price spikes.
Pricing Analysis
Service bundling separates integrated mills offering lot traceability documentation and blockchain fiber provenance from commodity converters selling uncoated grades on spot indices. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, volume scale, and after-sales technical support intensity. Pricing pressure stems from softwood pulp futures volatility when Finnish and Swedish curtailments tighten long-fiber sulfate availability. Cement producers in Turkey and India exhibit highest price sensitivity due to thin construction material margins, while German confectionery brand owners prioritize compostability compliance over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle high-volume cement and agricultural demand, while specialized distributors serve mid-tier food-grade converters requiring technical qualification support. Production concentrates in Finland, Sweden, and Russia for virgin softwood pulp, with India and Brazil emerging as extensible kraft converting hubs. Supply chains rest on long-fiber sulfate pulp, bio-based coating chemistries, and woven polypropylene reinforcement inputs. Single-source vulnerability concentrates in Nordic pulp mill curtailments during energy price spikes, forcing buyers toward Russian Segezha Group or North American integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural sack kraft paper markets operate under pronounced supply constraint as Nordic energy costs and EU F-Gas Regulation compliance compress available capacity for food-contact grades, propping pricing power among integrated operators with captive forestry assets.
For Market Incumbents: Hedge against softwood pulp volatility through backward integration into forestry assets or long-term offtake contracts with Russian and North American suppliers. Defend market position by accelerating cellulose nanofibril barrier coating R&D ahead of Q4 2025 EU enforcement milestones, while consolidating converter relationships through bundled traceability documentation services that commodity competitors cannot replicate.
For New Entrants and Emerging Players: Begin with underpenetrated Indian food-grade segments where BIS certification barriers have stranded European imports and domestic integrated mills capture share through compressed qualification timelines. Target Maharashtra-based agricultural exporters demanding FIBC-compatible extensible kraft with specific elongation characteristics, leveraging local production to avoid cross-border compliance delays and currency exposure that burden incumbent European suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with Brazilian and Indonesian mills developing bio-based coating platforms given EU export qualification catalysts and accelerating polyethylene-free procurement from German and French food brand owners. Acquisition focus should center on mid-scale regional specialists with extensible kraft capabilities and existing forestry concessions. Watch for cellulose nanofibril coating cost parity achievement as the inflection signal for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Captive softwood pulp supply insulates Mondi and Smurfit Westrock from Nordic curtailment-driven price spikes. |
| Bio-Based Coating R&D Scale-Up | Cellulose nanofibril and chitosan platforms enable EU F-Gas Regulation compliance ahead of enforcement deadlines. |
| Automated Valve Bag Line Partnerships | Turkish cement producers piloting high-speed filling systems demand precise extensibility specifications from qualified mills. |
| BIS Certification Fast-Track Investment | Maharashtra-based converters capture Indian food-grade share by qualifying local production under compressed timelines. |
| Blockchain Traceability Overlay Deployment | Fiber provenance documentation satisfies EU due diligence directives and accelerates supplier onboarding for compliant producers. |
Research Methodology
Document review covered trade customs data, SEC 10-K filings from packaging majors, EU F-Gas Regulation amendments, and BIS certification requirement documents, complemented by interviews with plant managers at Nordic pulp mills, procurement leads at Turkish cement producers, technical R&D directors at barrier coating developers, and distribution channel partners across Indian agricultural export corridors. Primary fieldwork with industry stakeholders was validated against secondary sources including pulp futures pricing databases, forestry industry association reports, and food contact substance notification filings with FDA and BIS. Bottom-up volume modeling across grade tiers and applications was triangulated against top-down macroeconomic drivers.
Segment-level outputs across product type, application, end user, and packaging format dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of pulp-to-paper capacity additions, FIBC adoption curves in Black Sea and Indian agricultural export flows, and EU compostability mandate compliance timelines. Industry-specific forecast inputs incorporated energy price sensitivity of Nordic mill operating rates and cellulose nanofibril coating pilot scale production milestones.
Underlying measurement precision varies by segment; FIBC and biodegradable bag categories carry tighter precision than emerging barrier coating applications where pilot production data remains sparse. Forecasts reflect assumptions regarding Nordic energy price stabilization, EU enforcement timeline adherence, and Indian agricultural export growth trajectories. Periodic stress-testing of base assumptions is recommended given pulp commodity volatility and regulatory implementation uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market