
 Global Pancreatic Cancer Therapeutics and Diagnostics Market | 2026-2036
Global Pancreatic Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pancreatic Cancer Therapeutics and Diagnostics Market Foresight
ISO 13485 certification for in vitro diagnostic medical devices is bifurcating the competitive landscape between established manufacturers and emerging platform developers. Roche leverages its vertically integrated diagnostics-to-therapeutics pipeline to sustain leadership in companion diagnostic development. Bristol-Myers Squibb anchors its position through immuno-oncology portfolios aligned with biomarker-driven patient stratification. AstraZeneca competes by extending its presence in targeted therapy categories with established regulatory track records.
Pancreatic cancer therapeutics and diagnostics encompass systemic treatments and molecular detection platforms designed to address ductal adenocarcinoma, the predominant histological subtype characterized by KRAS mutation prevalence exceeding 90 percent and dense desmoplastic stroma that impairs drug penetration. The primary commercial purpose centers on extending survival intervals through early intervention and precision-matched therapy selection. Targeted therapy commands the deepest margin pools due to orphan drug pricing structures and narrow indication scopes. Liquid biopsy represents the fastest-expanding detection modality as blood-based circulating tumor DNA analysis displaces invasive tissue acquisition protocols. Diagnostic kits maintain volume leadership in routine monitoring applications across hospital-based pathology laboratories.
FDA breakthrough device designations and EMA accelerated assessment pathways compress development timelines while demanding robust biomarker validation datasets. The EU In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for companion diagnostics, elevating compliance costs for market entrants. ISO 15189 accreditation standards for medical laboratories shape procurement specifications across European and Asia-Pacific healthcare systems. Stakeholders must monitor evolving reimbursement frameworks for multi-cancer early detection tests as payors reassess coverage criteria for screening applications.
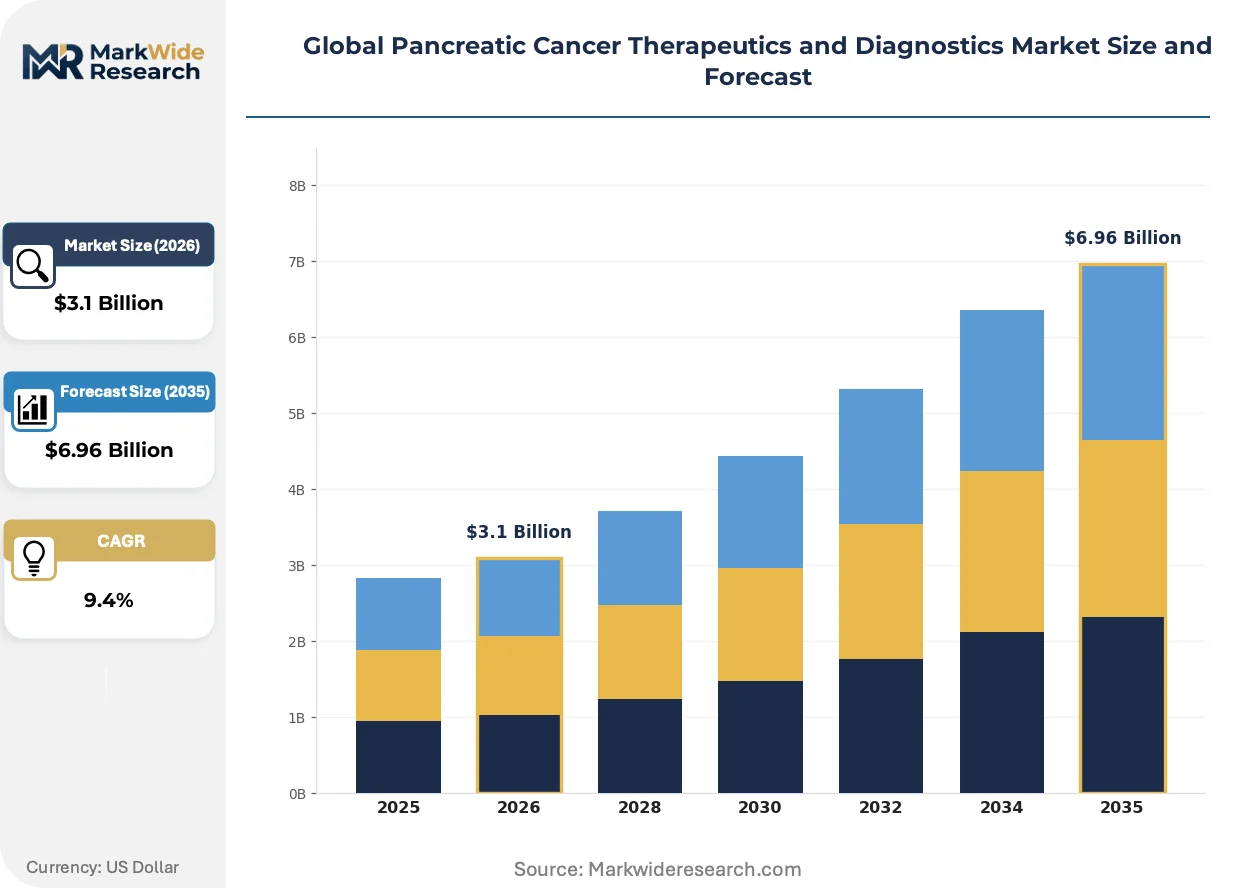
Market Dynamics
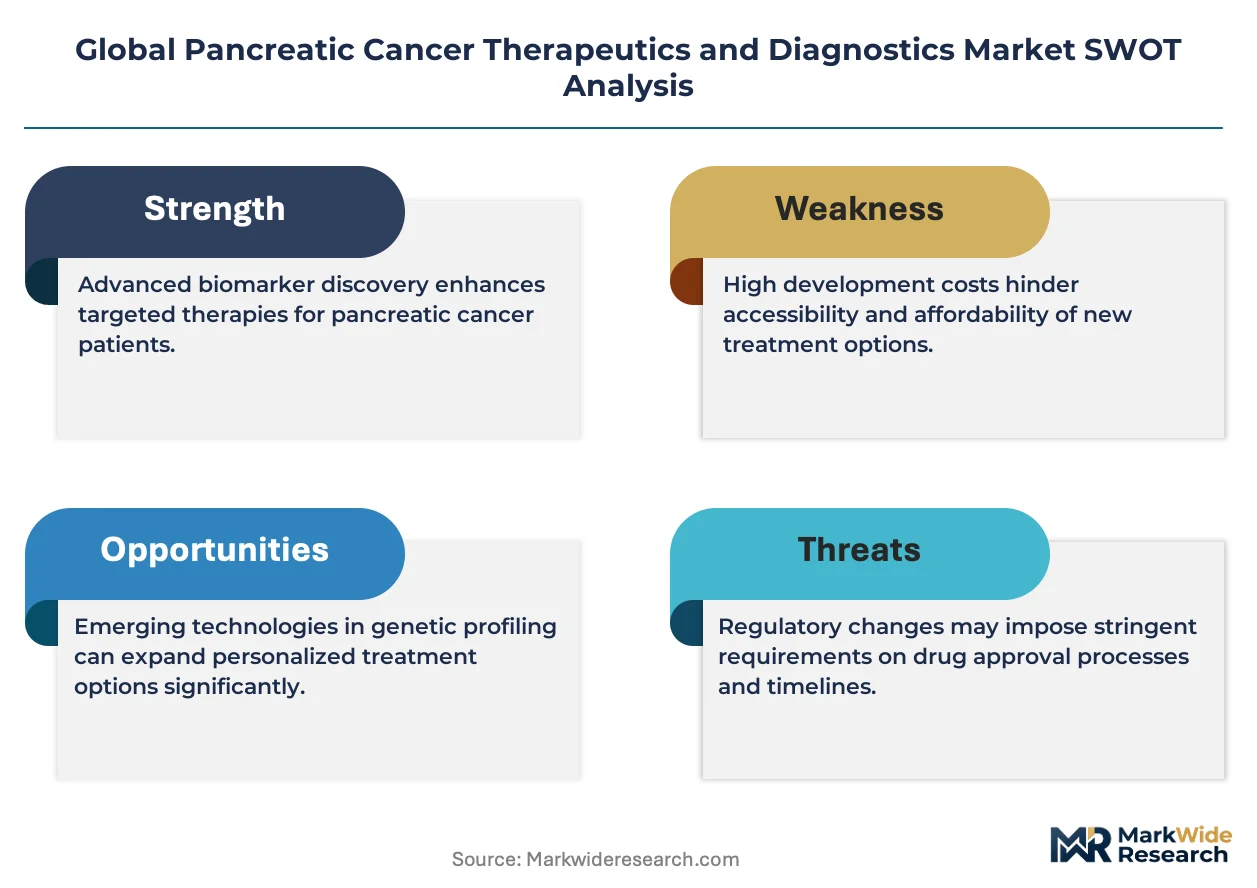
Liquid biopsy platforms are compressing diagnostic timelines while FDA breakthrough designations and EMA accelerated pathways compress development cycles, creating a dual-speed market where biomarker-validated entrants outpace conventional developers.
Growth Catalysts
- FDA Breakthrough Device Designations:Compressed review timelines accelerate commercialization for pancreatic cancer detection platforms. Developers leveraging this pathway reach oncology clinics faster than conventional regulatory routes permit.
- KRAS-Directed Therapy Pipelines:Targeted agents addressing the mutation present in over ninety percent of ductal adenocarcinoma cases expand addressable patient populations. Companion diagnostic requirements for these therapies stimulate parallel demand for molecular profiling infrastructure.
- Specialized Cancer Center Expansion:Concentrated treatment volumes at high-throughput institutions in the United States, Germany, and Japan drive protocol standardization. These centers serve as early adopters for novel therapeutic and diagnostic modalities.
Market Restraints
- Desmoplastic Stroma Barrier:Dense fibrotic tissue surrounding pancreatic tumors impairs systemic drug penetration, limiting efficacy of conventional chemotherapy and targeted agents alike.
- EU IVDR Compliance Burden:Stricter clinical evidence requirements for companion diagnostics under the In Vitro Diagnostic Regulation elevate validation costs and extend timelines for European market entry.
- Tissue Acquisition Dependency:Invasive biopsy procedures remain necessary for definitive diagnosis in many cases, restricting patient eligibility and introducing procedural risk that blood-based alternatives have not fully eliminated.
Strategic Opportunities
- Multi-Cancer Early Detection Reimbursement:Evolving payor coverage frameworks for screening applications in the United States create precedent for pancreatic-specific liquid biopsy inclusion in preventive care protocols.
- Artificial Intelligence-Enhanced Pathology:Integration of machine learning algorithms with digital histopathology workflows addresses specialist shortage constraints in community hospital settings across Japan and Germany.
- Orphan Drug Pricing Structures:Narrow indication scopes for targeted therapies command premium reimbursement tiers, sustaining margin pools despite limited patient volumes per approved indication.
Industry Challenges
- Biomarker Validation Expertise Scarcity:Clinical laboratories face recruitment constraints for specialists capable of executing prospective validation studies required for companion diagnostic co-approval.
- ISO 15189 Accreditation Timelines:Medical laboratory certification processes across European and Asia-Pacific healthcare systems introduce procurement delays for diagnostic platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pancreatic Cancer Therapeutics and Diagnostics Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Chemotherapy, Radiotherapy, Diagnostic Kits, Liquid Biopsy Therapy Area: Metastatic Pancreatic Cancer, Locally Advanced Pancreatic Cancer, Early-Stage Cancer, Recurrent Cancer End User: Oncology Clinics, Diagnostic Laboratories, Specialized Cancer Centers, Research Institutions Delivery Mode: Oral Administration, Intravenous Infusion, Injectable, Imaging-Guided Procedures, Biomarker Testing |
| Companies Covered | Roche, Bristol-Myers Squibb, AstraZeneca, Pfizer, Merck, Eli Lilly and Company, Novartis, Thermo Fisher Scientific, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pancreatic Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Next-generation sequencing workflows and artificial intelligence-augmented pathology are restructuring how pancreatic lesions are classified and treated, with regulatory pathways adapting to accommodate novel evidentiary standards.
Circulating tumor DNA analysis is bifurcating the detection landscape between tissue-dependent and blood-based diagnostic paradigms. Community oncology practices and academic medical centers are adopting liquid biopsy protocols for treatment monitoring and recurrence surveillance. This modality is bifurcating patient pathways by enabling serial sampling without invasive procedures, compressing the time between molecular progression detection and therapeutic adjustment.
The EU In Vitro Diagnostic Regulation enforces graduated clinical evidence requirements based on diagnostic risk classification. Companion diagnostics for oncology applications now face mandatory performance studies with defined statistical endpoints. European notified bodies are prioritizing pancreatic cancer biomarker panels given the disease's mortality burden and unmet diagnostic need.
Hospital procurement committees are consolidating vendor relationships for integrated diagnostics-to-therapeutics platforms. Single-source contracting for companion diagnostic development and targeted therapy supply is displacing fragmented purchasing across separate therapeutic and pathology budgets. This concentration is most visible in United States integrated delivery networks managing captive oncology populations.
Global Pancreatic Cancer Therapeutics and Diagnostics Market Segmentation
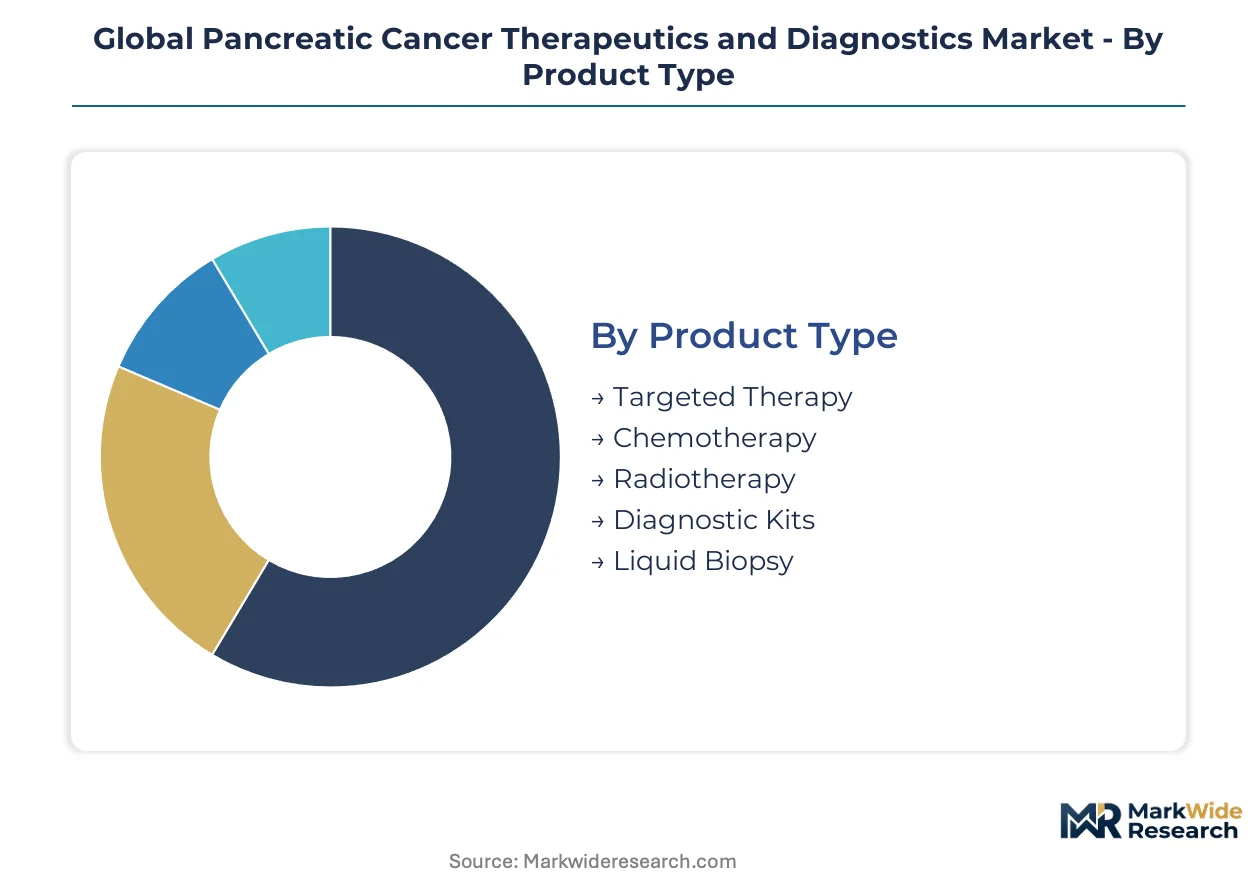
Segmentation in pancreatic cancer care reveals divergent commercial logics between high-margin targeted interventions and high-volume diagnostic monitoring. Product type and therapy area splits expose where pricing power concentrates versus where volume scale dominates procurement decisions.
Product Type:
Geographic demand patterns split sharply between domestically consumed hospital-administered therapies and export-oriented diagnostic platforms serving distributed laboratory networks.
- Targeted Therapy:Precision agents directed at KRAS mutations and other actionable alterations command orphan drug premiums. Demand clusters in United States integrated delivery networks and German university hospitals where biomarker testing infrastructure supports patient stratification protocols.
- Chemotherapy:Systemic cytotoxic regimens remain the backbone of first-line treatment across community oncology settings. Volume leadership in India and Brazil reflects cost-sensitive procurement patterns and established generic substitution pathways.
- Radiotherapy:External beam and stereotactic body radiation modalities address localized disease and palliative indications.
- Diagnostic Kits:Immunohistochemistry and molecular profiling assays serve routine pathology workflows in hospital-based laboratories.
- Liquid Biopsy:Circulating tumor DNA platforms enable serial monitoring without invasive tissue acquisition. Adoption accelerates in Japanese cancer centers addressing specialist shortages through blood-based alternatives.
Targeted therapy commands the established base. The steepest expansion runs through liquid biopsy.
Therapy Area:
Patient volume and reimbursement intensity invert across disease stages, with late-stage populations driving commercial scale while early-stage detection promises longer treatment durations.
- Metastatic Pancreatic Cancer:Systemic therapy dominates this largest addressable population, with combination regimens extending survival intervals. United States Medicare reimbursement frameworks and Japanese universal coverage sustain treatment access despite high per-patient costs.
- Locally Advanced Pancreatic Cancer:Neoadjuvant chemotherapy and radiation protocols aim to convert unresectable tumors to surgical candidates. German and French multidisciplinary tumor boards drive protocol standardization for this technically demanding segment.
- Early-Stage Cancer:Surgical resection with adjuvant therapy offers curative intent for the minority diagnosed before metastasis.
- Recurrent Cancer:Second-line systemic options and clinical trial enrollment characterize this heavily pretreated population.
Metastatic disease anchors volume scale. Early-stage detection carries the highest unmet need for therapeutic intervention.
End User:
Procurement sophistication tiers separate academic medical centers with integrated research operations from community clinics dependent on external laboratory services.
- Oncology Clinics:Community-based practices administer systemic therapy and coordinate referral pathways. United States independent oncology groups consolidate purchasing through group purchasing organizations, while German ambulatory care networks maintain direct manufacturer relationships.
- Diagnostic Laboratories:Centralized pathology services process high-throughput testing volumes for distributed healthcare systems. Commercial laboratory chains in the United States and hospital-affiliated networks in Japan dominate regional sample flows.
- Specialized Cancer Centers:Comprehensive cancer institutes combine clinical trials access with advanced interventional capabilities.
- Research Institutions:Academic medical centers and contract research organizations execute biomarker discovery and early-phase clinical studies.
Specialized cancer centers concentrate the highest-value procedures. Diagnostic laboratories capture the broadest geographic reach.
Delivery Mode:
Administration complexity and patient convenience trade-offs shape competitive positioning between hospital-based infusion centers and emerging oral alternatives.
- Intravenous Infusion:Cytotoxic and biologic agents requiring supervised administration dominate current practice. United States outpatient infusion centers and Japanese day-ward facilities manage high patient throughput with nursing-intensive protocols.
- Oral Administration:Targeted small molecules enable home-based treatment with reduced healthcare utilization. Patient adherence programs in Germany and pharmacy benefit management in the United States address compliance monitoring challenges.
- Injectable:Subcutaneous and intramuscular formulations support specific therapeutic classes.
- Imaging-Guided Procedures:Interventional radiology techniques enable localized drug delivery and tissue acquisition.
- Biomarker Testing:Companion diagnostic workflows integrate molecular profiling with therapeutic decision-making.
Intravenous infusion retains procedural dominance. Oral administration is gaining share fastest among patient-accessibility initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cancer centers in the United States, Germany, and Japan concentrate the highest-value therapeutic protocols, while diagnostic platform adoption spreads through hospital networks in secondary markets. FDA breakthrough pathways and EMA accelerated assessments compress development timelines unevenly across jurisdictions.
United States
Medicare reimbursement frameworks sustain access to high-cost targeted therapies and companion diagnostics for metastatic populations. The FDA breakthrough device designation pathway compresses commercialization timelines for liquid biopsy developers. MD Anderson Cancer Center and Memorial Sloan Kettering anchor protocol standardization for neoadjuvant and adjuvant regimens.
Germany
University hospitals and multidisciplinary tumor boards drive biomarker-driven patient stratification for locally advanced cases. The EU In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for companion diagnostics entering the European market. The Heidelberg and Munich cancer clusters concentrate pathology infrastructure and molecular profiling capacity.
Japan
Universal coverage sustains treatment access despite per-patient costs, while specialist shortages accelerate blood-based diagnostic adoption. PMDA consultation frameworks align with global development timelines for oncology applications. Tokyo and Osaka cancer centers pioneer artificial intelligence-augmented pathology workflows addressing workforce constraints.
United Kingdom
NICE technology appraisals shape reimbursement access for novel therapeutics, creating staged adoption patterns distinct from US and German markets. The MHRA operates under retained EU regulatory frameworks post-Brexit with diverging timelines for diagnostic approvals. The London and Manchester cancer research clusters integrate clinical trials access with routine care pathways.
India
Cost-sensitive procurement patterns favor generic chemotherapy regimens in community oncology settings, while tertiary centers build molecular profiling capacity. CDSCO regulatory pathways for oncology diagnostics are streamlining through harmonization with ICH guidelines. Mumbai and Bangalore hospital networks are expanding liquid biopsy access through commercial laboratory partnerships.
Global Pancreatic Cancer Therapeutics and Diagnostics Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical conglomerates with diagnostics-to-therapeutics pipelines, supplemented by specialized molecular diagnostics developers and contract research organizations. The competitive structure concentrates around three strategic archetypes: integrated pharma-diagnostic conglomerates commanding companion diagnostic co-development, pure-play liquid biopsy platform developers racing for FDA breakthrough designations, and oncology-focused biotechs leveraging orphan drug pricing structures. Dominant competitive moves include strategic partnerships between therapeutic developers and diagnostic platform vendors, plus backward integration into biomarker discovery capabilities.
Within the integrated conglomerate tier, Roche and Bristol-Myers Squibb exemplify archetypes combining therapeutic portfolios with companion diagnostic infrastructure. Among specialized diagnostics developers, Thermo Fisher Scientific occupies a position representing laboratory equipment and molecular profiling supply chains. These three companies anchor the competitive landscape through their representation of distinct strategic positions: full vertical integration, immuno-oncology specialization with biomarker alignment, and enabling technology supply respectively.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb |
| AstraZeneca |
| Pfizer |
| Merck |
| Eli Lilly and Company |
| Novartis |
| Thermo Fisher Scientific |
| QIAGEN |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates both diagnostic platform qualification and tiered reimbursement access, creating simultaneous barriers to supply entry and price positioning in pancreatic cancer care. Manufacturers without accredited quality management systems face exclusion from procurement committees at German university hospitals and United States integrated delivery networks, while certified suppliers command companion diagnostic co-development premiums.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate biologic and diagnostic manufacturing agreements, insulating producers from commodity volatility while capping margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms from CE-marked alternatives and unvalidated research-use-only assays. Price differentiation hinges on biomarker validation depth and companion diagnostic co-approval status. Cost compression in chemotherapy generics intensifies because of Indian and Chinese API oversupply. Community oncology clinics exhibit highest price sensitivity; specialized cancer centers prioritize clinical performance over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for perishable reagents and short-half-life biologics, while strategic stockpiling characterizes radioisotope and critical antibody reserves. Manufacturing concentration spans the United States, Germany, and Switzerland for precision diagnostics, with China and India anchoring API and generic active pharmaceutical ingredient supply. Production draws from recombinant protein cell lines, synthetic nucleic acid chemistries, and rare earth-dependent imaging isotopes. Single-source vulnerability runs through Chinese heparin and isotope processing capacity. Distribution runs through hospital-affiliated central laboratories and commercial diagnostic chains with cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy platform economics approach an interoperability inflection where biomarker data liquidity across competing systems determines competitive survival, mirroring the EMR integration battles that restructured hospital IT procurement.
For Market Incumbents: Fortify companion diagnostic infrastructure through captive biomarker discovery capabilities and exclusive oncology clinic partnerships. Emerging pure-play liquid biopsy developers threaten diagnostic-to-therapeutic integration advantages. Priority investment targets ISO 15189-accredited laboratory networks in Japan and Germany. For New Entrants and Emerging Players: Community hospital pathology backlogs in the United States and specialist shortages across Japanese regional centers represent service-layer gaps where artificial intelligence-augmented diagnostic workflows penetrate fastest. Blood-based monitoring for recurrence surveillance offers the most penetrable application segment. Go-to-market execution should prioritize group purchasing organization contracts over direct hospital sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molecular diagnostics platforms holding FDA breakthrough designations but lacking therapeutic partnerships. Five-to-ten year viability depends on reimbursement expansion for multi-cancer early detection screening. Acquisition targets include biomarker validation specialists with prospective study infrastructure. Signal to monitor: CMS national coverage determination for pancreatic cancer liquid biopsy screening protocols.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compresses commercialization timelines for circulating tumor DNA platforms at MD Anderson and Memorial Sloan Kettering. |
| Companion Diagnostic Co-Development | Locks in therapeutic-diagnostic pairing through Roche's centralized pathology and oncology clinic contracting. |
| EU IVDR Compliance Investment | Elevates clinical evidence requirements for European market entry, favoring established manufacturers with validation resources. |
| Artificial Intelligence Pathology Integration | Addresses workforce constraints in Japanese cancer centers through machine learning-augmented histopathology workflows. |
| Orphan Drug Pricing Structure | Sustains premium reimbursement tiers for KRAS-directed targeted therapies despite narrow indication scopes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists; and secondary validation through FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down therapeutic category sizing provided cross-verification.
Across the analysis window, forecasts reflect segment-specific growth trajectories for product type (targeted therapy, chemotherapy, liquid biopsy, diagnostic kits), therapy area (metastatic, locally advanced, early-stage), and end user (specialized cancer centers, diagnostic laboratories, oncology clinics). CAGRs derive from epidemiological incidence projections, treatment penetration curves, and pricing evolution assumptions. Key inputs include biomarker testing adoption rates and companion diagnostic co-approval timelines.
Underlying assumptions cover regulatory pathway efficiency, reimbursement stability, and biomarker validation success rates, with deviation risk concentrated in EU IVDR implementation delays and multi-cancer early detection coverage determinations. Revision becomes warranted when FDA breakthrough designation grants or CMS national coverage decisions cross material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Ulcerative Colitis Market