
 Pan Liners Market | 2026-2036
Pan Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Pan Liners Market Analytics
Commercial foodservice is pivoting toward high-volume bakery and ready-meal segments as labor scarcity drives automation and disposables adoption. Reynolds Consumer Products leverages its retail and institutional distribution network to sustain shelf-space dominance across North American grocery and club channels. Ahlstrom-Munksjö anchors European supply through fiber-based specialty materials engineered for grease resistance and oven safety. Novolex competes on vertical manufacturing scale, controlling resin-to-film conversion for plastic liner grades serving broadline distributors.
Pan liners are disposable sheets placed between food and cooking surfaces to prevent adhesion, reduce cleaning, and extend equipment life; they are manufactured from aluminum foils, silicone-impregnated papers, or extruded polymer films with specified heat thresholds ranging from 400°F to 600°F depending on end-use. Parchment paper and silicone formulations lead material type demand in artisan and premium segments where brand positioning emphasizes natural fiber credentials and compostability. Non-stick and biodegradable coating categories capture expanding margin pools as regulatory pressure on per- and polyfluoroalkyl substances intensifies and European buyers prioritize end-of-life disposal pathways. Plastic liners retain volume dominance in cost-sensitive roasting and grilling use cases where single-use convenience outweighs sustainability premiums.
The U.S. FDA regulates pan liners as food-contact substances under 21 CFR requirements, while the EU REACH framework and F-Gas Regulation constrain fluorinated coating chemistries and pressure reformulation toward silicone and plant-derived barriers. The EU Single-Use Plastics Directive further segments market access by mandating extended producer responsibility for certain polymer-based products. Stakeholders must monitor evolving state-level packaging legislation in California and New York alongside European Commission revisions to food-contact material authorization, as compliance timing will determine which coating technologies and material platforms secure commercial viability across major demand centers.
Market Dynamics
Labor scarcity across commercial baking operations is accelerating automation investments and disposables adoption, while REACH and F-Gas Regulation constraints on fluorinated chemistries force coating reformulation toward silicone and plant-derived barriers.
Growth Catalysts
- EU Single-Use Plastics Directive:Extended producer responsibility mandates are redirecting procurement toward biodegradable-coated alternatives in Germany's industrial baking clusters.
- Quick-service restaurant expansion:High-volume bakery and ready-meal segments are scaling liner volumes as operators prioritize labor reduction and equipment protection.
- Silicone coating technology:Heat-stable formulations reaching 600°F thresholds are displacing legacy parchment in roasting applications where non-stick performance is critical.
Market Restraints
- Pulp fiber cost volatility:Specialty cellulose inputs for grease-resistant papers face pricing pressure from packaging sector competition and energy-intensive drying processes.
- Resin supply concentration:Extruded polymer film production depends on concentrated petrochemical feedstock regions, exposing converters to input cost spikes and logistics constraints.
- Composting infrastructure gaps:Biodegradable liners require industrial composting facilities that remain underdeveloped in most North American municipalities, limiting end-of-life value realization.
Strategic Opportunities
- California state packaging legislation:Advancing extended producer responsibility rules create first-mover advantage for compliant coating technologies in the largest US state economy.
- Cloud kitchen proliferation:Delivery-optimized ghost kitchen operations prioritize disposables over capital equipment, opening volume channels outside traditional foodservice distribution.
- Silicone-plant barrier convergence:Hybrid coating systems combining synthetic heat resistance with bio-based substrates address performance-sustainability trade-offs in premium artisan segments.
Industry Challenges
- Food-contact authorization timelines:FDA 21 CFR substance notifications and EFSA re-evaluations create 18-36 month lag between formulation innovation and commercial deployment.
- Legacy equipment compatibility:Automated liner dispensing systems in industrial bakeries require precise dimensional tolerances that complicate material transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pan Liners Market |
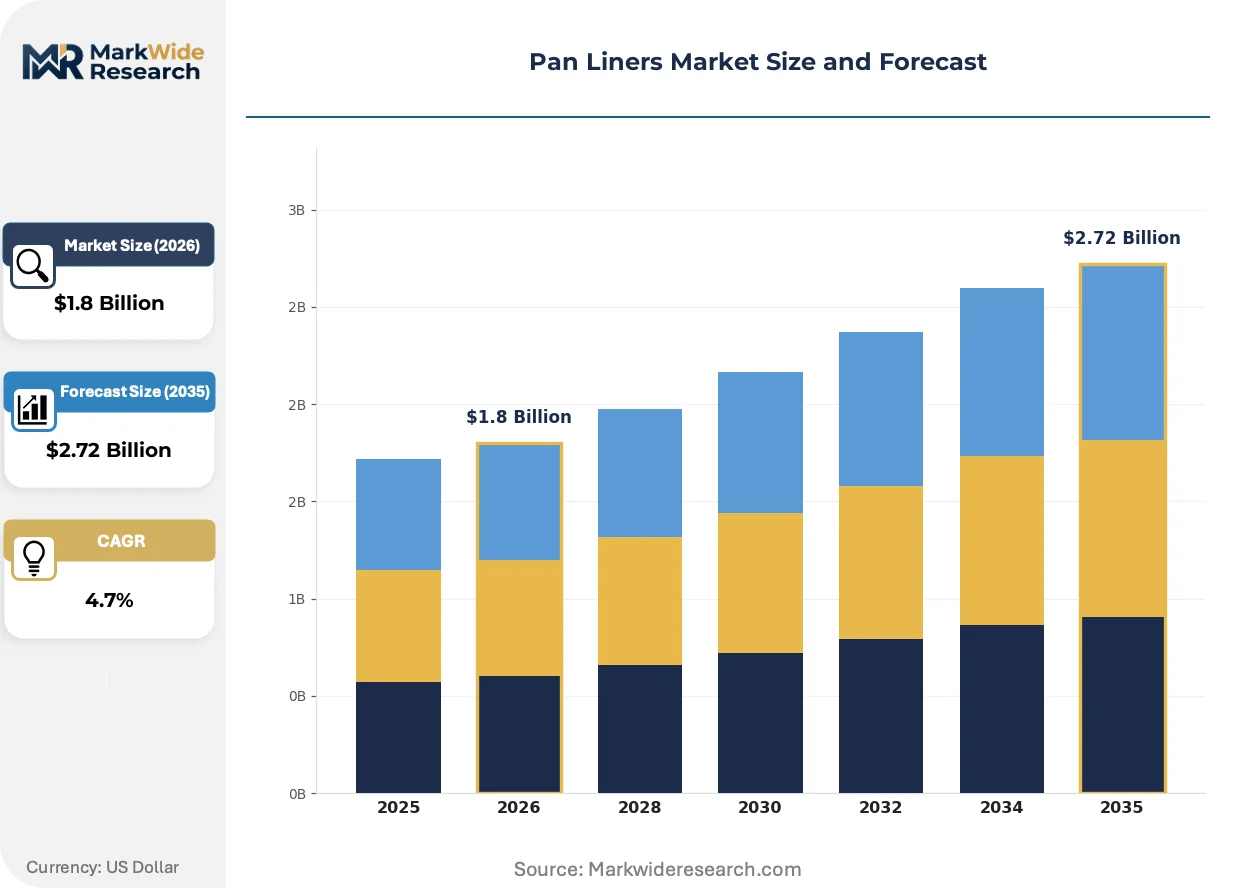
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Parchment Paper, Silicone, Plastic Coating Type: Non-Stick, Greaseproof, Heat-Resistant, Biodegradable Use Case: Baking, Roasting, Grilling, Frying Size: Small, Medium, Large, Custom |
| Companies Covered | Ahlstrom-Munksjö, Inteplast Group, Reynolds Consumer Products, LK Packaging, Handgards, Novolex, McNairn Packaging, Hoffmaster, PaperChef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pan Liners Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to reshape coating platforms, while procurement rationalization among consolidated foodservice operators is compressing supplier margins and accelerating specification standardization.
Silicone-impregnated parchment formulations are consolidating market position in artisan and premium segments where 450-500°F performance thresholds suffice. Independent bakeries and specialty food manufacturers are adopting these grades faster than industrial operators due to shorter equipment replacement cycles. The technology is consolidating margin pools previously fragmented between aluminum foil and conventional parchment by offering compostability credentials without heat sacrifice.
EU F-Gas Regulation constraints on perfluorinated coatings are forcing reformulation toward silicone and bio-barrier alternatives across European supply chains. Industrial bakeries in Germany and France face accelerated compliance timelines that compress R&D windows. Parchment paper and fiber-based platforms capture displaced volume as REACH authorization processes delay re-entry of fluorinated chemistries.
Consolidated broadline distributors are unbundling liner procurement from bundled foodservice supply contracts, exposing specialty manufacturers to direct price negotiation. Quick-service restaurant chains with centralized purchasing functions are consolidating supplier panels from six to three approved vendors. This concentration is most visible in North American markets where group purchasing organizations aggregate volume across regional operator networks.
Pan Liners Market Segmentation
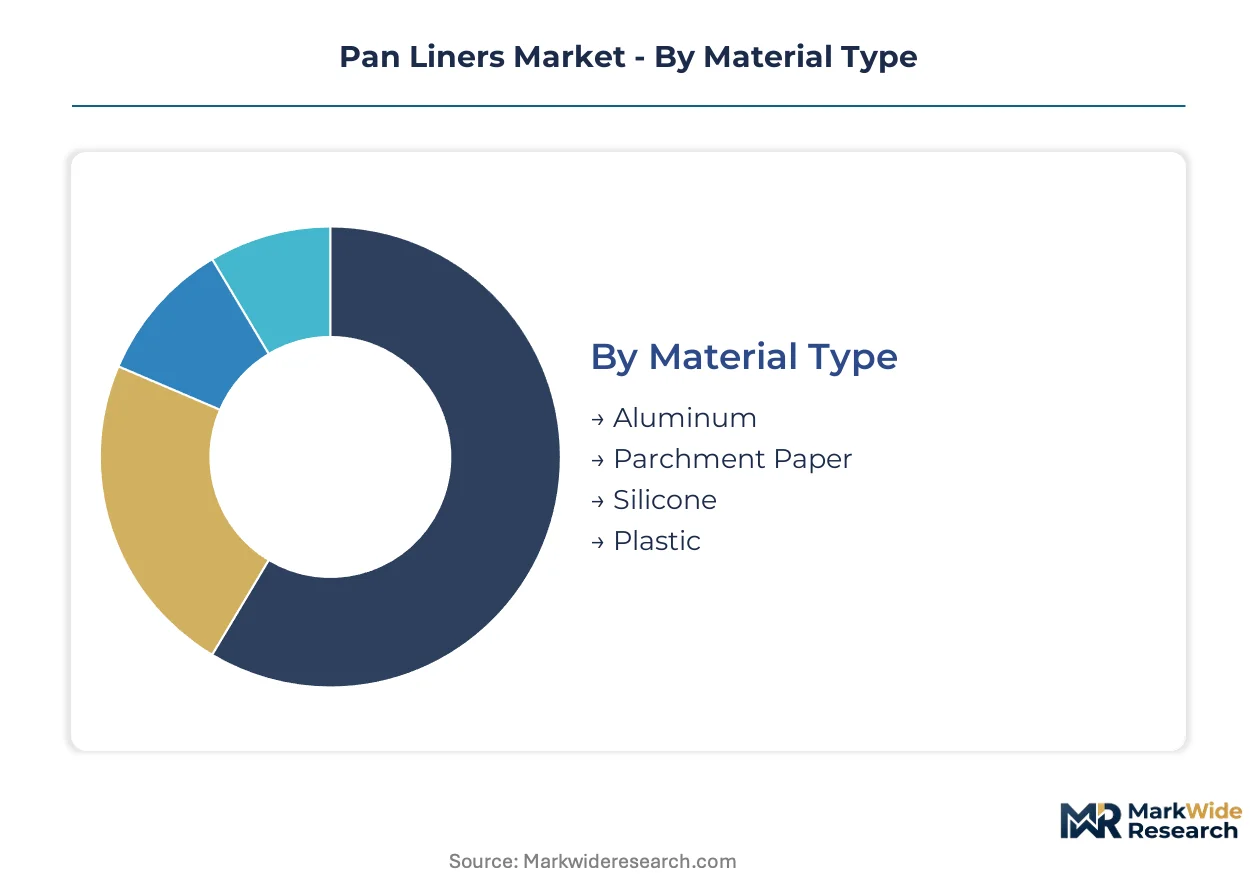
Pan liner procurement patterns diverge sharply across material platforms and thermal specifications. Industrial bakers prioritize heat stability and automated dispensing compatibility, while artisan operators emphasize compostability credentials and brand positioning.
Material Type:
Supply concentration in pulp fiber and petrochemical feedstocks shapes cost structures and reformulation timelines across each substrate category.
- Parchment Paper:Cellulose-based sheets impregnated with silicone deliver 450-500°F performance thresholds with certified compostability. German industrial baking clusters and French artisan cooperatives concentrate procurement here as EU packaging waste laws tighten disposal requirements.
- Silicone:Platinum-cured elastomer formulations withstand 600°F continuous exposure without degradation, displacing legacy alternatives in high-temperature roasting. Quick-service restaurant chains with centralized purchasing specify these grades for automated production lines where equipment protection justifies premium positioning.
- Aluminum:Rolled foil products offer conductive heat distribution for browning-critical applications. Commercial kitchens in cost-sensitive segments retain volume despite sustainability limitations.
- Plastic:Extruded polymer films from concentrated petrochemical regions dominate single-use roasting and grilling where heat exposure remains moderate.
Today's leader: Parchment Paper. Tomorrow's challenger: Silicone.
Coating Type:
Performance specifications and regulatory authorization timelines determine which barrier chemistries secure commercial deployment across food-contact applications.
- Non-Stick:Silicone-based release surfaces eliminate food adhesion without fluorinated chemistries. REACH and F-Gas Regulation constraints in Europe accelerate displacement of legacy perfluorinated coatings toward these reformulated platforms.
- Biodegradable:Plant-derived barrier systems engineered for industrial composting facilities address end-of-life disposal mandates. California state packaging legislation and EU extended producer responsibility rules concentrate early adoption in these regulatory jurisdictions.
- Heat-Resistant:Ceramic-reinforced silicone composites maintain structural integrity above 550°F for extended roasting cycles. Heavy-duty commercial applications specify these grades where standard formulations fail.
- Greaseproof:Dense cellulose structures with fluorine-free treatments resist oil penetration in fried food applications. FDA 21 CFR compliance requirements govern authorization timelines for new barrier chemistries entering US foodservice channels.
Non-Stick coatings command current volume. Biodegradable alternatives are climbing the fastest as regulatory pressure intensifies.
Use Case:
Equipment automation levels and labor substitution economics drive specification divergence across thermal processing applications.
- Baking:Precision-cut liners for bread, pastry, and confectionery production integrate with automated dispensing systems. Industrial bakeries in Germany specify dimensional tolerances within millimeter ranges to prevent jamming on high-speed lines.
- Roasting:High-temperature exposure demands 500°F+ performance thresholds where silicone-impregnated substrates displace conventional parchment. Quick-service restaurant chains scale procurement volumes here as menu expansion into roasted proteins accelerates.
- Grilling:Open-flame contact requires specialized non-stick surfaces that withstand direct heat exposure. Outdoor and commercial grilling segments prioritize convenience over compostability given contamination with grease and carbonized residue.
- Frying:Oil immersion applications specify greaseproof barriers with structural integrity at 375°F sustained temperatures. Food manufacturers processing battered and breaded products dominate this specification tier.
Baking maintains volume leadership. Roasting applications are gaining share fastest as protein-centered menu trends expand.
Size:
Standardization versus customization trade-offs reflect customer scale and equipment replacement cycles across the buyer base.
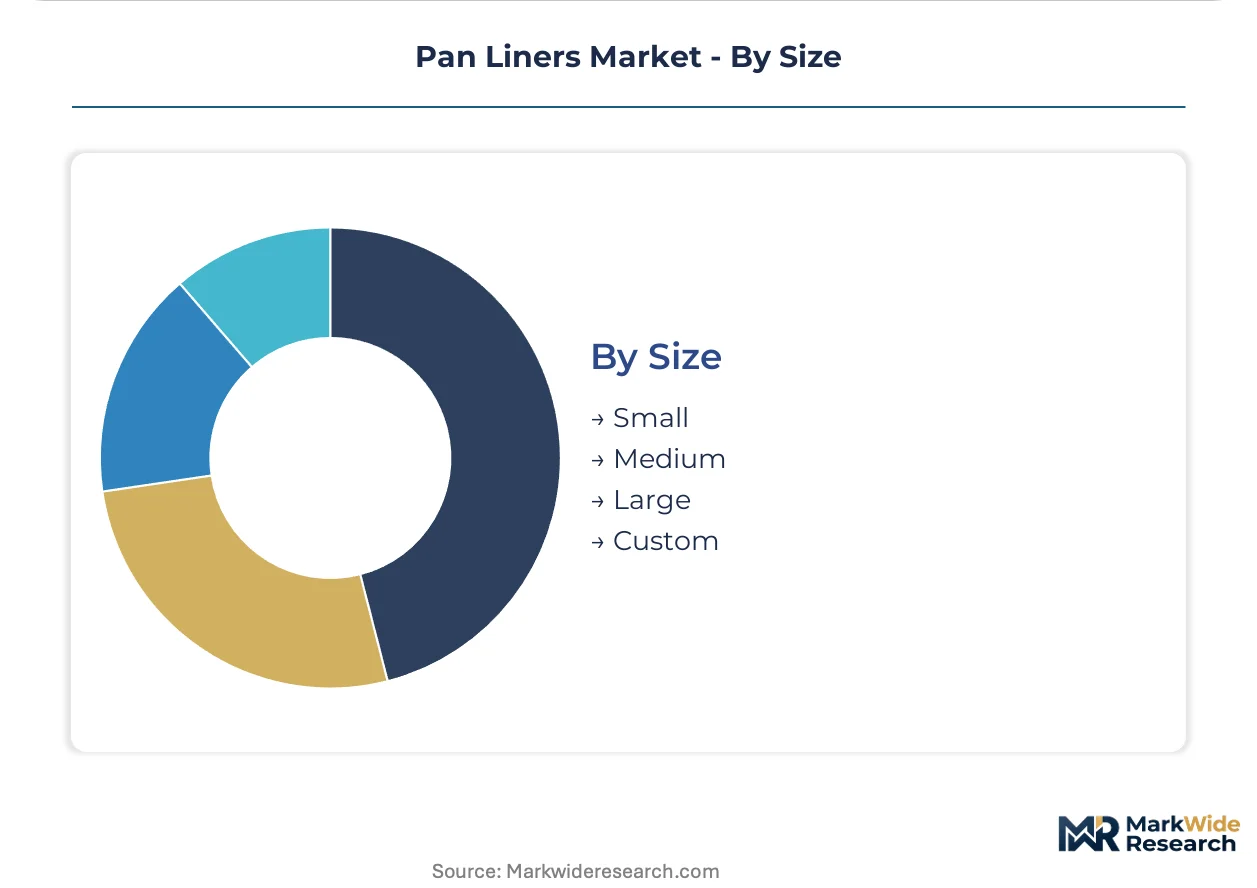
- Custom:Die-cut dimensions matched to specific pan geometries and automated dispensing systems. Industrial bakeries with proprietary equipment configurations require these specifications despite longer lead times and minimum order quantities.
- Large:Full-sheet formats for commercial roasting pans and steam table operations. Broadline distributors stock these SKUs for institutional foodservice accounts with predictable volume patterns.
- Medium:Half-sheet and quarter-sheet standards compatible with conventional bakery equipment. Independent bakeries and small commercial kitchens default to this tier for inventory simplification.
- Small:Pre-cut rounds and specialty shapes for individual portion baking. Artisan producers and specialty food manufacturers specify these grades for product differentiation and labor reduction.
Custom formats dominate industrial procurement. Large sizes are expanding most quickly as consolidated foodservice operators standardize specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers relocate conversion capacity to jurisdictions with lower compliance burdens. The EU Single-Use Plastics Directive and REACH constraints on fluorinated coatings have widened cost-of-compliance gaps between European and North American operations.
United States
Quick-service restaurant chains with centralized procurement dominate liner volumes as labor scarcity drives disposables adoption. FDA 21 CFR food-contact substance regulations govern coating authorization timelines. Industrial baking clusters in Chicago and California's Central Valley concentrate automated production lines requiring precision-cut custom formats.
Germany
Industrial baking cooperatives and artisan producers accelerate biodegradable-coated procurement under stringent packaging waste laws. The EU F-Gas Regulation and extended producer responsibility mandates constrain fluorinated chemistry use. Baden-Württemberg's specialized paper converters engineer fiber-based grease-resistant substrates for oven-safe applications.
France
Artisan bakery segments prioritize compostability credentials and natural fiber positioning in premium channels. REACH authorization processes delay re-entry of perfluorinated coatings into food-contact applications. Paris Basin industrial zones host reformulation facilities migrating toward silicone and plant-derived barrier systems.
China
Export-oriented converters supply cost-sensitive roasting and grilling segments to North American and European distributors. National food-contact material standards under SAMR jurisdiction govern import compliance for coated substrates. Yangtze River Delta manufacturing zones concentrate extruded polymer film production for single-use applications.
Canada
Foodservice distributors serving cross-border quick-service operators standardize specifications with US procurement patterns. Health Canada and PMRA regulate food-contact coatings alongside provincial extended producer responsibility pilots in British Columbia and Ontario. Toronto-Waterloo corridor converters supply die-cut formats for automated bakery equipment.
Pan Liners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail-channel dominance consolidating around consumer-facing names while institutional procurement favors direct converter relationships. The vendor base organizes into three tiers: multinational paper and plastics conglomerates with captive resin or pulp supply, regional specialty converters focused on custom die-cutting and coating services, and private-label assemblers serving broadline distributors. M&A activity concentrates on coating technology acquisitions and automated converting capacity expansion.
Among North American consumer brands, Reynolds Consumer Products anchors retail shelf-space positioning across grocery and club channels. Ahlstrom-Munksjö exemplifies European fiber-based specialty material engineering for grease resistance and oven safety. Novolex occupies a position on the scale-driven end, controlling resin-to-film conversion for plastic liner grades serving broadline distribution networks.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Inteplast Group |
| Reynolds Consumer Products |
| LK Packaging |
| Handgards |
| Novolex |
| McNairn Packaging |
| Hoffmaster |
| PaperChef |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant chains with centralized procurement dominate volume aggregation and compress channel margins across North American distribution networks. Their consolidated purchasing power enforces contract-based pricing with tiered structures separating silicone-impregnated parchment grades from commodity polymer alternatives.
Pricing Analysis
Distributor markups on institutional-grade pan liners compress as broadline operators unbundle liner procurement from bundled foodservice contracts. Three-tier pricing structure across premium silicone-impregnated parchment, standard grease-resistant papers, and economy polymer films reflects certification grade and volume scale differentiation. Cost compression in standard parchment tiers intensifies because pulp fiber inputs face packaging sector competition. Independent artisan bakeries exhibit highest price sensitivity, while industrial operators with automated dispensing systems prioritize dimensional precision over unit cost.
Supply Chain Analysis
FDA 21 CFR food-contact substance authorization and EU REACH compliance certification gate market access for coating technology suppliers. Pulp fiber supply concentrates in Nordic regions and North American timber belts, while silicone resin production anchors in Germany and Japan. Specialty cellulose inputs, platinum-cured elastomers, and extruded polymer films constitute critical material dependencies. Single-source vulnerability in fluorinated chemistry alternatives exposes converters to reformulation delays. Distribution runs through broadline foodservice distributors and direct converter relationships with industrial bakery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pan liners rests on silicone coating technology premiumization and biodegradable substrate substitution as regulatory compliance costs reshape cost structures. Reformulation toward plant-derived barriers enables tier ascension for compliant suppliers.
For Market Incumbents: Deploy coating technology acquisition programs to secure silicone-impregnated parchment formulations ahead of EU F-Gas Regulation enforcement deadlines. Consolidate automated converting capacity in Germany's Baden-Württemberg industrial zone to serve biodegradable-coated demand from industrial baking cooperatives. Defensive positioning requires backward integration into specialty cellulose supply as pulp fiber cost volatility threatens standard-grade margins. For New Entrants and Emerging Players: California state packaging legislation opens a window for biodegradable-coated alternatives in the largest US state economy. Target cloud kitchen operations outside traditional foodservice distribution channels with delivery-optimized liner formats. Penetrate artisan bakery segments through compostability credentials and natural fiber brand positioning, leveraging shorter equipment replacement cycles for faster specification adoption. For Investors and Strategic Acquirers: Paper and packaging conglomerates are the most active acquirer in this space, seeking coating technology capabilities and food-contact authorization portfolios. Long-term viability favors targets with FDA 21 CFR substance notifications and EU REACH-compliant silicone barrier platforms. Watch for EU Commission revisions to food-contact material authorization timelines as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Acquisition | Secures silicone-impregnated formulations ahead of F-Gas Regulation compliance deadlines in Germany. |
| Automated Converting Capacity Expansion | Baden-Württemberg facilities serve precision-cut custom formats for German industrial baking clusters. |
| Biodegradable Substrate Development | Plant-derived barriers address California extended producer responsibility and EU packaging waste mandates. |
| Direct Cloud Kitchen Distribution | Ghost kitchen channels bypass consolidated broadline distributor procurement panels in North America. |
| Food-Contact Authorization Investment | FDA 21 CFR notifications and EFSA evaluations reduce commercial deployment lag for new formulations. |
Research Methodology
Multiple input streams — primary interviews with plant managers at industrial bakeries, procurement leads at quick-service restaurant chains, coating technology R&D directors, and broadline distributor category managers, alongside secondary validation through FDA 21 CFR substance databases, EU ECHA REACH registration data, customs trade records, and foodservice industry procurement reports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon applied analytical frameworks modeling material type segmentation by heat threshold and compostability credential, coating chemistry by regulatory authorization status, and use case by equipment automation level. CAGRs were derived from volume-weighted trajectory analysis incorporating pulp fiber pricing indices, silicone resin supply trends, and quick-service restaurant capital expenditure patterns for automated production lines.
Revisions become necessary when EU Commission food-contact material authorization timelines accelerate, FDA 21 CFR substance notification backlogs extend, or industrial composting infrastructure deployment in North American municipalities materially exceeds baseline assumptions. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement interpretation or California extended producer responsibility rule finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Global Micro-Perforated Films Market